
 Residential Water Purifier Market | 2026-2036
Residential Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Water Purifier Market Analysis
Asset-light subscription and leasing models is reconfiguring competitive entry barriers by lowering upfront capital requirements for middle-income households. Eureka Forbes leverages its direct-to-home service infrastructure to sustain recurring revenue streams. Kent RO Systems anchors its position through captive manufacturing of membrane components. A. O. Smith competes on NSF-certified build quality for premium residential installations.
A residential water purifier is a point-of-use or point-of-entry treatment device engineered to reduce contaminants including dissolved solids, microbial pathogens, and chemical impurities through physical filtration, membrane separation, or ultraviolet irradiation, typically achieving total dissolved solids rejection rates exceeding 90 percent in reverse osmosis configurations. Its primary commercial purpose is to deliver potable water compliant with health-based standards in households lacking consistent municipal treatment quality. Reverse osmosis systems dominate value capture due to membrane replacement economics and higher unit pricing, while ultraviolet units represent the fastest-growing technology segment in regions with pre-treated surface water. Online retail channels are expanding fastest among distribution pathways as platform logistics and installation partnerships reduce friction for first-time buyers.
The US EPA Safe Drinking Water Act and NSF/ANSI standards shape product certification requirements, while India's BIS drinking water purifier standards mandate specific contaminant reduction claims for market access. China's SAMR enforces GB standards for water treatment equipment performance labeling. Stakeholders must monitor evolving membrane efficiency regulations and channel-specific compliance documentation as certification divergence across jurisdictions complicates product platform strategies.
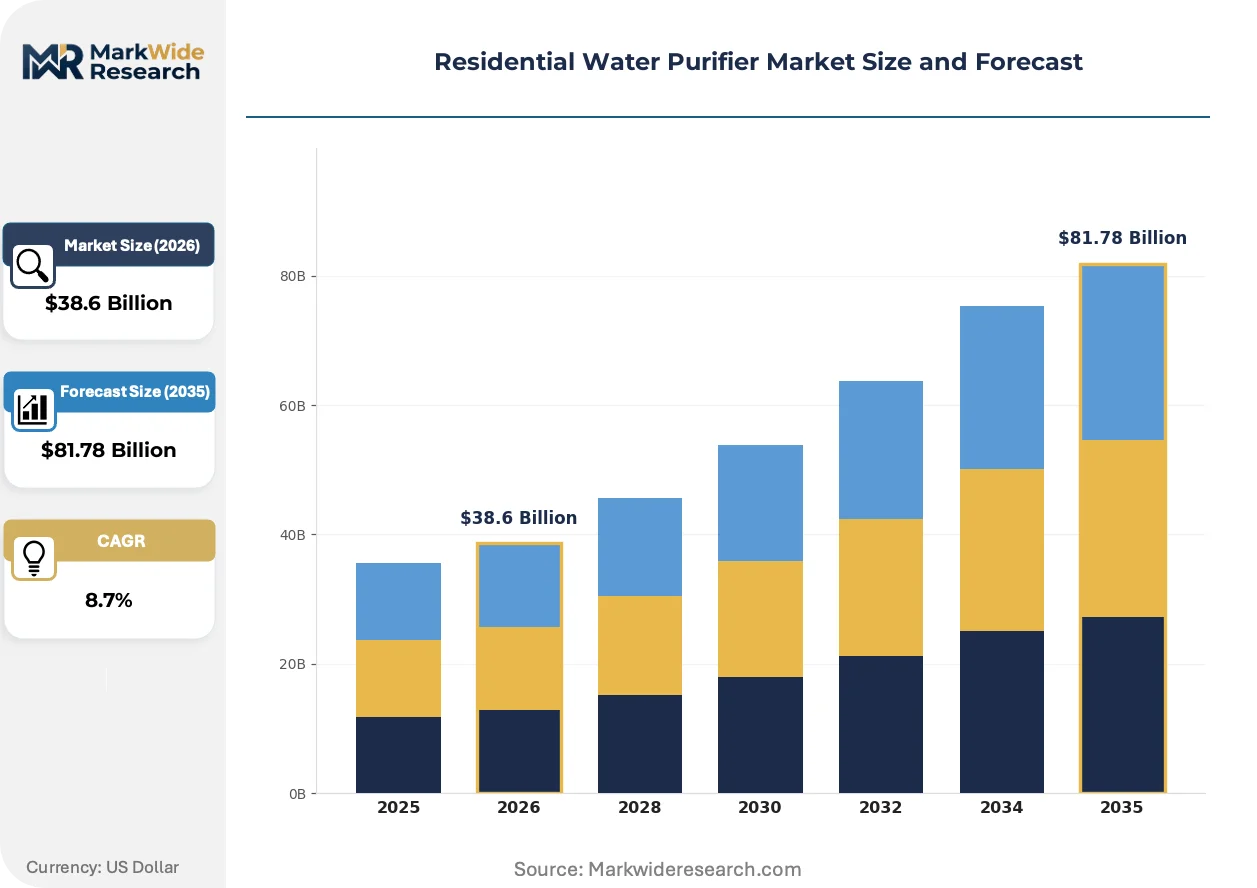
Market Dynamics
Subscription financing and membrane technology maturation are compressing replacement cycles while expanding addressable household segments beyond traditional owner-occupiers.
Growth Catalysts
- BIS Certification Mandates:India's tightening drinking water purifier standards are eliminating substandard imports and consolidating domestic manufacturing capacity around compliant producers.
- Ultraviolet Technology:UV-C LED systems are gaining traction in regions with pre-treated municipal supply, offering lower operating costs than thermal alternatives.
- Apartment Dweller Concentration:China's tier-one cities exhibit persistent municipal water quality variability that drives rental-compatible portable system demand.
Market Restraints
- Membrane Import Dependency:Thin-film composite reverse osmosis membranes concentrate production in East Asian chemical processing clusters, exposing pricing to petrochemical feedstock volatility.
- NSF/ANSI Certification Friction:US EPA-aligned testing protocols extend product launch timelines by 8-14 months for multi-contaminant reduction claims.
- Bottled Water Substitution:Bulk drinking water delivery services retain cost advantages in regions with unreliable electricity supply.
Strategic Opportunities
- Service-Unbundled Distribution:Online platform logistics partnerships are collapsing traditional dealer-installer networks in first-time buyer segments.
- GB Standards Alignment:China's SAMR performance labeling requirements create compliance-first positioning for certified foreign entrants.
- UV-RO Convergence:Sequential ultraviolet-reverse osmosis configurations are opening specification opportunities in healthcare-adjacent residential installations.
Industry Challenges
- Field Technician Scarcity:Membrane replacement and sensor calibration require certified service personnel that outpace training pipeline output in high-growth metros.
- Multi-Jurisdiction Documentation:Divergent BIS, NSF/ANSI, and GB certification requirements fragment product platform economics for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Water Purifier Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RO, UV, Activated Carbon, Distillation Technology: Filtration, Reverse Osmosis, Ultraviolet, Ion Exchange End User: Households, Apartments, Villas, Commercial Kitchens Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Brita, Culligan, Pentair, A. O. Smith, Eureka Forbes, LG Electronics, Whirlpool, Kent RO Systems, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Water Purifier Market Emerging Trajectories
Connected monitoring and predictive maintenance capabilities are redefining aftermarket revenue capture, while regulatory fragmentation forces modular certification strategies.
Smart purification hardware is hybridizing sensor arrays with cloud-based total dissolved solids tracking to enable proactive membrane replacement scheduling. Property management firms in China's Shenzhen and Shanghai corridors are piloting fleet-wide deployment of these systems. The technology is compressing traditional break-fix service intervals into subscription-predictable revenue streams.
India's BIS drinking water purifier standards revision is mandating quantitative contaminant reduction disclosures for all marketed systems. Domestic manufacturers are restructuring quality assurance departments to accommodate accelerated testing protocols. The regulation most affects ultraviolet system producers previously operating under self-certified efficacy claims.
Asset-light acquisition models are displacing outright purchase in urban rental markets where tenant turnover exceeds three-year equipment depreciation cycles. Platform-mediated rental subscriptions now coordinate installation, maintenance, and end-of-term recovery through single interfaces. This pattern concentrates in India's Mumbai and Bengaluru apartment corridors where deposit constraints limit capital outlay tolerance.
Residential Water Purifier Market Segmentation
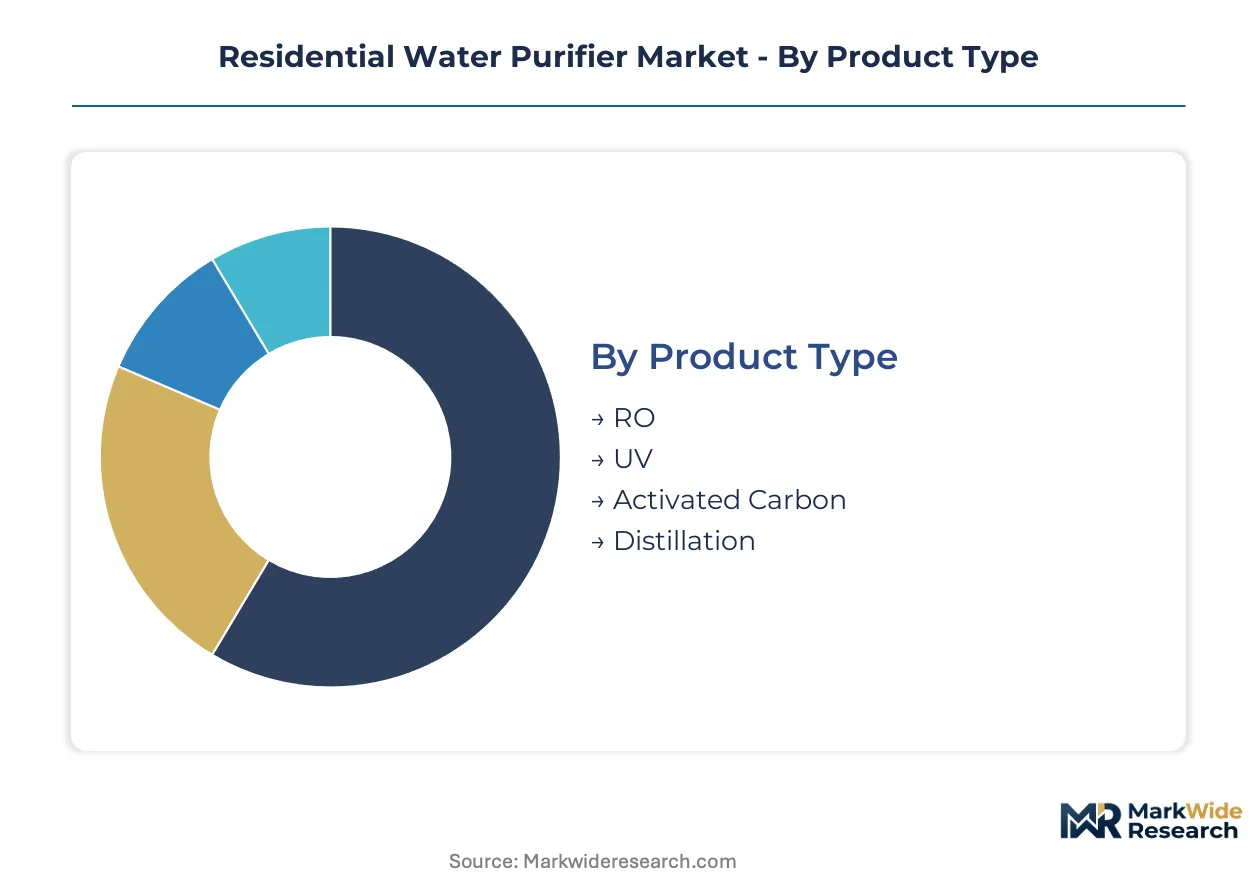
Segmentation in residential water purification reveals divergent equipment lifecycles and replacement economics. Membrane-based systems generate recurring revenue through consumable dependencies, while filtration alternatives compete on capital efficiency and lower service intensity.
Product Type:
Replacement cycle economics vary sharply across purification technologies, with membrane-dependent systems commanding extended service relationships versus passive media configurations.
- RO:Thin-film composite membranes achieve dissolved solids rejection exceeding 90 percent through multi-stage pressure-driven separation. Demand clusters in Indian metropolitan corridors where BIS certification mandates and brackish groundwater conditions coincide. Membrane replacement intervals of 12-18 months sustain aftermarket revenue concentration.
- UV:Ultraviolet irradiation systems utilizing mercury vapor or emerging UV-C LED sources target microbiological inactivation without chemical alteration. Chinese tier-one cities exhibit accelerating specification rates where municipal pre-treatment reduces dissolved solids burden. Operating cost advantages versus thermal alternatives are reshaping competitive positioning in rental-subscription channels.
- Activated Carbon:Adsorptive media configurations address chlorine, volatile organic compounds, and taste-odor complaints through porous carbon structures. Replacement cycles compress to 6-12 months in high-sediment environments.
- Distillation:Thermal vaporization-condensation systems deliver pharmaceutical-grade purity through phase-change separation. Niche demand persists in healthcare-adjacent residential installations and regions with extreme contamination profiles.
RO dominates installed base. UV is where expansion concentrates.
Technology:
Core separation mechanisms differentiate capital intensity, energy consumption, and contaminant addressability across household treatment applications.
- Filtration:Physical sieving through pleated, spun-bond, or ceramic media removes particulate matter and protozoan cysts at sub-micron ratings. Mass-market penetration in Southeast Asian urban corridors leverages minimal power requirements and disposable cartridge economics.
- Reverse Osmosis:Semi-permeable membrane separation under hydraulic pressure rejects dissolved ions, heavy metals, and synthetic organic compounds. Captive manufacturing of membrane elements in East Asian chemical processing clusters shapes supply security considerations.
- Ultraviolet:Photochemical disinruption of nucleic acids through 254nm irradiation provides non-chemical pathogen control. UV-C LED maturation is displacing mercury arc systems in premium residential specifications.
- Ion Exchange:Resin-based cation-anion substitution targets water hardness and specific ionic contaminants through regenerable or disposable media beds. Demand concentrates in North American regions with elevated calcium-magnesium groundwater profiles.
Filtration commands volume leadership. Ultraviolet configurations are gaining share fastest.
End User:
Residential accommodation typologies determine installation constraints, portability requirements, and financing model compatibility across demand segments.
- Households:Single-family owner-occupied dwellings accommodate permanent under-sink or whole-house systems with dedicated plumbing modifications. Indian suburban corridors exhibit persistent specification rates where municipal supply intermittency drives point-of-entry redundancy.
- Apartments:Multi-unit rental housing favors countertop or wall-mounted portable configurations with reversible installation. China's Shenzhen and Shanghai corridors pilot fleet-wide smart system deployment through property management intermediaries.
- Villas:High-value standalone residences integrate whole-house treatment trains with dedicated storage and pressure boosting. Specification complexity accommodates sequential UV-RO configurations in healthcare-adjacent installations.
- Commercial Kitchens:Food service residential adjuncts demand NSF-certified systems with documented pathogen log reduction for regulatory compliance.
Households anchor revenue concentration. Apartments are where asset-light subscription models are displacing outright purchase.
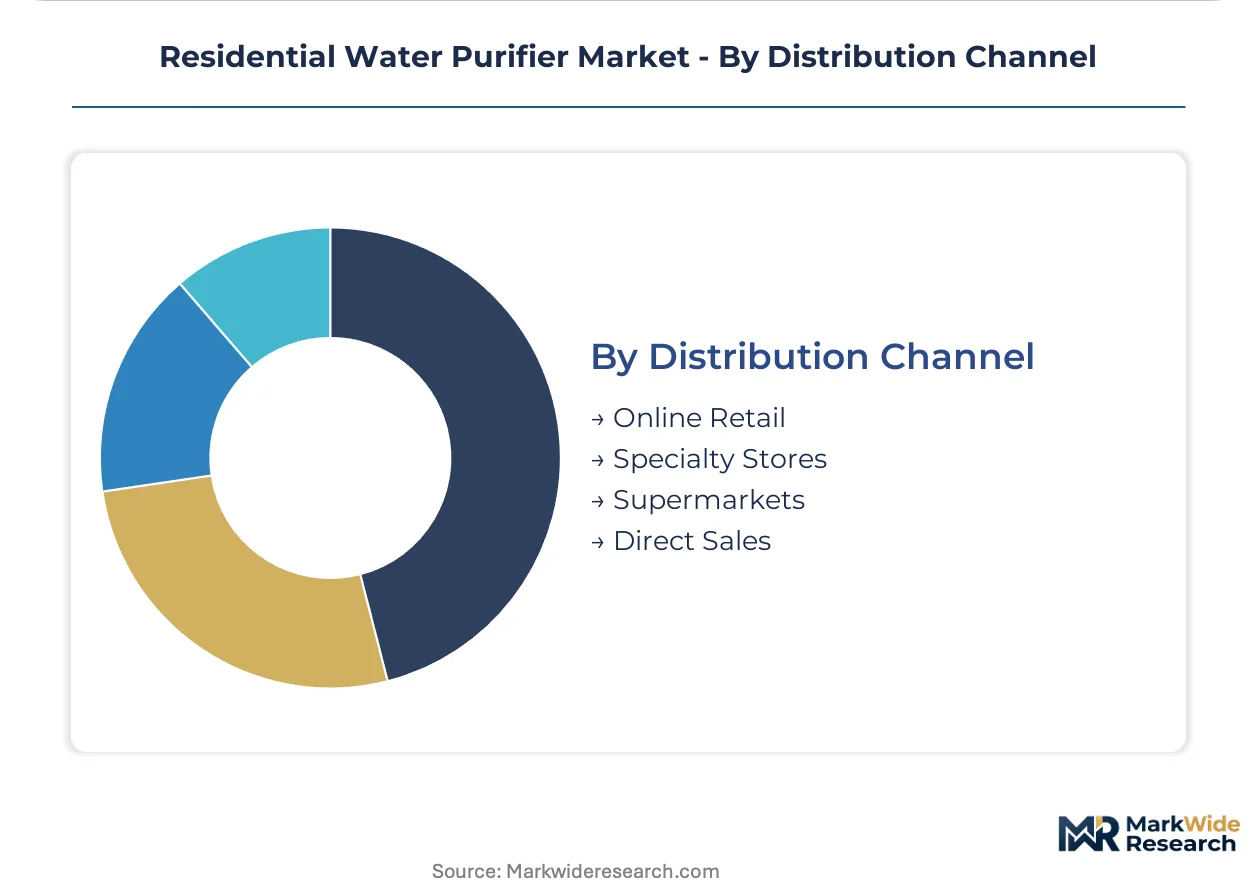
Distribution Channel:
Channel economics determine customer acquisition cost, installation coordination burden, and aftermarket service attach rates across purchase pathways.
- Online Retail:Platform-mediated transactions with logistics-integrated installation partnerships collapse traditional dealer networks. First-time buyer segments in Indian metro corridors exhibit accelerating migration to e-commerce channels.
- Specialty Stores:Dedicated water treatment retailers provide hands-on specification consultation and immediate consumable availability. Service bundling sustains margin capture in membrane replacement scheduling.
- Supermarkets:Mass merchandiser placement targets impulse replacement cartridge purchases and entry-level system trials. Limited technical consultation compresses average selling prices.
- Direct Sales:Manufacturer-employed or contracted field representatives deliver in-home water testing and customized system specification. Eureka Forbes sustains recurring revenue streams through captive direct-to-home service infrastructure.
Direct sales retains highest service attach rates. Online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban apartment dwellers in China, India, and the United States drive demand concentration, with municipal water quality variability and rental financing compatibility shaping specification patterns across metropolitan corridors.
China
Shenzhen and Shanghai property management firms pilot fleet-wide smart purification deployment as tenant turnover exceeds equipment depreciation cycles. SAMR enforces GB standards for water treatment equipment performance labeling, tightening compliance documentation for cross-border suppliers. Pearl River Delta manufacturing clusters concentrate membrane element production for regional OEM supply.
India
Mumbai and Bengaluru apartment corridors exhibit accelerating subscription-model adoption where deposit constraints limit capital outlay tolerance. BIS drinking water purifier standards mandate quantitative contaminant reduction disclosures, eliminating substandard imports and consolidating domestic manufacturing capacity. National Capital Region suburban corridors sustain point-of-entry system specification where municipal supply intermittency persists.
United States
First-time buyer segments migrate toward platform-mediated online retail as logistics-integrated installation partnerships reduce purchase friction. EPA Safe Drinking Water Act and NSF/ANSI standards extend product launch timelines for multi-contaminant reduction claims. Southwest and Sun Belt metros exhibit specification concentration where groundwater hardness profiles elevate ion exchange demand.
Germany
REACH and RoHS compliance requirements shape material selection for residential treatment equipment marketed across EU member states. Bavaria and Baden-Württemberg industrial corridors host precision filtration component fabrication for premium residential specifications. German households demonstrate elevated NSF-certified build quality preference in owner-occupied single-family installations.
Japan
Tokyo and Osaka metropolitan households specify UV-C LED configurations where municipal pre-treatment reduces dissolved solids burden. METI efficiency regulations and JIS standards govern product performance claims and energy consumption labeling. Kanto region electronics manufacturing clusters supply sensor arrays for connected monitoring capabilities.
Residential Water Purifier Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Direct-to-home service infrastructure and captive manufacturing capabilities define strategic positioning. Three archetypes dominate: integrated service-network operators, membrane-technology specialists, and diversified appliance conglomerates. Competitive moves concentrate on logistics-platform partnerships and backward integration into membrane component supply.
Among diversified appliance conglomerates, LG Electronics and Whirlpool occupy positions spanning mass-market retail and premium specification tiers. Within the water-purification specialist tier, Brita exemplifies consumable-dependent recurring revenue models, while Kent RO Systems anchors the membrane-technology specialist archetype through captive manufacturing positioning. Eureka Forbes represents the integrated service-network model with direct-to-home infrastructure sustaining aftermarket attachment rates.
| Leading Market Players |
|---|
| Brita |
| Culligan |
| Pentair |
| A. O. Smith |
| Eureka Forbes |
| LG Electronics |
| Whirlpool |
| Kent RO Systems |
| Panasonic |
| Others |
Supply Flow & Price Mechanics
East Asian chemical processing clusters concentrate thin-film composite reverse osmosis membrane production, anchoring margin pools in aftermarket replacement cycles rather than initial equipment sales. This upstream concentration forces downstream pricing discipline around consumable dependencies and service bundling.
Pricing Analysis
Certification level creates the primary spread between premium NSF/ANSI-certified builds and self-certified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes, with BIS-mandated quantitative disclosure requirements in India compressing margins on unverified claims. Price erosion runs through entry-level ultraviolet configurations as UV-C LED maturation reduces component costs. Apartment dwellers in Chinese tier-one cities exhibit highest price sensitivity due to tenant turnover economics, while villa owners in healthcare-adjacent installations demonstrate lowest sensitivity to upfront capital outlay.
Supply Chain Analysis
Contract manufacturing capacity for membrane element fabrication concentrates in Pearl River Delta facilities serving regional OEM demand. China, South Korea, and Japan anchor raw material supply for polyamide active layers, polysulfone support structures, and UV-C LED semiconductor substrates. Single-source vulnerability persists in specialized ion exchange resin formulations. Distribution runs through platform-mediated online retail partnerships collapsing traditional dealer-installer networks in Indian and US first-time buyer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified field technician scarcity constrains service network expansion, creating acquisition premiums for players with trained workforce pipelines. This capability gap rewards early investment in training infrastructure and predictive maintenance technology deployment.
For Market Incumbents: Entrench service attach rates by deepening backward integration into membrane component supply and locking property management firm relationships through fleet-wide smart system pilots in Chinese Shenzhen and Shanghai corridors. Defend against unbundled online platform entrants by accelerating subscription financing penetration where deposit constraints limit capital outlay tolerance among Indian apartment dwellers.
For New Entrants and Emerging Players: Mid-market rental apartments in India's Mumbai and Bengaluru corridors represent the most penetrable entry point given BIS certification consolidation eliminating substandard import competition. UV-C LED configurations for pre-treated municipal supply regions offer specification differentiation without membrane import dependency. Platform logistics partnerships with installation coordination capabilities provide the critical go-to-market angle for first-time buyer capture.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with direct-to-home service infrastructure operators possessing captive technician networks and recurring revenue streams. Long-term viability centers on membrane replacement economics durability and regulatory compliance documentation capabilities across multi-jurisdiction product platforms. Monitor BIS enforcement intensity and SAMR GB standards alignment progress as inflection indicators for domestic manufacturing consolidation pace.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive supply of thin-film composite elements insulates margin pools from petrochemical feedstock volatility. |
| Smart System Fleet Deployment | Property management firm partnerships in Chinese tier-one cities compress break-fix intervals into subscription revenue. |
| Platform Logistics Partnership | E-commerce channel integration with installation coordination collapses customer acquisition costs in Indian metro corridors. |
| BIS Certification Investment | Quantitative contaminant reduction disclosure compliance eliminates substandard import competition in domestic manufacturing. |
| UV-C LED Technology Transition | Mercury arc displacement reduces operating costs and enables rental-subscription channel penetration in municipal pre-treatment regions. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and platform transaction records. Interviews with water treatment equipment procurement managers, property management firm operations directors, membrane manufacturing plant engineers, and certified field service technicians informed demand segmentation and replacement cycle assumptions. BIS notification records, SAMR GB standard documentation, and EPA Safe Drinking Water Act enforcement data provided regulatory constraint calibration. Bottom-up equipment shipment analysis and top-down household penetration modeling were cross-validated for triangulation.
Forecast inputs include membrane replacement interval elasticity, subscription financing adoption curves, and certification compliance cost trajectories across the analysis window. Segmentation dimensions span purification technology, end-user accommodation type, distribution channel, and regional regulatory cluster. CAGRs derive from installed base growth and consumable attach rate projections. Industry-specific inputs incorporate BIS testing protocol acceleration timelines and UV-C LED cost decline curves.
Macroeconomic conditions sit as an overlay; deviation in residential construction permitting, urban rental vacancy rates, or municipal infrastructure investment would shift the trajectory. Forecasts reflect documented assumptions around membrane import dependency persistence and regulatory enforcement continuity. Quarterly review of certification body backlog data and platform seller concentration metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Middle East and Africa Air Purifier Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Saudi Arabia Cookware Market
Household Items
Air Humidifier Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
US Flashlights Market
Household Items
Smart Air Purifier Market
Household Items
Hydralight Lanterns Market
Household Items
Stick Vacuum Cleaner Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Electric Soap Dispenser Market
Household Items
Liquid Hand Soap Market
Household Items
Powered Lawn Mowers Market
Household Items
Pet Safe Cleaners Market
Household Items
Hand Wash Station Market
Household Items
Smart Toilet Market