
 Hydrogen Fuel Cell Train Market | 2026-2036
Hydrogen Fuel Cell Train Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Fuel Cell Train Market Analysis
The hydrogen fuel cell train sector is restructuring around a sharp divergence between premium integrated systems and commodity powertrain components. Alstom leverages its Coradia iLint platform to dominate European passenger corridors with complete train-integrated hydrogen solutions. Siemens Mobility competes through high-voltage traction expertise and digital rail infrastructure coupling. Ballard Power Systems anchors the supply base with specialized fuel cell stack manufacturing for multiple rolling stock integrators.
A hydrogen fuel cell train converts chemical energy from compressed hydrogen into electricity via proton exchange membrane or solid oxide fuel cells, typically operating at 300-700 kW gross power output to drive electric traction motors for zero-emission rail propulsion. Passenger trains command the dominant share of current deployments as municipal operators replace diesel multiple units on non-electrified lines. Proton exchange membrane technology leads commercial adoption due to its favorable power density and cold-start performance for rail duty cycles. Urban transit applications concentrate near-term demand where route predictability simplifies hydrogen refueling infrastructure planning.
Germany's KBA certifies hydrogen train safety standards while the EU F-Gas Regulation shapes coolant and sealing material compliance across European deployments. Japan's METI hydrogen supply chain targets and the EU Green Deal's 2050 climate neutrality framework directly mandate public procurement shifts away from diesel traction. Stakeholders must monitor hydrogen production cost curves and electrolyzer scaling timelines to align fleet investment decisions with fuel availability.
Market Dynamics
EU Green Deal rail decarbonization mandates are forcing municipal transit authorities to accelerate diesel fleet replacement, compressing procurement timelines and reshaping supplier qualification criteria across European corridors.
Growth Catalysts
- EU F-Gas Regulation:The regulation mandates phase-down of high-global-warming-potential coolants, driving rolling stock integrators toward proton exchange membrane fuel cell architectures with compliant thermal management systems.
- German KBA certification pathway:Germany's federal motor transport authority established streamlined hydrogen train safety protocols, reducing type-approval timelines for regional passenger operators replacing diesel multiple units.
- Compressed hydrogen infrastructure:Electrolyzer scaling along Hamburg-Frankfurt and Tokyo-Osaka corridors is concentrating refueling node deployment, enabling predictable route planning for fuel cell rolling stock procurement.
Market Restraints
- Platinum group metal supply concentration:Fuel cell stack manufacturing depends on platinum and iridium catalysts sourced from South African and Russian mining operations, exposing integrators to geopolitical supply disruptions and price volatility.
- Electrified line substitution:Battery-electric multiple units with catenary-infill capability are capturing shorter non-electrified segments, constraining addressable route length for hydrogen-only deployments.
- High-voltage traction integration complexity:Solid oxide fuel cell systems require thermal cycling management incompatible with rapid passenger rail duty cycles, limiting technology optionality for high-frequency services.
Strategic Opportunities
- Japan METI hydrogen supply chain targets:Japan's Ministry of Economy, Trade and Industry allocated public funding for hydrogen production, storage, and distribution infrastructure, creating procurement pull for fuel cell rolling stock on Shinkansen feeder lines.
- Freight locomotive retrofit kits:Shunting yard and short-haul freight operators represent an untapped application segment, with modular fuel cell powerpacks enabling diesel locomotive conversion without full fleet replacement.
- Digital rail infrastructure coupling:Integration of fuel cell train telematics with traffic management systems enables predictive refueling optimization, opening service contract models linking energy supply to operational availability guarantees.
Industry Challenges
- High-voltage electrical safety certification:Traction system validation requires specialized testing facilities with hydrogen handling capabilities, creating bottlenecks as multiple rolling stock programs compete for limited KBA and TÜV audit slots.
- Cross-functional workforce gaps:Maintenance depots must retrain diesel mechanics on cryogenic hydrogen storage, high-pressure fueling protocols, and fuel cell stack diagnostics, stretching technical training capacity across European operator networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Fuel Cell Train Market |
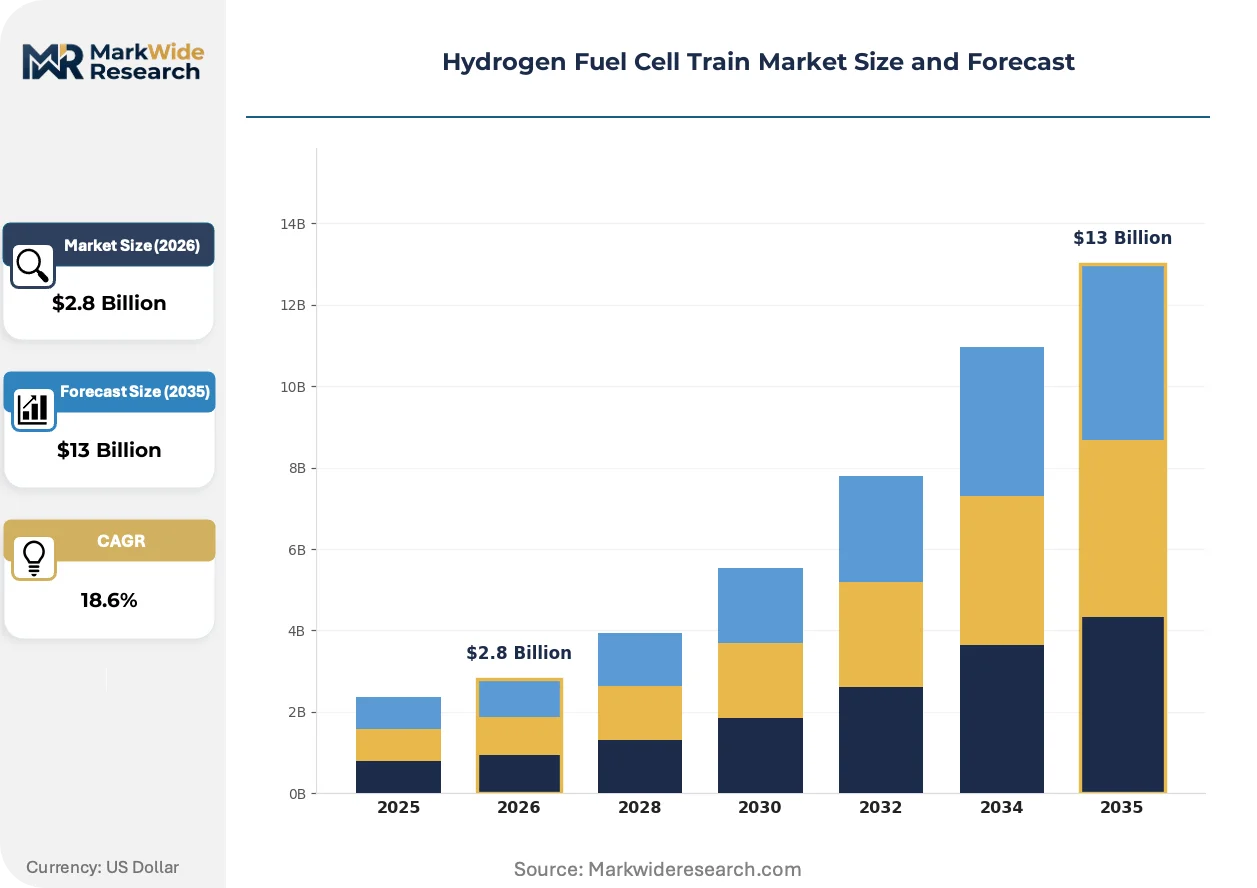
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Trains, Freight Trains, Light Rail, High-Speed Trains Technology: Proton Exchange Membrane, Alkaline Fuel Cells, Solid Oxide Fuel Cells, Direct Methanol Fuel Cells End User: Public Transport, Freight Operators, Private Operators, Government Agencies Application: Urban Transit, Intercity Travel, Cargo Transport, Specialized Services |
| Companies Covered | Alstom, Siemens Mobility, Ballard Power Systems, CRRC Corporation, Stadler Rail, Hitachi Rail, CAF, Hyundai Rotem, Toyota Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Fuel Cell Train Market Emerging Trajectories
Modular fuel cell powerpack architectures are fragmenting supplier relationships, enabling regional integrators to compete without captive stack manufacturing while compressing development cycles for specialized rolling stock variants.
Proton exchange membrane fuel cell technology is decentralizing propulsion system sourcing for regional train builders. Czech and Polish rolling stock manufacturers now procure Ballard and Hyundai fuel cell modules separately from traction inverter packages, collapsing the traditional integrated powertrain procurement model. This componentization enables shorter product development timelines for specialized narrow-gauge and mountain railway variants previously uneconomical for platform-scale production.
Japan's METI hydrogen roadmap is mandating public-private consortia for refueling infrastructure deployment along designated corridors. The policy requires municipal transit authorities to coordinate hydrogen supply agreements with industrial off-take clusters, locking in demand aggregation mechanisms before rolling stock procurement proceeds. Prefecture-level operators in Shizuoka and Gifu are restructuring tender specifications around 20-year fuel availability guarantees rather than capital cost minimization.
Service-based contracting is displacing capital purchase models for fuel cell rolling stock in German regional concessions. Transport authorities in Lower Saxony and Schleswig-Holstein now specify availability-based payments covering energy, maintenance, and mid-life stack replacement, transferring technology performance risk to rolling stock lessors. This financial structure favors fleet operators with captive hydrogen supply relationships and compressed operational data feedback loops for predictive maintenance algorithm refinement.
Hydrogen Fuel Cell Train Market Segmentation
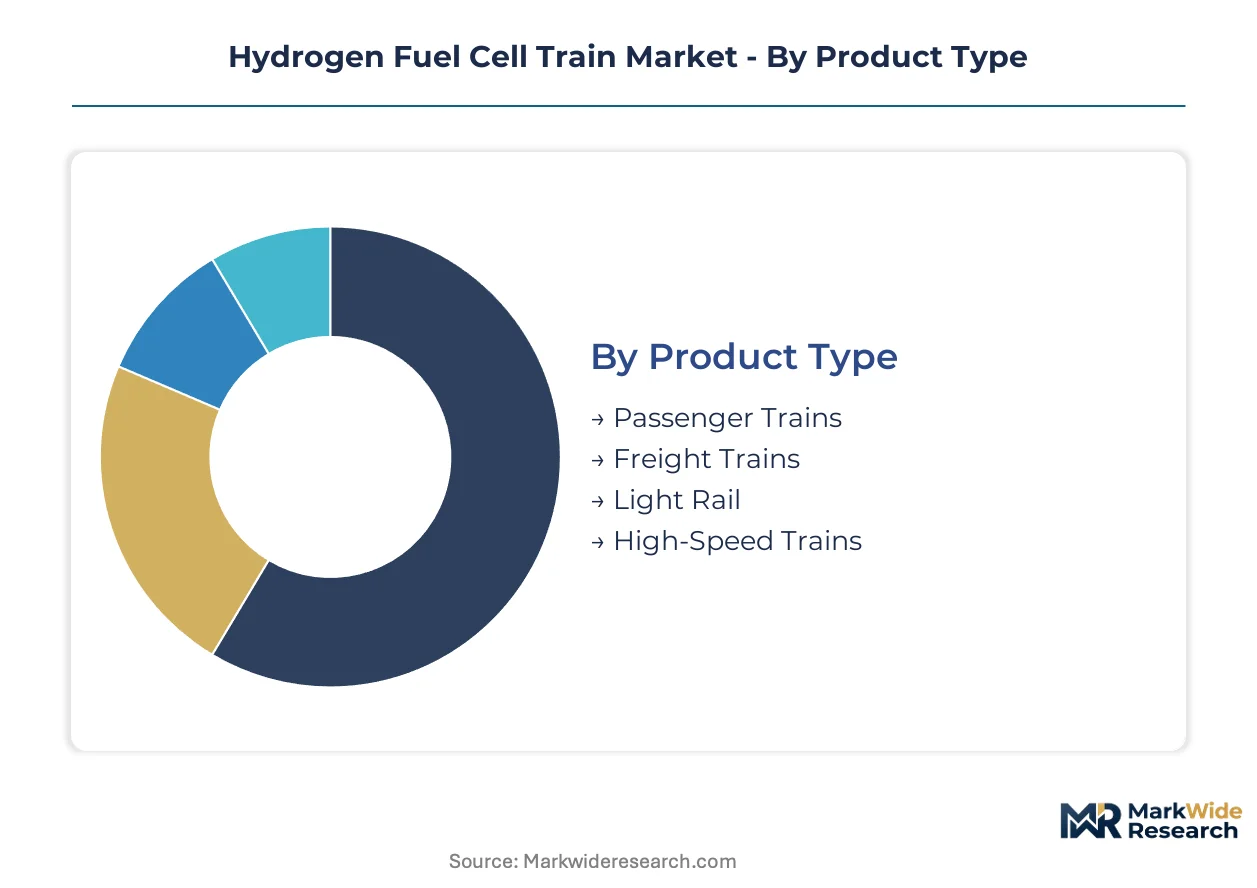
Segmentation in hydrogen fuel cell trains reveals how procurement criteria diverge between municipal operators optimizing for route predictability and freight integrators prioritizing power density. Technical specifications, duty cycle demands, and infrastructure availability reshape competitive positioning across each dimension.
Product Type:
Route electrification status and fleet replacement timelines determine which product category captures procurement budgets.
- Passenger Trains:Regional multiple units dominate current deployments, with German operators replacing diesel fleets on Hamburg-Frankfurt corridors. KBA certification pathways compress procurement timelines for these standardized configurations.
- Freight Trains:Shunting yard locomotives and short-haul switchers represent emerging demand, with modular powerpacks enabling diesel conversion without full fleet replacement. Yard operators prioritize torque density over top speed.
- Light Rail:Tram-train hybrids on mixed-traffic urban corridors.
- High-Speed Trains:Experimental prototypes for Shinkansen feeder lines in Japan.
Passenger trains lead on scale; freight trains lead on momentum.
Technology:
Power density requirements and thermal management constraints filter viable fuel cell architectures for rail duty cycles.
- Proton Exchange Membrane:Favorable power-to-weight ratios and cold-start performance below freezing temperatures suit regional passenger services. EU F-Gas Regulation compliance drives coolant system redesigns toward lower-global-warming-potential alternatives.
- Solid Oxide Fuel Cells:Higher electrical efficiency appeals to stationary auxiliary power applications, but thermal cycling limitations restrict traction use. Rapid start-stop rail duty cycles expose ceramic stack durability challenges.
- Alkaline Fuel Cells:Lower catalyst costs attract stationary hydrogen production integration.
- Direct Methanol Fuel Cells:Liquid fuel handling advantages for remote maintenance vehicles.
Proton exchange membrane dominates installed base; solid oxide fuel cells show steepest expansion trajectory in auxiliary applications.
End User:
Capital structure and risk appetite separate public procurement from private fleet investment patterns.
- Public Transport:Municipal authorities in Lower Saxony and Schleswig-Holstein specify availability-based contracts covering energy, maintenance, and mid-life stack replacement. Twenty-year fuel availability guarantees now outweigh upfront capital minimization.
- Government Agencies:National rail infrastructure owners fund demonstration corridors to validate multi-operator hydrogen supply chains.
- Freight Operators:Yard-focused retrofit economics favor incremental powerpack deployment.
- Private Operators:Tourist and heritage railway niche applications.
Public transport commands procurement volume; government agencies set technical standards.
Application:
Route predictability and refueling infrastructure density determine hydrogen competitiveness against battery-electric alternatives.
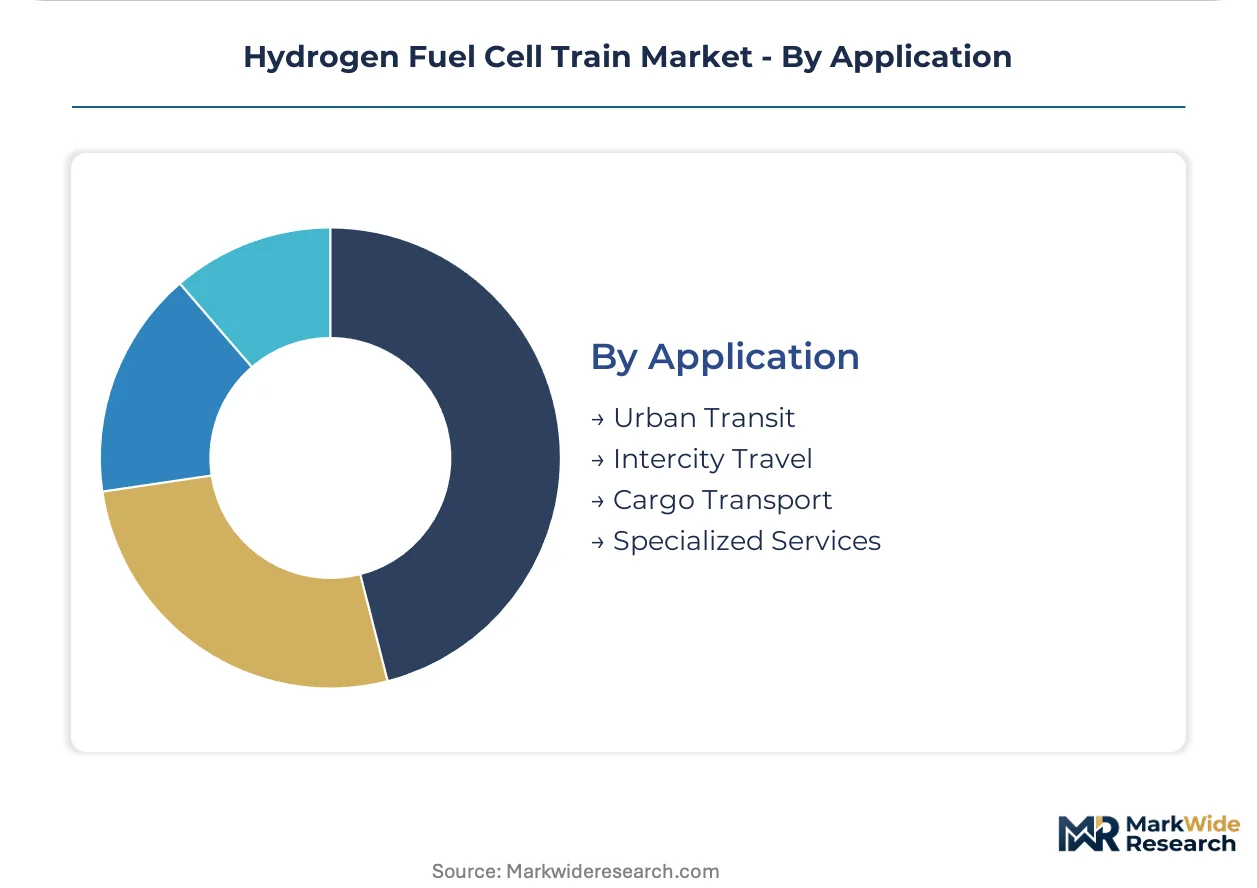
- Urban Transit:Fixed-route tram and metro extensions concentrate near-term demand where electrolyzer nodes align with depot locations. Prefecture-level operators in Shizuoka coordinate hydrogen supply with industrial off-take clusters.
- Intercity Travel:Non-electrified regional corridors between 100-400 kilometers represent the addressable sweet spot. Battery-electric multiple units with catenary-infill capability capture shorter segments.
- Cargo Transport:Port shuttle and last-mile container movements.
- Specialized Services:Maintenance-of-way vehicles and tunnel rescue trains.
Urban transit anchors deployment density; intercity travel offers largest unconstrained route inventory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized rail engineering talent clusters in Germany and Japan anchor hydrogen fuel cell train development, with cross-border technical exchange programs accelerating certification expertise transfer between KBA auditors and METI standards bodies.
Germany
Regional transit authorities in Lower Saxony and Schleswig-Holstein operate Europe's largest hydrogen train fleet under availability-based service contracts. The KBA streamlined type-approval protocols for fuel cell rolling stock, cutting certification timelines by half for diesel replacement corridors. Industrial hydrogen clusters along the Hamburg-Frankfurt corridor concentrate electrolyzer deployment near rail maintenance depots.
Japan
METI's hydrogen roadmap mandates public-private consortia for refueling infrastructure along Shinkansen feeder lines in Shizuoka and Gifu prefectures. The ministry allocated dedicated funding for 20-year fuel availability guarantees, restructuring procurement criteria away from capital cost minimization. Prefecture-level operators coordinate hydrogen supply agreements with industrial off-take clusters before fleet procurement proceeds.
China
CRRC Corporation leverages domestic electrolyzer manufacturing scale to compress fuel cell powerpack costs for regional railway applications. The national railway administration designated hydrogen demonstration corridors in the Yangtze River Delta under dual carbon policy frameworks. Provincial operators in Jiangsu and Zhejiang pilot fuel cell multiple units on non-electrified commuter segments.
France
Alstom's Coradia iLint production facility in Salzgitter supplies French regional operators replacing diesel fleets under EU Green Deal rail decarbonization mandates. The national railway safety authority harmonized hydrogen train certification with German KBA standards, enabling cross-border fleet deployment. Industrial hydrogen hubs in the Auvergne-Rhône-Alpes region align refueling infrastructure with Alpine railway corridors.
United Kingdom
Network Rail's traction decarbonization strategy identifies hydrogen as optimal for rural routes exceeding battery-electric range limits. The Department for Transport allocated demonstration funding for regional passenger services in the Midlands and North England. Hydrogen supply partnerships with industrial clusters in Teesside and Merseyside anchor planned refueling infrastructure for 2028 fleet deployments.
Hydrogen Fuel Cell Train Market Vendor Landscape
Capital-heavy rolling stock integrators compete with specialized fuel cell component suppliers for value chain positioning. European manufacturers dominate complete train-integrated solutions through captive traction system expertise, while North American and Asian stack specialists supply modular powerpacks to regional integrators. Three archetypes define competitive structure: platform-scale train builders, fuel cell stack specialists, and emerging regional assemblers sourcing decoupled propulsion modules. Consolidation pressure operates through strategic partnerships linking hydrogen supply guarantees to fleet procurement, plus technology licensing agreements compressing development timelines for narrow-gauge variants.
Among platform-scale European integrators, Alstom and Siemens Mobility exemplify the complete-system archetype through integrated hydrogen train offerings. Ballard Power Systems anchors the fuel cell specialist tier as a stack supplier to multiple rolling stock programs. Stadler Rail occupies a hybrid position, sourcing modular powerpacks from external fuel cell providers while retaining final system integration and vehicle assembly expertise.
| Leading Market Players |
|---|
| Alstom |
| Siemens Mobility |
| Ballard Power Systems |
| CRRC Corporation |
| Stadler Rail |
| Hitachi Rail |
| CAF |
| Hyundai Rotem |
| Toyota Motor Corporation |
| Others |
Supply Flow & Price Mechanics
Rare fuel cell stack engineering talent clusters in Germany and Japan widen pricing spreads between premium integrated train systems and commodity powerpack components. Labor-cost differentials between these specialized engineering hubs and emerging assembly locations in Central Europe compress margins on standardized regional train variants while sustaining premium capture for KBA-certified complete-system offerings.
Pricing Analysis
Bundled availability-based service contracts now dominate procurement in German regional concessions, displacing traditional capital purchase models. Pricing stratifies across premium complete-train integrators, mid-tier modular assemblers, and economy component suppliers, with differentiation driven by KBA certification status and captive hydrogen supply relationships. Cost compression in the mid-tier is intensifying as Czech and Polish manufacturers source decoupled fuel cell modules from Ballard and Hyundai. Municipal operators in Lower Saxony show lowest price sensitivity due to 20-year fuel availability guarantees, while freight yard operators exhibit highest sensitivity to upfront powerpack costs.
Supply Chain Analysis
KBA and METI certification pathways gate supplier qualification, concentrating fuel cell stack manufacturing in Germany, Japan, and Canada. Platinum and iridium catalysts draw from South African and Russian mining operations, while proton exchange membrane materials source from specialized chemical producers in the United States and Belgium. Single-source vulnerability in platinum group metal supply exposes integrators to geopolitical disruption and price volatility. Distribution runs through rolling stock lessors with captive hydrogen supply relationships, linking fleet deployment to refueling infrastructure lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen fuel cell train market compounds steadily as EU Green Deal mandates force diesel replacement timelines across European regional corridors. This regulatory enforcement creates predictable procurement visibility for rolling stock integrators and component suppliers alike.
For Market Incumbents: Deepen backward integration into platinum group metal recycling and alternative catalyst R&D to mitigate supply concentration risk from South African and Russian sources. Secure long-term electrolyzer offtake agreements in the Hamburg-Frankfurt corridor to anchor availability-based service contract economics. Battery-electric multiple units with catenary-infill capability threaten hydrogen's addressable route length; defend through high-voltage traction integration expertise that solid oxide fuel cell competitors cannot match. For New Entrants and Emerging Players: Heritage railway and tourist line operators represent an underserved buyer archetype with limited procurement sophistication and relaxed certification requirements. Narrow-gauge mountain railways in Alpine corridors offer penetrable entry points where platform-scale manufacturers disengage due to volume constraints. Shunting yard retrofit kits for diesel locomotive conversion provide white-space access with modular powerpack economics. A component-supplier-to-regional-integrator go-to-market angle bypasses direct competition with Alstom and Siemens Mobility. For Investors and Strategic Acquirers: Rolling stock lessors with integrated hydrogen supply operations are the most active acquirer in this space, consolidating fleet operators to capture availability-based contract economics. The 5-10 year investment horizon favors fuel cell stack specialists with proven rail duty cycle validation over pre-revenue technology developers. Watch electrolyzer cost curves and green hydrogen production scaling timelines as the primary inflection indicator for fleet deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Availability-Based Service Contract Expansion | Transports technology performance risk to fleet operators with hydrogen supply integration. |
| Fuel Cell Stack Specialist Acquisition | Consolidates modular powerpack supply relationships for regional train builders. |
| Electrolyzer Node Co-Location | Aligns refueling infrastructure with KBA-certified maintenance depots in Hamburg-Frankfurt corridor. |
| Platinum Group Metal Recycling Investment | Reduces catalyst supply exposure to South African and Russian mining concentration. |
| Narrow-Gauge Platform Development | Captures heritage railway and mountain corridor demand outside standard gauge competition. |
Methodological Framework
Direct dialogue with rolling stock procurement directors, KBA certification auditors, fuel cell stack engineering leads, and regional transit authority planning officers grounded qualitative assessment. Secondary validation drew from EU F-Gas Regulation filings, German federal transport authority type-approval databases, METI hydrogen roadmap documentation, and electrolyzer deployment registries. Bottom-up fleet deployment tracking and top-down regulatory mandate analysis triangulated market sizing.
Installed base projections and revenue estimates emerged from segment-level modeling across passenger train, freight locomotive, and maintenance vehicle categories throughout the forecast period. Power output tier, route electrification status, and refueling infrastructure density shaped segmentation dimensions. CAGRs derived from electrolyzer scaling timelines, platinum price trajectory assumptions, and diesel fleet replacement schedule acceleration under EU Green Deal enforcement. Hydrogen production cost curves and fuel cell stack durability improvements anchored technology adoption rate inputs.
Underlying measurement precision varies by segment; German regional passenger deployments carry tighter precision than emerging freight retrofit applications due to KBA disclosure requirements. Forecasts reflect assumptions on electrolyzer deployment pacing, catalyst cost trajectories, and battery-electric competitive substitution thresholds. A model refresh is warranted upon material change in EU Green Deal enforcement intensity or platinum group metal supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Bullet Train Market
Railway
Railway Buffer Stops Market
Railway
France Connected Rail Market
Railway
Railway Braking System Market
Railway
Railway Pantograph Market
Railway
Freight Cars Market
Railway
Automatic Train Control Market
Railway
Rail Brace Market
Railway
Rail Seat Market
Railway
Rolling Stock Management Market
Railway
India Rail Freight Transport Market
Railway
Automatic Train Operation System Market
Railway
Global Train Brake Market
Railway
Railway Axle Market
Railway
Locomotive Market
Railway
Railroad Tie Market