
 40-Foot Platform Wagons Market | 2026-2036
40-Foot Platform Wagons Market Size, Share, and Industry Trends Forecast 2026-2036
40-Foot Platform Wagons Market Outlook
Logistics operators are unwinding historical reliance on general freight carriers and redirecting procurement toward dedicated intermodal platforms. VTG GmbH leverages its European leasing network to capture fleet turnover demand. UWC RPC PJSC anchors production capacity near the Russian border for eastbound cargo flows. Tatravagónka a.s. competes on specialized bogie designs that reduce track wear.
A 40-foot platform wagon is a rail-mounted flatcar measuring approximately twelve meters in deck length, designed to carry standardized intermodal containers, swap bodies, or semi-trailers at maximum gross weights up to ninety tonnes. Flatbed configurations dominate European corridors because they handle double-stacked containers and roll-on cargo with minimal deck height restrictions. Steel construction sustains the installed base despite aluminum growth in lightweight regional fleets. Heavy hauling applications concentrate margin pools where axle-load certifications command premium lease rates.
The European Union Agency for Railways (ERA) enforces interoperability standards that dictate braking performance and gauge clearances across member networks. Germany's Federal Railway Authority (EBA) and Poland's Office of Rail Transport (UTK) administer national safety approvals that gate market access for new wagon designs. Stakeholders must monitor how the EU Green Deal freight modal-shift targets reshape procurement timelines and infrastructure investment priorities.
Market Dynamics
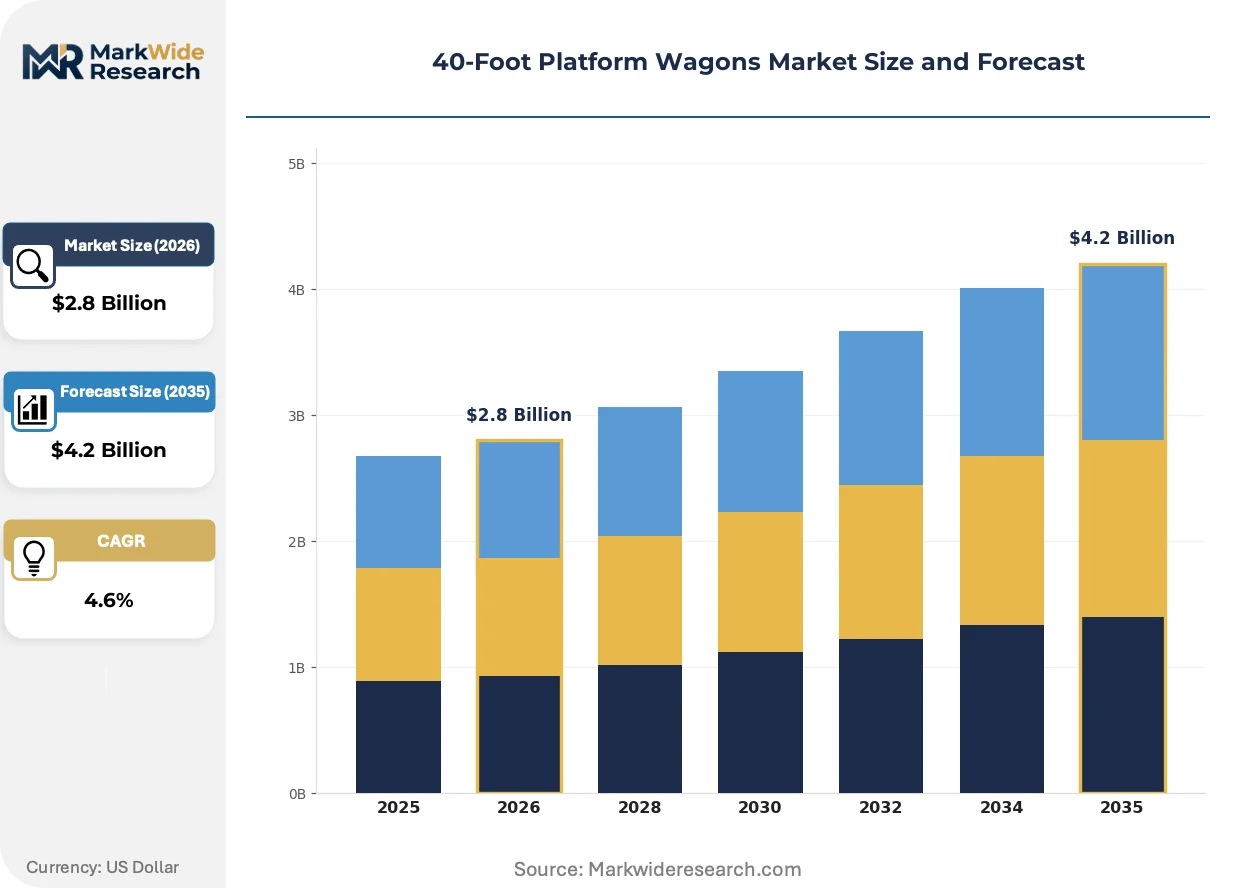
Rail freight modal-shift mandates under the EU Green Deal are forcing logistics operators to accelerate fleet replacement cycles, tightening the link between wagon availability and corridor capacity planning.
Growth Catalysts
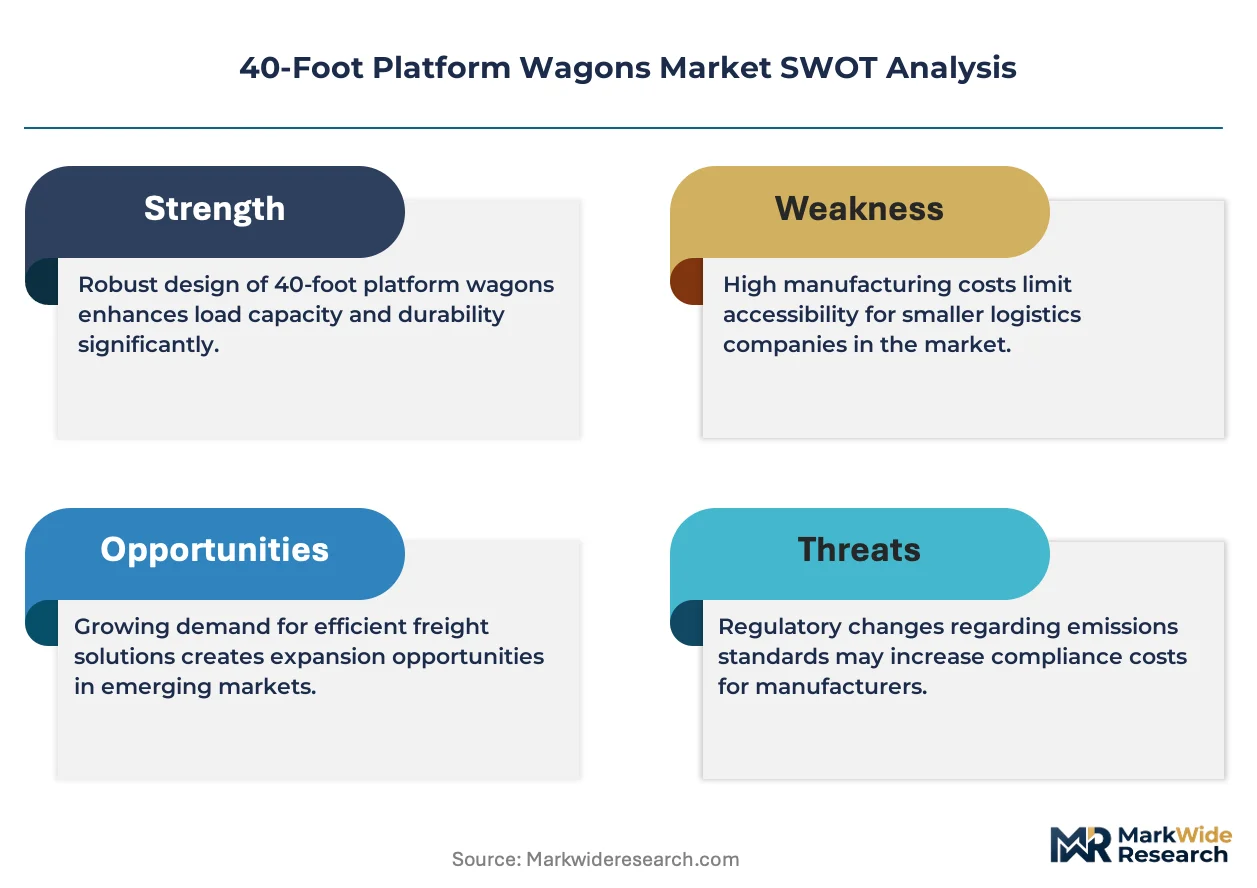
- Axle-load harmonization:ERA interoperability standards are enabling cross-border fleet deployment without national recertification, reducing idle time on Germany-Poland corridors.
- Steel recycling mandates:Circular economy frameworks are extending wagon lifecycle value through certified refurbishment programs at central European maintenance hubs.
- Port congestion spillover:Rotterdam and Hamburg container backlogs are redirecting volume onto rail-ferry connections that demand 40-foot platform flexibility.
Market Restraints
- Specialized steel plate supply:High-tensile deck construction relies on concentrated rolling mill capacity in the Czech Republic and Slovakia, creating input bottlenecks.
- Brake system certification lag:EBA type-approval timelines for composite brake blocks extend 14-18 months, freezing design iterations.
- Road freight substitution:Flexible trucking networks capture time-sensitive cargo that rail scheduling cannot accommodate.
Strategic Opportunities
- Polish corridor expansion:Małaszewicze terminal upgrades are creating demand for wagons configured to Russian and Chinese gauge interfaces.
- Digital freight matching:Platform-based load aggregation is connecting small forwarders directly to leased wagon pools, bypassing traditional fleet operators.
- Battery-electric locomotive pairing:Zero-emission traction requirements are favoring lighter wagon designs that extend electric range on Alpine routes.
Industry Challenges
- Bogie engineering specialization:Y25-derived frame designs require welders certified to EN 15085 Class 1 standards, constraining production scaling.
- Legacy telematics integration:ERA TSI compliance demands retrofitting GPS and axle sensors onto 1990s-era wagons without original documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 40-Foot Platform Wagons Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed, Enclosed, Lowbed, Highboy Material: Steel, Aluminum, Composite, Wood End User: Construction, Manufacturing, Logistics, Agriculture Application: Heavy Hauling, Equipment Transport, Freight Shipping, Material Handling |
| Companies Covered | AstraRail Industries S.A., ELH Waggonbau Niesky GmbH, NYMWAG CS a.s., RM RAIL, Tatravagónka a.s., UWC RPC PJSC, VTG GmbH, Altaivagon Joint-Stock Company, TMH International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
40-Foot Platform Wagons Market Strategic Shifts
Active suspension monitoring and composite braking materials are compressing maintenance intervals while ERA digital certification pathways are shortening design-to-deployment timelines.
Composite brake blocks are decomposing the historical dominance of cast-iron friction materials in heavy-haul applications. Deutsche Bahn Cargo and Polish State Railways are specifying organic composite formulations for new-build orders. This material transition is decomposing the supplier base as foundries lose volume to polymer-ceramic specialists.
EU Green Deal freight modal-shift targets are mandating 30% rail volume growth by 2030, forcing national regulators to accelerate type-approval processes. Germany's EBA has introduced parallel-track certification for proven bogie designs. Polish UTK is adopting mutual recognition agreements to reduce duplicate testing for Czech-manufactured wagons.
Leasing contract structures are shortening from seven-year terms to rolling three-year agreements with maintenance-included pricing. Forwarders in the automotive and chemical sectors are demanding availability guarantees rather than asset ownership. This preference shift is most pronounced in Germany's Rhine-Ruhr industrial cluster where just-in-time supply chains dominate.
40-Foot Platform Wagons Market Segmentation
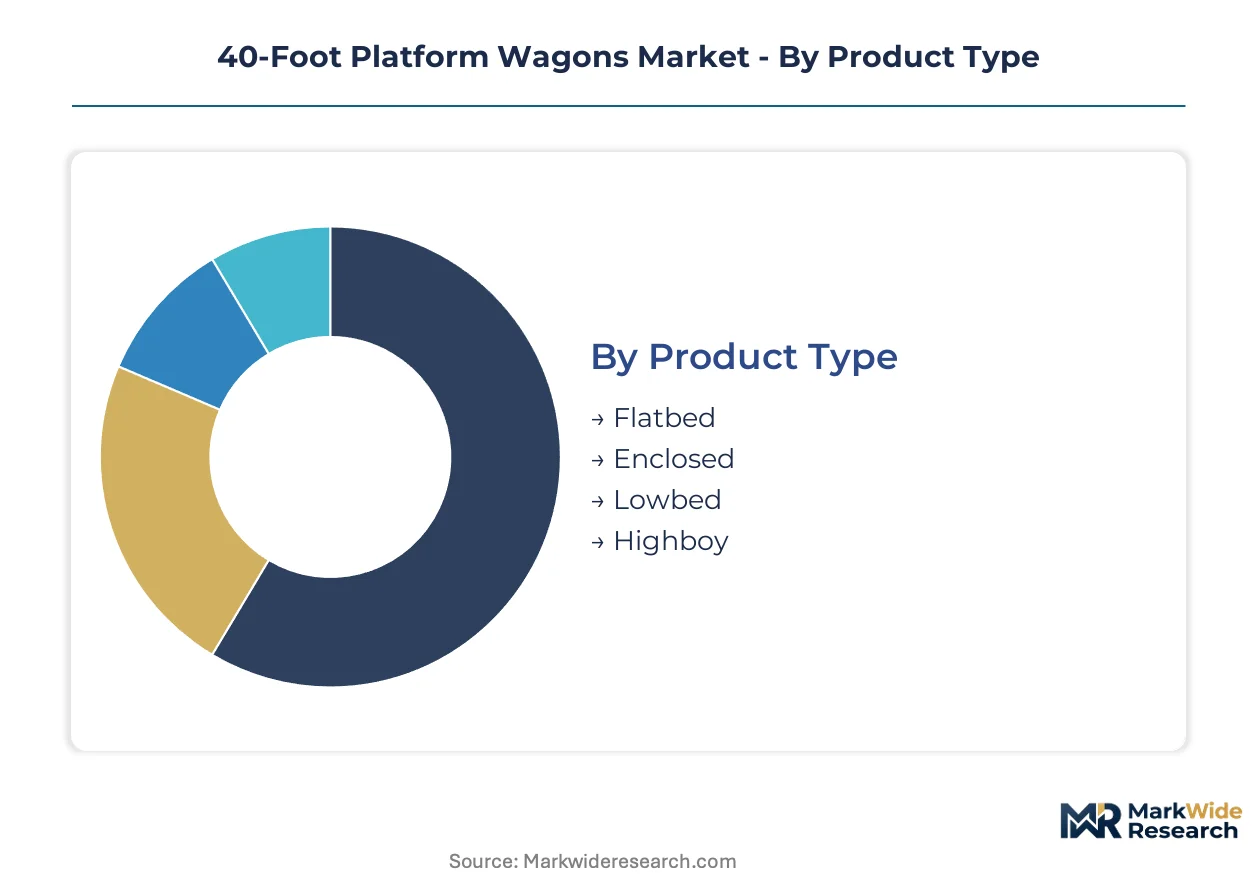
Segmentation in the 40-foot platform wagon market determines fleet procurement patterns, lease rate structures, and maintenance scheduling. Operators match wagon specifications to corridor requirements, cargo types, and interoperability mandates across European networks.
Product Type:
Flatbed configurations flow through direct manufacturer sales and long-term leasing channels, while specialized variants concentrate in project-based procurement.
- Flatbed:Open-deck design accommodates double-stacked containers and roll-on semi-trailers without height restrictions. Demand concentrates on Germany-Poland corridors where ERA gauge clearances enable maximum cube utilization, though operators face axle-load certification delays from EBA.
- Enclosed:Weather-protected cargo space with integrated tarpaulin or hard-shell systems. Automotive and chemical forwarders in the Rhine-Ruhr cluster specify these for just-in-time supply chains where contamination protection commands premium lease rates.
- Lowbed:Reduced deck height for oversized machinery transport.
- Highboy:Elevated frame for vertical clearance on restricted routes.
Flatbed dominates installed base. Enclosed is where expansion concentrates.
Material:
Material selection maps to cost tier and lifecycle strategy, with steel anchoring heavy-haul premium pricing and alternatives penetrating regional feeder networks.
- Steel:High-tensile construction sustains gross weights up to ninety tonnes under EN standards. Czech and Slovak rolling mills supply concentrated plate capacity, creating input bottlenecks that extend delivery timelines for new-build orders.
- Aluminum:Lightweight frames reduce tare weight for battery-electric locomotive pairing on Alpine routes. Polish State Railways and Deutsche Bahn Cargo are specifying these for zero-emission traction corridors where range extension matters.
- Composite:Emerging formulations for specialized corrosion resistance.
- Wood:Limited to heritage and niche applications with minimal commercial volume.
Steel retains margin concentration in heavy hauling. Aluminum is climbing the fastest on modal-shift corridors.
End User:
Customer type dictates contract structure, with logistics operators driving pooled fleet models and construction buyers favoring asset ownership.
- Logistics:Third-party operators and forwarders aggregate demand through leasing networks. VTG GmbH and similar lessors capture this segment with rolling three-year maintenance-included agreements that replace historical seven-year terms.
- Construction:Project developers and contractors purchase dedicated fleets for infrastructure builds. Demand clusters in Poland and the Czech Republic where EU cohesion fund projects are expanding rail siding capacity.
- Manufacturing:Industrial shippers with captive cargo requirements.
- Agriculture:Seasonal grain and bulk commodity movement with intermittent utilization.
Logistics commands pooled fleet economics. Construction is where spot procurement concentrates.
Application:
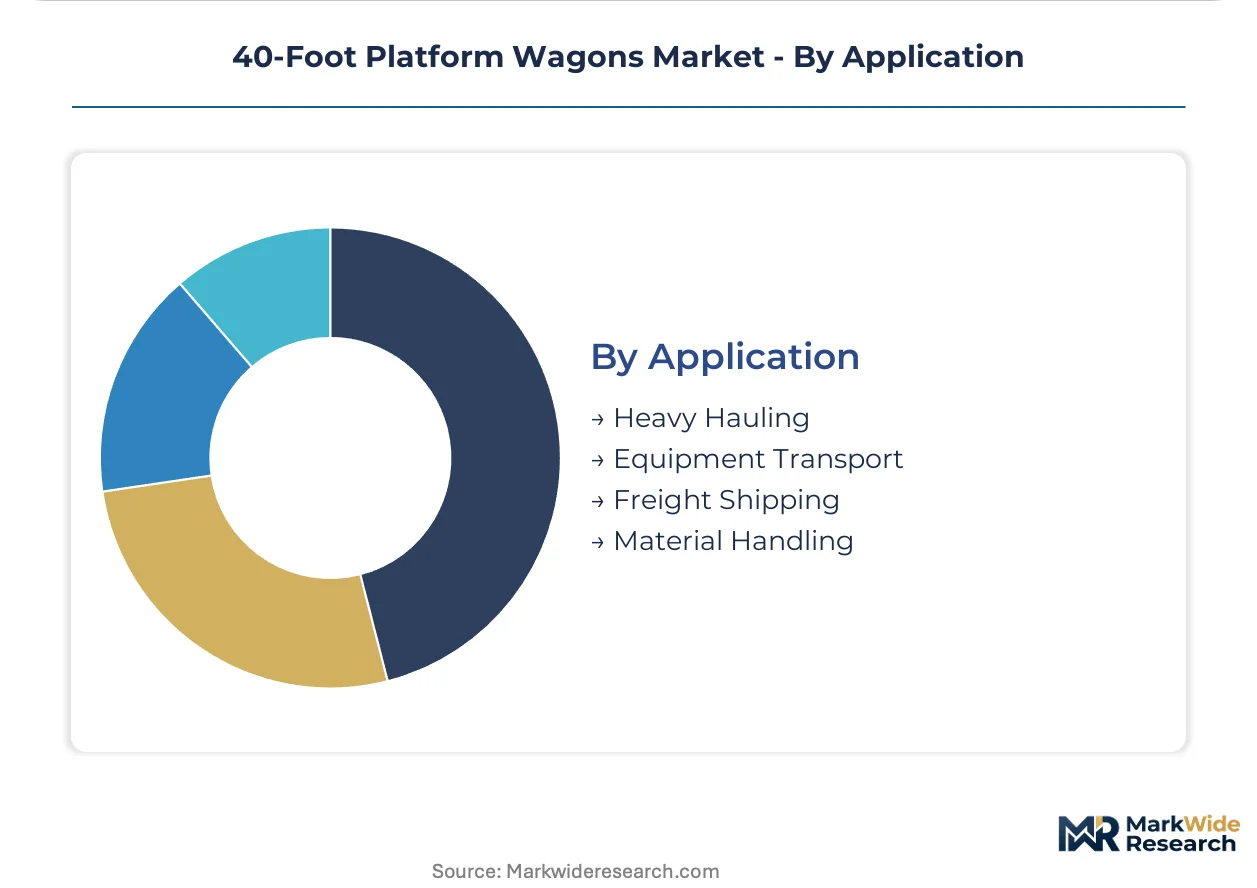
Use case segmentation aligns with brake system certification tiers and axle-load ratings, creating distinct margin pools.
- Heavy Hauling:Maximum axle-load certifications up to ninety tonnes with composite brake blocks. EBA type-approval timelines of 14-18 months freeze design iterations, concentrating margin in proven bogie configurations.
- Freight Shipping:Intermodal container movement with standardized twist-lock fittings. Rotterdam and Hamburg port congestion is redirecting volume onto rail-ferry connections that demand 40-foot platform flexibility.
- Equipment Transport:Project cargo and machinery movement with specialized lashing.
- Material Handling:Short-haul yard and terminal operations with intensive duty cycles.
Heavy Hauling sustains premium lease rate tiers. Freight Shipping is where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Małaszewicze-Brest rail corridor anchors central Europe's east-west freight flows, with terminal upgrades driving concentrated wagon demand across Poland, Germany, and the Czech Republic. This infrastructure asset underwrites the region's role in intermodal container movement between EU markets and Asian rail connections.
Germany
Fleet operators in the Rhine-Ruhr industrial cluster are accelerating replacement cycles for double-stack container wagons. The Federal Railway Authority (EBA) administers 14-18 month type-approval timelines for composite brake block certifications. Hamburg port congestion is redirecting volume onto rail-ferry connections that demand 40-foot platform flexibility.
Poland
Małaszewicze terminal expansion is creating demand for wagons configured to Russian and Chinese gauge interfaces. The Office of Rail Transport (UTK) adopts mutual recognition agreements to reduce duplicate testing for Czech-manufactured wagons. Silesian manufacturing corridors concentrate new-build orders from EU cohesion fund infrastructure projects.
Czech Republic
High-tensile steel plate rolling mills in Ostrava and Plzeň supply concentrated input capacity for heavy-haul deck construction. EN 15085 Class 1 welding certification requirements constrain production scaling at specialized bogie fabricators. The country's central positioning enables cross-border fleet deployment without national recertification under ERA interoperability standards.
Slovakia
Žilina-based component suppliers feed axle-load certification programs for 90-tonne gross weight configurations. REACH-compliant steel recycling frameworks extend wagon lifecycle value through certified refurbishment programs. The Košice industrial zone anchors maintenance hub operations for eastbound cargo flows.
Russia
Ural rail manufacturing clusters near the European border position production capacity for gauge-adaptable platform designs. The country's national rail safety regulator enforces braking performance standards that interface with ERA technical specifications. Kaliningrad corridor development is redirecting Baltic container volumes onto Russian rail networks.
40-Foot Platform Wagons Market Competitive Environment
Listed leaders compete with private specialists across leasing networks and manufacturing capacity. The vendor base clusters around three structural tiers: pan-European lessors with pooled fleet operations, integrated manufacturers with captive bogie engineering, and regional fabricators serving corridor-specific gauge requirements. Strategic moves concentrate on backward integration into steel plate supply and geographic expansion toward Polish-Russian border terminals.
Within the integrated manufacturing tier, Tatravagónka a.s. and UWC RPC PJSC exemplify specialized bogie design capabilities that reduce track wear and enable heavy-haul certifications. VTG GmbH occupies a position representing the pan-European lessor archetype, capturing fleet turnover demand through rolling three-year maintenance-included agreements that replace historical seven-year terms. These three companies anchor the competitive structure across central European corridors.
| Leading Market Players |
|---|
| AstraRail Industries S.A. |
| ELH Waggonbau Niesky GmbH |
| NYMWAG CS a.s. |
| RM RAIL |
| Tatravagónka a.s. |
| UWC RPC PJSC |
| VTG GmbH |
| Altaivagon Joint-Stock Company |
| TMH International |
| Others |
Value Chain & Pricing Dynamics
EBA type-approval timelines for composite brake blocks gate both supplier qualification and lease rate tiering simultaneously, compressing margins for uncertified fabricators while concentrating premium pricing power with ERA-compliant fleet operators.
Pricing Analysis
Volume-discount tiering structures separate heavy-haul certified operators from regional feeders across three performance levels. Pricing stratifies across premium, standard, and economy tiers based on axle-load certification grade and maintenance-included bundling. Cost compression in the economy tier is intensifying because uncertified Polish fabricators compete on spot delivery timelines. Automotive forwarders in the Rhine-Ruhr cluster exhibit the lowest price sensitivity, while agricultural seasonal users drive the hardest bargain on per-trip rates.
Supply Chain Analysis
Czech and Slovak rolling mill capacity for high-tensile steel plate creates a chokepoint that extends new-build delivery timelines for German and Polish fleet operators. Manufacturing draws from Ostrava steel inputs, Y25-derived bogie fabrications, and EN 15085 Class 1 welding labor pools. Single-source vulnerability concentrates in the Plzeň-Ostrava corridor where two mills supply 90-tonne deck construction. Distribution runs through VTG GmbH's pooled leasing network and direct manufacturer sales to project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ERA digital certification pathways are transforming this market toward platform-economics dynamics, where interoperability standards reward pooled fleet operators over asset owners.
For Market Incumbents: Fortify backward integration into Czech steel plate supply to secure input allocation during rolling mill bottlenecks. Deepen captive bogie engineering capabilities to accelerate EBA parallel-track certification timelines. Defensive consolidation should target Polish maintenance hub operators before Małaszewicze terminal expansion completes. For New Entrants and Emerging Players: Digital freight matching platforms represent the most penetrable service-layer gap where incumbents under-serve small forwarders. Target three-year maintenance-included lease structures for automotive sector buyers in the Rhine-Ruhr cluster. Go-to-market execution should anchor on GPS-telemetry retrofit bundles for 1990s-era wagon fleets lacking ERA TSI documentation. For Investors and Strategic Acquirers: EU Green Deal modal-shift mandates reshape the acquisition landscape toward lighter aluminum-frame specialists paired with battery-electric locomotive corridors. Long-term viability favors integrated manufacturers with captive EN 15085 welding certification rather than pure lessors. Signal to monitor: Polish UTK mutual recognition agreement expansion into Baltic states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Supply | Captive Ostrava mill capacity insulates German fleet operators from Slovak rolling bottlenecks. |
| Digital Certification Pathway Investment | ERA parallel-track approval compresses EBA timelines for proven bogie designs. |
| Maintenance Hub Network Expansion | Košice and Žilina refurbishment capacity captures circular economy mandate value. |
| Aluminum Frame Product Line Launch | Lightweight designs extend Deutsche Bahn Cargo electric range on Alpine routes. |
| Telematics Retrofit Service Development | GPS-axle sensor bundles unlock 1990s-era wagon pools for ERA TSI compliance. |
Study Parameters
Operator-level perspectives from fleet managers at VTG GmbH, procurement leads at Deutsche Bahn Cargo, maintenance directors at Tatravagónka a.s., and forwarding executives in the Rhine-Ruhr cluster anchored the qualitative base. Secondary validation drew from ERA technical specifications, EBA type-approval registries, UTK mutual recognition agreements, and EU Green Deal freight modal-shift policy documents. Bottom-up wagon deployment data triangulated against top-down corridor capacity assessments.
Sensitivity analysis tested forecast outputs against varying axle-load harmonization timelines and composite brake block adoption curves across the projection horizon. Segmentation modeling incorporated product type, material grade, end-user contract structure, and application certification tier. CAGRs derived from fleet replacement cycle acceleration rates and infrastructure investment lag functions specific to Małaszewicze terminal throughput expansion.
Forecasts assume regulatory continuity in EBA and UTK certification regimes; material policy shifts around ERA interoperability standards or REACH steel recycling mandates would require re-modeling. Practitioners should keep alternative scenarios live as EU Green Deal enforcement intensity and Polish corridor gauge adaptation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Locomotive Maintenance Market
Railway
Rail Glazing Market
Railway
South Korea Connected Rail Market
Railway
Freight Wagon Market
Railway
Rail Maintenance Management System Market
Railway
South Africa Rail Freight Transport Market
Railway
Rolling Stocks Market
Railway
Railway Buffer Stops Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Railway Horn Market
Railway
Railway Engine Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Gearbox for Rail Vehicles Market
Railway
Railroads Market
Railway
Tugger Trains Market
Railway
Railway Telematics Market