
 Railway Management System Market | 2026-2036
Railway Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Management System Market Analysis
Platform licensing revenue is reconfiguring profit pools away from perpetual hardware sales toward recurring software subscriptions. Siemens Mobility leverages its digital interlocking portfolio to capture long-term service contracts across European corridors. Alstom SA anchors its margin structure through integrated signaling and train control packages. Hitachi Rail specializes in AI-driven predictive maintenance modules that extend customer retention cycles.
A railway management system orchestrates train movement, infrastructure monitoring, and passenger information through centralized control platforms operating on sub-second response protocols and SIL-4 safety integrity levels. Its primary purpose is to maximize track utilization while preventing collisions and minimizing service disruptions. Traffic management solutions dominate current procurement budgets as congestion rises on saturated corridors. Cloud-based deployment architectures represent the fastest-expanding segment, though on-premises systems retain preference among operators with strict data sovereignty requirements. Edge computing nodes are emerging as a hybrid alternative for real-time decision-making in remote track sections.
The European Union Agency for Railways enforces ERTMS baseline specifications that shape cross-border interoperability mandates and equipment certification pathways. India's Ministry of Railways and the Dedicated Freight Corridor Corporation impose indigenous content requirements that condition market access for foreign suppliers. The Federal Railroad Administration in the United States maintains positive train control enforcement standards that sustain upgrade demand across Class I networks. Stakeholders must weigh modular upgrade paths against full-system replacements as signaling lifecycles converge with cybersecurity compliance deadlines.
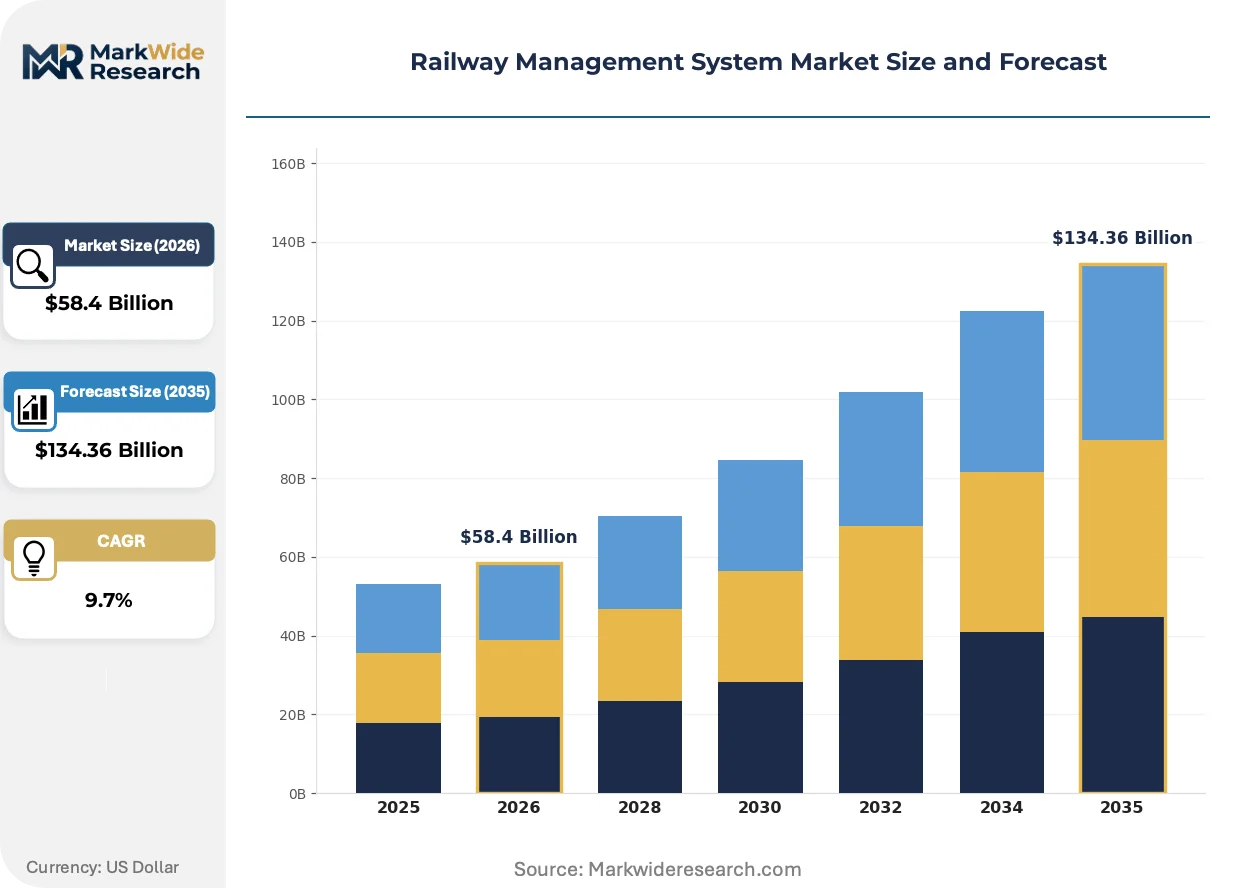
Market Dynamics
The EU's ERTMS mandate is forcing wholesale replacement of national legacy signaling networks, compressing procurement cycles and redistributing supplier influence toward platform-integrated vendors with certified interoperability stacks.
Growth Catalysts
- ERTMS Baseline 3 Mandate:The European Union Agency for Railways mandates baseline 3 specifications for cross-border corridors, compelling member states to accelerate digital signaling procurement and retire analog block systems.
- Dedicated Freight Corridor Expansion:India's Ministry of Railways and DFCCIL are deploying centralized traffic management systems across 2,800 route kilometers, creating sustained demand for train control hardware.
- AI-Driven Predictive Maintenance:Machine learning modules analyzing axle vibration and track geometry data are extending maintenance intervals and reducing unplanned service suspensions for freight operators.
Market Restraints
- Semiconductor Supply Concentration:Safety-critical SIL-4 processors rely on concentrated fabrication capacity in East Asia, exposing European and North American suppliers to extended lead times for certified components.
- Copper and Rare Earth Input Volatility:Traction power cabling and permanent magnet motors for hybrid locomotives face price instability from concentrated mining jurisdictions.
- Interoperability Certification Friction:The European Union Agency for Railways maintains strict no-objection certificate requirements that extend validation timelines for non-incumbent suppliers.
Strategic Opportunities
- Urban Metro Digitization in Southeast Asia:Bangkok, Jakarta, and Ho Chi Minh City are greenfielding metro networks without legacy infrastructure, enabling native digital signaling deployment.
- 5G-ERTMS Convergence:Integration of 5G radio block centers with existing ERTMS architectures promises reduced wayside equipment density and lower lifecycle maintenance burdens.
- US Positive Train Control Modernization:The Federal Railroad Administration's enforcement standards sustain upgrade demand across Class I networks seeking capacity expansion on saturated corridors.
Industry Challenges
- SIL-4 Software Engineering Talent Scarcity:Safety integrity level certification requires specialized embedded systems expertise that outpaces university pipeline output in Western Europe and North America.
- Cybersecurity Compliance Timeline Compression:The EU's NIS2 Directive and IEC 62443 standards impose concurrent security validation alongside functional safety certification, straining quality assurance bandwidth.
- Legacy Analog Integration Complexity:Brownfield corridors require protocol gateways translating between digital ERTMS and existing relay-based interlockings, multiplying commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Management System Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $134.36 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traffic Management, Asset Management, Communication Systems, Scheduling Software End User: Government Agencies, Private Operators, Freight Companies, Maintenance Providers Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Technology: IoT, AI, Big Data Analytics, GPS Tracking |
| Companies Covered | Siemens Mobility, Alstom SA, Hitachi Rail, Huawei Technologies Co., Ltd., ABB Ltd., Wabtec Corporation, Cisco Systems, Inc., IBM Corporation, Indra Sistemas, S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Management System Market Emerging Trajectories
Digital signaling architectures are fragmenting deployment models across cloud-native, edge-distributed, and on-premises configurations, with procurement criteria increasingly weighting cybersecurity posture and API extensibility alongside traditional availability metrics.
Digital interlocking systems are hybridizing centralized control logic with geographically distributed edge nodes that execute safety-critical decisions locally while maintaining supervisory oversight from regional control centers. Deutsche Bahn and SNCF Réseau are piloting these architectures on secondary lines to reduce wayside cabling costs. This topology is hybridizing the traditional separation between traffic management and infrastructure control, compressing vendor margins on standalone interlocking sales while expanding recurring software licensing opportunities.
The EU AI Act imposes risk classification requirements on automated train operation algorithms, compelling suppliers to document training data provenance and establish human oversight protocols for safety-critical AI components. Industrial consequence includes mandatory conformity assessments for predictive maintenance modules previously deployed without regulatory scrutiny. Freight corridors in Germany and Austria are most affected, with operators demanding pre-certified AI subsystems to avoid operational authorization delays.
Asset-as-a-service contracting is displacing capital-heavy signaling procurements, with operators preferring availability-based payments tied to train-path reliability metrics rather than upfront hardware acquisition. Infrastructure managers in the Netherlands and Switzerland are leading this transition, unbundling maintenance obligations from initial system delivery. This shift is most visible in urban metro renewals, where municipal budget constraints favor operational expenditure treatment over long-term debt financing of signaling assets.
Railway Management System Market Segmentation
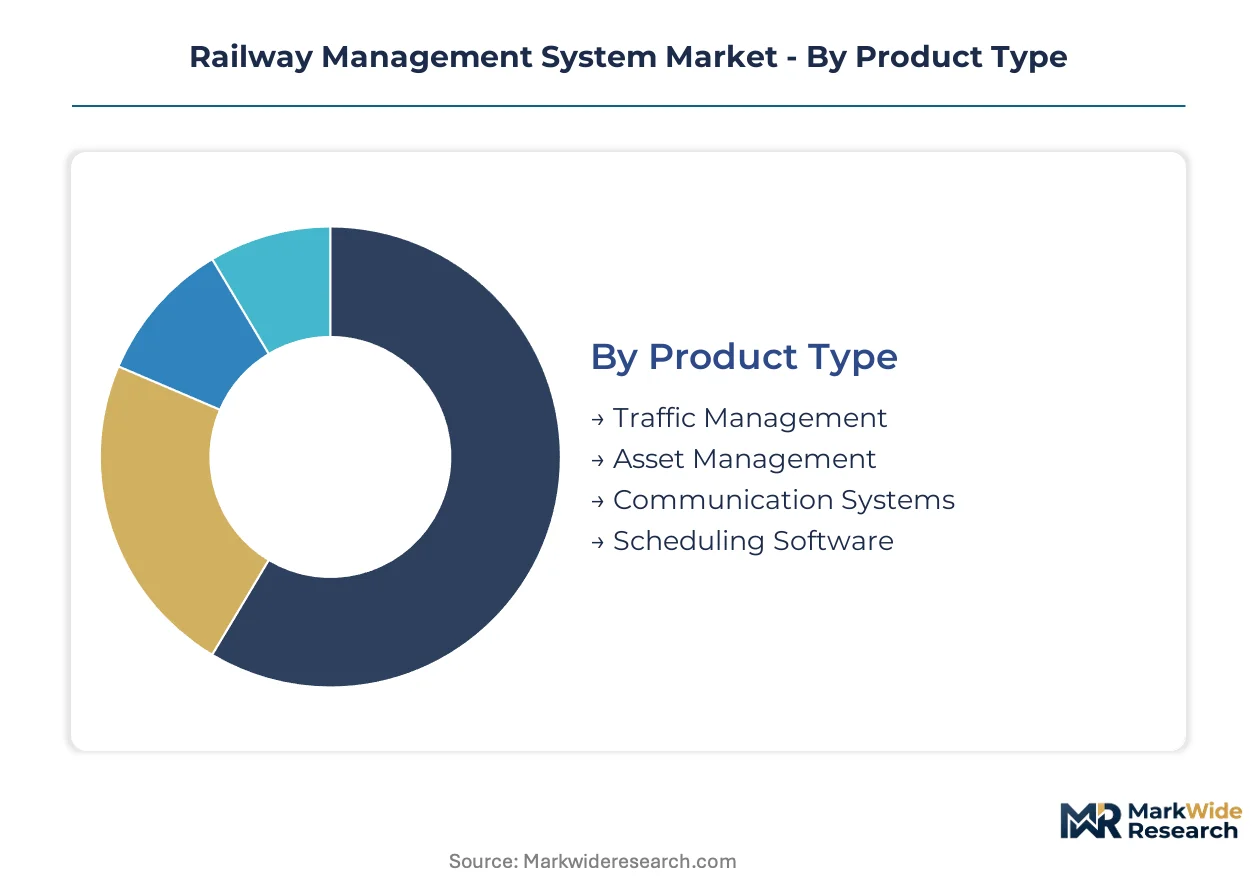
Railway management systems fragment across four intersecting dimensions that determine procurement cadence and vendor engagement models. Product type dictates replacement cycles spanning from annual software licenses to decade-long signaling infrastructure. Deployment architecture and technology maturity further stratify customer investment horizons and integration complexity.
Product Type:
Traffic management solutions turn over fastest as operators chase congestion relief, while asset management platforms embed for fifteen-year depreciation cycles.
- Traffic Management:Centralized control platforms orchestrate train movement through sub-second response protocols and SIL-4 safety integrity levels. India's Dedicated Freight Corridor projects and Germany's ERTMS corridor upgrades are concentrating procurement budgets here as saturation demands capacity expansion without track laying.
- Asset Management:Predictive maintenance modules analyze axle vibration and track geometry data to extend maintenance intervals. Deutsche Bahn and SNCF Réseau are deploying these systems across secondary lines where lifecycle cost reduction outweighs capital constraints.
- Communication Systems:Radio block centers and train-to-ground networks enable ERTMS Level 2 operation without trackside signaling.
- Scheduling Software:Crew rostering and path allocation algorithms optimize rolling stock utilization across irregular demand patterns.
Traffic Management dominates installed base. Asset Management is where expansion concentrates.
End User:
Procurement authority clusters differently across public infrastructure managers, commercial freight hauliers, and outsourced maintenance specialists.
- Government Agencies:National infrastructure managers like Germany's DB Netz and France's SNCF Réseau control track access and mandate interoperability standards. Their ERTMS procurement timelines compress supplier delivery schedules.
- Private Operators:Open-access freight and passenger companies in the UK, Sweden, and Italy purchase traffic management slots rather than infrastructure.
- Freight Companies:Class I railroads in the United States maintain positive train control systems under Federal Railroad Administration enforcement.
- Maintenance Providers:Specialized contractors deliver availability-based service contracts that unbundle maintenance from initial system delivery.
Government Agencies control infrastructure procurement. Private Operators are expanding fastest in open-access jurisdictions.
Deployment:
Architecture choice reflects data sovereignty tolerance versus latency sensitivity across control center and trackside environments.
- On-Premises:Regional control centers host safety-critical applications within operator-owned facilities. Strict data sovereignty requirements in Germany and France sustain preference despite higher capital intensity.
- Cloud-Based:SaaS delivery of non-safety applications enables municipal metro operators in Bangkok and Jakarta to circumvent long-term debt financing constraints.
- Hybrid:Safety-critical logic remains local while analytics and passenger information migrate to cloud instances.
- Edge Computing:Distributed nodes execute real-time decisions in remote track sections without continuous backhaul to control centers.
On-Premises retains safety-critical dominance. Cloud-Based deployment is climbing the fastest in greenfield metro networks.
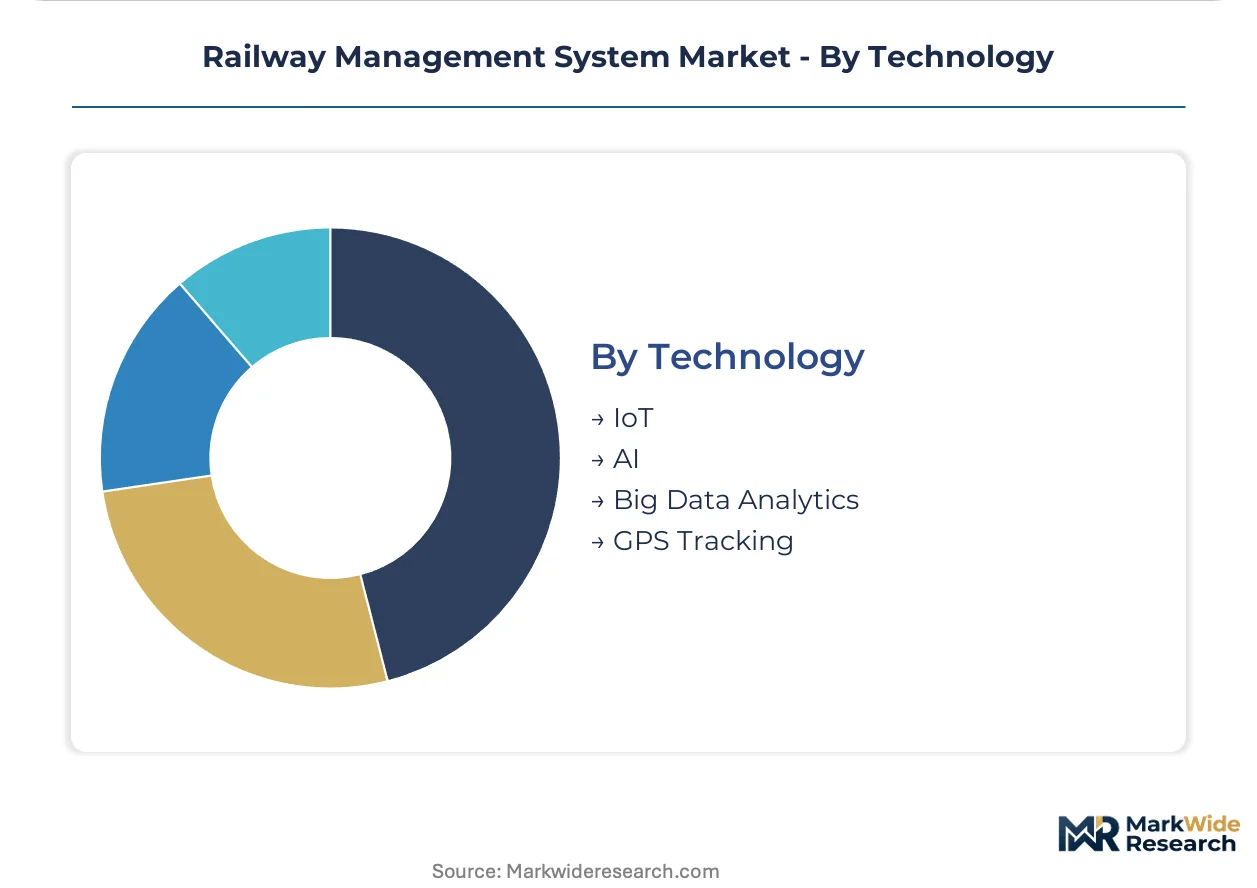
Technology:
Technology stack selection determines integration complexity with legacy relay-based interlockings and future 5G-ERTMS convergence pathways.
- IoT:Sensor networks monitor point machines, track circuits, and axle counters for condition-based maintenance triggering.
- AI:Machine learning modules for predictive maintenance face EU AI Act risk classification requirements that mandate training data provenance documentation.
- Big Data Analytics:Historical train performance datasets enable delay attribution and infrastructure bottleneck identification.
- GPS Tracking:Satellite positioning supplements balise-based train location in low-density rural corridors.
IoT sensors constitute the broadest installed base. AI modules are gaining share fastest where regulatory pre-certification accelerates deployment authorization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight operators in India demonstrate the highest price elasticity, squeezing margins on hardware procurement, while European infrastructure managers absorb premium pricing for certified interoperability stacks. Government budget cycles in Southeast Asia create volatile procurement cadences distinct from North American Class I railroads with steady capital allocation.
Germany
Deutsche Bahn's ERTMS corridor modernization and secondary line digitization pilot programs concentrate demand for hybrid edge-node architectures. The Federal Railway Authority enforces strict no-objection certificate requirements under EU baseline 3 mandates. Industrial activity clusters in the Rhine-Ruhr corridor where DB Netz coordinates cross-border interoperability testing with Dutch and Belgian infrastructure managers.
United States
Class I railroads sustain positive train control upgrade demand across Union Pacific and BNSF networks seeking capacity expansion without new track construction. The Federal Railroad Administration maintains enforcement standards that condition operational authorization on system certification. Deployment concentrates along the Chicago freight hub and Los Angeles-Long Beach port corridor where traffic density justifies modernization investment.
India
The Dedicated Freight Corridor Corporation deploys centralized traffic management systems across 2,800 route kilometers connecting Delhi-Mumbai and Delhi-Kolkata industrial belts. The Ministry of Railways imposes indigenous content requirements that condition market access for foreign signaling suppliers. Manufacturing and integration activity concentrates in Gujarat and Maharashtra where DFCCIL maintains procurement offices and testing facilities.
France
SNCF Réseau accelerates ERTMS Level 2 deployment on Atlantic and North Sea corridors ahead of EU interoperability deadlines. The French national safety authority applies EU AI Act risk classifications to automated train operation algorithms entering service. Technical validation centers in the Île-de-France region host certification testing for predictive maintenance modules destined for domestic and export deployment.
Indonesia
Jakarta's greenfield metro expansion and planned high-speed rail connectivity create demand for native digital signaling without legacy integration burdens. The national transportation regulator adapts international safety standards to tropical climate conditions and seismic resilience requirements. System integration activity concentrates in Greater Jakarta where PT Kereta Api Indonesia coordinates with Japanese and European technology partners on corridor development.
Railway Management System Market Vendor Landscape
Capability concentration sits with signaling specialists holding certified interoperability stacks; scale advantage sits with diversified industrial conglomerates with captive rail divisions. The vendor base stratifies across three tiers: platform-integrated European incumbents, Asian electronics conglomerates with communications expertise, and North American industrial automation specialists. Dominant competitive moves include strategic partnerships for 5G-ERTMS convergence development and geographic licensing agreements to satisfy indigenous content mandates.
Within the platform-integrated tier, Siemens Mobility and Alstom SA exemplify European vendors anchoring long-term service contract structures. Hitachi Rail occupies a position among Japanese industrial groups applying AI-driven maintenance expertise to extend customer retention cycles. Huawei Technologies Co., Ltd. represents Chinese telecommunications specialists targeting greenfield metro digitization in Southeast Asian markets.
| Leading Market Players |
|---|
| Siemens Mobility |
| Alstom SA |
| Hitachi Rail |
| Huawei Technologies Co., Ltd. |
| ABB Ltd. |
| Wabtec Corporation |
| Cisco Systems, Inc. |
| IBM Corporation |
| Indra Sistemas, S.A. |
| Others |
Supply Flow & Price Mechanics
East Asian semiconductor fabrication concentration for SIL-4 safety processors funnels pricing power toward certified component vendors while compressing margins for European system integrators dependent on just-in-time delivery schedules.
Pricing Analysis
Long-term service contracts and availability-based payments now generate the dominant share of lifetime customer value, displacing upfront hardware margins. Three-tier pricing structure across premium certified-interoperability, standard baseline-compliant, and economy non-critical tiers reflects ERTMS certification grade and geographic delivery scope. Cost compression in the economy tier intensifies because Indian freight operators and Southeast Asian metro agencies prioritize capital expenditure minimization over feature depth. Government infrastructure managers in Germany and France show lowest price sensitivity, absorbing premiums for EU Agency for Railways no-objection certificates.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for telecommunications equipment and edge computing nodes. Safety-critical processor fabrication concentrates in Taiwan, South Korea, and Japan, while copper cabling and rare earth permanent magnets draw from Chinese and Australian mining jurisdictions. Single-source vulnerability persists for radiation-hardened SIL-4 chipsets where foundry qualification cycles exceed five years. Distribution runs through systems integrators holding ERTMS baseline 3 certification rather than direct OEM-to-operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The railway management system market rewards vendors controlling scarce embedded systems engineering talent and certified interoperability stacks, with SIL-4 software expertise outpacing university pipeline output across Western Europe and North America.
For Market Incumbents: Build switching-cost moats through integrated signaling and maintenance service contracts that embed predictive analytics modules. Deepen backward integration into safety-critical processor sourcing to insulate against East Asian foundry lead time volatility. Acquire specialized AI maintenance startups before EU AI Act conformity assessment requirements harden competitive barriers.
For New Entrants and Emerging Players: Establish a beachhead in greenfield Southeast Asian metro digitization where legacy analog integration burdens are absent. Target Jakarta, Bangkok, and Ho Chi Minh City for native digital signaling deployment without protocol gateway development costs. Partner with local state-owned rail operators for indigenous content compliance rather than competing head-to-head with ERTMS-certified European incumbents.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed European signaling specialists facing succession planning and EU cybersecurity compliance investment cliffs. Long-term viability hinges on recurring software revenue share exceeding forty percent of total contract value. Monitor 5G-ERTMS convergence pilot announcements from Deutsche Bahn and SNCF Réseau as inflection indicators for radio block center obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| 5G-ERTMS Radio Block Center Integration | Deutsche Bahn pilot programs validate reduced wayside equipment density for lifecycle cost reduction. |
| AI Predictive Maintenance Module Certification | EU AI Act risk classification mandates training data provenance documentation for automated train operation algorithms. |
| Indigenous Content Partnership Structuring | India's Ministry of Railways local sourcing requirements condition market access for foreign signaling suppliers. |
| Edge Computing Node Deployment | SNCF Réseau secondary line pilots compress vendor margins on standalone interlocking sales. |
| Asset-as-a-Service Contract Transition | Dutch and Swiss infrastructure managers unbundle maintenance obligations from initial system delivery. |
Methodological Framework
A spread of perspectives from traffic control center operators, signaling procurement directors, embedded systems engineers, and EU Agency for Railways certification officials converged on the working assumptions. Primary interviews combined with secondary validation from ERTMS baseline specification documents, national rail infrastructure investment disclosures, and EU NIS2 Directive implementation guidance. Bottom-up project pipeline analysis triangulated against top-down infrastructure budget appropriations from India's Dedicated Freight Corridor Corporation and Deutsche Bahn capital expenditure filings.
Demand-supply balance framing anchored the analytical framework across the analysis window, modeling traffic management solution deployment against certified systems integrator capacity constraints. Segmentation dimensions included product type, deployment architecture, technology maturity, and end-user procurement authority. CAGRs derived from compound growth trajectory analysis of digital signaling procurement cycles and ERTMS mandate compliance timelines. Forecast inputs incorporated AI Act regulatory compliance cost burdens and 5G-ERTMS convergence adoption curves.
Sensitivities concentrate around semiconductor supply disruption, EU cybersecurity certification timeline extensions, and Indian indigenous content requirement enforcement intensity. Forecasts reflect assumptions about ERTMS baseline 3 deployment acceleration and Southeast Asian greenfield metro investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Global Train Control and Management Systems Market
Railway
Rail Brace Market
Railway
Railway Draft Gears Market
Railway
Global Smart Locomotive Market
Railway
Light Rail Market
Railway
Automatic Train Supervision Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
Rolling Stock Management Market
Railway
Railway Rolling Stock Market
Railway
Railway Bearing Market
Railway
Railway Pantograph Market
Railway
Global Hyperloop Train Market
Railway
Hydrogen Trains Market
Railway
Rail Brake Frame Market
Railway
Maglev Train Market
Railway
Railway Automated Inspection Equipment Market