
 South Africa Rail Freight Transport Market | 2026-2036
South Africa Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Rail Freight Transport Market Insights
Freight corridors linking the Port of Durban to inland industrial hubs is reconfiguring cargo flows across Southern Africa. Transnet Freight Rail dominates the core network infrastructure and controls the Richards Bay and Maputo corridor gateways. Imperial Logistics leverages integrated warehousing and rail-road coordination to serve mining and retail clients. Traxtion specializes in private locomotive leasing and maintenance, competing on operational flexibility where Transnet's capacity constraints create openings.
South Africa rail freight transport encompasses the movement of bulk commodities and containerized goods over dedicated heavy-haul and general freight networks using diesel-electric and electric locomotives with axle loads up to 26 tonnes on the coal export lines. Bulk cargo movements, particularly coal and manganese, anchor revenue volumes through long-term offtake contracts with mining houses. Container freight and intermodal transport represent faster-growing service categories as retailers and logistics providers seek alternatives to road congestion on the N3 corridor. Cross-border transport modes gain structural importance through the Maputo Corridor and North-South Corridor linking to Zimbabwe and Zambia.
The National Railway Safety Regulator enforces operational safety standards while the Department of Transport oversees infrastructure licensing under the National Land Transport Act. Transnet's Market Demand Strategy and the government's Rail Policy White Paper shape private sector participation frameworks and investment priorities. Stakeholders must monitor regulatory clarity on third-party track access and the pace of locomotive fleet renewal to assess competitive entry timelines.
Market Dynamics
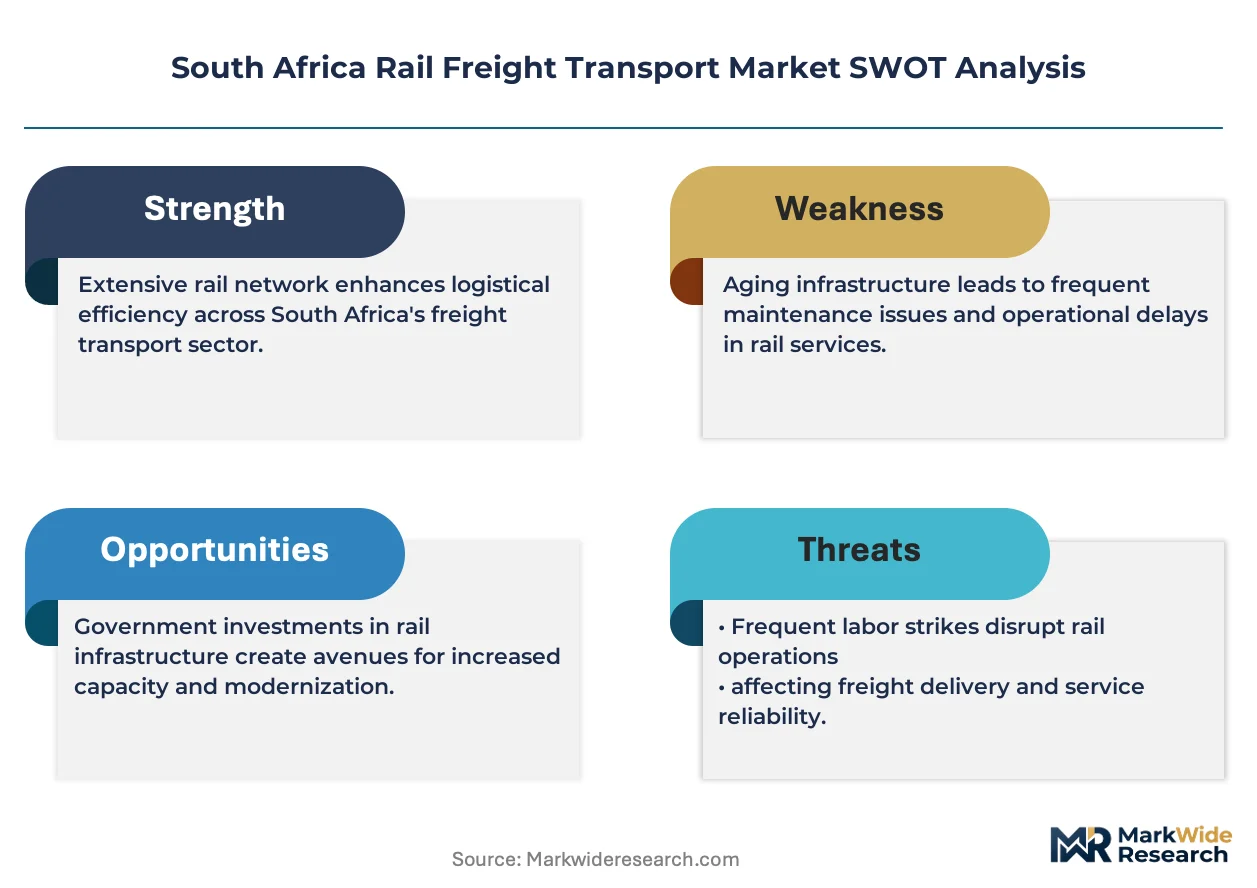
Transnet's Market Demand Strategy and third-party access frameworks are restructuring competitive entry conditions across South Africa's rail freight network. Mining houses on the Richards Bay Coal Line are pressing for capacity expansion while private operators seek operational slots on congested corridors.
Growth Catalysts
- Rail Policy White Paper:The Department of Transport's private sector participation framework is opening track access for independent locomotive operators and intermodal providers.
- Mining offtake contracts:Bulk commodity exporters on the coal and manganese lines are committing to long-term volume guarantees that justify infrastructure recapitalization.
- Durban-Johannesburg corridor congestion:Road freight bottlenecks on the N3 highway are pushing containerized cargo toward rail intermodal alternatives.
Market Restraints
- Diesel price volatility:Fuel input costs swing with rand-dollar exchange rates and international oil markets, compressing margins on non-electrified branch lines.
- Transnet network concentration:Single-operator control of core trunk routes limits competitive pricing and service differentiation for captive shippers.
- Limited cross-border gauge compatibility:Technical misalignment with neighboring rail networks restricts seamless freight movement into Zimbabwe and Zambia.
Strategic Opportunities
- Maputo Corridor expansion:The North-South rail link through Mpumalanga offers alternative port access for Gauteng industrial clusters seeking route diversification.
- Containerized agricultural exports:Citrus and deciduous fruit growers in the Western Cape are exploring refrigerated rail solutions to bypass Cape Town road congestion.
- Green hydrogen logistics:Emerging renewable energy clusters in the Northern Cape will require dedicated bulk transport for ammonia and hydrogen derivatives.
Industry Challenges
- Locomotive engineer shortages:Transnet and private operators compete for scarce certified drivers and maintenance technicians across the heavy-haul network.
- Legacy signaling integration:New positive train control systems must interface with decades-old track circuits and manual interlocking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Rail Freight Transport Market |
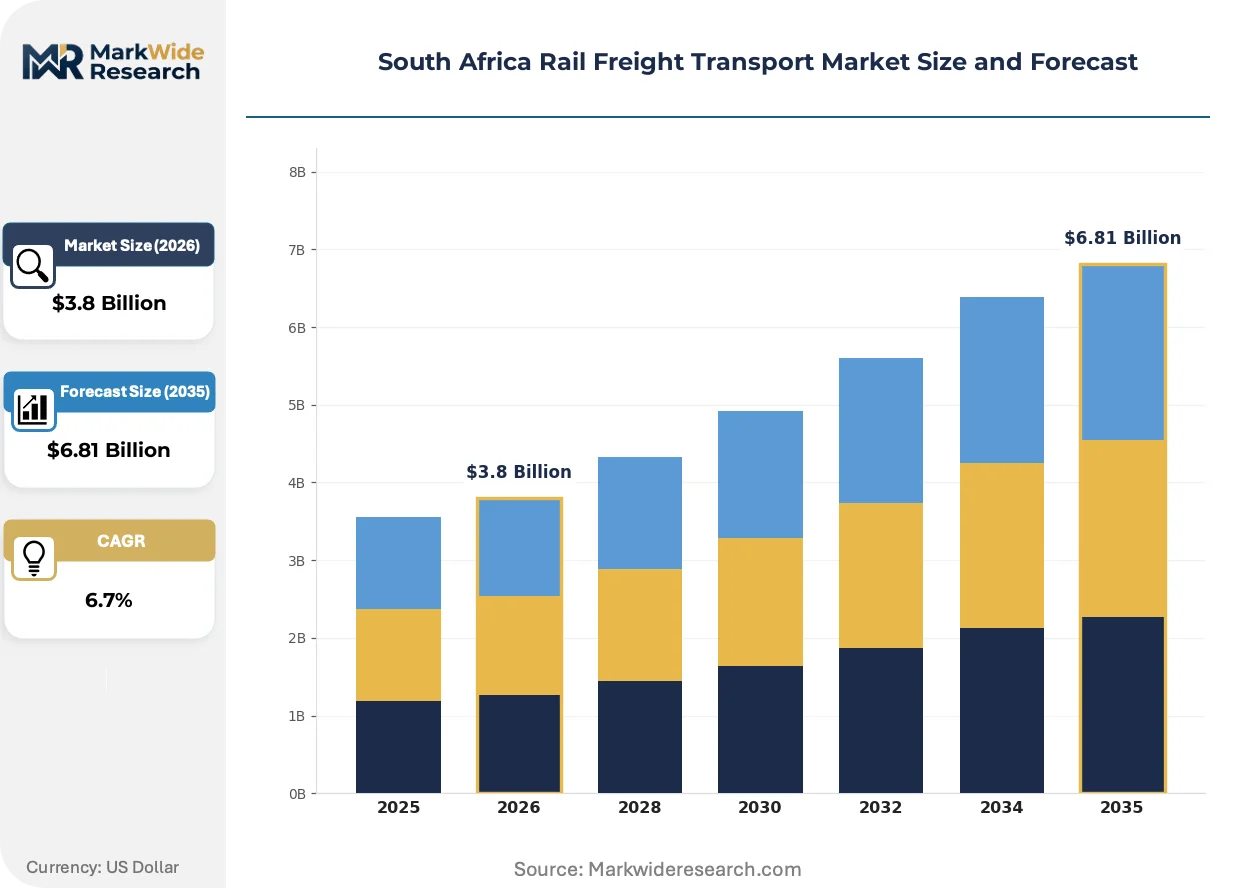
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Container Freight, Bulk Cargo, Intermodal Transport, Heavy Haul Cargo Type: Coal, Chemicals, Agriculture, Consumer Goods End User: Mining Sector, Agriculture Sector, Retailers, Logistics Providers Transportation Mode: Long-Distance Transport, Short-Distance Transport, Cross-Border Transport, Urban Transport |
| Companies Covered | Imperial Logistics, DSV, Transnet Freight Rail, DB Schenker, Kuehne+Nagel, Traxtion, DHL Group, Wabtec, DP World, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Rail Freight Transport Market Trends and Innovations
Digitization and alternative propulsion systems are reshaping operational models across South Africa's heavy-haul corridors. These shifts are altering capital deployment patterns and competitive positioning among freight operators.
Diesel-electric locomotives with battery assist modules are hybridizing power delivery on non-electrified branch lines serving manganese mines in the Northern Cape. Mining houses are piloting these dual-mode units to reduce fuel consumption on steep gradient sections. The technology is compressing operating cost differentials between electrified and unelectrified routes.
The National Railway Safety Regulator is tightening operational safety standards under revised heavy-haul certification requirements. Mining exporters must now demonstrate enhanced braking system compliance for 26-tonne axle load operations. The Richards Bay Coal Line operators are retrofitting wagon fleets to meet these mandates ahead of enforcement deadlines.
Shippers on the Durban-Johannesburg corridor are consolidating freight procurement through integrated logistics providers rather than contracting directly with rail operators. Retail and automotive manufacturers are bundling warehousing, road feeder services, and mainline rail under single-service agreements. This concentration is most pronounced among Gauteng-based fast-moving consumer goods distributors seeking end-to-end visibility.
South Africa Rail Freight Transport Market Segmentation
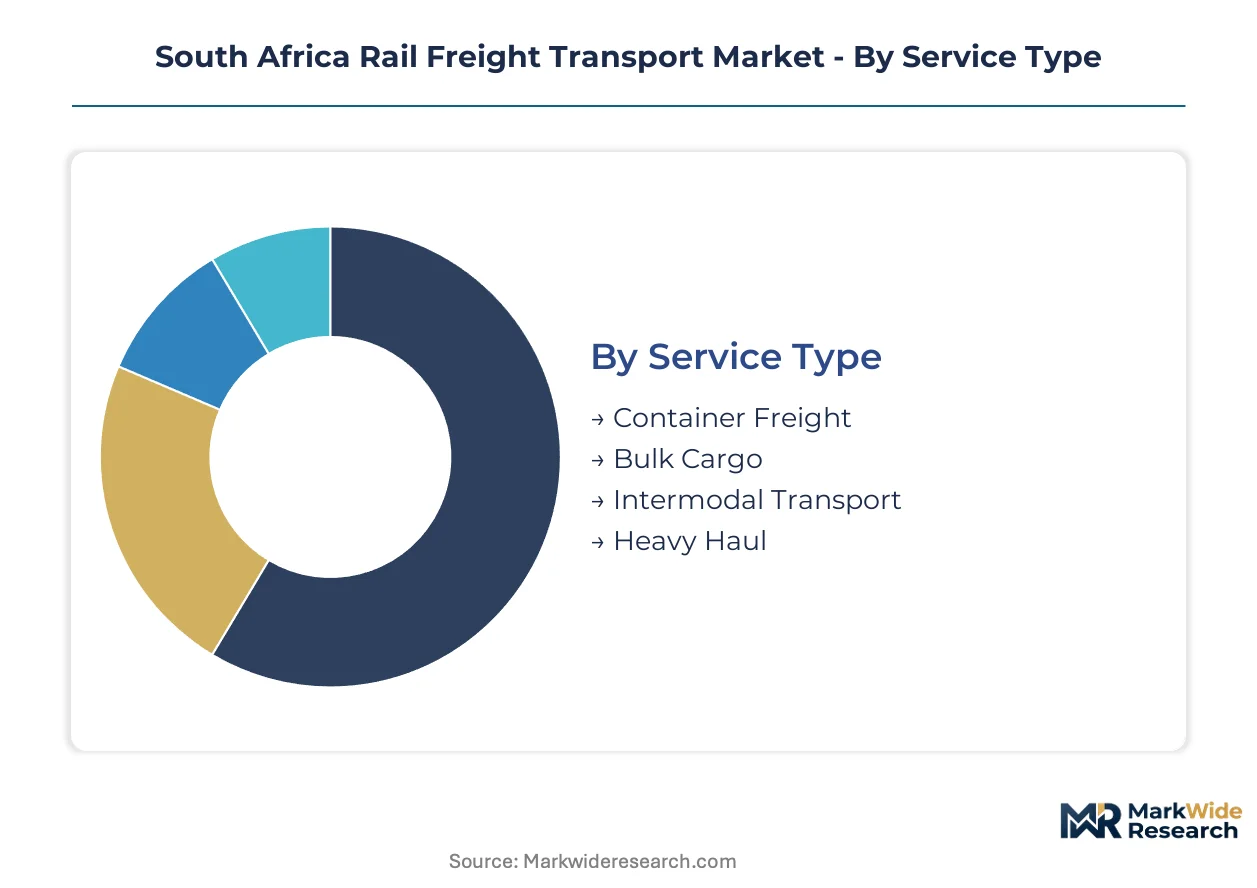
Segmentation in South African rail freight reveals how service specialization, cargo characteristics, and customer requirements shape infrastructure investment priorities. Distinct operational models serve bulk commodity exporters versus containerized supply chains, with each segment demanding different locomotive configurations, terminal equipment, and corridor access rights.
Service Type:
After-sales intensity varies sharply across service categories, with heavy-haul coal operations requiring intensive maintenance partnerships while container services demand real-time tracking support.
- Container Freight:Standardized intermodal units moving manufactured goods and retail merchandise through Durban-Johannesburg corridors. Gauteng-based automotive and fast-moving consumer goods distributors are consolidating procurement under integrated logistics contracts that bundle warehousing with mainline rail slots.
- Bulk Cargo:Dedicated unit trains hauling unpackaged commodities like coal, iron ore, and manganese under long-term offtake agreements. Mining houses on the Richards Bay Coal Line anchor revenue through volume guarantees that justify 26-tonne axle load infrastructure recapitalization.
- Intermodal Transport:Coordinated road-rail solutions combining truck feeder services with long-haul rail segments. Retailers seeking N3 highway alternatives are driving adoption across the Durban-Johannesburg corridor.
- Heavy Haul:Ultra-high-capacity operations on dedicated mineral export lines using electric locomotive fleets. The National Railway Safety Regulator's enhanced braking compliance mandates are forcing fleet retrofits ahead of enforcement deadlines.
By volume, Bulk Cargo leads. By growth pace, Container Freight is ahead.
Cargo Type:
Cost tier differentiation separates high-value temperature-controlled agricultural shipments from low-margin bulk mineral movements.
- Coal:Thermal and metallurgical grades dominate export volumes through Richards Bay terminals. Eskom's domestic supply requirements and Asian export demand create dual-market pricing dynamics.
- Chemicals:Hazardous and non-hazardous industrial inputs requiring specialized wagon fleets with containment systems. Sasol and industrial chemical producers in Mpumalanga and KwaZulu-Natal generate consistent corridor demand.
- Agriculture:Grains, citrus, and deciduous fruit moving from Western Cape and Free State production zones. Refrigerated rail solutions are expanding as Cape Town road congestion worsens.
- Consumer Goods:Packaged retail merchandise and automotive components in containerized formats. E-commerce fulfillment networks are pulling inventory positioning closer to Gauteng distribution centers.
Coal generates the highest absolute tonnage. Consumer Goods is climbing the fastest as retail supply chains diversify from pure road dependency.
End User:
Customer type determines contract structure, with mining houses negotiating decade-long commitments while retailers demand seasonal flexibility.
- Mining Sector:Coal, manganese, and iron ore producers securing dedicated capacity through Transnet's Market Demand Strategy framework. Private operators like Traxtion are leasing locomotives to supplement Transnet Freight Rail capacity during peak export windows.
- Agriculture Sector:Grain cooperatives and fruit exporters seeking harvest-season surge capacity. Western Cape citrus growers are piloting dedicated refrigerated block trains to Port Elizabeth terminals.
- Retailers:Mass merchandisers and grocery chains requiring predictable inbound supply schedules. Shoprite and Woolworths distribution centers in Gauteng are anchoring intermodal terminal investments.
- Logistics Providers:Third-party operators like Imperial Logistics bundling multimodal services under single-contract arrangements. These intermediaries are capturing procurement decisions from direct rail contracting.
Mining Sector commitments anchor infrastructure financing. Logistics Providers are gaining share fastest as shippers outsource coordination complexity.
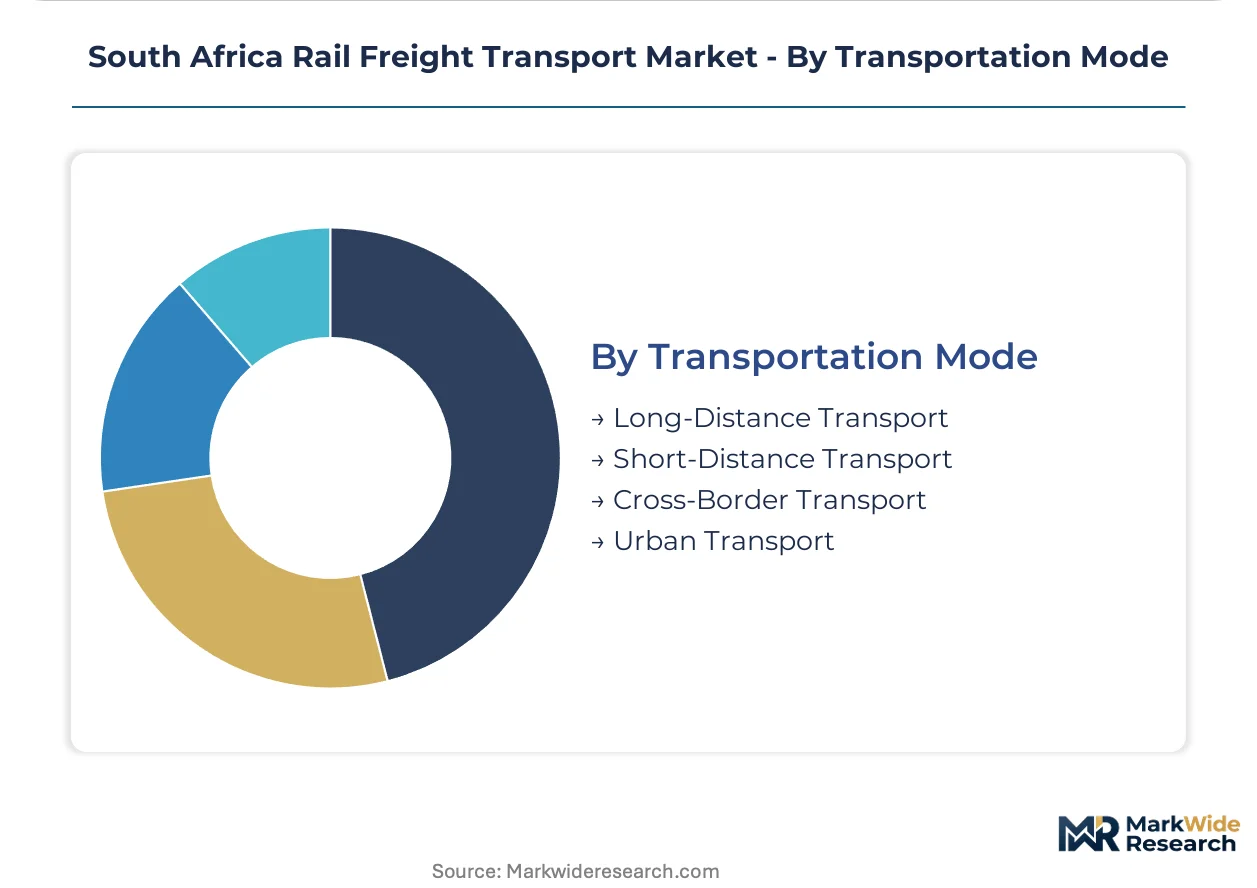
Transportation Mode:
Geographic scope shapes equipment utilization rates, with cross-border movements suffering from gauge incompatibility delays.
- Long-Distance Transport:Corridor movements exceeding 500 kilometers connecting inland production to coastal ports. The Durban-Johannesburg route handles the densest general freight flows.
- Short-Distance Transport:Regional shuttle services linking mines to processing facilities or intermodal terminals. Northern Cape manganese operations rely on these feeder movements to mainline junctions.
- Cross-Border Transport:International movements through the Maputo Corridor and North-South Corridor into Zimbabwe and Zambia. Technical misalignment with neighboring networks forces transshipment at border points.
- Urban Transport:Last-mile distribution within metropolitan freight rings, primarily serving construction materials and fuel. Gauteng urban nodes face road-rail interface congestion at terminal approaches.
Long-Distance Transport dominates tonnage. Cross-Border Transport is expanding most quickly as Maputo Corridor alternatives attract Gauteng industrial shippers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Richards Bay Coal Line commands premium freight rates that Gauteng industrial shippers cannot replicate on the Durban-Johannesburg corridor. This pricing-power asymmetry shapes infrastructure investment flows across South Africa's rail network.
Gauteng Province
Automotive manufacturers and fast-moving consumer goods distributors cluster around Johannesburg and Pretoria, generating dense container flows toward Durban port. The Department of Transport's Rail Policy White Paper is opening third-party track access for private locomotive operators. Shoprite and Woolworths distribution centers in Johannesburg are anchoring intermodal terminal investments to bypass N3 highway congestion.
KwaZulu-Natal
The Port of Durban handles the densest general freight volumes, with Richards Bay anchoring bulk coal and mineral exports. Transnet's Market Demand Strategy is recapitalizing the coal line infrastructure to meet mining house volume guarantees. The Durban-Johannesburg corridor faces acute capacity constraints as retailers shift cargo from road to rail alternatives.
Mpumalanga
Coal mining operations feed the Richards Bay export line through dense heavy-haul movements. The National Railway Safety Regulator is enforcing enhanced braking compliance mandates for 26-tonne axle load operations. Mining houses in the Witbank coalfield are retrofitting wagon fleets ahead of enforcement deadlines.
Northern Cape
Manganese producers in the Hotazel and Sishen districts rely on diesel-electric locomotives with battery assist modules for steep gradient sections. Emerging renewable energy clusters will require dedicated bulk transport for green hydrogen derivatives. Regional shuttle services link mines to mainline junctions serving the Port of Saldanha.
Western Cape
Citrus and deciduous fruit growers in the Ceres and Grabouw valleys are piloting refrigerated rail solutions. Cape Town road congestion is pushing agricultural exporters toward dedicated block trains to Port Elizabeth terminals. The provincial government is supporting cold-chain infrastructure investments at rail terminals.
South Africa Rail Freight Transport Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on equipment and maintenance. Transnet Freight Rail dominates core trunk infrastructure through single-operator control of the Richards Bay and Maputo corridor gateways. Private logistics providers compete on operational flexibility where capacity constraints create openings. Strategic moves concentrate on intermodal service bundling and third-party track access negotiations under evolving regulatory frameworks.
Among integrated logistics providers, Imperial Logistics and DSV exemplify the bundling archetype that combines warehousing, road feeder services, and mainline rail coordination. Traxtion occupies a position within the private locomotive leasing tier, competing on operational flexibility. Transnet Freight Rail anchors the infrastructure-control archetype through its Market Demand Strategy framework. These three represent distinct competitive positions: full-service integration, specialized equipment provision, and network infrastructure ownership.
| Leading Market Players |
|---|
| Imperial Logistics |
| DSV |
| Transnet Freight Rail |
| DB Schenker |
| Kuehne+Nagel |
| Traxtion |
| DHL Group |
| Wabtec |
| DP World |
| Others |
Pricing and Supply Chain Analysis
Undercapacity on the Richards Bay Coal Line is driving mining houses to pay premium rates for guaranteed slot access while Transnet negotiates long-term offtake contracts that lock in volume commitments. This utilization squeeze cascades into the Durban-Johannesburg corridor, where container shippers face rationed capacity and escalating intermodal premiums.
Pricing Analysis
The customization-premium spread separates heavy-haul unit-train contracts from standard container slot pricing. Contract-based long-term offtake agreements dominate bulk mineral movements, with mining houses securing dedicated capacity through volume guarantees that justify 26-tonne axle load infrastructure investment. Price differentiation hinges on corridor congestion severity and locomotive availability windows, with Richards Bay Coal Line slots commanding substantial premiums over Maputo Corridor alternatives. Pricing pressure stems from diesel-electric hybrid fleet conversion costs on non-electrified Northern Cape branch lines. Mining exporters show the least price sensitivity due to captive port access requirements, while agricultural shippers in the Western Cape exhibit acute sensitivity to refrigerated block-train tariffs.
Supply Chain Analysis
Upstream feedstock for rail freight operations draws from Chinese and German locomotive manufacturing clusters, South African manganese and coal extraction zones, and Australian iron ore supply basins. Critical inputs include diesel-electric traction systems, 26-tonne axle load wagon chassis, and high-grade steel for track infrastructure. Single-source vulnerability concentrates in Transnet Freight Rail's monopoly control of core trunk routes and Richards Bay terminal access. Distribution runs through integrated logistics providers like Imperial Logistics and DSV that bundle warehousing, road feeder services, and mainline rail coordination under single-contract arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where third-party track access frameworks under the Rail Policy White Paper are fragmenting Transnet's infrastructure control and enabling interoperable private locomotive operations.
For Market Incumbents: Build switching-cost moats by embedding maintenance partnerships and real-time tracking capabilities into long-term mining offtake contracts. Deepen backward integration into captive wagon fleets and terminal equipment to defend against Traxtion's operational flexibility positioning. Prioritize certification investment for enhanced braking compliance ahead of National Railway Safety Regulator enforcement deadlines.
For New Entrants and Emerging Players: Build out refrigerated rail capabilities serving Western Cape citrus and deciduous fruit exporters as the most penetrable segment where road congestion creates modal-switch urgency. Target cross-border Maputo Corridor operations where gauge compatibility investments unlock Gauteng industrial shipper demand. Pursue go-to-market angles bundling last-mile road distribution with mainline rail slots through partnerships with Gauteng-based retail distribution centers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across private locomotive leasing as battery-assist hybrid technology reduces fuel cost exposure and improves asset utilization rates. Acquisition targets should display integrated logistics bundling capabilities and established relationships with mining houses or retail distributors. Watch for regulatory clarity on third-party track access pricing as the signal indicating competitive entry timeline acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Third-Party Track Access Negotiation | Private operators like Traxtion gain operational slots where Transnet capacity constraints create openings. |
| Hybrid Locomotive Fleet Conversion | Battery-assist diesel-electric units reduce fuel costs on Northern Cape manganese branch lines. |
| Refrigerated Block-Train Deployment | Western Cape citrus growers bypass Cape Town road congestion through dedicated cold-chain rail. |
| Intermodal Terminal Investment | Shoprite and Woolworths distribution centers anchor Gauteng infrastructure to capture N3 diversion. |
| Cross-Border Gauge Harmonization | Maputo Corridor expansion attracts Gauteng shippers seeking alternative port access diversification. |
Research Methodology
Desk research of Transnet annual reports, Department of Transport policy white papers, and National Railway Safety Regulator filings preceded structured interviews with Transnet Freight Rail operations executives, private locomotive leasing managers, mining house logistics directors, and integrated logistics provider procurement leads. Secondary validation drew from customs trade data, Eskom electricity supply agreements, and Richards Bay Coal Line throughput disclosures. Bottom-up volume modeling triangulated against top-down infrastructure capacity assessments.
Assumption sets held fixed Transnet's Market Demand Strategy implementation pace and Rail Policy White Paper regulatory clarity timelines while varying mining export demand intensity and road-rail modal shift elasticity. Segmentation dimensions modeled included service type, cargo category, end-user sector, and transportation mode across the analysis window. CAGRs derived from corridor-specific volume trajectories and infrastructure investment schedules, with green hydrogen logistics demand and containerized agricultural export growth as key industry-specific inputs.
Stress conditions across diesel price volatility, rand-dollar exchange rate swings, and locomotive engineer availability shortages were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory enforcement timing and cross-border gauge standardization progress. Cross-checking against Transnet Freight Rail published capacity utilization metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Global High-Speed Train Seat Market
Railway
Railway Buffer Stops Market
Railway
Europe Intermodal Terminals Market
Railway
Railway Horn Market
Railway
Hydrogen Trains Market
Railway
Railroad Tie Market
Railway
Automatic Train Control Market
Railway
Rolling Stocks Market
Railway
Automatic Train Supervision Market
Railway
Rail Damper Market
Railway
Sanitary Systems for Rail Transit Market
Railway
Gearbox for Rail Vehicles Market
Railway
Railroad Brake Shoe Market
Railway
Road-Rail Vehicles Market
Railway
Locomotive Maintenance Market
Railway
Railcar Vehicle Toilet Market