
 Check Rails Market | 2026-2036
Check Rails Market Size, Share, and Industry Trends Forecast 2026-2036
Check Rails Market Outlook
Digital twin integration in rail system engineering is reconfiguring how check rail manufacturers prototype, validate, and deliver precision-guided motion infrastructure. ArcelorMittal leverages captive steel supply and metallurgical R&D to dominate specification-grade rail production for heavy-duty industrial applications. CRRC Corporation Limited anchors large-scale manufacturing capacity and competes aggressively on cost-adjusted performance in conveying system deployments across Asia.
Check rails are rigid linear or curved guidance elements, typically manufactured from hardened steel or extruded aluminum with tolerances measured in hundredths of a millimeter, designed to constrain, position, or redirect moving components along predetermined paths in automated machinery. Linear check rails sustain the largest installed base across mature industrial economies where retrofit cycles and maintenance replacement generate predictable revenue, while magnetic check rails represent the fastest-growing category as servo-driven pick-and-place systems demand contactless positioning with reduced particulate generation. Heavy duty check rails concentrate margin pools in steel mill, port logistics, and automotive press shop applications where load-bearing capacity and fatigue resistance command specification premiums.
The EU Machinery Directive and ISO 12100 machinery safety standards mandate hazard analysis and protective measures for linear motion systems, compelling manufacturers to certify deflection limits and emergency stop compatibility before CE-marked market access. Germany's KBA-influenced industrial safety protocols and Japan's METI-guided factory automation standards further fragment compliance requirements, forcing suppliers to maintain parallel certification tracks. Stakeholders must monitor convergence between functional safety standards and predictive maintenance data architectures as buyers increasingly specify check rails with embedded sensor readiness for Industry 4.0 integration.
Market Dynamics
Digital twin integration in rail system engineering is reconfiguring how check rail manufacturers prototype, validate, and deliver precision-guided motion infrastructure. The convergence of virtual commissioning with ISO 12100 safety compliance is compressing design-to-deployment cycles while elevating specification thresholds for linear motion components.
Growth Catalysts
- EU Machinery Directive:CE-marking requirements for linear motion systems mandate certified deflection limits and emergency stop compatibility, forcing specification-grade upgrades across automated machinery deployments in Germany and France.
- Automotive press shops:Servo-driven pick-and-place systems in stamping and welding lines demand magnetic check rails with contactless positioning and reduced particulate generation for cleanroom-adjacent operations.
- Steel metallurgy advances:Hardened alloy formulations with fatigue resistance exceeding 10 million cycles are extending replacement intervals in port logistics and heavy material handling installations.
Market Restraints
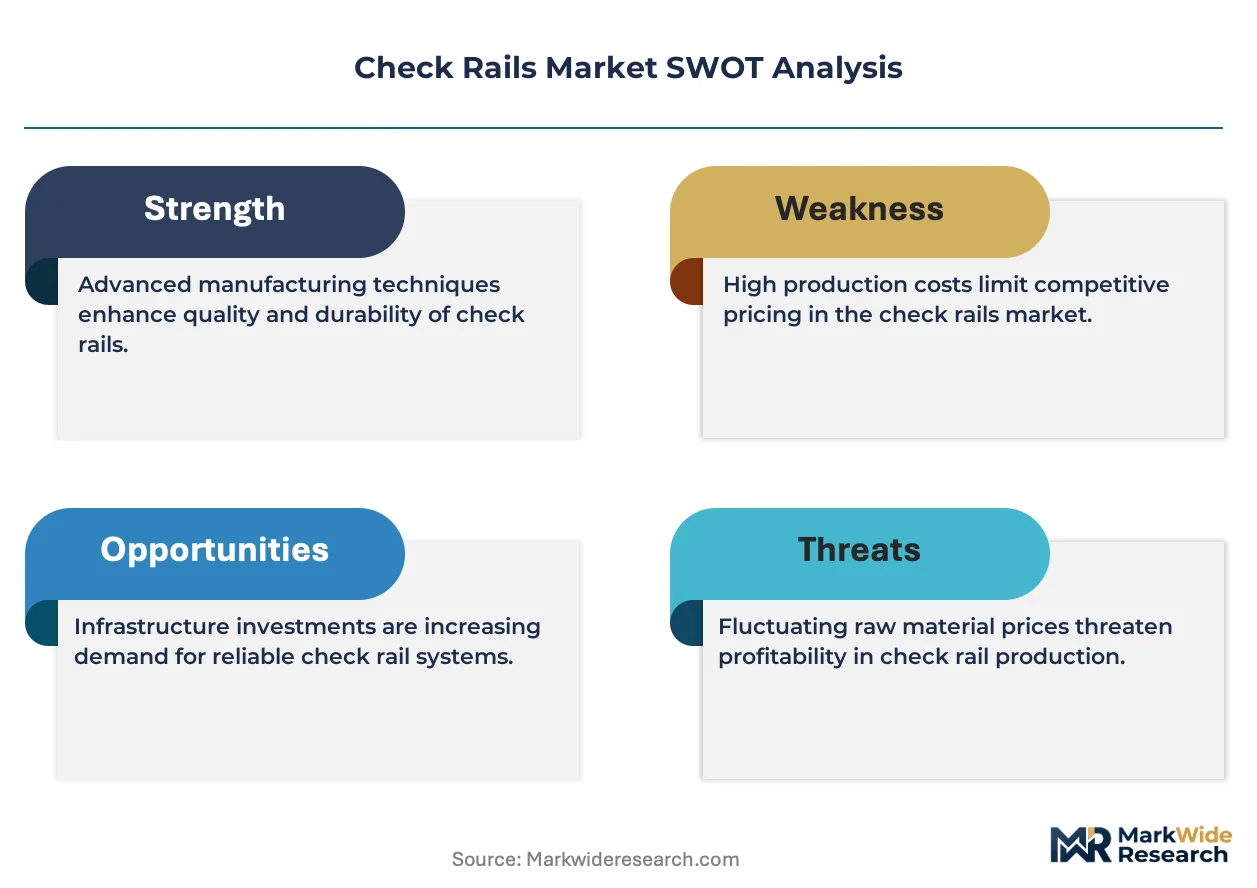
- Aluminum extrusion cost volatility:Energy-intensive smelting operations concentrate input price risk with European and Gulf state suppliers, compressing margins on standard-grade linear rail systems.
- Specification-grade steel concentration:Premium rail alloy production clusters with integrated steelmakers in Germany and Japan, creating supply bottlenecks for tier-two machinery builders without captive metallurgical partnerships.
- Polymer composite substitution:Carbon-fiber reinforced guidance elements penetrate light-load conveying applications below 500 kg, eroding addressable volume in packaging and electronics assembly.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced manufacturing equipment create localized demand for precision linear motion infrastructure in automotive and electronics clusters near Pune and Chennai.
- Embedded sensor readiness:Check rails with pre-integrated strain gauge and temperature monitoring architectures capture specification premiums from Industry 4.0 retrofit programs in Japanese and German automotive OEM supply chains.
- CE-MDR convergence:Aligning machinery safety certification with medical device regulation streamlines market access for laboratory automation and pharmaceutical handling equipment requiring dual compliance.
Industry Challenges
- Functional safety engineering talent:ISO 13849-1 compliance for safety-related control systems requires specialized expertise scarce outside German and Japanese industrial automation clusters, extending certification timelines.
- Legacy system integration:Retrofitting digital twin-ready check rails into existing PLC architectures demands custom mechanical adapters and protocol gateways, inflating project engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Check Rails Market |
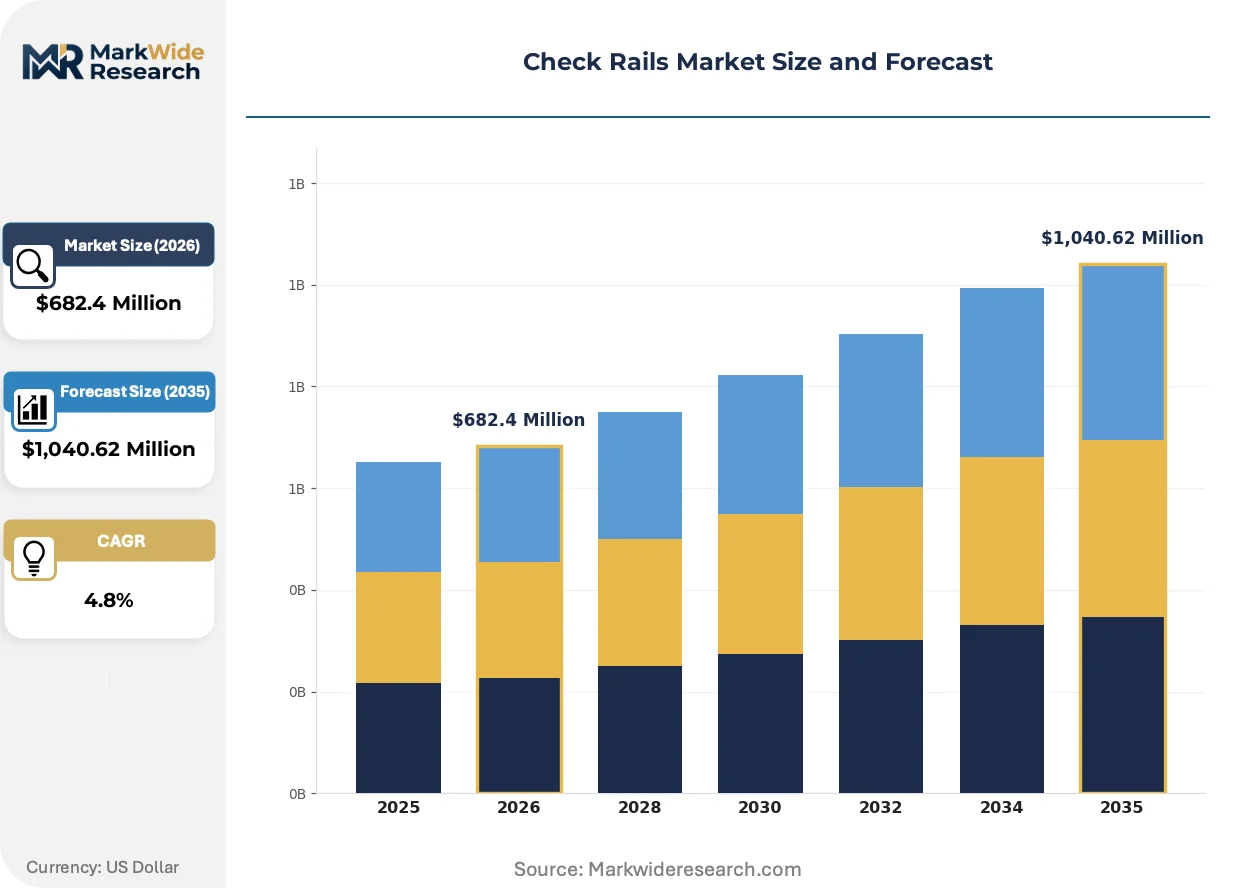
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,040.62 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Check Rails, Curved Check Rails, Heavy Duty Check Rails, Magnetic Check Rails Installation Method: Surface Mount, Embedded, Wall-Mounted, Ceiling-Mounted Material: Aluminum, Steel, Plastic, Composite Application: Industrial Automation, Robotics, Conveying Systems, Packaging Equipment |
| Companies Covered | Progress Rail, Patil Group, Moxon Industries, Kimes Steel & Rail, Vossloh AG, ArcelorMittal, Voestalpine Schienen GmbH, Alstom SA, CRRC Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Check Rails Market Strategic Shifts
Active magnetic levitation guidance is displacing conventional contact-based positioning in precision-critical automation cells. Three technology and demand trajectories are restructuring competitive positioning and procurement patterns across the specification-grade rail segment.
Magnetic check rails utilizing permanent magnet arrays with servo-controlled air gaps are rendering obsolete mechanical recirculating ball guides in semiconductor wafer handling and pharmaceutical cleanroom applications. Electronics OEMs in South Korea and Taiwan specify contactless architectures to eliminate lubricant particulate contamination. The technology is compressing maintenance intervals from quarterly to annual cycles while commanding 40-60% specification premiums over hardened steel equivalents.
Japan's METI-guided Factory Automation Standards Initiative mandates predictive maintenance data architectures for capital equipment depreciation incentives. Machinery builders must demonstrate sensor-ready linear motion components to qualify for accelerated tax treatment. German automotive OEMs are responding by specifying check rails with standardized IO-Link interfaces for condition monitoring, forcing suppliers to maintain parallel certification tracks across METI and KBA-influenced protocols.
Buyer concentration among tier-one automotive and logistics OEMs is consolidating specification authority into centralized engineering procurement functions. Traditional distributor channels face disintermediation as direct OEM-supplier technical partnerships govern long-term frame agreements. The shift is most visible in Germany, where Volkswagen, BMW, and Daimler Truck have established captive linear motion engineering centers with preferred rail supplier qualification programs.
Check Rails Market Segmentation
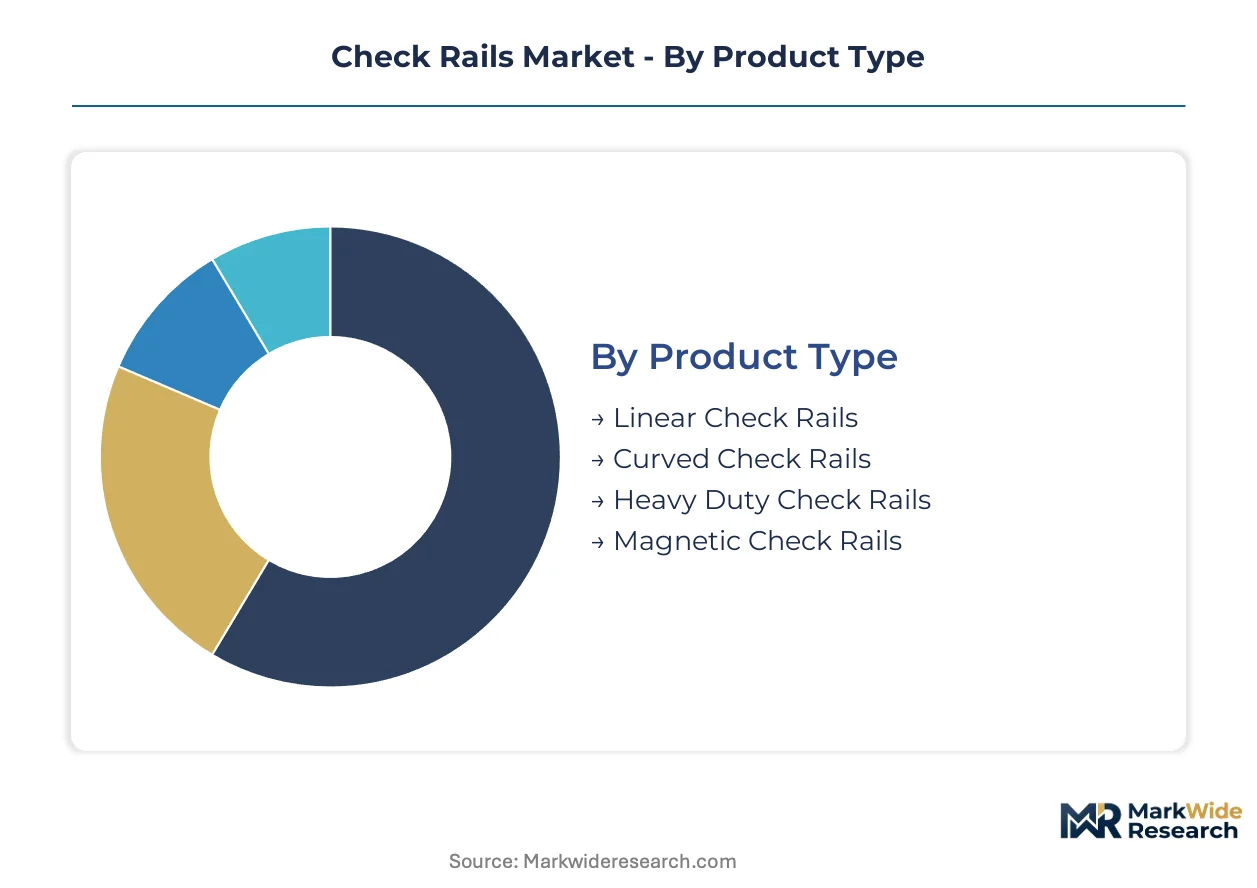
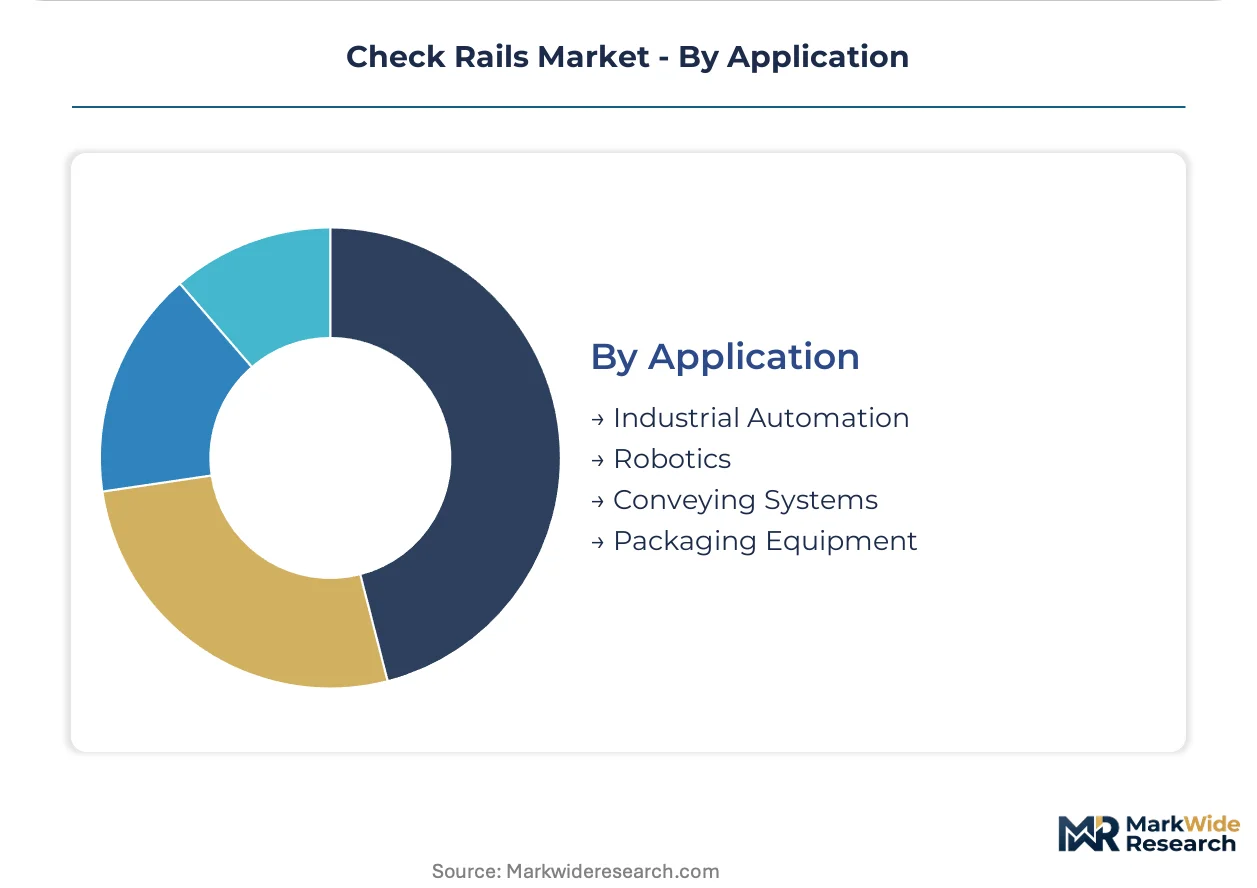
Check rails serve divergent operational requirements across automation architectures, from high-cycle linear positioning to contactless magnetic guidance. Segmentation reveals how specification-grade versus standard-grade procurement splits along application criticality, installation environment, and metallurgical performance thresholds.
Product Type:
After-sales service intensity varies dramatically across product architectures, with magnetic and heavy-duty installations demanding specialized field engineering while linear rails sustain predictable maintenance revenue through replacement cycles.
- Linear Check Rails:Recirculating ball or roller-bearing guidance systems manufactured from hardened alloy steel with sub-0.01 mm straightness tolerances. Demand concentrates in German automotive press shops and Japanese electronics assembly where retrofit programs and preventive maintenance generate recurring specification-grade procurement.
- Magnetic Check Rails:Permanent magnet arrays with servo-controlled air gaps enabling contactless positioning. Semiconductor wafer handling in South Korea and pharmaceutical cleanrooms in Switzerland specify these architectures to eliminate lubricant contamination, compressing maintenance intervals while commanding substantial specification premiums.
- Curved Check Rails:CNC-bent or extruded arc segments for rotary indexing tables and circular conveyor layouts, common in packaging machinery around Bologna and automotive component assembly near Stuttgart.
- Heavy Duty Check Rails:Forged or rolled steel profiles with fatigue ratings exceeding 10 million load cycles, specified for port crane logistics in Rotterdam and steel mill material handling in Duisburg.
By volume, Linear Check Rails leads. By growth pace, Magnetic Check Rails is ahead.
Installation Method:
Installation complexity drives project engineering margins, with embedded and ceiling-mounted configurations requiring structural analysis and custom fabrication that surface-mount alternatives avoid.
- Surface Mount:Bolt-down rail assemblies on machined subplates or steel frames, dominant in retrofit automation lines where floor or platform access permits rapid deployment without structural modification.
- Embedded:Rail channels set into concrete or epoxy-filled trenches, specified for heavy-load port logistics and steel mill applications where absolute rigidity and vibration dampening override installation cost.
- Wall-Mounted:Vertical rail orientations for pick-and-place gantries and elevated conveying systems, common in electronics assembly cleanrooms where floor space optimization governs layout design.
- Ceiling-Mounted:Overhead rail suspensions for intralogistics and automated storage systems, prevalent in distribution centers near Leipzig and Eindhoven where cubic space utilization drives architectural decisions.
Surface Mount captures the largest installed base. Embedded commands the highest project value per linear meter.
Material:
Material selection locks in performance ceilings and supply chain exposure, with steel formulations requiring metallurgical partnerships and aluminum extrusion tying margins to energy-intensive smelting economics.
- Steel:Through-hardened or case-hardened alloy grades with 58-62 HRC surface hardness, specified for automotive press shops and heavy material handling where fatigue resistance and impact tolerance are non-negotiable.
- Aluminum:6061-T6 or 7075-T6 extrusions with anodized wear surfaces, dominant in packaging machinery and light robotics where weight reduction and corrosion resistance outweigh load-bearing requirements.
- Plastic:Acetal or UHMW-PE guidance elements for chemical exposure environments and food-contact applications, specified in pharmaceutical handling equipment requiring FDA-compliant materials.
- Composite:Carbon-fiber reinforced polymer rails penetrating light-load conveying below 500 kg, eroding aluminum volume in electronics assembly and consumer goods packaging.
Steel dominates specification-grade procurement. Composite is gaining share fastest in weight-sensitive applications.
Application:
Application end-use determines certification requirements, with industrial automation and robotics demanding ISO 13849-1 functional safety compliance while conveying systems prioritize throughput reliability.
- Industrial Automation:Linear motion infrastructure for machine tools, assembly systems, and test equipment, anchored by German automotive OEM engineering centers with captive supplier qualification programs.
- Robotics:Precision guidance for articulated arm bases, gantry systems, and collaborative robot workcells, concentrated in Japanese and German factory automation clusters with METI and KBA-influenced safety protocols.
- Conveying Systems:Pallet and unit-load transport rails for intralogistics and distribution, common in Dutch port logistics and French automotive supplier parks where throughput density governs specification.
- Packaging Equipment:High-speed carton and bottle handling lines, prevalent in Italian packaging machinery districts and German pharmaceutical manufacturing where cleanroom compatibility shapes material selection.
Industrial Automation generates the largest revenue pool. Robotics shows the steepest specification-grade growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM engineering centers in Germany and logistics operators in the Netherlands concentrate specification-grade check rail procurement authority, while steel mill and port infrastructure investments in China and India reshape regional demand patterns.
Germany
Automotive press shops at Volkswagen, BMW, and Daimler Truck drive specification-grade linear rail consumption with captive engineering centers in Wolfsburg, Munich, and Stuttgart. KBA-influenced industrial safety protocols mandate ISO 13849-1 functional safety compliance for all new automation deployments. The Baden-Württemberg and Bavaria industrial clusters anchor European precision motion infrastructure specification.
China
Steel mill modernization and port logistics automation in Shanghai, Tianjin, and Guangzhou generate heavy-duty check rail demand for load-bearing applications exceeding 10 million fatigue cycles. MIIT-guided smart manufacturing initiatives accelerate Industry 4.0 retrofit programs requiring sensor-ready linear motion components. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate domestic specification-grade procurement.
United States
Automotive stamping lines in Michigan and Ohio sustain replacement cycles for hardened steel linear guidance systems in Detroit and Toledo supplier parks. OSHA machinery safety enforcement and NHTSA-influenced automotive quality protocols elevate certification requirements for linear motion components. The Midwest industrial corridor maintains the largest installed base of legacy recirculating ball rail systems.
Japan
Electronics assembly and semiconductor wafer handling equipment in Tokyo, Osaka, and Nagoya specify magnetic check rails for cleanroom-adjacent operations with contactless positioning. METI's Factory Automation Standards Initiative mandates predictive maintenance data architectures for capital equipment tax incentives. The Kanto and Kansai industrial belts lead specification-grade adoption for servo-driven pick-and-place systems.
India
Automotive and electronics manufacturing clusters near Pune, Chennai, and Gurugram expand precision linear motion infrastructure under the PLI scheme for advanced manufacturing equipment. BIS machinery safety standards and CDSCO-influenced pharmaceutical handling regulations tighten compliance for cleanroom-compatible rail systems. The Maharashtra and Tamil Nadu industrial corridors anchor emerging specification-grade demand.
Check Rails Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where specification-grade steel production clusters with integrated metallurgical operations and standard-grade aluminum extrusion fragments among regional fabricators. The vendor base separates into three strategic archetypes: captive steelmakers with metallurgical R&D depth, large-scale rolling stock manufacturers with cost-adjusted performance positioning, and precision machining specialists serving retrofit and maintenance replacement cycles. Dominant competitive moves include backward integration into alloy formulation and capacity expansion in automotive-adjacent industrial clusters.
Among integrated steelmakers with captive rail production, ArcelorMittal and Voestalpine Schienen GmbH exemplify the metallurgical-depth archetype, while CRRC Corporation Limited represents scale-driven manufacturing capacity serving conveying system deployments. Progress Rail and Vossloh AG occupy positions within the rolling stock and infrastructure specialist tier, with Alstom SA and Patil Group representing regional fabrication and engineering-service positioning across divergent compliance environments.
| Leading Market Players |
|---|
| Progress Rail |
| Patil Group |
| Moxon Industries |
| Kimes Steel & Rail |
| Vossloh AG |
| ArcelorMittal |
| Voestalpine Schienen GmbH |
| Alstom SA |
| CRRC Corporation Limited |
| Others |
Value Chain & Pricing Dynamics
Integrated steelmakers in Germany and Japan anchor premium alloy supply, concentrating margin capture in specification-grade check rails while tier-two machinery builders face sourcing bottlenecks without captive metallurgical partnerships. Cost-plus contracts with steel scrap indexation transfer raw material volatility downstream, compressing standard-grade aluminum extrusion margins.
Pricing Analysis
Cost-plus contracts indexed to hot-rolled steel and aluminum LME benchmarks dominate specification-grade procurement, with three-tier pricing structure across premium, standard, and economy levels separating ISO 13849-1 certified systems from uncertified alternatives. Price differentiation rests on fatigue cycle ratings and embedded sensor architectures, with automotive OEMs in Wolfsburg and Stuttgart showing lowest sensitivity due to captive engineering centers, while packaging machinery builders in Bologna face acute pressure from composite substitution below 500 kg load thresholds. Margins are tightening in standard-grade linear rails as energy-intensive smelting economics erode aluminum extrusion profitability.
Supply Chain Analysis
Scrap steel and primary alloy feedstock draw from integrated mills in Germany, Japan, and China, with rare-earth magnet arrays for magnetic check rails sourcing predominantly from Chinese separation facilities. Supply chain risk centers on single-source dependency for specification-grade steel formulations certified to 10 million cycle thresholds. Distribution runs through direct OEM-supplier frame agreements in German automotive clusters, bypassing traditional distributor channels, while aftermarket replacement cycles sustain regional fabricator networks across European industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one automotive and logistics OEMs with centralized engineering procurement functions, fragmenting specification authority away from traditional distributor channels. Volkswagen, BMW, and Daimler Truck have established captive linear motion engineering centers that govern long-term supplier qualification.
For Market Incumbents: Build metallurgical R&D moats through backward integration into hardened alloy formulation and fatigue testing capabilities. Defend against polymer composite substitution by extending sensor-ready architectures with standardized IO-Link interfaces for Industry 4.0 retrofit programs. Add capacity in automotive-adjacent clusters near Pune and Chennai to capture PLI scheme localization demand. For New Entrants and Emerging Players: Pursue white-space opportunities in magnetic check rails for semiconductor wafer handling, where South Korean and Taiwanese electronics OEMs specify contactless architectures with limited incumbent specialization. Target India's emerging specification-grade demand under PLI incentives for advanced manufacturing equipment. Enter through technical partnerships with regional system integrators lacking metallurgical depth. For Investors and Strategic Acquirers: Capital is best deployed toward precision machining specialists with established retrofit and maintenance replacement channels, given long-term viability through predictable revenue cycles in mature industrial economies. Monitor convergence between functional safety standards and predictive maintenance data architectures as inflection indicator for specification premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Formulation | Captive steel supply secures specification-grade rail production for German automotive press shop demand. |
| Sensor-Ready Architecture Development | Pre-integrated strain gauge and temperature monitoring captures METI-guided depreciation incentives in Japan. |
| Capacity Expansion in India | Localized production near Pune and Chennai clusters addresses PLI scheme procurement requirements. |
| ISO 13849-1 Certification Investment | Functional safety compliance unlocks CE-marked access to German KBA-influenced industrial automation deployments. |
| Direct OEM Technical Partnership | Long-term frame agreements with Volkswagen and BMW engineering centers disintermediate distributor channels. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads across German, Japanese, and Chinese industrial clusters, and secondary validation through customs and trade data, SEC filings from listed rail and steel producers, machinery safety certification databases, and automotive production statistics. Bottom-up demand modeling triangulated against top-down industrial automation capex forecasts.
Forecast inputs span product type segmentation by load-bearing capacity and guidance architecture, installation method by structural configuration, material grade by metallurgical performance threshold, and application end-use by certification requirements across the projection horizon. CAGRs derive from regression analysis against industrial automation equipment shipments and predictive maintenance adoption curves, with magnetic check rail penetration in semiconductor handling serving as a demand elasticity anchor.
Macroeconomic conditions sit as an overlay; deviation in steel scrap pricing, energy-intensive smelting economics, or automotive OEM capex cycles would shift the trajectory. Cross-checking against industrial automation equipment shipment data from German and Japanese machinery associations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Rail Maintenance Management System Market
Railway
Locomotive Market
Railway
Train Locomotive Suspension Market
Railway
Smart Railways Market
Railway
Global Smart Locomotive Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Train HVAC Market
Railway
Road-Rail Vehicles Market
Railway
Railway Digital Signal Axle Counters Market
Railway
Railway System Market
Railway
Rail Seat Market
Railway
Rail Freight Slot and Path Optimization Platforms Market
Railway
Railway Engine Market
Railway
Global Train Control and Management Systems Market
Railway
Rail Composites Market
Railway
Locomotive Radiator Fan Market