
 Driver Monitoring System (DMS) Market | 2026-2036
Driver Monitoring System (DMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Driver Monitoring System (DMS) Market Foresight
The EU General Safety Regulation is expanding the addressable market for driver monitoring hardware in European commercial vehicle fleets. Motive leverages its integrated fleet safety platform to capture share among North American trucking operators. Samsara sustains technology leadership through cloud-native video telematics that unify DMS with vehicle diagnostics. Geotab dominates open-platform fleet data exchange, allowing third-party DMS modules to integrate across mixed vehicle pools.
A driver monitoring system combines optical sensors, infrared emitters, and embedded vision processors to track ocular movement, head pose, and eyelid closure duration in real time; its primary purpose is to detect impairment states and trigger tiered alerts before safety incidents occur. Camera-based technology leads unit shipments due to declining CMOS sensor costs and proven accuracy in drowsiness classification algorithms. Fleet management applications generate the highest software attach rates because operators monetize DMS data through insurance premium reductions and driver coaching programs. Hardware components retain the largest revenue share, though cloud solutions are growing fastest as over-the-air update architectures replace boxed software licenses.
The EU General Safety Regulation and NHTSA advanced notice of proposed rulemaking on impaired driving detection are converging to mandate DMS fitment in new commercial and passenger vehicles across two major markets. ISO 26262 functional safety standards and IEC 61508 SIL ratings govern processor certification, creating compliance barriers for unqualified entrants. Stakeholders must monitor the trajectory of Chinese GB standards for intelligent connected vehicles, as domestic OEM integration timelines will determine whether NMPA-type approval processes accelerate or delay market access for foreign component suppliers.
Market Dynamics
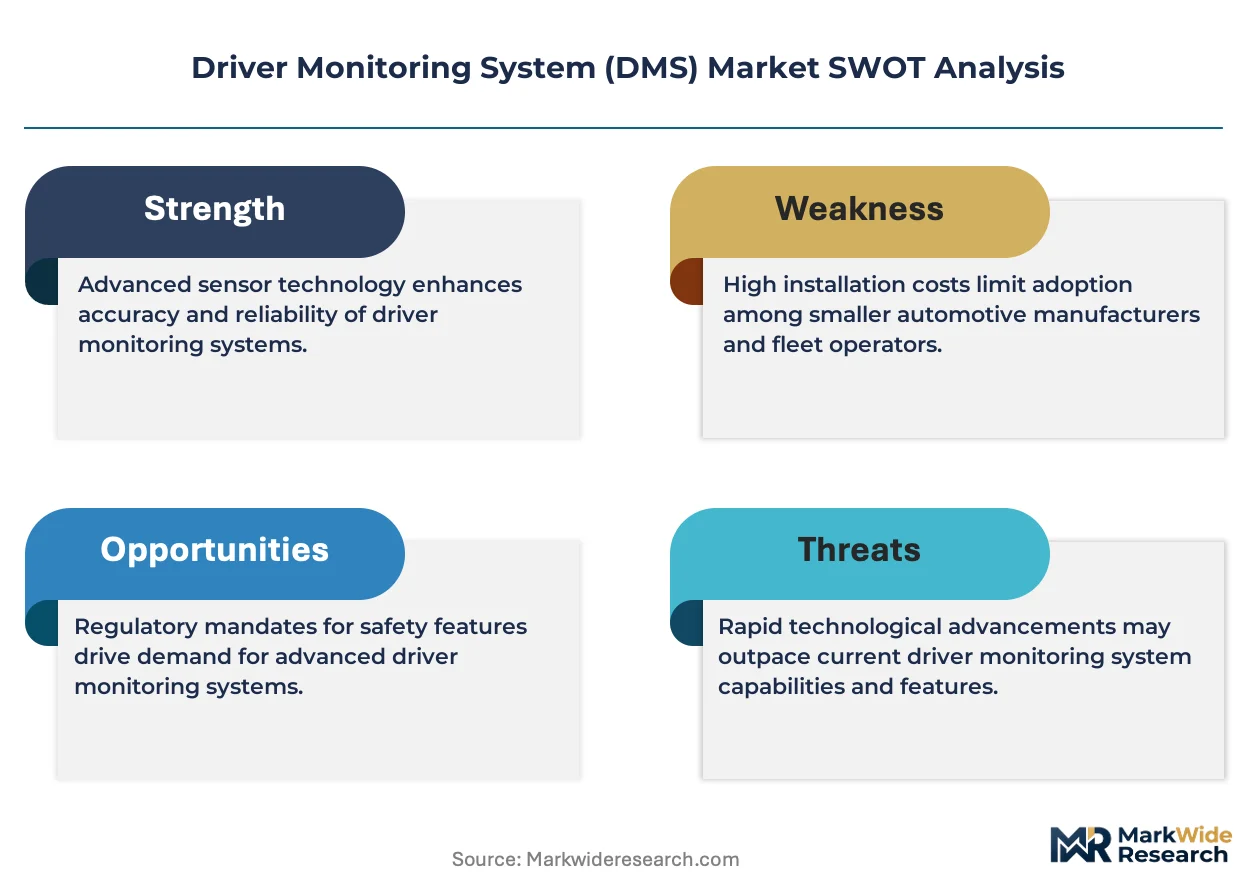
The EU General Safety Regulation mandates direct driver monitoring technology in all new commercial vehicles, forcing Tier-1 suppliers to reconfigure optical sensor supply chains and certification workflows around ISO 26262 functional safety standards.
Growth Catalysts
- EU General Safety Regulation:The mandate requires drowsiness and distraction detection systems in trucks and buses above 3.5 tonnes, creating guaranteed hardware demand through 2028 and beyond.
- Fleet insurance underwriting:Commercial vehicle insurers in the United States now offer premium reductions of 10-15% for operators deploying camera-based DMS with telematics integration.
- Infrared emitter miniaturization:Advances in 940nm VCSEL packaging reduce module footprint by 40%, enabling dashboard-integrated designs that preserve cabin aesthetics.
Market Restraints
- CMOS sensor supply concentration:Sony and ON Semiconductor control 70% of automotive-grade image sensor output, creating single-source vulnerability for DMS camera modules.
- Silicon wafer cost volatility:300mm wafer spot prices fluctuated 23% in 2022-2023, compressing margins for vision processor ASIC vendors serving the mid-tier DMS segment.
- Low-light classification accuracy:Existing algorithms degrade below 5 lux ambient illumination without active infrared illumination, adding cost and power draw.
Strategic Opportunities
- India commercial vehicle retrofit:The country's 3.5 million existing truck fleet lacks factory-fit DMS, creating aftermarket demand as insurers and fleet owners mandate upgrades.
- Occupant monitoring convergence:Child presence detection and passenger gaze tracking merge with driver monitoring into unified cabin sensing platforms, expanding per-vehicle content value.
- China GB/T intelligent connected vehicle standards:Draft requirements for fatigue monitoring in passenger cars will replicate the EU mandate pattern, opening domestic OEM integration contracts.
Industry Challenges
- Functional safety certification timelines:ISO 26262 ASIL-B qualification for new vision processors requires 18-24 months, delaying product launches and freezing design wins.
- Algorithm training data diversity:Eyelid closure and head pose models underperform for certain demographic groups, requiring expensive dataset expansion and revalidation.
- Legacy fleet telematics integration:Proprietary CAN bus protocols in older commercial vehicles block plug-and-play DMS deployment, forcing custom engineering per truck model.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driver Monitoring System (DMS) Market |
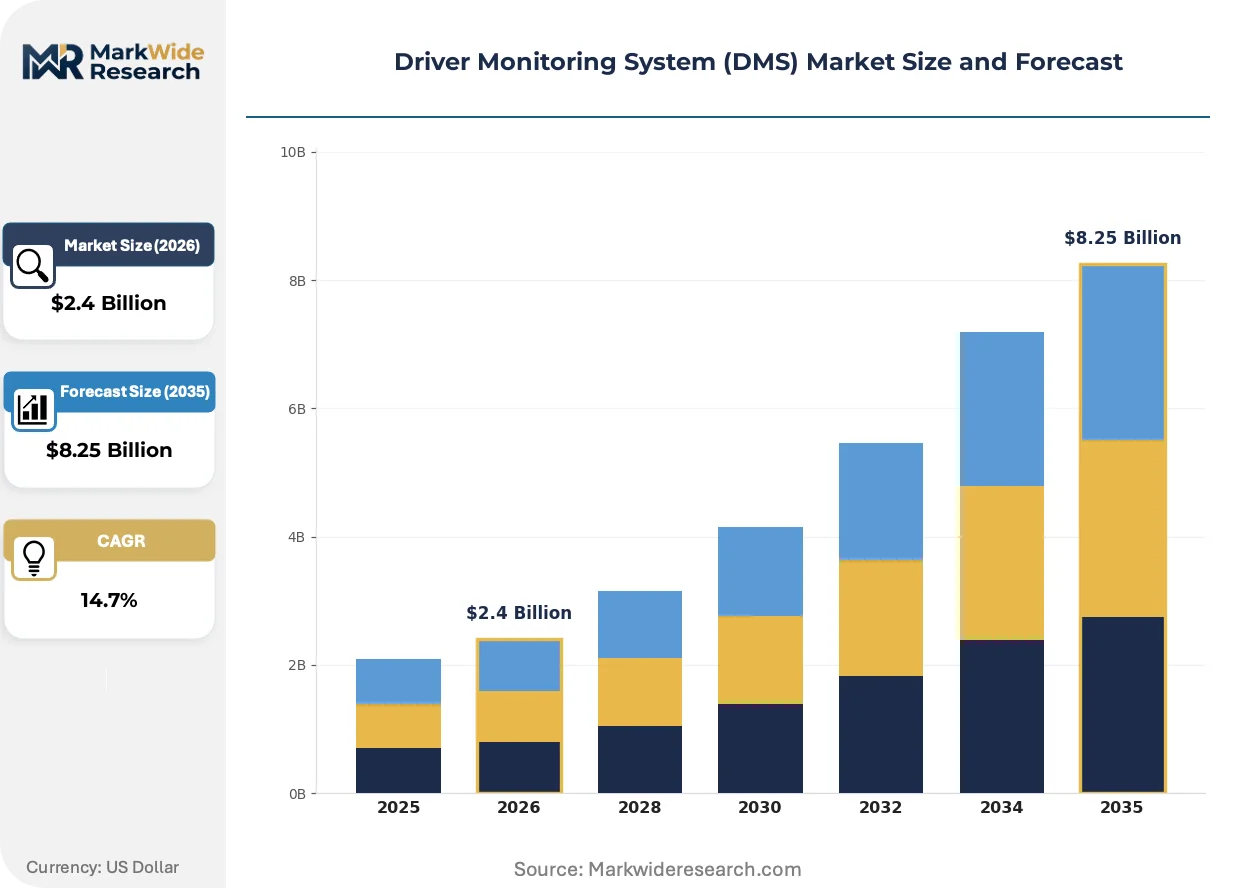
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
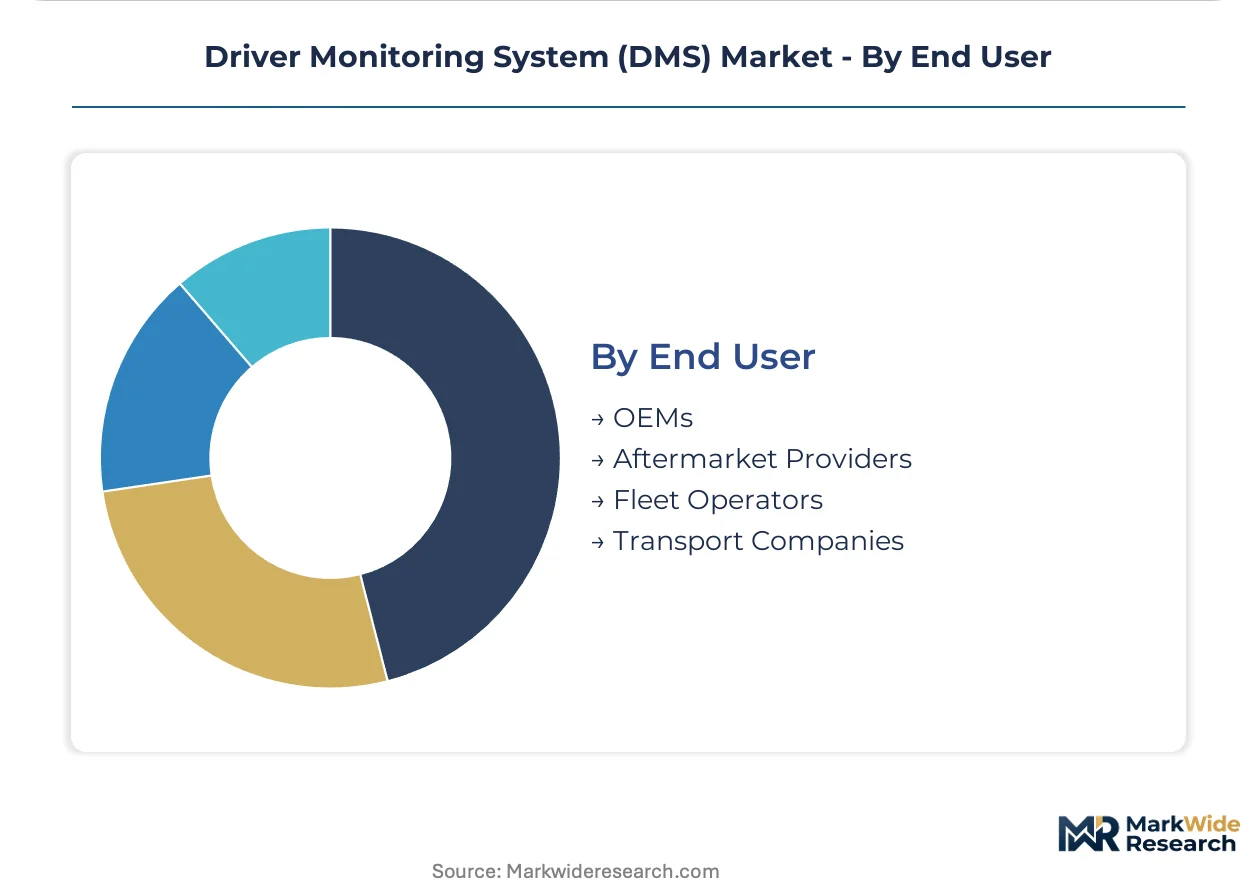
| Segmentation | Technology: Camera-Based, Sensor-Based, Infrared, Radar Application: Commercial Vehicles, Passenger Cars, Fleet Management, Autonomous Vehicles Component: Hardware, Software, Cloud Solutions, Integration Kits End User: OEMs, Aftermarket Providers, Fleet Operators, Transport Companies |
| Companies Covered | Samsara, SafetyCulture, Motive, Linxup, Azuga, Verizon Connect, Geosavi, Quartix, Geotab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driver Monitoring System (DMS) Market Shifts & Advancements
Neural network acceleration at the edge is compressing DMS response latency from hundreds of milliseconds to sub-100ms, enabling real-time intervention before impairment-induced lane departures occur.
Transformer-based computer vision architectures are automating the feature extraction pipeline for drowsiness classification, eliminating hand-engineered eye aspect ratio thresholds that fail across ethnicities and lighting conditions. European OEMs are adopting these models fastest, driven by liability exposure under the EU General Safety Regulation's strict performance requirements. The shift is compressing competitive differentiation around data scale rather than algorithmic craft.
NHTSA's advanced notice of proposed rulemaking on impaired driving detection signals federal mandate expansion beyond the EU's commercial vehicle scope into US passenger cars. The regulatory trajectory forces Tier-1 suppliers to design dual-market platforms from inception rather than regional variants. Domestic OEMs are pre-positioning infrared DMS in 2025 model year vehicles to avoid retrofit penalties.
Fleet procurement departments now bundle DMS with video telematics under unified safety-as-a-service contracts, displacing discrete hardware purchases. The model shift concentrates buying power with cloud-native platform vendors and marginalizes boxed-equipment distributors. North American trucking operators lead this transition, with insurance carriers mandating integrated data feeds for policy eligibility.
Driver Monitoring System (DMS) Market Segmentation
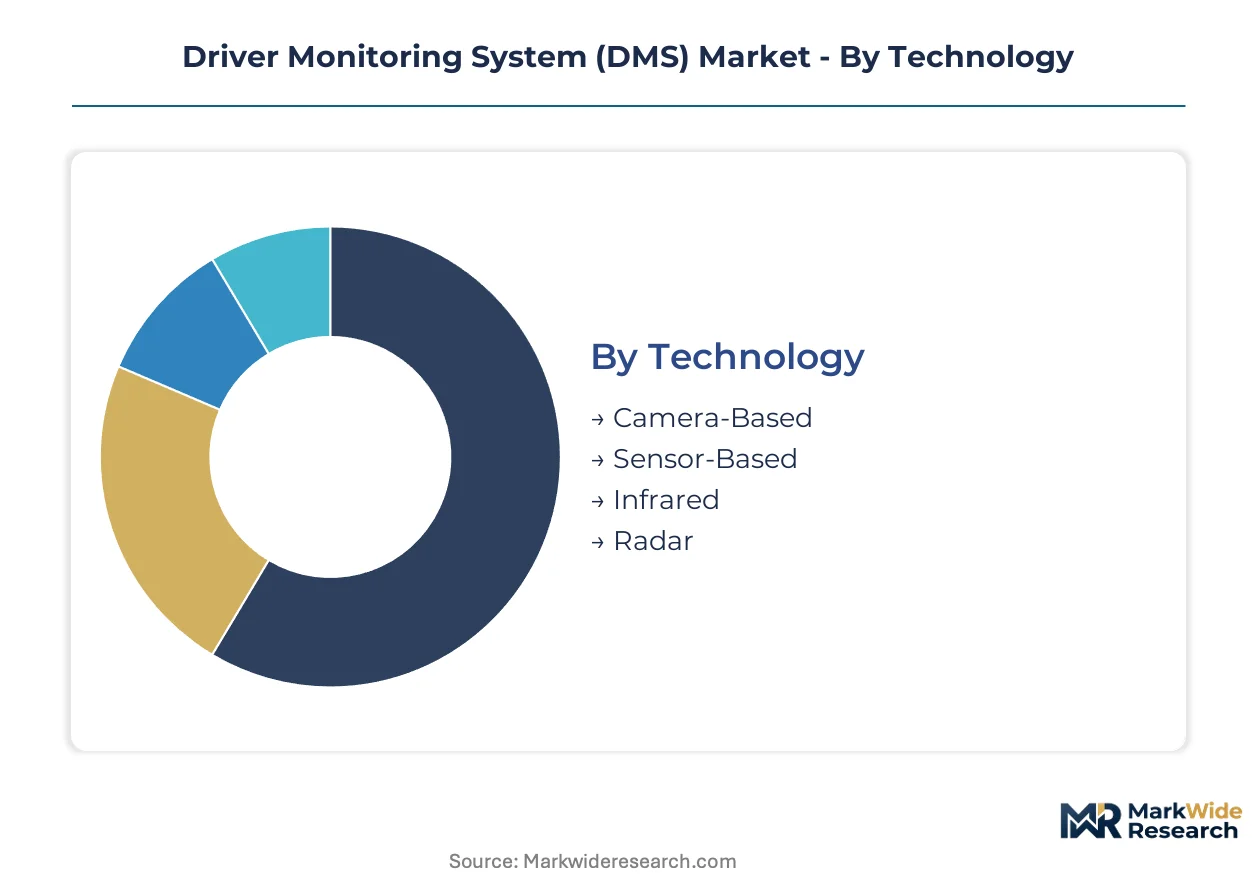
DMS procurement patterns diverge sharply across technology maturity, vehicle integration depth, and buyer sophistication. Segment boundaries are blurring as infrared emitters merge with camera modules and fleet operators demand unified hardware-software bundles rather than discrete components.
Technology:
Optical sensing architectures define performance benchmarks and cost structures for DMS deployment across vehicle classes.
- Camera-Based:CMOS image sensors capture facial landmarks, head pose vectors, and eyelid closure dynamics at 30-60 frames per second. Fleet operators in the United States negotiate insurance premium reductions contingent on camera-based systems with cloud video archival.
- Infrared:940nm VCSEL arrays enable reliable pupil tracking below 1 lux ambient illumination without driver distraction from visible light emission. Chinese OEMs integrate infrared DMS into new energy vehicle platforms as standard equipment ahead of anticipated GB/T mandate expansion.
- Sensor-Based:Steering angle sensors, lane departure warnings, and seat pressure mats provide indirect impairment proxies without optical privacy concerns. European commercial vehicle retrofits favor sensor fusion approaches to minimize driver union resistance.
- Radar:Millimeter-wave Doppler signatures detect micro-movements in chest cavity and head position for drowsiness classification. Tier-1 suppliers prototype radar-DMS fusion for Level 3 autonomous handover scenarios.
Mature deployment sits with Camera-Based systems. Newer deployment is concentrated in Infrared modules as cabin aesthetic integration tightens.
Application:
Regulatory mandate timing and liability exposure create divergent adoption velocities across vehicle categories.
- Fleet Management:Unified safety-as-a-service contracts bundle DMS hardware with telematics platforms and driver coaching analytics. North American trucking operators now require integrated video feeds for insurance policy eligibility.
- Commercial Vehicles:The EU General Safety Regulation mandates direct driver monitoring in trucks and buses above 3.5 tonnes, guaranteeing hardware demand through 2028. Tier-1 suppliers reconfigure ISO 26262 certification workflows around this mandate.
- Passenger Cars:NHTSA advanced notice of proposed rulemaking signals federal impaired driving detection requirements extending beyond commercial scope. Domestic OEMs pre-position infrared DMS in 2025 model year vehicles to avoid retrofit penalties.
- Autonomous Vehicles:Handover readiness monitoring demands sub-100ms latency for impairment detection before control transfer. Edge neural network acceleration compresses response times to meet functional safety thresholds.
Volume concentration rests with Commercial Vehicles. Steepest expansion trajectory belongs to Fleet Management as procurement shifts from discrete hardware to subscription platforms.
Component:
Value capture migrates from boxed equipment toward recurring software revenue as over-the-air architectures mature.
- Hardware:Optical sensor modules, infrared emitters, and embedded vision processors retain the largest revenue share. Sony and ON Semiconductor supply 70% of automotive-grade CMOS image sensors for DMS camera modules.
- Cloud Solutions:Over-the-air algorithm updates and centralized driver coaching dashboards displace perpetual software licenses. Cloud-native platforms concentrate buying power with integrated vendors and marginalize boxed-equipment distributors.
- Software:Transformer-based computer vision architectures automate drowsiness classification without hand-engineered thresholds. European OEMs adopt these models fastest under EU General Safety Regulation liability exposure.
- Integration Kits:CAN bus adapters and proprietary protocol bridges enable DMS retrofit in legacy commercial vehicle fleets. India's 3.5 million existing truck fleet creates aftermarket demand as insurers mandate upgrades.
Margin capture favors Hardware today. Cloud Solutions are climbing the fastest as fleet procurement shifts to subscription models.
End User:
Buyer sophistication and integration capability determine pricing power and contract structure across the value chain.
- Fleet Operators:Sophisticated procurement departments negotiate unified safety-as-a-service contracts bundling DMS with video telematics. Insurance carriers mandate integrated data feeds for premium eligibility.
- OEMs:Vehicle manufacturers specify ASIL-B qualified vision processors and infrared modules for factory integration. ISO 26262 functional safety certification timelines of 18-24 months freeze design wins and delay product launches.
- Aftermarket Providers:Independent installers serve India's commercial vehicle retrofit opportunity and European owner-operator segments. Custom CAN bus engineering per truck model blocks plug-and-play deployment.
- Transport Companies:Municipal bus operators and long-haul logistics firms balance regulatory compliance against driver privacy concerns. Union negotiations in Germany and France slow camera-based system rollout.
Contract sophistication peaks with Fleet Operators. Volume expansion concentrates in OEMs as mandate coverage broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit anchors North American DMS engineering activity, with Tier-1 suppliers clustering around the city's autonomous vehicle development corridors to prototype handover-ready monitoring systems for domestic OEMs.
United States
NHTSA's advanced notice of proposed rulemaking on impaired driving detection is forcing domestic OEMs to pre-position infrared DMS in 2025 model year vehicles. Fleet insurance underwriters in the United States now mandate integrated video telematics feeds for premium eligibility. Michigan's automotive corridor hosts the majority of Tier-1 vision processor certification activity.
China
Chinese OEMs integrate infrared DMS into new energy vehicle platforms at scale ahead of anticipated GB/T mandate expansion. NMPA-type approval processes for intelligent connected vehicle components determine market access timelines for foreign suppliers. Shenzhen and Shanghai host the dominant clusters of domestic DMS module manufacturing.
Germany
The EU General Safety Regulation mandates direct driver monitoring in commercial vehicles above 3.5 tonnes, guaranteeing hardware demand through 2028. KBA certification workflows for ISO 26262 ASIL-B vision processors freeze design wins for 18-24 month cycles. Stuttgart and Munich anchor Continental European optical sensor supply chain reconfiguration.
India
The country's 3.5 million existing truck fleet lacks factory-fit DMS, creating aftermarket demand as insurers mandate upgrades. BIS standards for commercial vehicle safety equipment are converging toward mandatory fatigue monitoring. Tamil Nadu and Maharashtra host the primary clusters of telematics integration engineering for legacy fleet retrofit.
Japan
METI guidance on autonomous vehicle safety is accelerating edge neural network deployment for sub-100ms impairment detection latency. JIS standards for driver monitoring hardware are tightening ahead of Level 3 autonomous handover commercialization. Nagoya and Tokyo anchor the development of radar-DMS fusion systems for premium passenger vehicles.
Driver Monitoring System (DMS) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and data platform integration. The vendor base stratifies into three tiers: cloud-native platform vendors capturing unified safety-as-a-service contracts, telematics-integrated hardware specialists, and boxed-equipment distributors facing margin compression. Dominant competitive moves include strategic partnerships bundling DMS with fleet insurance programs and geographic expansion into India's commercial vehicle retrofit opportunity.
Within the cloud-native platform tier, Samsara and Motive exemplify the integrated safety-as-a-service model consolidating procurement power among North American fleet operators. Geotab occupies a position anchoring open-platform data exchange, allowing third-party DMS modules to integrate across mixed vehicle pools. Verizon Connect represents the telecommunications-backed entrant leveraging existing fleet connectivity relationships.
| Leading Market Players |
|---|
| Samsara |
| SafetyCulture |
| Motive |
| Linxup |
| Azuga |
| Verizon Connect |
| Geosavi |
| Quartix |
| Geotab |
| Others |
Supply & Pricing Matrix
Automotive-grade CMOS image sensor costs cascade through three distinct pricing tiers as Sony and ON Semiconductor output flows from wafer fabrication in Japan and the United States to module integrators in China and Germany. Tier-1 suppliers absorb silicon wafer spot price volatility through long-term offtake agreements, while mid-tier DMS vendors face margin compression from 300mm wafer cost swings.
Pricing Analysis
Insurance premium reduction value anchors DMS pricing, with fleet operators monetizing 10-15% premium cuts through subscription-based safety-as-a-service contracts. Pricing stratifies across ASIL-B certified vision processors, ASIL-D qualified modules, and uncertified aftermarket kits. Cost compression in the mid-tier segment is intensifying because Chinese OEMs are integrating infrared DMS as standard equipment ahead of anticipated GB/T mandate expansion. Fleet operators exhibit the highest price sensitivity due to procurement centralization, while luxury passenger car OEMs prioritize certification grade over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European Tier-1 suppliers mandate parallel qualification of Sony and ON Semiconductor CMOS sensors, plus secondary VCSEL emitter vendors in Taiwan and South Korea. Module assembly draws from precision optics manufacturers in Germany, infrared packaging specialists in Japan, and vision processor foundry capacity in Taiwan. Single-source vulnerability concentrates in 940nm VCSEL emitters where ams Osram dominates high-volume automotive qualification. Distribution runs through Tier-1 system integrators to OEM assembly plants, with aftermarket channels serving India's commercial vehicle retrofit demand through telematics specialists in Tamil Nadu.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DMS market is transitioning from discrete camera hardware to edge-accelerated neural network platforms, with transformer-based computer vision architectures displacing hand-engineered eye aspect ratio algorithms. This technology shift reconfigures competitive advantage around data scale rather than optical engineering craft.
For Market Incumbents: Extend cloud-native platform capabilities to capture unified safety-as-a-service contracts before fleet procurement centralizes buying power with integrated vendors. Defensive consolidation through backward integration into infrared emitter manufacturing reduces exposure to ams Osram single-source vulnerability. ISO 26262 ASIL-D certification investment creates differentiation as functional safety timelines freeze design wins for 18-24 month cycles.
For New Entrants and Emerging Players: The gap between premium ASIL-B qualified systems and uncertified economy aftermarket kits offers entry space for mid-tier players targeting India's 3.5 million truck retrofit opportunity. Focus initial penetration on commercial vehicle fleet operators in Maharashtra and Tamil Nadu where BIS standards convergence is mandating fatigue monitoring upgrades. Partner with domestic telematics integrators to bypass proprietary CAN bus protocol barriers in legacy vehicle deployment.
For Investors and Strategic Acquirers: NHTSA's advanced notice of proposed rulemaking on impaired driving detection is the leading indicator that federal mandate expansion will replicate the EU General Safety Regulation pattern across United States passenger cars. Long-term viability favors vendors with dual-market platform architectures qualified for both commercial and passenger vehicle integration. Watch for GB/T standard finalization in China as the signal determining whether NMPA-type approval processes accelerate or delay foreign supplier market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Neural Network Acceleration | Sub-100ms latency enables real-time intervention before impairment-induced lane departures occur. |
| ASIL-D Functional Safety Certification | KBA and NHTSA qualification workflows freeze design wins for 18-24 month competitive moats. |
| Cloud-Native Platform Integration | Samsara and Motive consolidate fleet procurement power through unified safety-as-a-service contracts. |
| India Aftermarket Channel Partnership | Tamil Nadu telematics integrators unlock access to 3.5 million legacy commercial vehicles. |
| Dual-Market Platform Architecture | Simultaneous EU and United States qualification avoids regional variant engineering penalties. |
Research Methodology
Document review covered regulatory filings from NHTSA, KBA, and NMPA, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, fleet safety managers at North American trucking operators, and infrared module manufacturing specialists. Secondary validation drew from ISO 26262 certification databases, vehicle production registries, and insurance underwriting guideline disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across hardware, software, and cloud solution segments.
Cross-referencing historical adoption curves from EU General Safety Regulation implementation against expert panel input on GB/T timeline probabilities shaped the projection framework. Segmentation modeling covered technology architecture, application category, component type, and end-user sophistication across the analysis window. CAGRs were derived from unit economics analysis of CMOS sensor cost decline trajectories and cloud subscription attach rate expansion. Forecast inputs incorporated VCSEL miniaturization roadmaps and neural network inference latency benchmarks.
Underlying measurement precision varies by segment; fleet management applications carry tighter precision than aftermarket retrofit projections due to procurement data availability. Forecasts reflect assumptions about regulatory mandate timing and silicon wafer cost stabilization. Deviation in NHTSA rulemaking finalization or Chinese GB/T standard publication would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Rear Cross Traffic Alert System Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market
Automotive Safety and Security Systems
Automotive Biometric Identification Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Automotive Vacuumless Braking Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Car Safety Market
Automotive Safety and Security Systems
Automotive Shielding Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Front Collision Warning Market
Automotive Safety and Security Systems
Traffic Jam Assist (TJA) Market
Automotive Safety and Security Systems
Automotive Brake Override System Market
Automotive Safety and Security Systems
Vehicle Anti-Theft System Market
Automotive Safety and Security Systems
Occupant Classification System Market