
 Egypt Cold Chain Logistics Market | 2026-2036
Egypt Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Cold Chain Logistics Market Foresight
Project finance and leasing arrangements for refrigerated fleet assets are reshaping competitive entry barriers in Egypt's cold chain sector. Logistics for Storage Services (S.A.E) leverages its bonded warehouse network near Alexandria Port to dominate pharmaceutical import handling. EPx Logistics anchors its position through specialized fleet deployment across the Nile Delta agricultural belt. Kuehne + Nagel competes via integrated sea-air-road temperature-controlled corridors linking Egyptian producers to European markets.
Cold chain logistics encompasses the temperature-controlled supply chain infrastructure maintaining specified thermal conditions for perishable goods from origin through final delivery, utilizing refrigerated transport units, insulated containers, and climate-mapped warehouse zones operating between -25°C and +15°C depending on cargo requirements. The primary commercial purpose centers on preserving product integrity, extending shelf life, and ensuring regulatory compliance for temperature-sensitive commodities across pharmaceutical, food, and agricultural value chains. Warehousing services command the deepest margin pools due to high capital barriers and long-term lease structures, while monitoring technology segments show the steepest growth trajectory as IoT-enabled real-time temperature tracking becomes standard in pharmaceutical and food safety protocols. Transportation services remain the most fragmented segment with intense price competition among local fleet operators.
Egypt's Food Safety Authority and the General Authority for Supply Commodities enforce HACCP and temperature logging standards that determine market access for imported perishables and pharmaceutical products. The Egyptian Drug Authority mandates GDP-compliant cold chain documentation for all vaccine and biologic distribution, creating compliance-driven demand for validated storage and transport systems. Stakeholders must monitor regulatory harmonization pressures between Egyptian standards and evolving EU Green Deal cold chain emissions protocols that could reshape import-export logistics requirements.
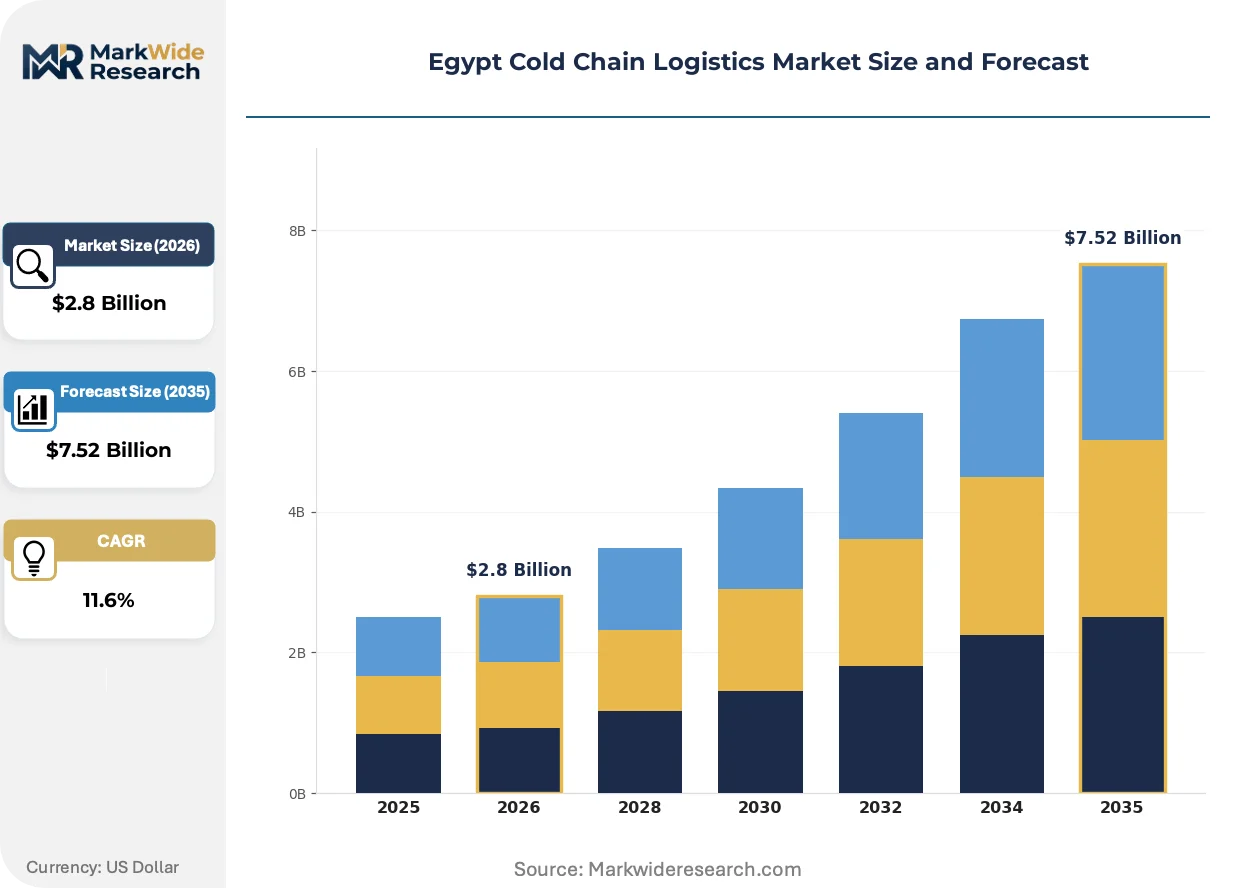
Market Dynamics
Egypt's Food Safety Authority has tightened HACCP compliance mandates for perishable imports, forcing warehouse upgrades nationwide and reshaping competitive entry barriers across refrigerated storage and transport infrastructure.
Growth Catalysts
- Pharmaceutical distribution expansion:Temperature-sensitive biologics require validated cold chain networks. Egypt's Egyptian Drug Authority mandates GDP-compliant documentation for vaccine distribution, driving demand for certified storage systems.
- EU Green Deal alignment pressures:Export-oriented producers face evolving emissions protocols for refrigerated transport. Compliance investments are accelerating fleet modernization along Alexandria-to-Europe corridors.
- IoT-enabled monitoring adoption:Real-time temperature tracking is digitizing pharmaceutical and food safety protocols. Bonded warehouse operators in Greater Cairo are deploying sensor networks to satisfy import inspection requirements.
Market Restraints
- Refrigerated fleet asset intensity:High capital requirements for temperature-controlled vehicles limit independent operator entry. Leasing arrangements dominate, compressing margins for asset-light competitors.
- Diesel price volatility:Transport segment profitability fluctuates with fuel cost swings. Nile Delta agricultural belt operators face margin erosion during price spikes.
- Bonded warehouse concentration:Cold storage capacity clusters near Alexandria Port and Greater Cairo. Peripheral governorates experience service gaps and elevated logistics costs.
Strategic Opportunities
- Upper Egypt agricultural corridors:Refrigerated transport penetration remains limited south of Cairo. Specialized fleet deployment into Sohag and Qena governorates addresses post-harvest losses in fresh produce value chains.
- Solar-powered cold storage:Photovoltaic integration with warehouse refrigeration reduces grid dependency. Rural agricultural cooperatives represent an underpenetrated customer segment for off-grid solutions.
- Red Sea port development:Suez Canal Economic Zone expansion creates demand for transhipment cold storage. Temperature-controlled facilities at Ain Sokhna target East African and Gulf re-export markets.
Industry Challenges
- Certified technician scarcity:Refrigeration system maintenance and GDP documentation expertise is concentrated in Alexandria and Cairo. Upcountry facilities face recruitment bottlenecks and training cost burdens.
- Multi-modal temperature integrity:Sea-air-road handoffs between Egyptian producers and European buyers create compliance documentation gaps. Integration complexity rises with corridor diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Cold Chain Logistics Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Monitoring Temperature Range: 1°C to 4°C, -18°C or Below, Ambient, Controlled End User: Pharmaceuticals, Food & Beverage, Agriculture, Retail Technology: GPS Tracking, RFID, IoT Solutions, Cold Storage Systems |
| Companies Covered | Logistics for Storage Services (S.A.E), EPx Logistics, Logistica, Kuehne + Nagel, DHL Supply Chain, Multi Fruit Egypt, Custom Storage Company (CSC), Aramex, CACC Cargolinx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Cold Chain Logistics Market Shifts & Advancements
Refrigerated supply chains are converging with digital infrastructure and regulatory harmonization pressures. Three developments are restructuring how temperature-sensitive cargo moves through Egyptian ports and agricultural belts.
IoT sensor networks are digitizing cold chain visibility from warehouse to final delivery. Pharmaceutical distributors and fresh produce exporters are deploying cellular-enabled temperature loggers at container and pallet level. This technology is digitizing compliance documentation for Egyptian Drug Authority inspections and reducing rejection rates at European entry points.
Egypt's Food Safety Authority has implemented mandatory HACCP temperature logging for all imported perishables. Warehouse operators must now maintain continuous digital records traceable to individual shipment lots. Small and mid-sized cold storage facilities in Alexandria port corridors are retrofitting monitoring infrastructure to avoid import license suspension.
Biologics manufacturers are consolidating procurement around integrated logistics providers offering end-to-end temperature validation. Fragmented local fleet operators are losing share to bonded warehouse networks with captive transport assets. This concentration is most visible in vaccine distribution contracts where Egyptian Drug Authority GDP certification serves as a non-negotiable qualifier.
Egypt Cold Chain Logistics Market Segmentation
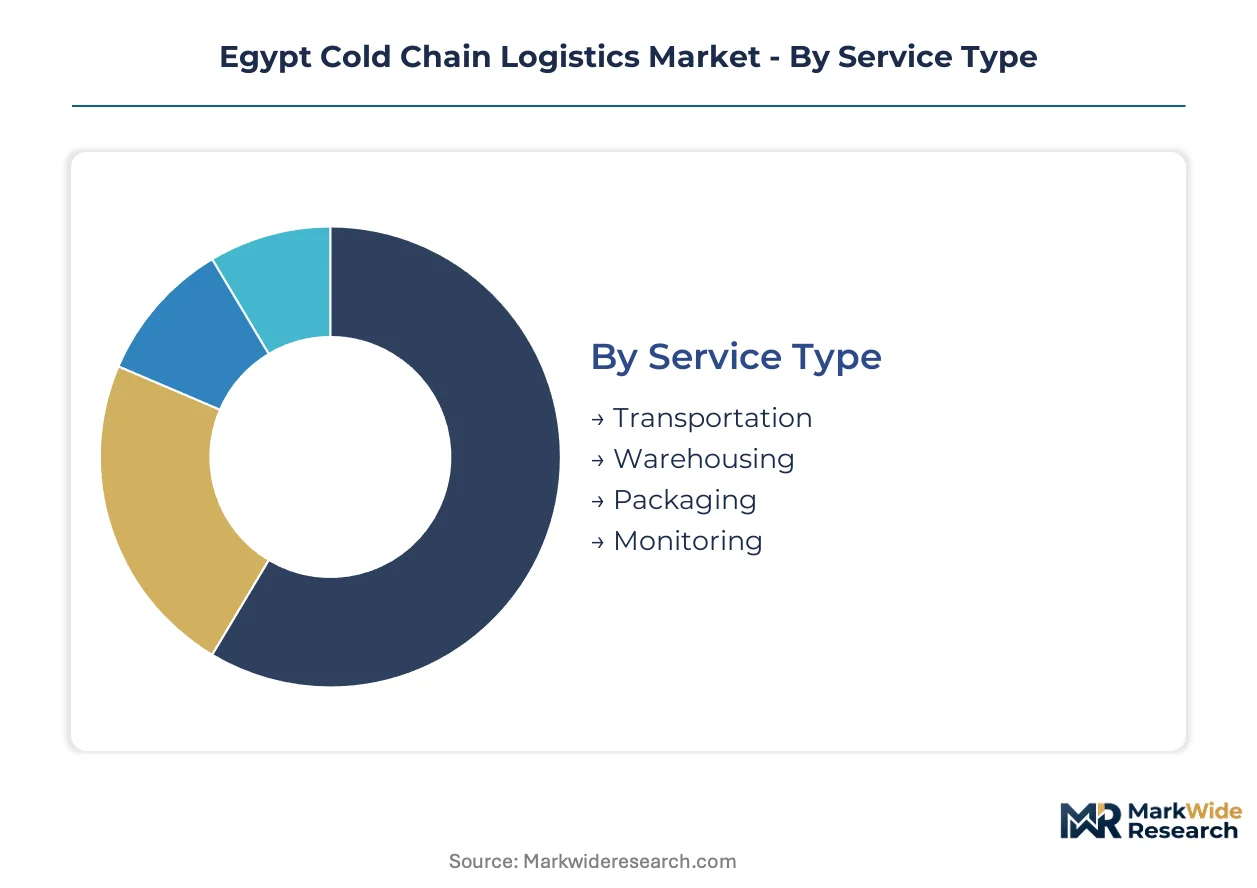
Egypt's cold chain logistics market segments across four functional dimensions that determine capital deployment patterns and margin structures. Each segmentation axis reveals distinct competitive dynamics between bonded warehouse operators, fleet owners, and technology providers serving temperature-sensitive cargo flows.
Service Type:
Cost tier determines competitive intensity and capital barriers across the four service categories.
- Transportation:Refrigerated fleet assets operate across road corridors linking Alexandria Port to Greater Cairo distribution hubs. Nile Delta agricultural belt demand concentrates here, though diesel price volatility compresses margins for independent operators during fuel cost spikes.
- Warehousing:Bonded cold storage facilities near Alexandria Port and Greater Cairo command premium lease rates due to HACCP compliance mandates from Egypt's Food Safety Authority. High capital barriers and long-term lease structures protect incumbent positions.
- Packaging:Insulated containers and temperature-stable materials support pharmaceutical exports to European markets. Demand clusters around vaccine and biologic distribution networks requiring GDP-compliant documentation.
- Monitoring:Real-time temperature tracking systems digitize compliance protocols for Egyptian Drug Authority inspections. IoT sensor deployment is climbing fastest among bonded warehouse operators serving import inspection requirements.
Warehousing holds installed capacity. Monitoring is rotating up the share rankings.
Temperature Range:
Application-specific thermal requirements segment infrastructure investment and operational protocols.
- 1°C to 4°C:Pharmaceutical cold chain corridors maintain this band for vaccine and biologic integrity. Egyptian Drug Authority GDP mandates concentrate demand around validated storage systems in Greater Cairo pharmaceutical distribution hubs.
- -18°C or Below:Frozen food imports and export-oriented seafood processing require deep-freeze infrastructure. Alexandria Port bonded facilities dominate this segment due to proximity to European re-export markets.
- Ambient:Non-refrigerated transport handles dry goods within temperature-controlled facilities. Retail distribution networks use this category for shelf-stable products moving through shared logistics infrastructure.
- Controlled:Variable temperature zones accommodate mixed cargo loads and seasonal adjustments. Agricultural cooperatives in Upper Egypt governorates represent emerging demand for flexible cold storage protocols.
-18°C or Below holds installed capacity. 1°C to 4°C is rotating up the share rankings.
End User:
Customer type determines service level requirements and compliance documentation intensity.
- Pharmaceuticals:Temperature-sensitive biologics and vaccine distribution command premium pricing. Egypt's Egyptian Drug Authority mandates GDP-compliant cold chain documentation, creating non-negotiable certification barriers for logistics providers.
- Food & Beverage:Perishable imports face tightened HACCP compliance mandates from Egypt's Food Safety Authority. Warehouse operators in Alexandria port corridors are retrofitting monitoring infrastructure to avoid license suspension.
- Agriculture:Post-harvest losses in fresh produce value chains drive refrigerated transport demand south of Cairo. Sohag and Qena governorates represent underpenetrated corridors for specialized fleet deployment.
- Retail:Supermarket chains and e-grocery platforms require last-mile temperature integrity. Greater Cairo concentration creates service gaps in peripheral governorates with elevated logistics costs.
Food & Beverage holds installed capacity. Pharmaceuticals is rotating up the share rankings.
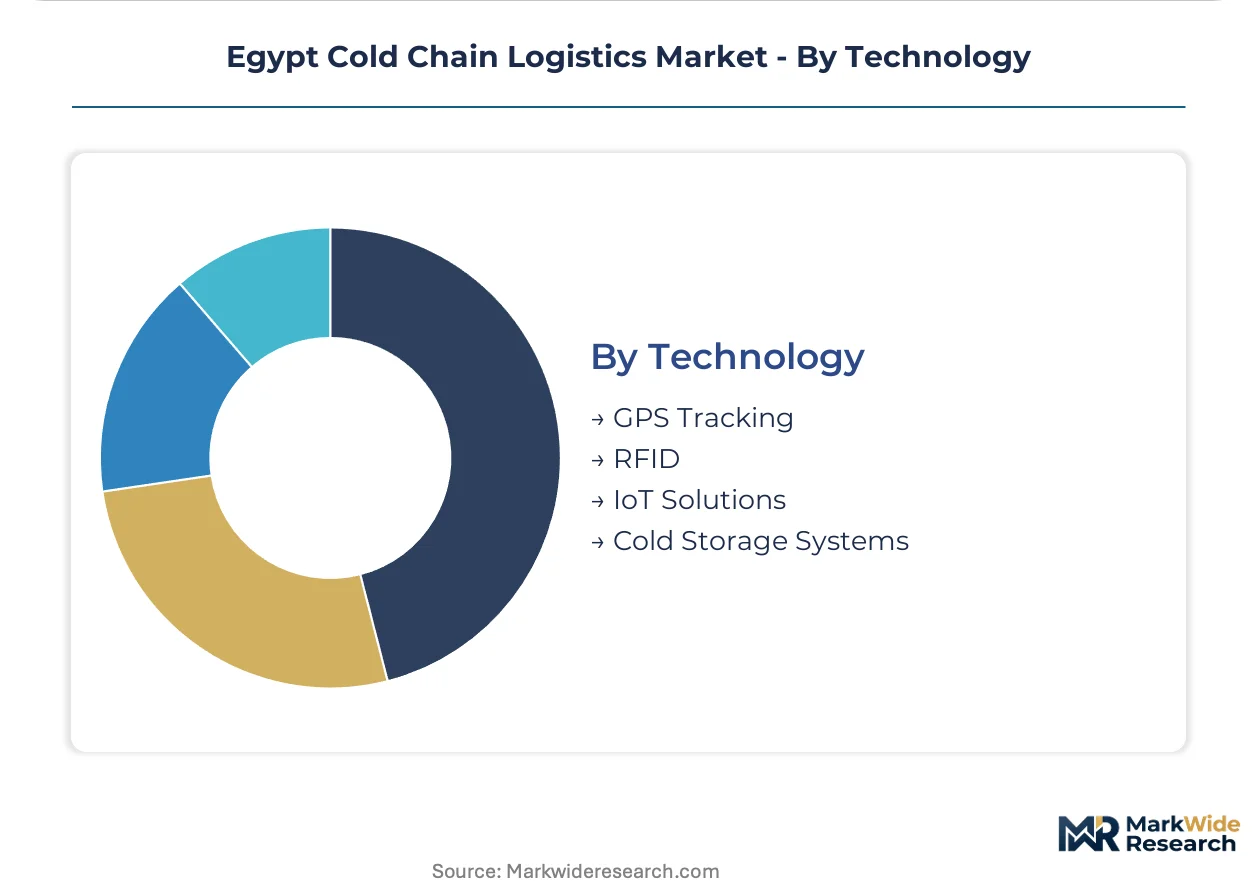
Technology:
Maturity curves and integration complexity segment adoption patterns across four technology categories.
- GPS Tracking:Fleet location monitoring enables route optimization and delivery confirmation. Transport operators across the Nile Delta agricultural belt deploy this as baseline fleet management infrastructure.
- RFID:Automated inventory tracking supports warehouse throughput and lot traceability. Pharmaceutical distributors use RFID for Egyptian Drug Authority inspection readiness and rejection rate reduction at European entry points.
- IoT Solutions:Cellular-enabled temperature loggers provide real-time visibility from container to pallet level. Bonded warehouse operators in Greater Cairo deploy sensor networks to satisfy mandatory HACCP temperature logging requirements.
- Cold Storage Systems:Refrigeration hardware and climate-mapped warehouse zones form the physical infrastructure backbone. Solar-powered integration is emerging among rural agricultural cooperatives seeking grid-independent solutions.
Cold Storage Systems holds installed capacity. IoT Solutions is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's Food Safety Authority mandates are redistributing cold chain investment across governorates, with bonded warehouse upgrades concentrating near Alexandria Port while refrigerated fleet deployment pushes into underpenetrated agricultural corridors south of Cairo.
Greater Cairo
Pharmaceutical distribution hubs dominate temperature-controlled demand as Egyptian Drug Authority GDP compliance concentrates vaccine and biologic storage in certified facilities. IoT sensor networks digitize compliance documentation across bonded warehouses serving import inspection requirements. New Cairo and 6th of October City industrial zones anchor pharmaceutical logistics clustering.
Alexandria Port Corridor
Perishable import volumes drive deep-freeze infrastructure investment along Egypt's Mediterranean gateway. HACCP temperature logging mandates from Egypt's Food Safety Authority force warehouse retrofitting among bonded cold storage operators. Borg El Arab industrial zone hosts expanding refrigerated capacity targeting European re-export markets.
Nile Delta Agricultural Belt
Post-harvest fresh produce losses create refrigerated transport demand across Kafr El Sheikh, Dakahlia, and Gharbia governorates. Diesel price volatility compresses margins for independent fleet operators during fuel cost spikes. Mansoura and Tanta serve as consolidation points for temperature-controlled agricultural exports.
Upper Egypt Governorates
Refrigerated penetration remains limited south of Cairo despite significant fresh produce volumes in Sohag, Qena, and Luxor. Solar-powered cold storage pilots target rural agricultural cooperatives seeking grid-independent solutions. Post-harvest loss reduction programs are accelerating specialized fleet deployment into these corridors.
Suez Canal Economic Zone
Ain Sokhna port expansion creates transhipment cold storage demand for East African and Gulf re-export markets. Temperature-controlled facilities target seafood and pharmaceutical transhipment volumes. Suez Governorate infrastructure investments are attracting integrated logistics providers with captive transport assets.
Egypt Cold Chain Logistics Market Competitive Landscape
On the supply side, the industry is bifurcated between bonded warehouse incumbents with captive fleet assets and fragmented independent transport operators competing on price. Strategic archetypes divide into integrated pharmaceutical logistics providers, port-centric perishable handlers, and agricultural belt fleet specialists. Dominant competitive moves include warehouse certification upgrades for HACCP compliance and solar-powered cold storage pilots targeting rural cooperatives.
Within the integrated logistics tier, Logistics for Storage Services (S.A.E) and Kuehne + Nagel occupy positions exemplifying bonded warehouse dominance near Alexandria Port and multi-modal temperature-controlled corridors respectively. EPx Logistics represents the agricultural belt specialization archetype through Nile Delta fleet deployment. These three entities anchor competitive positioning across Egypt's pharmaceutical import, European export, and domestic agricultural value chains.
| Leading Market Players |
|---|
| Logistics for Storage Services (S.A.E) |
| EPx Logistics |
| Logistica |
| Kuehne + Nagel |
| DHL Supply Chain |
| Multi Fruit Egypt |
| Custom Storage Company (CSC) |
| Aramex |
| CACC Cargolinx |
| Others |
Supply & Pricing Matrix
Diesel price volatility functions as the dominant risk vector determining both pricing tier spreads and supply chain configuration across Egypt's cold chain sector. Transport operators absorb fuel cost swings through contract renegotiation while warehouse incumbents leverage bonded status to command premium lease rates insulated from commodity fluctuations.
Pricing Analysis
Certification level creates the primary spread between GDP-compliant pharmaceutical handlers and standard perishable operators. Three-tier pricing structure across premium, standard, and economy levels reflects Egyptian Drug Authority validation status, warehouse location proximity to Alexandria Port, and captive fleet asset ownership. Cost compression in the independent transport tier is intensifying because diesel price spikes erode margins faster than contract adjustment cycles allow. Agricultural cooperatives in Upper Egypt governorates exhibit highest price sensitivity, while vaccine distributors demonstrate lowest sensitivity due to non-negotiable compliance requirements.
Supply Chain Analysis
Extended payment terms from bonded warehouse operators to refrigerated fleet subcontractors stretch working capital across the Nile Delta agricultural belt. Refrigeration compressor units draw from China and Germany, insulated container materials rest on European suppliers, and IoT sensor hardware hinges on South Korean and Taiwanese manufacturers. Single-source vulnerability concentrates in compressor component sourcing where Egyptian Drug Authority pre-approval limits substitution options. Distribution runs through Alexandria Port consolidation hubs into Greater Cairo pharmaceutical corridors and southbound agricultural collection points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
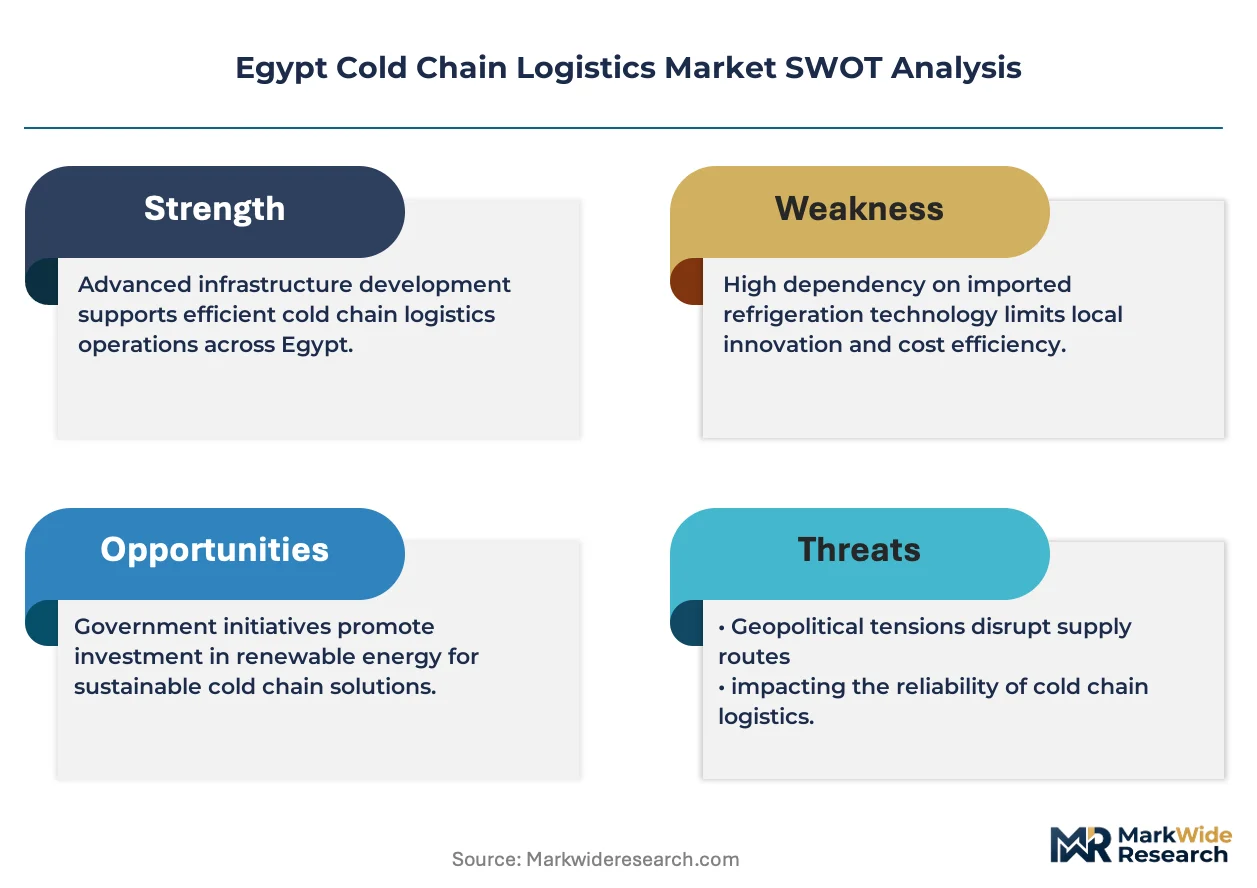
Egypt's cold chain sector presents a defensive-moat story anchored in regulatory entrenchment. Egyptian Drug Authority GDP certification and Food Safety Authority HACCP mandates create switching costs that protect incumbent positions against price-based disruption.
For Market Incumbents: Insulate warehouse network advantages through backward integration into captive refrigerated fleet assets serving pharmaceutical corridors. Certification investment in solar-powered cold storage pilots addresses diesel price volatility while creating differentiation for rural agricultural cooperative contracts. Threat substitution emerges from IoT-enabled monitoring providers offering compliance-as-a-service without physical infrastructure. For New Entrants and Emerging Players: Establish a beachhead in Upper Egypt governorates where refrigerated penetration remains limited and incumbent warehouse networks lack bonded status. Sohag and Qena agricultural collection points represent the most penetrable geography given post-harvest loss reduction program funding and limited specialized fleet deployment. Go-to-market execution should anchor on solar-powered cold storage leasing to rural cooperatives seeking grid-independent solutions. For Investors and Strategic Acquirers: Bonded warehouse operators with dual pharmaceutical and perishable certification represent the priority acquisition archetype given scarcity value in Alexandria Port corridor positioning. Long-term viability across a 5-10 year window rests on regulatory harmonization between Egyptian standards and evolving EU Green Deal emissions protocols. The signal to watch is Egyptian Food Safety Authority expansion of mandatory digital temperature logging to domestic produce distribution, which would force facility upgrades and consolidation among subscale operators.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | Egyptian Drug Authority validation opens vaccine distribution contracts with state procurement networks. |
| Solar-Powered Cold Storage Deployment | Photovoltaic integration reduces diesel dependency for Upper Egypt agricultural cooperatives. |
| IoT Sensor Network Installation | Real-time temperature tracking satisfies HACCP digital logging mandates at Alexandria Port bonded facilities. |
| Captive Fleet Asset Acquisition | Refrigerated vehicle ownership secures pharmaceutical corridor capacity against subcontractor price volatility. |
| Red Sea Port Facility Development | Ain Sokhna temperature-controlled infrastructure targets East African and Gulf re-export transhipment volumes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cold storage facility managers, pharmaceutical distribution executives, refrigerated fleet operators, and agricultural cooperative procurement leads. Secondary validation drew from Egyptian Drug Authority regulatory filings, Food Safety Authority compliance bulletins, customs import data for refrigerated equipment, and Suez Canal Economic Zone development disclosures. Bottom-up capacity assessments across Alexandria Port bonded warehouses and top-down pharmaceutical import volume analysis were triangulated to establish market sizing.
Calibration against historical fleet deployment patterns and warehouse lease rate trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, temperature range, end-user industry, and technology adoption tier alongside geographic corridor penetration rates. CAGRs were derived from installed capacity expansion timelines and regulatory mandate implementation schedules. Forecast inputs incorporated diesel price scenario modeling and EU Green Deal alignment pressure assessments for export-oriented refrigerated transport.
Stress conditions across fuel cost volatility bands, regulatory enforcement intensity levels, and pharmaceutical import growth trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding certification timeline compliance and infrastructure investment continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
FMCG Logistics Market
Transportation & Logistics
Europe Reverse Logistic Market
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Ride-Hailing and Taxi Market
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Customs Brokerage Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Refrigerated Trailer Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Transportation and Security System Market
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
Europe Container Drayage Market
Transportation & Logistics
Cable Car and Ropeways Market
Transportation & Logistics
Hong Kong Customs Brokerage Market