
 Tugger Trains Market | 2026-2036
Tugger Trains Market Size, Share, and Industry Trends Forecast 2026-2036
Tugger Trains Market Analytics
Aftermarket service revenue is reshaping margin distribution across the tugger trains value chain. Jungheinrich AG leverages its dense European service network to capture recurring maintenance contracts. KION Group anchors its position through backward integration into drive-system components. Toyota Material Handling competes by extending its lean-manufacturing consulting alongside hardware sales.
A tugger train consists of a powered towing unit coupled to multiple passive carts, typically operating on fixed routes at speeds up to 25 km/h to move palletized or containerized loads within industrial facilities. Electric drive technology dominates new procurement as lithium-ion battery packs displace lead-acid alternatives, while automated tugger variants gain share in automotive OEM settings where magnetic or vision-guided navigation eliminates driver costs. Warehousing applications show the fastest trajectory among end-use segments as e-commerce fulfillment centers adopt milk-run circuits to compress order-picking cycles.
Germany's KBA enforces type-approval standards for industrial towing vehicles operating on public access roads within plant perimeters. The EU Machinery Directive mandates risk assessments and CE marking for automated tugger systems, effectively raising engineering barriers for non-European suppliers. OSHA in the United States requires operator training certification and pedestrian separation protocols that shape facility layout decisions. Buyers must weigh total-cost-of-ownership models against upfront capital outlays as automation premiums compress payback periods.
Market Dynamics
Automotive OEMs are synchronizing assembly-line material flow through fleet-wide tugger train deployments, compressing replenishment cycles from hours to minutes and forcing warehouse operators to match that velocity or lose supplier status.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for automated tugger systems are accelerating replacement of manually operated fleets in German and French automotive plants.
- Lithium-ion battery chemistry:Energy density improvements and faster charging protocols are eliminating lead-acid infrastructure and extending operational uptime in multi-shift facilities.
- Automotive OEM demand concentration:Volkswagen, BMW, and Mercedes-Benz assembly networks in Stuttgart, Wolfsburg, and Munich are standardizing milk-run circuits, creating template procurement specifications that cascade to tier suppliers.
Market Restraints
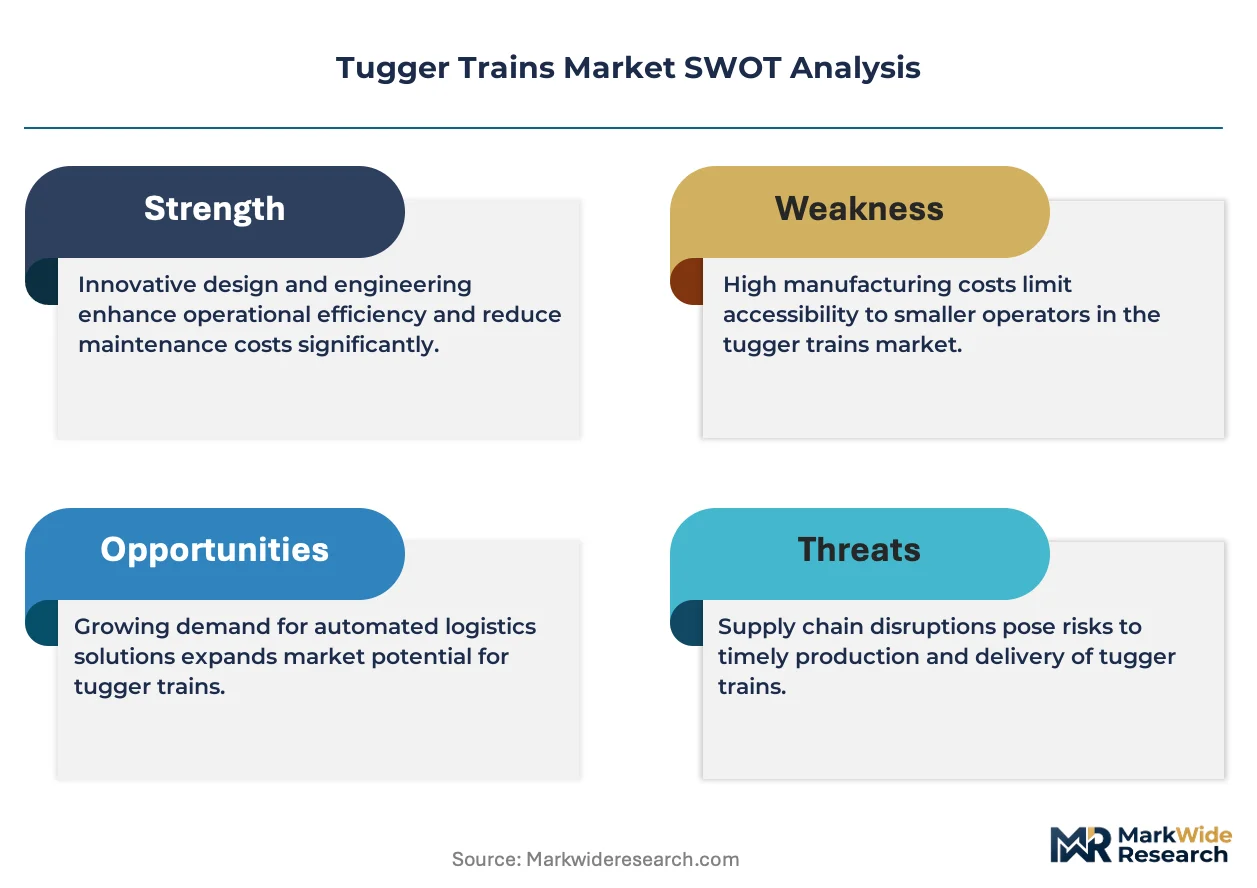
- Drive motor and controller supply concentration:German and Italian electromechanical component suppliers control critical traction system inputs, exposing buyers to 16-24 week lead times during capacity constraints.
- Magnetic tape and vision sensor cost volatility:Rare earth magnet pricing and semiconductor shortages for camera modules are inflating automation premiums on guided tugger variants.
- ISO 3691-4 certification timelines:Safety validation for autonomous operation requires 8-14 months of field testing, delaying revenue recognition for system integrators.
Strategic Opportunities
- E-commerce fulfillment center penetration:Amazon, Zalando, and Otto Group distribution hubs in Poland and Czech Republic remain underpenetrated for milk-run automation.
- EU Green Deal industrial decarbonization incentives:Battery-electric tugger fleets qualify for national subsidy schemes in France, Italy, and Spain that offset 15-30% of capital expenditure.
- 5G private network convergence:Real-time kinematic positioning and fleet management software integration is enabling centimeter-accurate navigation without physical guide path installation.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of automated tugger fleets requires combined mechanical, electrical, and software diagnostics skills that vocational training pipelines have not scaled to match deployment velocity.
- Warehouse Management System integration complexity:Retrofitting legacy WMS architectures to support tugger train task allocation and battery state monitoring demands custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tugger Trains Market |
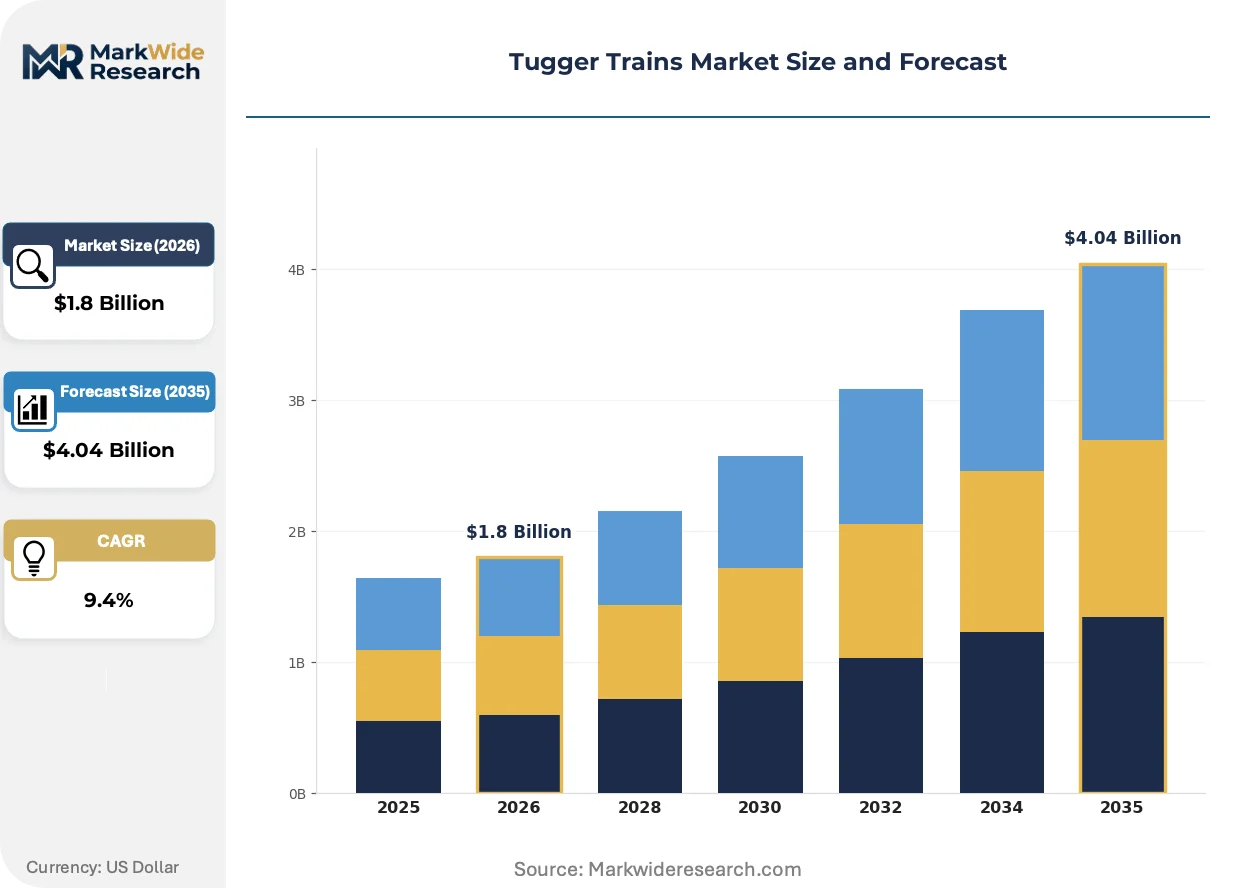
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tugger, Diesel Tugger, Manual Tugger, Automated Tugger Application: Manufacturing, Warehousing, Distribution, Mining End User: Logistics Providers, Retail Chains, Automotive OEMs, E-Commerce Technology: Electric Drive, Hydraulic Systems, Pneumatic Systems, Hybrid Systems |
| Companies Covered | Jungheinrich AG, SSI Schaefer Systems, KION Group, IGZ Logistics, FlexQube, Toyota Material Handling, Linde Material Handling, Crown Equipment Corporation, Hyster-Yale Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tugger Trains Market Evolving Landscape
Navigation architectures and powertrains are undergoing simultaneous transformation as buyers demand plug-and-play automation without infrastructure overhaul. Equipment specifications are converging on modular platforms that accommodate both manual and autonomous operation modes.
Lithium-iron-phosphate battery packs are migrating from niche cold-storage applications to mainstream warehouse deployment due to thermal stability and cycle life advantages. Third-party logistics operators in the Netherlands and Belgium are adopting these chemistries for 24-hour continuous operation. The shift is migrating from lead-acid dominance toward chemistry-agnostic procurement specifications that prioritize total cycle cost over upfront capital.
CE marking under the EU Machinery Directive is tightening validation requirements for collaborative operation zones where automated tuggers share aisles with pedestrian pickers. Manufacturers must now submit comprehensive risk assessments and functional safety documentation before market entry. Automotive assembly plants in Germany and Spain are responding by segregating automated and manual traffic flows through facility redesign.
Leasing and pay-per-use models are displacing outright purchase in mid-capitalization logistics operations. Equipment financiers in France and the United Kingdom are bundling maintenance, software updates, and battery replacement into per-hour rates. This transition is most visible among pharmaceutical distributors where seasonal volume spikes make fixed asset ownership economically inefficient.
Tugger Trains Market Segmentation
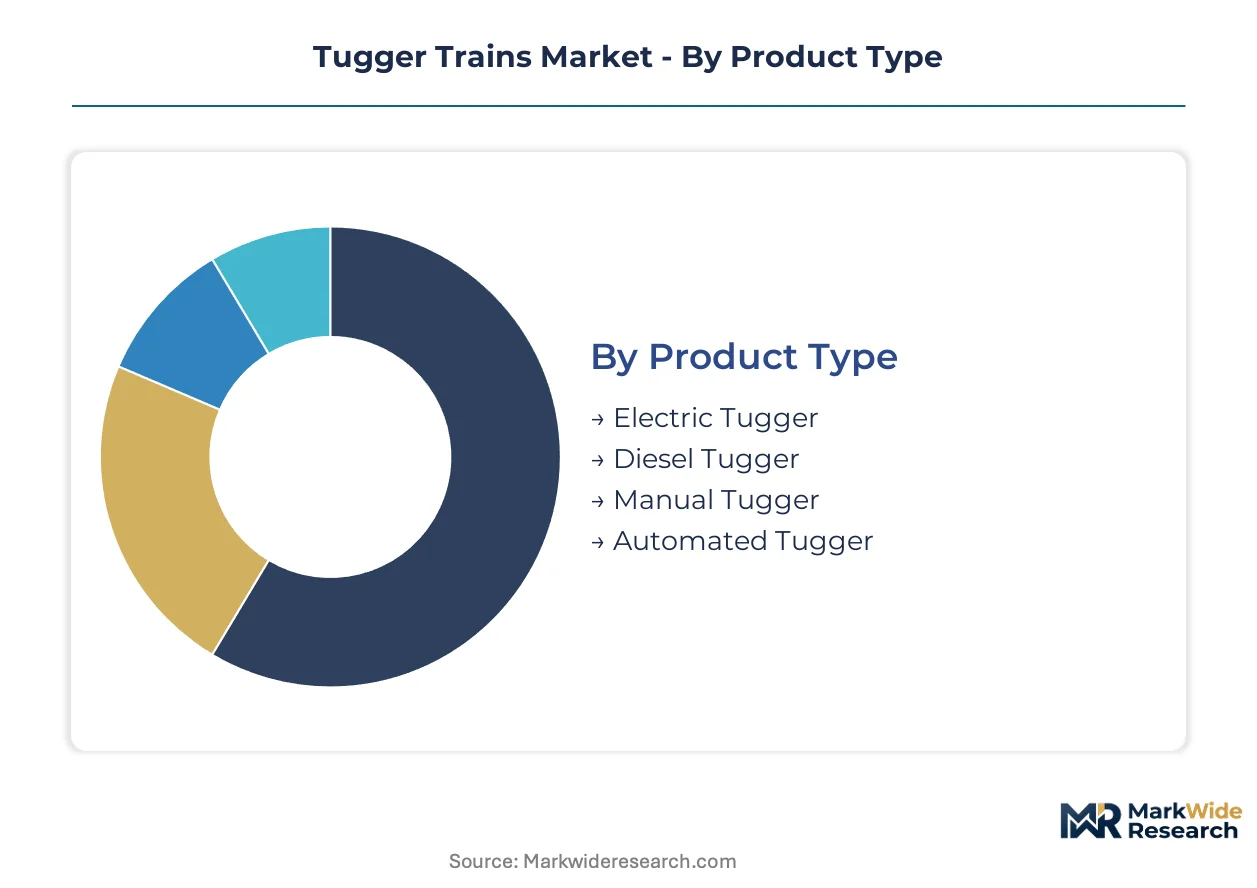
Tugger train procurement patterns diverge sharply across operational contexts, with cycle times ranging from 15-year manufacturing installations to 3-year e-commerce refresh schedules. Understanding these velocity differences enables suppliers to calibrate service attachment rates and inventory positioning.
Product Type:
Cycle times stretch longest for infrastructure-heavy automated systems and shortest for manually operated units that face rapid obsolescence pressures. Procurement velocity directly shapes aftermarket revenue capture and customer lifetime value calculations.
- Electric Tugger:Lithium-ion battery packs power traction motors delivering continuous torque for multi-shift operations. Volkswagen and BMW assembly plants in Stuttgart and Wolfsburg are standardizing these for milk-run circuits, with CE marking under the EU Machinery Directive accelerating fleet replacement timelines.
- Automated Tugger:Magnetic tape or vision-guided navigation eliminates operator costs while requiring 8-14 month ISO 3691-4 certification cycles. Amazon and Zalando fulfillment centers in Poland are deploying these for 24-hour picking operations, though semiconductor shortages for camera modules inflate automation premiums.
- Diesel Tugger:Internal combustion engines persist in outdoor yard operations and mining applications where battery infrastructure is uneconomical.
- Manual Tugger:Unpowered units with ergonomic hitching mechanisms serve intermittent low-volume material flows in small-batch manufacturing.
Electric tuggers dominate installed base. Automated variants are where expansion concentrates.
Application:
Cost tier stratification separates capital-intensive manufacturing deployments from asset-light distribution operations with compressed payback requirements.
- Warehousing:E-commerce fulfillment centers in the Czech Republic and Netherlands adopt milk-run circuits to compress order-picking cycles, with lithium-iron-phosphate batteries enabling continuous operation. Leasing models are displacing purchase here due to seasonal volume spikes.
- Manufacturing:Automotive OEMs synchronize assembly-line material flow through fleet-wide deployments, forcing tier suppliers to match replenishment velocity or lose contract status. KBA type-approval standards govern vehicles operating on public access roads within German plant perimeters.
- Distribution:Pharmaceutical hubs in France and the United Kingdom prioritize per-hour usage rates over ownership to manage demand volatility.
- Mining:Ruggedized diesel units handle bulk material transport in extraction operations with limited electrification infrastructure.
Manufacturing commands the highest capital allocation per site. Warehousing is climbing the fastest.
End User:
Customer type determines specification complexity, with automotive OEMs driving standardization that cascades through supplier tiers.
- Automotive OEMs:Mercedes-Benz, BMW, and Volkswagen networks in Munich and Wolfsburg template procurement specifications that tier suppliers must adopt, creating concentrated demand pools with exacting performance requirements.
- E-Commerce:Amazon and Otto Group distribution hubs require modular platforms accommodating both manual and autonomous modes for peak season flexibility.
- Logistics Providers:Third-party operators in Belgium and the Netherlands adopt chemistry-agnostic procurement prioritizing total cycle cost over upfront capital.
- Retail Chains:Seasonal volume patterns drive preference for bundled maintenance and battery replacement in per-hour rate structures.
Automotive OEMs dominate specification-setting. E-commerce is where deployment velocity is accelerating most sharply.
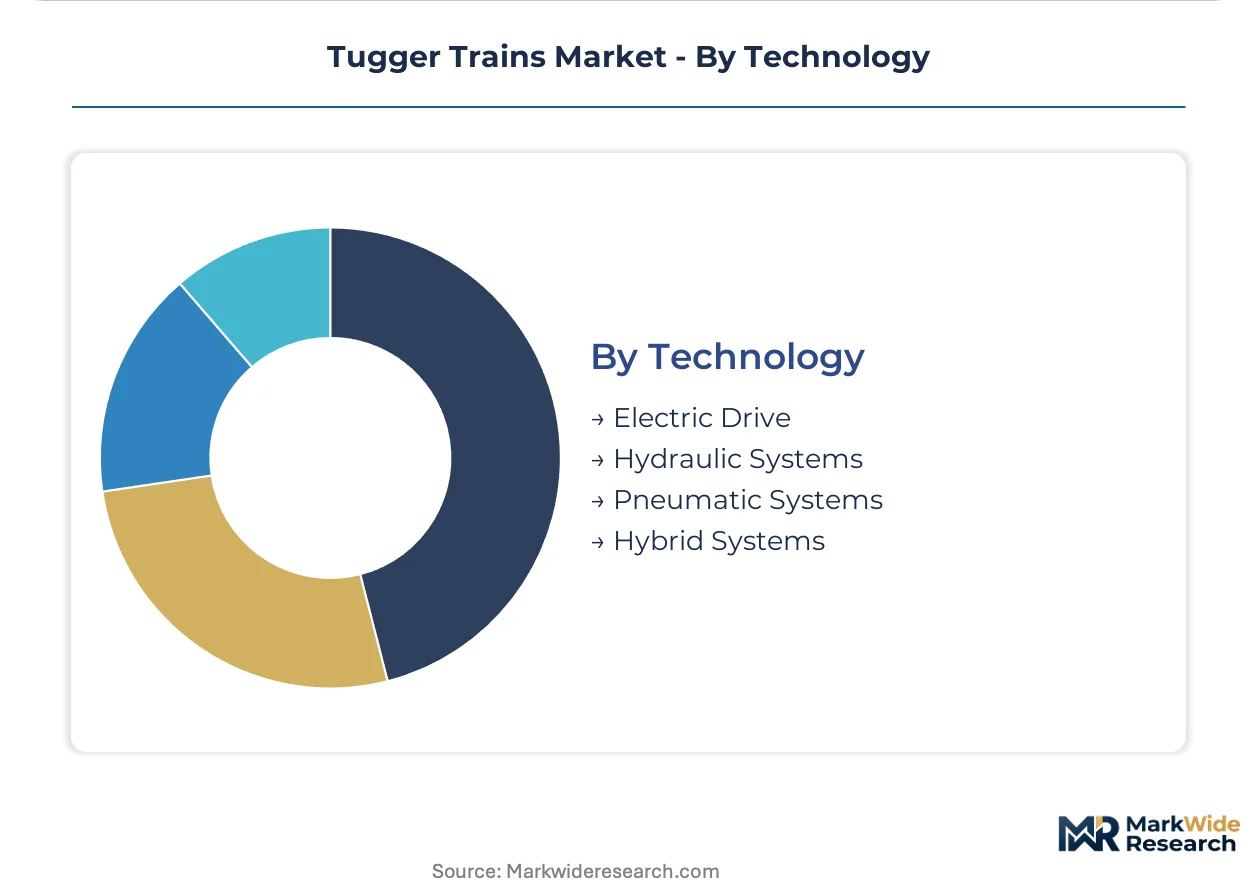
Technology:
Supply concentration in German and Italian electromechanical component suppliers shapes availability and lead time risk across traction system categories.
- Electric Drive:Brushless DC motors with regenerative braking dominate new procurement as lithium-ion displaces lead-acid infrastructure, with 16-24 week lead times on controllers during capacity constraints.
- Hybrid Systems:Dual power architectures combine electric traction with diesel range extension for facilities transitioning toward full electrification.
- Hydraulic Systems:Fluid power persists in heavy-load mining applications requiring precise force control.
- Pneumatic Systems:Compressed air traction serves specialized cleanroom and explosion-risk environments with limited adoption breadth.
Electric drive dominates new order intake. Hybrid architectures are gaining share fastest among facilities with mixed indoor-outdoor operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys tugger trains predominantly for automotive assembly-line synchronization, while the United States concentrates procurement in e-commerce fulfillment centers where seasonal velocity demands modular fleet configurations. China integrates these systems into battery manufacturing plants serving electric vehicle supply chains. Japan emphasizes precision manufacturing applications with exacting navigation tolerances.
Germany
Automotive OEMs in Stuttgart, Wolfsburg, and Munich standardize milk-run circuits that cascade procurement specifications through tier supplier networks. KBA enforces type-approval standards for industrial towing vehicles operating on public access roads within plant perimeters. Jungheinrich AG and KION Group anchor production and aftermarket service networks across Bavaria and Lower Saxony.
United States
E-commerce fulfillment centers in California and Texas adopt leasing models to manage seasonal volume spikes without fixed asset ownership. OSHA requires operator training certification and pedestrian separation protocols that reshape facility layout decisions. Amazon distribution hubs in the Pacific Northwest and Southeast are deploying automated variants for 24-hour picking operations.
China
Battery manufacturing plants in the Yangtze River Delta and Pearl River Delta integrate tugger trains to synchronize cell production lines with pack assembly operations. MIIT industrial equipment standards govern safety certification for automated guided vehicles in manufacturing settings. BYD and CATL supplier parks in Shenzhen and Ningbo are standardizing electric traction specifications.
Japan
Precision electronics manufacturers in Kanto and Kansai regions demand centimeter-accurate navigation for cleanroom material handling applications. METI energy efficiency guidelines incentivize lithium-ion battery adoption over lead-acid alternatives. Toyota production facilities in Aichi Prefecture template lean-manufacturing consulting alongside hardware procurement specifications.
Poland
E-commerce fulfillment centers near Warsaw and Wrocław remain underpenetrated for milk-run automation relative to Western European benchmarks. EU Green Deal industrial decarbonization incentives qualify battery-electric fleets for national subsidy schemes offsetting capital expenditure. Amazon and Zalando distribution hubs in Lower Silesia are accelerating procurement velocity.
Tugger Trains Market Competitive Landscape
Capability concentration sits with electromechanical component specialists; scale advantage sits with diversified material handling conglomerates. The market structure reflects a tiered hierarchy where German and Italian traction system suppliers control critical inputs, while integrated equipment manufacturers capture downstream value through service bundling. Strategic archetypes include backward-integrated drivetrain producers, modular platform specialists, and lean-manufacturing consultants. Dominant competitive moves center on geographic service network density and chemistry-agnostic battery procurement specifications.
Among Germany-based industrial equipment manufacturers, Jungheinrich AG and KION Group exemplify the service-anchored archetype, leveraging dense European aftermarket networks to capture recurring maintenance contracts. Toyota Material Handling occupies a position bridging hardware sales with operational consulting, reflecting Japanese manufacturing methodology transfer. SSI Schaefer Systems represents the warehouse automation integrator tier, situating tugger trains within broader intralogistics system architectures. These three anchors illustrate divergent paths to margin capture without overlapping strategic positioning.
| Leading Market Players |
|---|
| Jungheinrich AG |
| SSI Schaefer Systems |
| KION Group |
| IGZ Logistics |
| FlexQube |
| Toyota Material Handling |
| Linde Material Handling |
| Crown Equipment Corporation |
| Hyster-Yale Group |
| Others |
Value Network & Pricing Analysis
Rare earth magnet pricing volatility in Chinese processing facilities determines both the automation premium spread on vision-guided tugger variants and the geographic sourcing strategies of European system integrators. Buyers face compressed margins when magnetic tape navigation components spike, forcing chemistry-agnostic procurement specifications that prioritize total cycle cost over upfront capital outlays.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive OEMs and established German manufacturers, insulating volume buyers from spot market volatility in lithium-ion battery cells. Three-tier pricing structure across premium automated systems, standard electric traction units, and economy manual configurations reflects ISO 3691-4 certification status and aftermarket service bundling. Cost compression in the manual tier intensifies as Chinese producers expand European distribution, while pharmaceutical distributors exhibit lowest price sensitivity due to per-hour leasing preferences that externalize capital risk.
Supply Chain Analysis
Tariff exposure between China and Germany dominates component sourcing decisions for camera modules and rare earth magnetic sensors used in automated navigation systems. Brushless DC motor controllers concentrate in German and Italian electromechanical facilities, while lithium-iron-phosphate cell production rests on Chinese and South Korean chemical processing capacity. Single-source vulnerability in semiconductor foundry output for vision processing chips forces inventory pre-positioning. Distribution runs through OEM-direct channels for automotive assembly plants and third-party logistics integrators for e-commerce fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates multiple entry points as e-commerce fulfillment velocity demands outpace the standardization capacity of incumbent service networks. Modular platform specialists can capture niches between integrated conglomerates and component suppliers.
For Market Incumbents: Pre-empt margin erosion in manual tugger categories by accelerating backward integration into lithium-iron-phosphate battery pack assembly, securing captive supply against Chinese cell price volatility. Expand service network density in Poland and Czech Republic distribution corridors before regional integrators consolidate maintenance contracts. ISO 3691-4 certification investment represents the critical lever for automated system differentiation. For New Entrants and Emerging Players: Mid-market warehousing operators in Poland and Spain represent the most penetrable entry point, as these geographies remain underpenetrated for milk-run automation relative to German automotive benchmarks. Target third-party logistics providers with seasonal volume spikes using pay-per-use financing structures that incumbent balance sheets cannot match. Partner with 5G private network deployers to offer centimeter-accurate navigation without magnetic tape infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors aftermarket service specialists with dense technician networks over pure equipment manufacturers. Long-term viability hinges on recurring maintenance revenue capture rather than hardware shipment volume. Watch for lithium-ion battery replacement cycle inflection as early-installed fleets age out of warranty coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Captive lithium-iron-phosphate supply secures margin against Chinese cell price volatility for European manufacturers. |
| 5G Private Network Partnership | Centimeter-accurate navigation without physical guide paths reduces infrastructure costs for Polish fulfillment centers. |
| ISO 3691-4 Certification Acceleration | Safety validation documentation opens automotive OEM procurement channels previously blocked to non-European suppliers. |
| Pay-per-Use Financing Launch | Per-hour rate structures attract pharmaceutical distributors with seasonal demand volatility unwilling to own fixed assets. |
| Service Network Expansion | Dense technician coverage in Lower Silesia captures recurring maintenance contracts from Amazon and Zalando distribution hubs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary research phases, including maintenance directors at automotive assembly plants, OEM procurement teams specifying milk-run circuits, aftermarket service heads managing fleet uptime, and warehouse operations managers at e-commerce fulfillment centers. Secondary validation drew from SEC filings of listed material handling conglomerates, KBA type-approval documentation, EU Machinery Directive regulatory databases, and customs records tracking electromechanical component trade flows. Bottom-up equipment shipment estimates triangulated against top-down automotive production line investment data.
Calibration against historical lithium-ion battery cost curves and automation adoption rates in comparable intralogistics equipment informed projection methodology across the analysis window. Segmentation modeling incorporated product type, application context, end-user archetype, and technology platform dimensions. CAGRs derived from equipment replacement cycle analysis and regulatory compliance deadline clustering. Forecast inputs included semiconductor availability assumptions for vision module supply and EU Green Deal subsidy scheme continuation parameters.
Practitioners should monitor rare earth magnet price indices and ISO 3691-4 certification backlog lengths for early signals of automation premium compression or delivery timeline extension. Forecasts reflect assumptions regarding lithium-iron-phosphate thermal stability performance in continuous-operation warehousing environments and 5G private network deployment velocity in Central European logistics corridors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Road-Rail Vehicles Market
Railway
Light Rail Market
Railway
Locomotive Maintenance Market
Railway
Railway Pantograph Market
Railway
Global Train Brake Market
Railway
Railway Bearing Market
Railway
France Rail Freight Transport Market
Railway
Railroad Brake Shoe Market
Railway
Railway Management System Market
Railway
Global Train Lighting Market
Railway
Railway System Market
Railway
Global Train Control and Management Systems Market
Railway
Check Rails Market
Railway
Rail Freight Slot and Path Optimization Platforms Market
Railway
Rail Maintenance Management System Market
Railway
Railroads Market