
 Freight Cars Market | 2026-2036
Freight Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Freight Cars Market Foresight
Software-defined freight car monitoring is restructuring how rail operators procure rolling stock, shifting capital allocation toward sensor-integrated platforms that deliver real-time axle temperature and brake performance data. Trinity Industries leverages its manufacturing scale across multiple car types to sustain long-term supply agreements with Class I railroads. Greenbrier Companies differentiates through international diversification, competing across European and North American specifications with localized production capabilities.
Freight cars are steel-framed rail vehicles designed to haul bulk commodities, intermodal containers, or specialized cargo, typically constructed with high-tensile steel bodies, bogie suspension systems rated for specific axle loads, and coupler mechanisms compliant with AAR or UIC standards. Their primary purpose is to move raw materials and finished goods across long-haul rail networks at lower unit costs than road transport. Tank cars and hopper cars command the most specialized engineering investment, as hazardous material containment and controlled discharge mechanisms create distinct margin pools. Flatcars and gondola cars serve more commoditized construction and intermodal segments where load capacity ratings drive purchasing decisions.
The US DOT Pipeline and Hazardous Materials Safety Administration and Transport Canada jointly enforce tank car integrity standards that mandate thicker shell construction and thermal protection systems, directly shaping replacement demand for legacy fleets. The Association of American Railroads imposes mechanical interchange rules that determine which cars qualify for interchange service, creating a compliance threshold that filters out older equipment. Stakeholders must weigh the capital intensity of next-generation car builds against the regulatory certainty of phased-in mandates that will progressively tighten the eligible operating fleet.
Market Dynamics
Precision-scheduled railroading is compressing fleet utilization rates across North American Class I networks, forcing rail operators to retire aging rolling stock faster than historical replacement cycles while simultaneously demanding higher reliability specifications from new equipment procurements.
Growth Catalysts
- DOT-111 phase-out mandates:US DOT and Transport Canada regulations are accelerating replacement demand for non-compliant tank cars serving crude oil and ethanol corridors.
- Petrochemical corridor expansion:Gulf Coast chemical producers are sustaining orders for specialized pressure cars as ethylene and propylene output scales.
- Sensor-integrated platforms:Real-time axle temperature monitoring is integrating into procurement specifications as a baseline requirement.
Market Restraints
- Steel input volatility:High-tensile steel plate prices fluctuate with scrap metal and energy costs, compressing build margins for car manufacturers.
- Foundry concentration:Cast steel component supply concentrates among a limited set of North American foundries, creating bottleneck risk for bogie assemblies.
- AAR interchange compliance:Mechanical interchange rules filter out older equipment, stranding capital in non-compliant legacy fleets.
Strategic Opportunities
- Canadian oil sands logistics:Underpenetrated heavy crude transport routes offer white space for insulated tank car deployments.
- Battery-electric locomotive pairing:Zero-emission rail yards are creating demand for lighter-weight freight cars that optimize electric traction efficiency.
- Intermodal chassis integration:Double-stack well car designs are converging with automated terminal handling systems at Port of Long Beach and Savannah.
Industry Challenges
- Welding certification backlog:Qualified pressure vessel welders face extended credentialing timelines under ASME Section IX standards.
- Legacy telemetry incompatibility:New sensor platforms require integration with decades-old maintenance management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freight Cars Market |
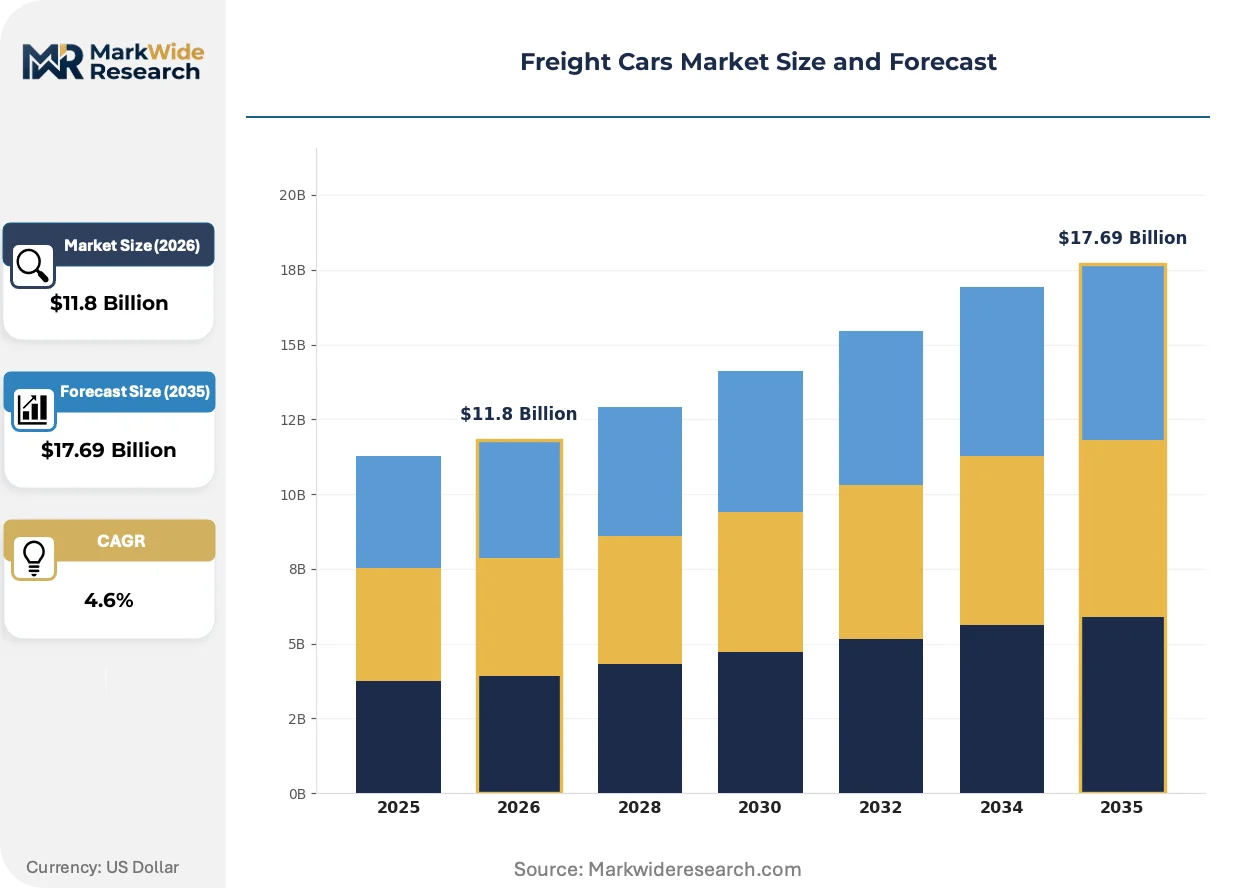
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxcar, Flatcar, Hopper Car, Tank Car, Gondola Car, Refrigerator Car Load Capacity: Light Capacity, Medium Capacity, Heavy Capacity, Ultra-Heavy Capacity Application: Bulk Transport, Container Transport, Liquid Transport, Refrigerated Goods, Automotive Components, Construction Materials Customer Type: Rail Operators, Logistics Providers, Industrial Manufacturers, Agricultural Suppliers, Construction Firms |
| Companies Covered | FreightCar America, Trinity Industries, Greenbrier Companies, Progress Rail, Union Tank Car Company, Titagarh Wagons Ltd., Jupiter Wagons Limited, Amsted Rail Company, Texmaco Rail & Engineering Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freight Cars Market Shifts & Advancements
Freight car engineering is pivoting toward predictive maintenance architectures, with digital twin modeling and edge computing reshaping how operators specify equipment durability and lifecycle cost structures.
Telematics hardware is integrating directly into bogie assemblies, embedding accelerometers and thermal sensors that transmit vibration signatures to centralized fleet management platforms. Class I railroads are mandating these systems on all new tank car orders. This capability is compressing maintenance windows from calendar-based to condition-based intervals.
Transport Canada and US DOT jointly enforce thermal protection standards for tank cars hauling Class 3 flammable liquids, mandating full-height head shields and normalized steel thickness. Rail operators serving Bakken crude routes are retrofitting existing fleets or retiring non-compliant cars ahead of regulatory deadlines. The specialty tank car segment bears the highest compliance capital burden.
Asset-light leasing structures are displacing direct ownership models among short-line railroads and industrial shippers. Third-party lessors now bundle maintenance, regulatory certification, and telemetry subscriptions into per-mile contracts. This shift concentrates procurement authority among a narrowed set of fleet management specialists in the US Midwest and Texas chemical corridors.
Freight Cars Market Segmentation
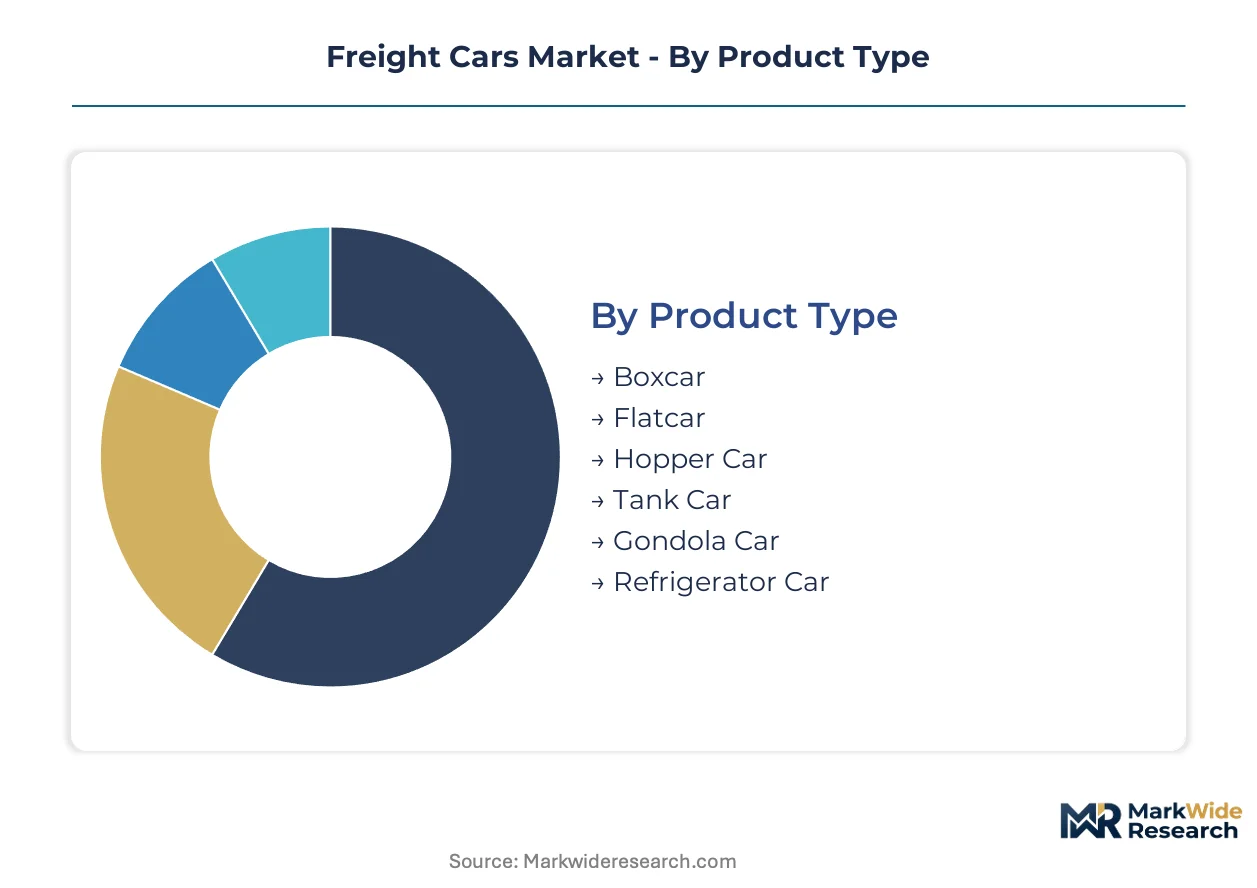
Freight car procurement specifications diverge sharply across cargo categories, with hazardous material containment and temperature-sensitive logistics imposing distinct engineering and certification requirements on manufacturers.
Product Type:
Tank cars and hopper cars carry the heaviest regulatory certification burdens under US DOT and Transport Canada mandates, while flatcars and boxcars face lighter mechanical interchange compliance thresholds.
- Tank Car:Cylindrical pressure vessels with normalized steel shells and thermal protection systems designed for crude oil, ethanol, and chemical transport. Gulf Coast petrochemical corridors sustain demand as ethylene output scales, though DOT-111 phase-out deadlines compress replacement timelines for legacy fleets.
- Hopper Car:Open-top or covered designs with pneumatic or gravity discharge systems for grain, coal, and mineral aggregates. Agricultural suppliers in the US Midwest and Canadian prairies dominate procurement, with precision-scheduled railroading demanding higher reliability specifications for unit train operations.
- Flatcar:Deck-level loading platforms for intermodal containers, construction equipment, and oversized machinery. Port of Long Beach and Savannah terminal automation is reshaping length and payload specifications.
- Gondola Car:Open-topped steel tubs for scrap metal, aggregates, and bulk construction materials. Steel input volatility directly compresses manufacturing margins for this commoditized segment.
- Boxcar:Enclosed rectangular bodies for palletized manufactured goods and paper products. E-commerce logistics providers are reviving interest for final-mile rail distribution.
- Refrigerator Car:Insulated bodies with mechanical refrigeration units for temperature-sensitive produce and pharmaceuticals. California agricultural exporters and Florida citrus shippers anchor niche demand.
Tank cars sit at the top of the volume ranking, with flatcars climbing the fastest as intermodal corridor investments accelerate.
Load Capacity:
Axle load ratings determine bogie assembly specifications and foundry sourcing strategies, with heavier configurations demanding concentrated supply relationships.
- Heavy Capacity:100-ton to 125-ton gross rail load ratings for coal, ore, and bulk mineral unit trains. Powder River Basin coal operators and Canadian oil sands logistics providers specify these configurations for density-optimized transport economics.
- Ultra-Heavy Capacity:130-ton-plus specialty designs for iron ore and heavy crude applications. Australian iron ore miners and Brazilian Vale operations drive limited but high-margin procurement.
- Medium Capacity:70-ton to 90-ton ratings for general merchandise and agricultural flows. Short-line railroads and regional grain cooperatives concentrate demand for this versatile tier.
- Light Capacity:Sub-70-ton legacy specifications for branch-line operations and industrial spurs. Asset-light lessors are retiring these units fastest as AAR interchange rules tighten.
Heavy capacity units dominate revenue concentration, with ultra-heavy capacity gaining share fastest in mining corridor expansions.
Application:
End-use specifications fragment procurement authority across distinct shipper categories with diverging maintenance and telemetry requirements.
- Liquid Transport:Crude-by-rail and chemical corridor movements requiring pressure-rated containment and thermal protection. Bakken crude producers and US Gulf Coast refiners mandate sensor-integrated fleets for real-time monitoring.
- Bulk Transport:Grain, coal, and mineral aggregates moving in dedicated unit trains. Canadian National and Union Pacific agricultural divisions specify high-utilization designs for precision-scheduled operations.
- Container Transport:Double-stack well cars and spine cars for international intermodal. Port of Savannah and Port of Los Angeles automation investments are converging with chassis-integrated designs.
- Refrigerated Goods:Temperature-controlled produce and pharmaceutical movements. Mexico-US cross-border agricultural lanes and Florida citrus exporters anchor specialized demand.
- Automotive Components:Multi-level autoracks and parts boxcars for finished vehicle and supplier logistics. Detroit Three manufacturers and Tesla supply chains specify damage-resistant interior configurations.
- Construction Materials:Gondolas and flatcars for lumber, steel, and precast concrete. Texas and Florida residential construction booms sustain regional fleet deployments.
Bulk transport commands the largest fleet footprint, with liquid transport expanding most quickly on petrochemical corridor investments.
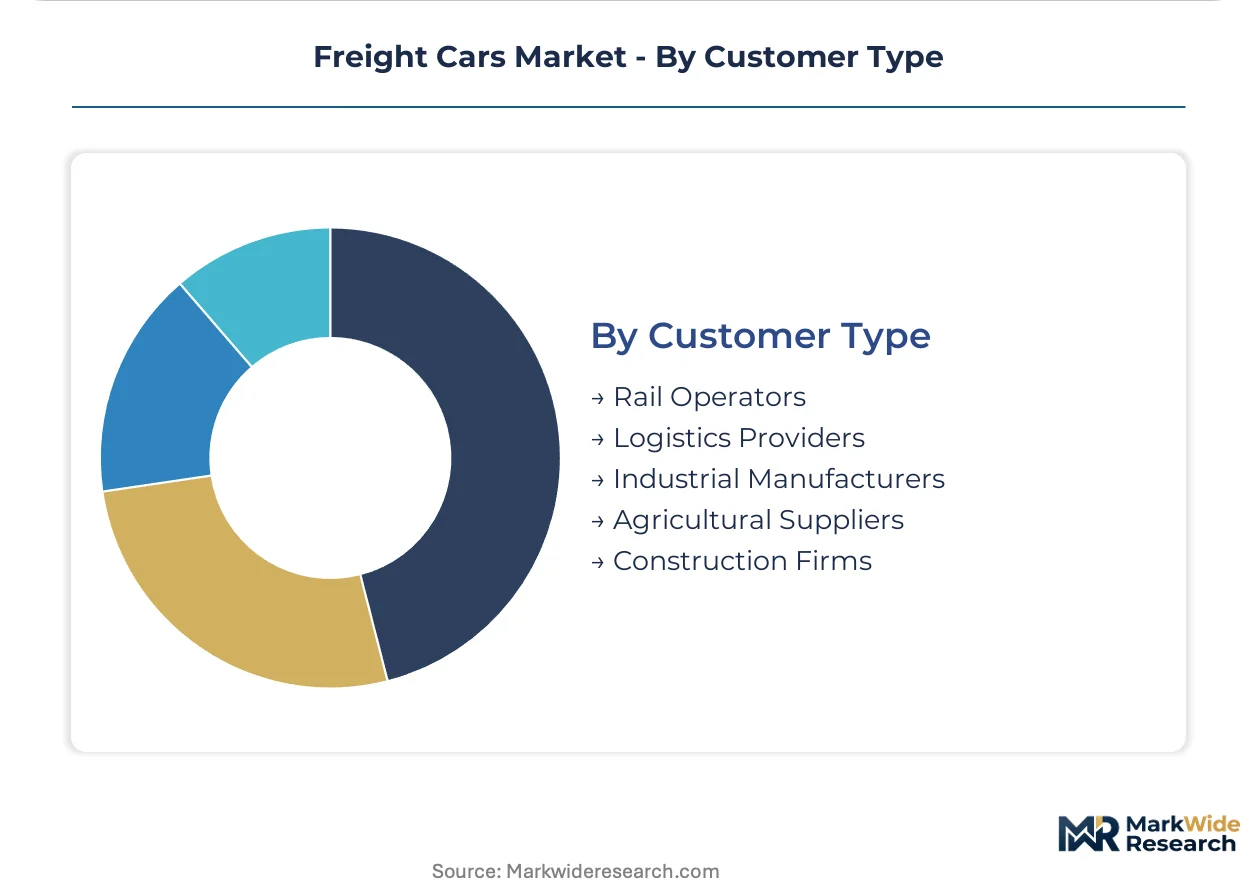
Customer Type:
Procurement authority concentrates differently across direct operators, third-party intermediaries, and industrial asset owners with varying capital deployment strategies.
- Rail Operators:Class I railroads and short lines specifying fleet-wide reliability and telemetry integration. BNSF and CSX are mandating sensor-integrated platforms on all new tank car orders.
- Logistics Providers:Third-party lessors bundling maintenance, certification, and per-mile contracts. Trinity Industries and Greenbrier leasing divisions are displacing direct ownership among Midwest agricultural shippers.
- Industrial Manufacturers:Chemical producers, automakers, and energy companies deploying captive fleets. Dow Chemical and ExxonMobil specify specialized pressure cars for Gulf Coast ethylene logistics.
- Agricultural Suppliers:Grain elevators, cooperatives, and food processors with seasonal utilization patterns. Cargill and ADM procurement concentrates in heavy-capacity hopper configurations.
- Construction Firms:Aggregate producers and building material distributors with project-driven demand. Vulcan Materials and Martin Marietta specify gondola fleets for regional quarry-to-plant movements.
Rail operators retain the deepest fleet ownership, with logistics providers capturing share fastest through integrated leasing structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains heavier freight car replacement cycles than Canada, driven by larger crude-by-rail volumes and more aggressive DOT-111 phase-out deadlines. Mexico's automotive export corridors are generating distinct procurement specifications for finished vehicle logistics. Brazil's iron ore mining expansions are pulling ultra-heavy capacity designs into South American supply chains.
United States
US Gulf Coast petrochemical producers are scaling ethylene output and mandating sensor-integrated pressure car fleets for real-time monitoring. The US DOT Pipeline and Hazardous Materials Safety Administration enforces thermal protection standards that compress replacement timelines for legacy tank cars. Bakken crude producers in North Dakota and Montana are retiring non-compliant DOT-111 fleets ahead of regulatory deadlines.
Canada
Canadian National and Canadian Pacific Kansas City are expanding unit train operations for oil sands heavy crude and prairie grain exports. Transport Canada jointly enforces tank car integrity standards with US regulators, creating synchronized compliance timelines across cross-border corridors. Alberta's oil sands logistics providers are specifying insulated tank car configurations for bitumen transport economics.
Mexico
Automotive manufacturers in Nuevo León and Bajío Region are reviving demand for multi-level autoracks and parts boxcars as nearshoring accelerates. Mexico's Secretariat of Infrastructure, Communications and Transportation oversees rail safety certifications aligned with US and Canadian standards. Lázaro Cárdenas and Manzanillo port expansions are reshaping intermodal chassis specifications for Pacific trade lanes.
Germany
German chemical producers in Ludwigshafen and Leverkusen are procuring specialized pressure cars for intra-European hazardous material flows. The European Union's REACH regulation and German Federal Railway Authority safety standards govern tank car construction and interoperability. Ruhr Valley industrial clusters are retrofitting gondola fleets for scrap metal and construction material logistics.
China
Chinese state rail operators are deploying heavy-capacity hopper cars for coal unit trains serving power generation corridors. The Ministry of Industry and Information Technology sets domestic rail equipment standards that diverge from AAR specifications. Yangtze River Delta manufacturing clusters are producing bogie assemblies for export markets across Southeast Asia.
Freight Cars Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated lessors capturing procurement authority from direct rail operator ownership. The vendor base concentrates among North American fabricators with captive foundry relationships and long-term Class I supply agreements. Three archetypes dominate: diversified rolling stock manufacturers with leasing divisions, regional specialists serving single car types, and component suppliers integrating into bogie and coupler assemblies. Competitive moves center on sensor platform partnerships and maintenance bundling into per-mile contracts.
Among North American-integrated manufacturers, Trinity Industries, Greenbrier Companies, and FreightCar America occupy positions across multiple car type specifications. Trinity Industries exemplifies scale-driven diversification across tank, hopper, and flatcar segments with embedded leasing structures. Greenbrier Companies represents international portfolio breadth with localized production capabilities spanning European and North American regulatory environments. FreightCar America anchors specialty manufacturing for coal and mineral car configurations with concentrated Appalachian and Powder River Basin customer relationships.
| Leading Market Players |
|---|
| FreightCar America |
| Trinity Industries |
| Greenbrier Companies |
| Progress Rail |
| Union Tank Car Company |
| Titagarh Wagons Ltd. |
| Jupiter Wagons Limited |
| Amsted Rail Company |
| Texmaco Rail & Engineering Ltd. |
| Others |
Supply & Pricing Matrix
Pressure vessel welders certified under ASME Section IX standards concentrate in the US Gulf Coast and Great Lakes industrial corridors, with labor-cost differentials between these regions and emerging fabrication centers in Mexico creating pricing-tier spreads across tank car builds.
Pricing Analysis
Capacity additions in Mexico are reshaping price floors for standard gondola and flatcar configurations, compressing margins on commoditized segments while specialty tank car builds retain premium positioning. Three-tier pricing structure across sensor-integrated, baseline-compliant, and legacy-grade specifications separates Class I railroad procurement from short-line and industrial shipper demand. Cost compression in standard hopper configurations is intensifying because Mexican fabricators are capturing share in agricultural car builds. Short-line railroads exhibit the highest price sensitivity, while petrochemical producers deploying captive fleets show minimal elasticity for pressure-rated containment systems.
Supply Chain Analysis
ASME Section IX welding certification creates a supply-side gate that limits qualified fabrication capacity for pressure car builds across North America. High-tensile steel plate draws from integrated mills in the United States, Canada, and South Korea, with bogie castings sourcing from concentrated foundry operations in Ohio, Pennsylvania, and Illinois. Single-source vulnerability in specialty steel alloys introduces disruption risk for thermal protection system builds. Distribution runs through direct Class I railroad procurement offices and third-party lessor fleet management platforms concentrated in Chicago and Houston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The freight car market functions as a stable compounder, with regulatory-mandated fleet replacement cycles providing predictable demand visibility regardless of macroeconomic volatility.
For Market Incumbents: Deploy sensor platform partnerships as the primary defensive lever. Trinity Industries and Greenbrier should deepen captive foundry relationships to secure bogie casting allocation during supply crunches. Accelerate telemetry subscription bundling into per-mile contracts to displace direct ownership models among agricultural shippers and short-line operators. The emergence of Mexican fabrication capacity threatens margin structures in commoditized gondola and flatcar segments. For New Entrants and Emerging Players: Enter via Canadian oil sands logistics corridors, where insulated tank car specifications for bitumen transport remain underpenetrated by established lessors. Target Midwest grain elevator cooperatives with asset-light leasing structures that bundle maintenance and regulatory certification. Pursue partnerships with Class II and Class III railroads bypassed by national fleet management platforms. For Investors and Strategic Acquirers: Chemical producers with captive fleet operations are the most active acquirer in this space, consolidating specialized pressure car lessors to secure ethylene and propylene transport capacity. Long-term viability rests on regulatory tailwinds from DOT-111 phase-out mandates and Transport Canada thermal protection standards. Monitor Transport Canada and US DOT joint rulemaking announcements as the critical signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Platform Integration | Class I railroads now mandate real-time axle temperature monitoring on all new tank car procurements. |
| Foundry Capacity Expansion | Bogie casting supply concentrates among Ohio and Pennsylvania operations, creating bottleneck risk during demand surges. |
| Asset-Light Leasing Structures | Third-party lessors bundle maintenance and telemetry subscriptions, displacing direct ownership among agricultural shippers. |
| Cross-Border Certification Alignment | Transport Canada and US DOT joint standards synchronize replacement timelines across Bakken crude and Gulf Coast chemical corridors. |
| Specialized Pressure Car Builds | Ethylene output scaling along the US Gulf Coast sustains demand for thermal-protected containment systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged rail equipment procurement officers at BNSF, CSX, Canadian National, and Union Pacific; fleet management executives at Trinity Industries and Greenbrier leasing divisions; plant managers at Ohio and Pennsylvania foundry operations; and agricultural shipper logistics directors at Cargill and ADM. Secondary validation drew from AAR mechanical interchange rule filings, US DOT PHMSA tank car safety mandates, Transport Canada regulatory notices, SEC 10-K disclosures from publicly traded manufacturers, and customs trade data on steel plate imports. Bottom-up car-type demand modeling and top-down fleet replacement cycle analysis were triangulated against precision-scheduled railroading utilization targets.
Segment-weighting approaches distributed volume and value projections across tank car, hopper car, flatcar, gondola car, boxcar, and refrigerator car categories, with load capacity tiers and customer type splits layered beneath. Application segmentation captured liquid transport, bulk transport, container transport, refrigerated goods, automotive components, and construction materials demand. CAGRs were derived from regression analysis of historical fleet data against regulatory deadline schedules and petrochemical capacity expansion timelines. Forecast inputs incorporated steel price volatility indices and welding certification backlog durations.
Inputs from AAR interchange statistics and DOT PHMSA compliance databases were available through the study window; gaps in short-line railroad fleet age distributions introduce uncertainty bands around replacement timing estimates. Forecasts reflect assumptions regarding regulatory adherence schedules and Class I capital expenditure commitments. A model refresh is warranted upon material change in DOT-111 phase-out enforcement timelines or Transport Canada thermal protection rule amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
France Connected Rail Market
Railway
Rolling Stocks Market
Railway
Global Hyperloop Train Market
Railway
Trams Market
Railway
Train Exterior Lighting Market
Railway
Rail Damper Market
Railway
South Korea Connected Rail Market
Railway
Locomotive Radiator Fan Market
Railway
Train Bogie Market
Railway
Railway Bearing Market
Railway
Global Train Brake Market
Railway
Locomotive Maintenance Market
Railway
Automatic Train Control Market
Railway
Solar Powered Train Market
Railway
Rail Composites Market
Railway
40-Foot Platform Wagons Market