
 North America Automotive AHSS Market | 2026-2036
North America Automotive AHSS Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive AHSS Market Analytics
The direct mill-to-stamp plant channel is fragmenting as OEMs diversify supply sources across the Great Lakes and Gulf Coast. ArcelorMittal NA leverages its Indiana Harbor capacity to anchor hot-rolled coil supply for Detroit-area vehicle programs. United States Steel Corporation competes through its Big River Steel mini-mill, which sustains cost advantages in electric-arc furnace production. Nucor Corporation differentiates by controlling scrap-to-sheet verticality across its southeastern bar-mill network.
Automotive advanced high-strength steel encompasses grades with tensile strength exceeding 590 MPa, produced via controlled thermomechanical processing and microalloying with niobium or titanium to achieve martensitic and bainitic microstructures. Hot stamped components dominate structural applications where ultimate tensile strength surpasses 1500 MPa, while tailored blanks capture margin pools by enabling variable-thickness single-piece designs that reduce weld count. Press hardening technology leads capital deployment among OEM in-house stamping operations, whereas laser cutting grows fastest in Tier-1 job shops serving low-volume electric vehicle platforms.
NHTSA Federal Motor Vehicle Safety Standards and EPA Corporate Average Fuel Economy rules jointly elevate AHSS penetration by mandating simultaneous mass reduction and crash-performance improvement. The EPA's revised light-duty greenhouse gas emissions targets and OSHA foundry exposure limits add compliance layers that favor integrated producers with environmental controls. Stakeholders must monitor how the SEC's climate disclosure requirements reshape capital allocation toward lower-carbon steelmaking routes before committing to long-term supply agreements.
Market Dynamics
Press hardening technology is consolidating OEM capital allocation across the Great Lakes corridor, compressing supplier lead times while NHTSA crashworthiness mandates force simultaneous lightweighting and structural reinforcement.
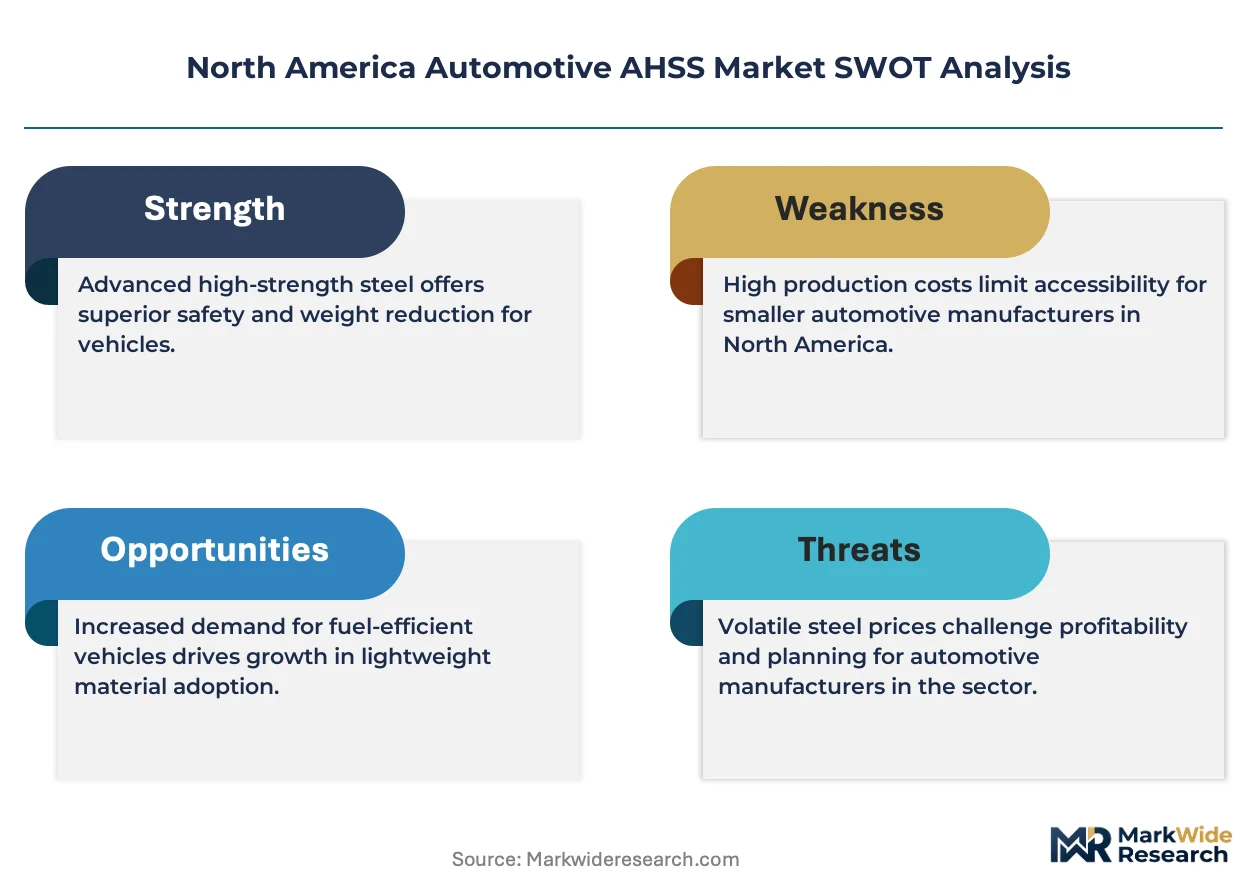
Growth Catalysts
- EPA CAFE Standards:Tightening Corporate Average Fuel Economy targets compel automakers to substitute conventional steel with AHSS grades for mass reduction without sacrificing occupant protection.
- Hot Stamping Technology:Controlled thermomechanical processing enables martensitic microstructures exceeding 1500 MPa tensile strength, unlocking structural applications previously reserved for aluminum or composites.
- Great Lakes Manufacturing Cluster:Concentrated stamping capacity between Detroit, Windsor, and Cleveland creates dense supplier networks that reduce logistics costs for just-in-sequence delivery.
Market Restraints
- Scrap Price Volatility:Electric-arc furnace producers face input cost instability from ferrous scrap markets, compressing margin predictability for mini-mill operators serving automotive contracts.
- Single-Source Tooling Risk:Hot stamping die fabrication concentrates among specialized tool-and-die shops in Ontario and Michigan, creating supply bottlenecks during program ramp-ups.
- Aluminum Substitution Threat:Cast aluminum battery enclosures and extruded crash structures capture share in electric vehicle platforms above 400 km range targets.
Strategic Opportunities
- Gulf Coast Capacity Expansion:Underdeveloped AHSS finishing capacity along the Texas-Louisiana corridor offers greenfield sites for producers seeking proximity to Mexican assembly plants.
- Tailored Blank Integration:Laser-welded variable-thickness sheets enable single-piece designs that eliminate weld joints, capturing margin pools in premium electric vehicle architectures.
- IRA Clean Manufacturing Credits:Section 45X advanced manufacturing production credits incentivize domestic hot-rolled coil capacity additions with embedded carbon intensity below regional baselines.
Industry Challenges
- Press Hardening Technician Shortage:Specialized furnace operators and die maintenance engineers remain scarce across the Midwest, constraining OEM in-house stamping expansion timelines.
- Microalloying Certification Delays:Niobium and titanium grade qualifications with NHTSA for new vehicle programs extend 18-24 months, freezing supplier switching costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive AHSS Market |
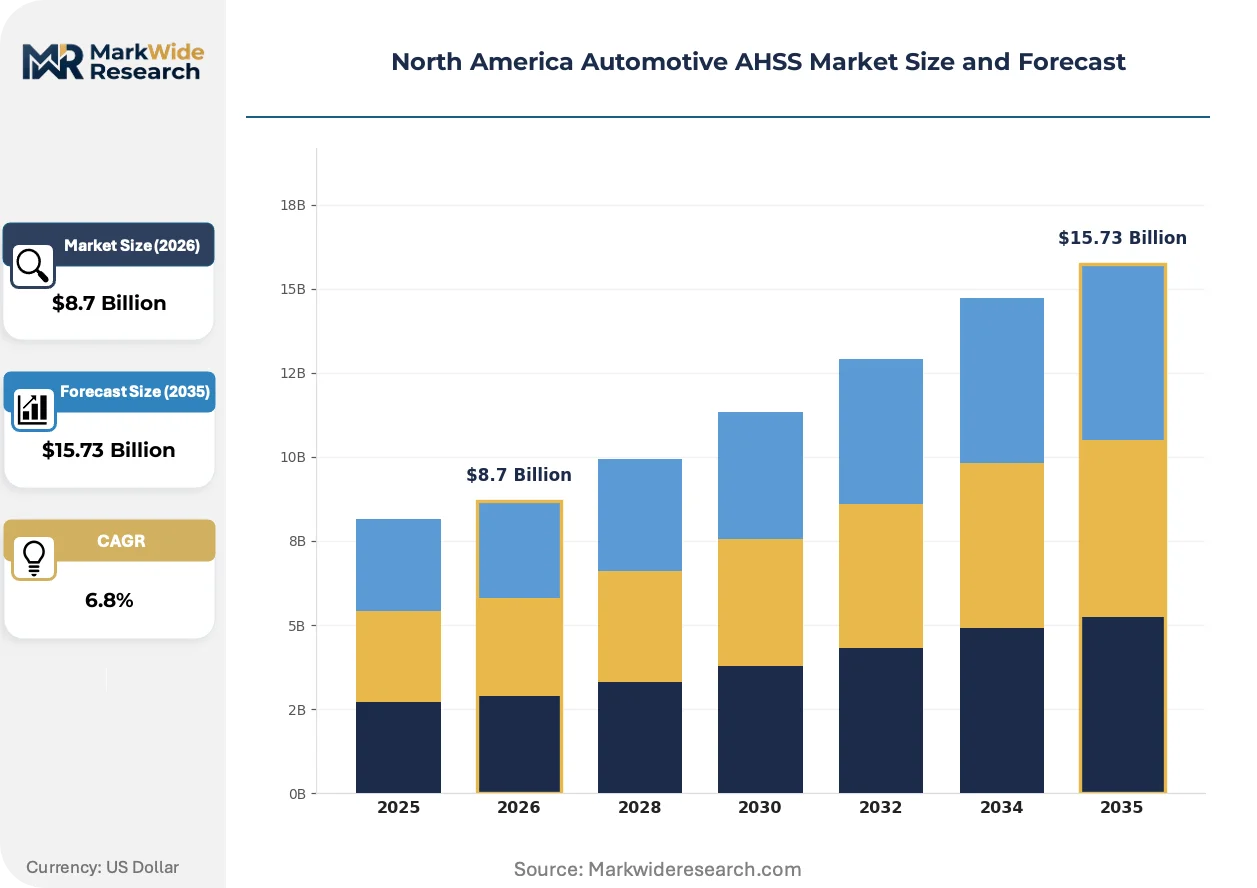
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Stamped, Cold Rolled, Galvanized, Tailored Blank End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Technology: Press Hardening, Laser Cutting, Welding, Forming Application: Body Structure, Chassis, Safety Components, Crash Management |
| Companies Covered | ArcelorMittal NA, United States Steel Corporation, Nucor Corporation, Cleveland-Cliffs Inc., SSAB AB, AK Steel, Thyssenkrupp, TATA Steel, POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive AHSS Market Evolving Landscape
Digital twin simulation and closed-loop process control are compressing development cycles for new AHSS grades while regulatory pressure accelerates capital deployment toward lower-carbon production routes.
Third-generation AHSS grades with improved formability-to-strength ratios are rendering obsolete first-generation dual-phase steels in structural reinforcement applications. Electric vehicle OEMs in Michigan and Ontario are adopting these grades at program-launch pace for battery enclosure rails and cross-car beams. The shift is compressing supplier qualification timelines from 36 months toward 18 months as virtual forming simulation replaces physical die trials.
NHTSA Federal Motor Vehicle Safety Standard 214 side-impact requirements are tightening intrusion limits for passenger compartments, forcing AHSS penetration into B-pillar and rocker panel assemblies previously specified with mild steel. The industrial consequence is elevated capital intensity for Tier-1 stampers serving Detroit Three programs. Ohio and Indiana-based job shops are responding by adding in-house hot stamping lines rather than outsourcing to integrated mills.
Automotive procurement teams are consolidating AHSS suppliers to capture volume-scale pricing while demanding embedded carbon disclosures aligned with SEC climate disclosure rules. Tier-1 stampers serving low-volume electric vehicle platforms are displacing traditional mill-direct contracts with toll-processing arrangements at regional service centers. The reconfiguration is most visible in the Cleveland-Toledo corridor where independent processors now finish coil from multiple melt sources.
North America Automotive AHSS Market Segmentation
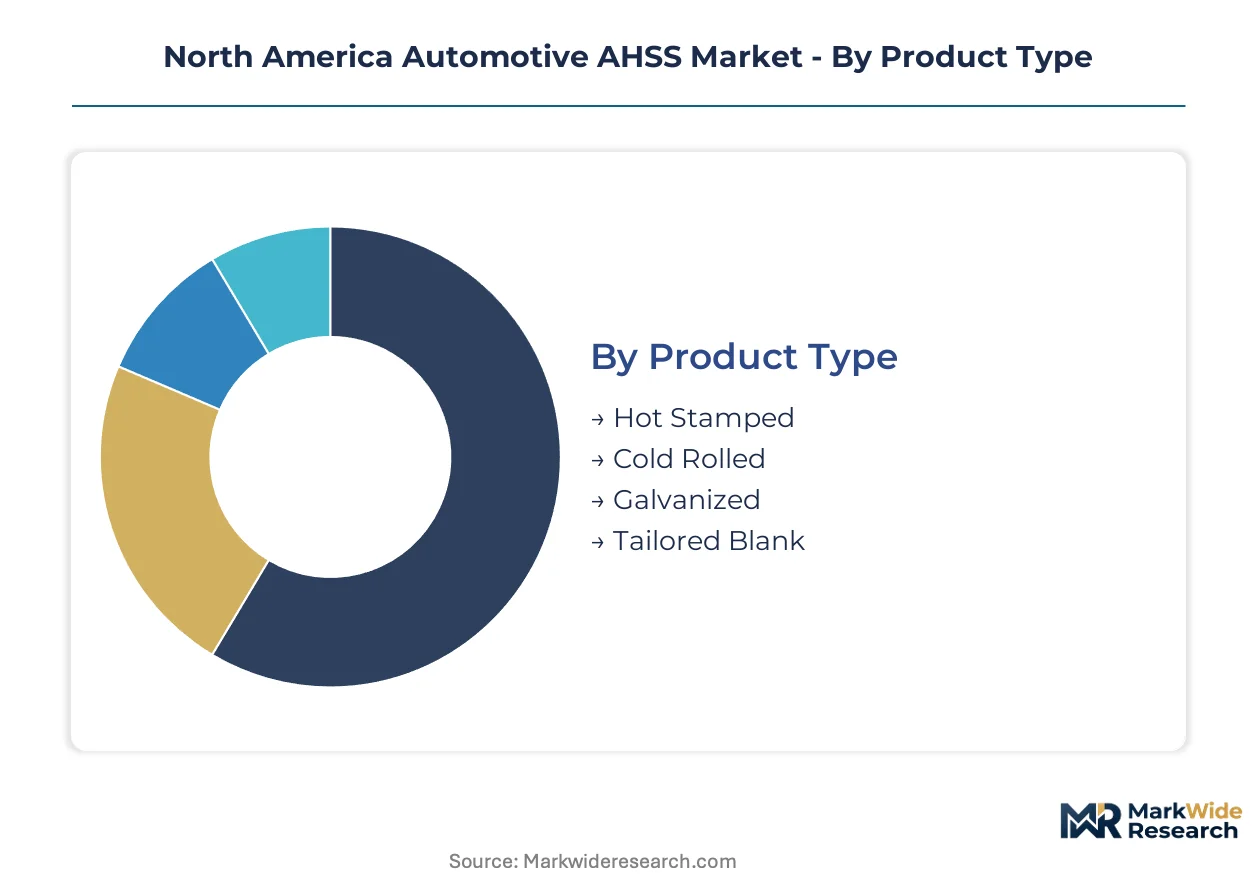
North American automakers source AHSS through distinct procurement channels that reflect capital intensity, technical certification requirements, and just-in-sequence logistics constraints. Understanding these segment boundaries clarifies where margin pools concentrate and where supplier switching costs create defensive positions.
Product Type:
Cost tier differentiation across AHSS product categories separates premium thermomechanically processed grades from commodity cold-rolled alternatives, with galvanization and blank tailoring commanding price premiums for corrosion-critical and complex-form applications.
- Hot Stamped:Controlled austenitization followed by die quenching produces martensitic microstructures exceeding 1500 MPa ultimate tensile strength. Demand concentrates in Detroit-area structural programs where NHTSA side-impact mandates force B-pillar reinforcement upgrades.
- Tailored Blank:Laser-welded variable-thickness sheets enable single-piece designs that eliminate redundant weld joints and reduce assembly labor. Michigan and Ontario electric vehicle platforms are adopting these for battery enclosure rails where mass reduction targets intersect with crash-performance requirements.
- Cold Rolled:Conventional low-carbon grades serve non-structural panels and closure components where formability exceeds strength requirements.
- Galvanized:Zinc-coated substrates protect against corrosion in rocker panels and underbody assemblies exposed to road salt and moisture intrusion.
Hot stamped capacity holds installed dominance across the Great Lakes corridor. Tailored blank processing is rotating up the share rankings as electric vehicle architectures proliferate.
End User:
Customer type determines contract structure, with direct OEM relationships demanding embedded carbon disclosures and Tier-1 suppliers capturing toll-processing margins through regional service center networks.
- OEMs:Integrated stamping divisions at Detroit Three and emerging electric vehicle manufacturers control press hardening lines in-house, sourcing coil directly from Indiana Harbor and Big River melt sources.
- Tier-1 Suppliers:Independent stampers serving low-volume platforms rely on toll-processing arrangements at Cleveland-Toledo corridor service centers, displacing traditional mill-direct contracts.
- Aftermarket Providers:Collision repair networks source certified replacement panels through authorized distributors with NHTSA compliance documentation.
- Dealerships:Retail channels capture marginal volume in accessory and cosmetic upgrade applications with minimal AHSS content.
OEM in-house operations hold installed capacity. Tier-1 toll-processing networks are rotating up the share rankings as procurement teams diversify supply sources.
Technology:
Process technology segmentation tracks capital deployment intensity, with press hardening absorbing the majority of new equipment investment while laser cutting expands fastest in job shop environments serving electric vehicle startups.
- Press Hardening:Heated blank transfer into water-cooled dies achieves fully martensitic transformation within seconds, enabling complex geometries at strength levels previously requiring aluminum or composite substitution.
- Laser Cutting:Fiber laser systems enable rapid prototyping and low-volume production without hard tooling investment, concentrating in Ontario and Michigan shops serving pre-production electric vehicle builds.
- Welding:Resistance and laser welding methods join AHSS components with controlled heat-affected zone properties to preserve base metal strength.
- Forming:Conventional stamping with advanced die materials and lubrication systems handles dual-phase and transformation-induced plasticity grades below 1000 MPa.
Press hardening holds installed capacity. Laser cutting services are rotating up the share rankings as electric vehicle platform diversity stretches tooling amortization timelines.
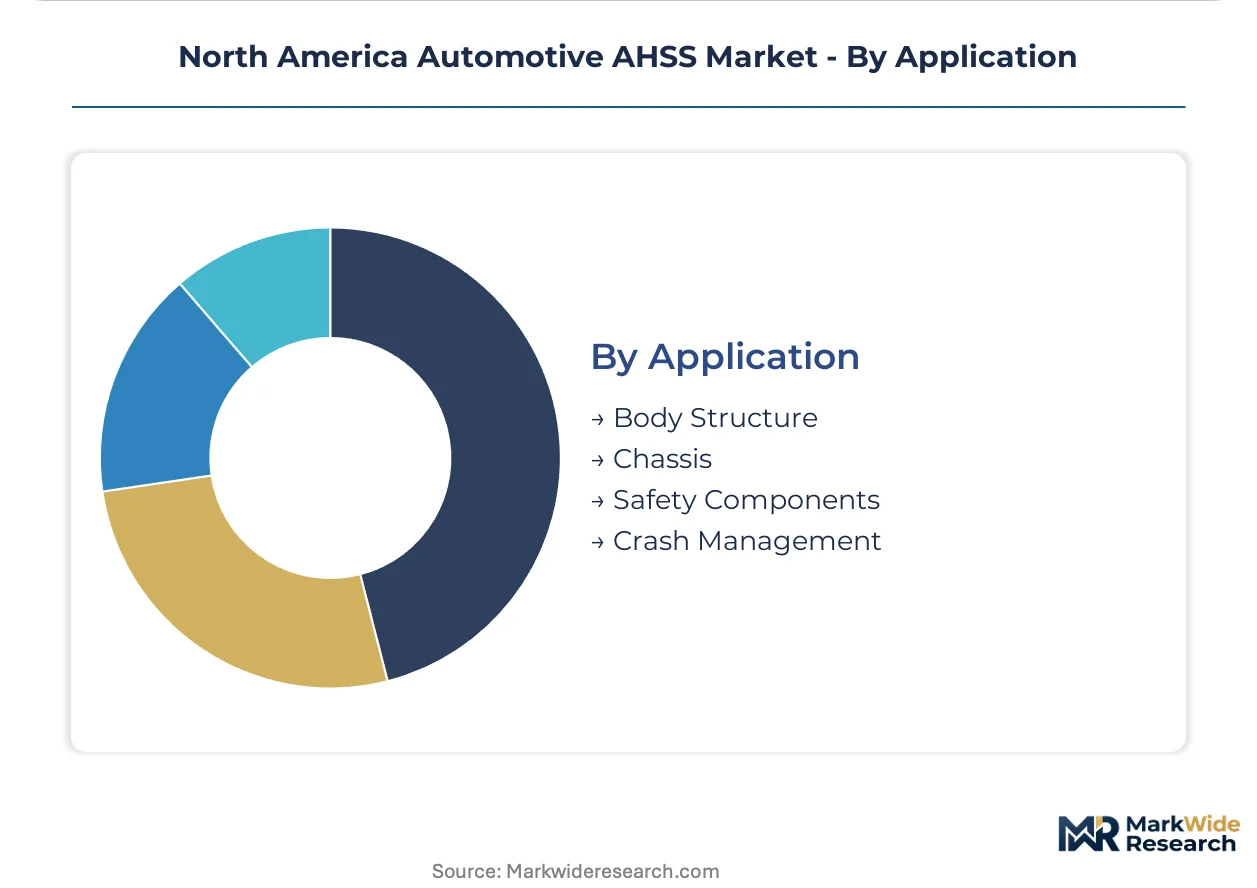
Application:
End-use application segmentation reveals where regulatory pressure translates directly into material specification upgrades, with safety-critical structures commanding premium grades and chassis components balancing strength against formability.
- Safety Components:B-pillars, roof rails, and door beams specified to NHTSA Federal Motor Vehicle Safety Standard 214 intrusion limits require 1500 MPa hot stamped grades with optimized energy absorption characteristics.
- Body Structure:Uniside and floor pan assemblies integrate multiple AHSS grades through tailored blank designs that place high-strength material only where load paths demand.
- Crash Management:Front and rear crush structures employ controlled-collapse geometries with gradient strength properties to manage deceleration pulses.
- Chassis:Suspension mounting points and subframe components balance weldability and fatigue resistance against package space constraints.
Safety component stamping holds installed capacity. Body structure tailored blank integration is rotating up the share rankings as platform architects pursue single-piece designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Great Lakes corridor while Gulf Coast producers absorb logistics penalties serving Mexican assembly plants. The asymmetry reflects integrated mill proximity to Detroit stamping operations versus mini-mill distance from border manufacturing.
United States
EPA CAFE standards and NHTSA crashworthiness mandates drive AHSS specification upgrades across Detroit Three vehicle programs. The Inflation Reduction Act's Section 45X credits incentivize domestic hot-rolled coil capacity with embedded carbon below regional baselines. Indiana Harbor and Big River Steel anchor supply networks feeding Michigan and Ohio stamping clusters.
Canada
Ontario electric vehicle OEMs expand AHSS adoption for lightweight battery enclosures and structural reinforcement. Health Canada and Transport Canada align vehicle safety regulations with NHTSA standards, streamlining cross-border component certification. Windsor and Toronto corridor stamping plants source coil through toll-processing arrangements at regional service centers.
Mexico
Assembly plant expansion in Nuevo León and Bajío Region attracts AHSS demand from platform localization mandates. Mexican automotive regulations under NOM standards incorporate UN ECE crash-test protocols, elevating material performance requirements. Northern border states concentrate Tier-1 stamping operations serving US-bound vehicle exports.
North America Automotive AHSS Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in coil supply and toll-finishing. The North America Automotive AHSS Market structures around three archetypes: integrated steel mills with captive hot-rolling capacity, mini-mill operators exploiting electric-arc furnace cost advantages, and regional service centers capturing toll-processing margins. Consolidation pressures concentrate among coil suppliers while fragmentation persists in specialized die fabrication and laser cutting services. Dominant competitive moves include backward integration into scrap supply and strategic partnerships for press hardening technology access.
Among integrated mill operators, ArcelorMittal NA and United States Steel Corporation exemplify the scale-driven archetype with anchored Great Lakes production assets. Nucor Corporation occupies a position within the mini-mill tier, leveraging electric-arc furnace verticality across southeastern operations. These three entities represent the primary coil supply anchors serving Detroit-area OEM stamping programs and Tier-1 toll-processing networks.
| Leading Market Players |
|---|
| ArcelorMittal NA |
| United States Steel Corporation |
| Nucor Corporation |
| Cleveland-Cliffs Inc. |
| SSAB AB |
| AK Steel |
| Thyssenkrupp |
| TATA Steel |
| POSCO |
| Others |
Value Network & Pricing Analysis
Tariff exposure on Canadian and Mexican coil imports determines both the spread between contract and spot pricing tiers and the geographic reshaping of melt-to-stamp logistics across the Great Lakes corridor. This regulatory chokepoint forces OEM procurement teams to dual-source from Indiana Harbor and Big River Steel while absorbing logistics premiums for just-in-sequence delivery to Detroit-area stamping plants.
Pricing Analysis
Configured-to-order pricing for tailored blank and hot stamped grades commands a 15-20% premium over standard cold-rolled coil, with the spread widening for NHTSA-certified safety-critical applications requiring embedded carbon disclosures. Price differentiation hinges on niobium microalloying certification tier and volume scale, with Detroit Three OEMs locking in multi-year offtake terms while electric vehicle startups face spot market exposure. Cost compression in commodity cold-rolled grades is intensifying because mini-mill operators at Big River Steel exploit electric-arc furnace feedstock advantages. Tier-1 stampers serving low-volume platforms exhibit the highest price sensitivity, whereas integrated OEM stamping divisions prioritize qualification speed over unit cost.
Supply Chain Analysis
Scrap metal feedstock from industrial Midwest demolition and automotive shredder residue anchors electric-arc furnace output at Indiana, Arkansas, and southeastern bar-mill complexes. Ferrous scrap draws from Great Lakes manufacturing waste streams, Brazilian pig iron imports, and obsolete auto hulks processed through Ohio and Michigan shredding operations. Single-source vulnerability concentrates in Ontario and Michigan tool-and-die shops fabricating hot stamping dies, where 18-month qualification timelines freeze supplier switching. Distribution runs through direct mill-to-stamp plant channels for Detroit Three OEMs, while toll-processing arrangements at Cleveland-Toledo service centers capture Tier-1 job shop demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Press hardening technician scarcity across the Midwest constrains OEM in-house stamping expansion and elevates acquisition premiums for qualified furnace operators and die maintenance engineers.
For Market Incumbents: Build captive die fabrication capacity in Windsor and Michigan to eliminate single-source tooling bottlenecks during program ramp-ups. Secure niobium supply agreements with Brazilian miners before microalloying certification delays extend supplier switching costs. Defensive consolidation should target regional service centers in the Cleveland-Toledo corridor to capture toll-processing margins from electric vehicle startups. For New Entrants and Emerging Players: Establish a beachhead in Gulf Coast hot-rolled coil finishing capacity serving Mexican assembly plants in Nuevo León and Bajío Region. Underdeveloped AHSS processing infrastructure along the Texas-Louisiana corridor offers the most penetrable geographic white space. A toll-processing go-to-market angle with regional service centers bypasses the capital intensity of integrated melt capacity while serving low-volume electric vehicle platforms. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated producers with environmental controls and SEC climate disclosure readiness. Long-term viability across the analysis window hinges on embedded carbon intensity below regional baselines for IRA Section 45X credit eligibility. Acquisition targets should display captive scrap supply and hot stamping technology partnerships. The signal to watch is NHTSA side-impact mandate tightening for B-pillar specification upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Press Hardening Capacity Expansion | Captures NHTSA-driven B-pillar upgrade cycles across Detroit Three vehicle programs. |
| Backward Integration into Scrap Supply | Insulates electric-arc furnace operators from ferrous scrap price volatility through captive shredder networks. |
| Tailored Blank Processing Investment | Enables single-piece battery enclosure designs that eliminate weld joints for Michigan and Ontario electric vehicle platforms. |
| Gulf Coast Greenfield Development | Positions finishing capacity proximal to Mexican assembly plant expansion in Nuevo León. |
| Carbon Intensity Certification Program | Aligns coil supply with SEC climate disclosure requirements and IRA Section 45X credit thresholds. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 supplier procurement directors, hot stamping line operators, and regional service center managers provided ongoing calibration against operational realities. Primary interviews with these stakeholders were cross-referenced with secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings, and EPA CAFE compliance reports. Bottom-up segmentation modeling and top-down demand aggregation were triangulated to reconcile volume estimates.
Scenario-bracketing around EPA regulatory stringency and electric vehicle platform ramp rates bounded the projection horizon across product type, end user, technology, and application dimensions. CAGRs were derived from segment-level build-up analysis incorporating content-per-vehicle trajectories and regional production cluster shifts. Forecast inputs included NHTSA safety standard revision timelines and IRA credit eligibility thresholds for embedded carbon intensity.
Sensitivities concentrate around scrap price volatility, single-source die fabrication bottlenecks, and aluminum substitution acceleration in battery enclosures. Forecasts reflect assumptions about regulatory compliance timelines and technology adoption curves that may shift with NHTSA rulemaking or OEM platform architecture decisions. Cross-checking against IHS Markit vehicle production forecasts and EPA CAFE compliance filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Seat Track Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Motorcycle Aluminum Casting Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Automotive Antifreeze Market
Automotive Parts
Off-Road Hoses Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
Tire Tread Cutting Machines Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Commercial Vehicles LED Bar Lights Market
Automotive Parts
Tappet Market
Automotive Parts
Automotive Trim Part Market