
 Rail and Intermodal Decarbonization Strategy Consulting Market | 2026-2036
Rail and Intermodal Decarbonization Strategy Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
Rail and Intermodal Decarbonization Strategy Consulting Market Insights
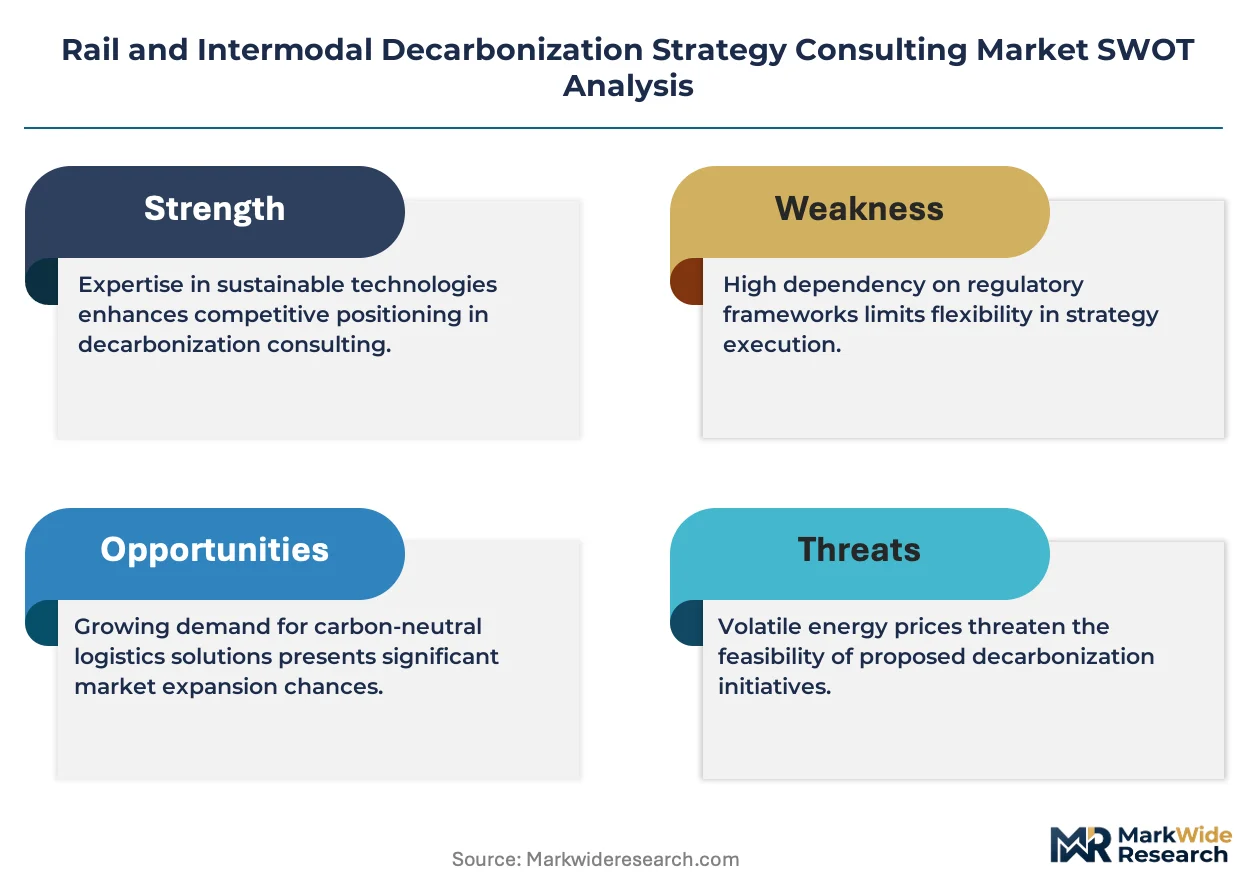
Europe's rail electrification build-out is tilting procurement toward specialized advisory capacity. Oliver Wyman leverages its European rail operator relationships to anchor decarbonization mandates across national networks. Roland Berger sustains differentiation through its alternative propulsion evaluation frameworks for freight corridors. Boston Consulting Group competes by controlling large-scale network-wide decarbonization program design for state-owned railways.
Rail and intermodal decarbonization strategy consulting encompasses advisory services that quantify greenhouse gas baselines, model emission abatement pathways, and design implementation roadmaps for rail freight and passenger networks transitioning from diesel traction. These engagements typically integrate locomotive energy consumption telemetry, infrastructure electrification feasibility studies, and lifecycle carbon accounting across multimodal supply chains. Carbon footprint analysis and emission reduction planning services dominate current revenue pools, while electrification strategy consulting represents the fastest-expanding segment as operators confront asset replacement cycles. Regulatory compliance advisory occupies a mature but stable position where margin pools concentrate among firms holding deep relationships with national rail safety and environmental regulators.
The EPA's locomotive emission standards and the EU Green Deal's transport decarbonization targets shape demand by mandating measurable emission reductions with enforceable timelines. EMA and national rail safety authorities across Europe enforce product standards that require documented abatement pathways before infrastructure funding approval. Stakeholders must monitor how tightening fuel efficiency benchmarks in North America and Europe reshape the competitive value of captive renewable energy integration expertise versus generalist sustainability advisory capabilities.
Market Dynamics
The EPA's locomotive emission standards are compressing diesel asset replacement timelines across North American freight networks, forcing operators to accelerate advisory procurement for electrification pathway modeling and infrastructure feasibility assessment.
Growth Catalysts
- EPA Locomotive Emission Standards:Freight operators in the United States face enforceable NOx and particulate matter reduction mandates that require documented abatement roadmaps before infrastructure funding approval.
- Battery-electric locomotive prototyping:Class I railroads are commissioning feasibility studies for yard-switching electrification, creating demand for specialized traction power modeling and lifecycle cost analysis.
- Deutsche Bahn network decarbonization:Germany's accelerated electrification timeline for non-electrified branch lines is concentrating procurement of catenary infrastructure advisory services.
Market Restraints
- Copper and aluminum price volatility:Overhead catenary system material costs fluctuate with commodity markets, compressing margin certainty on multi-year electrification advisory contracts.
- Specialized rail electrification engineering scarcity:Europe hosts a limited pool of consultants with documented traction power system design experience for mixed-traffic networks.
- EU Green Deal transport decarbonization enforcement gaps:Variable national implementation timelines for rail-specific emission benchmarks create planning uncertainty for cross-border corridor strategies.
Strategic Opportunities
- Hydrogen fuel cell corridor planning:Non-electrified heavy freight routes in Germany and Poland present white space for alternative propulsion infrastructure advisory.
- CSRD-aligned carbon accounting integration:European rail operators must embed Scope 3 supply chain emission tracking into procurement systems, requiring multimodal lifecycle analysis expertise.
- Real-time energy consumption telemetry convergence:Integration of locomotive IoT sensor networks with grid carbon intensity data enables dynamic traction optimization advisory services.
Industry Challenges
- Rail electrification systems engineering talent scarcity:Advisory firms struggle to recruit professionals with combined expertise in traction power engineering and carbon accounting methodology.
- Multimodal emission boundary definition complexity:Intermodal terminals lack standardized protocols for allocating carbon responsibility between rail and truck segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail and Intermodal Decarbonization Strategy Consulting Market |
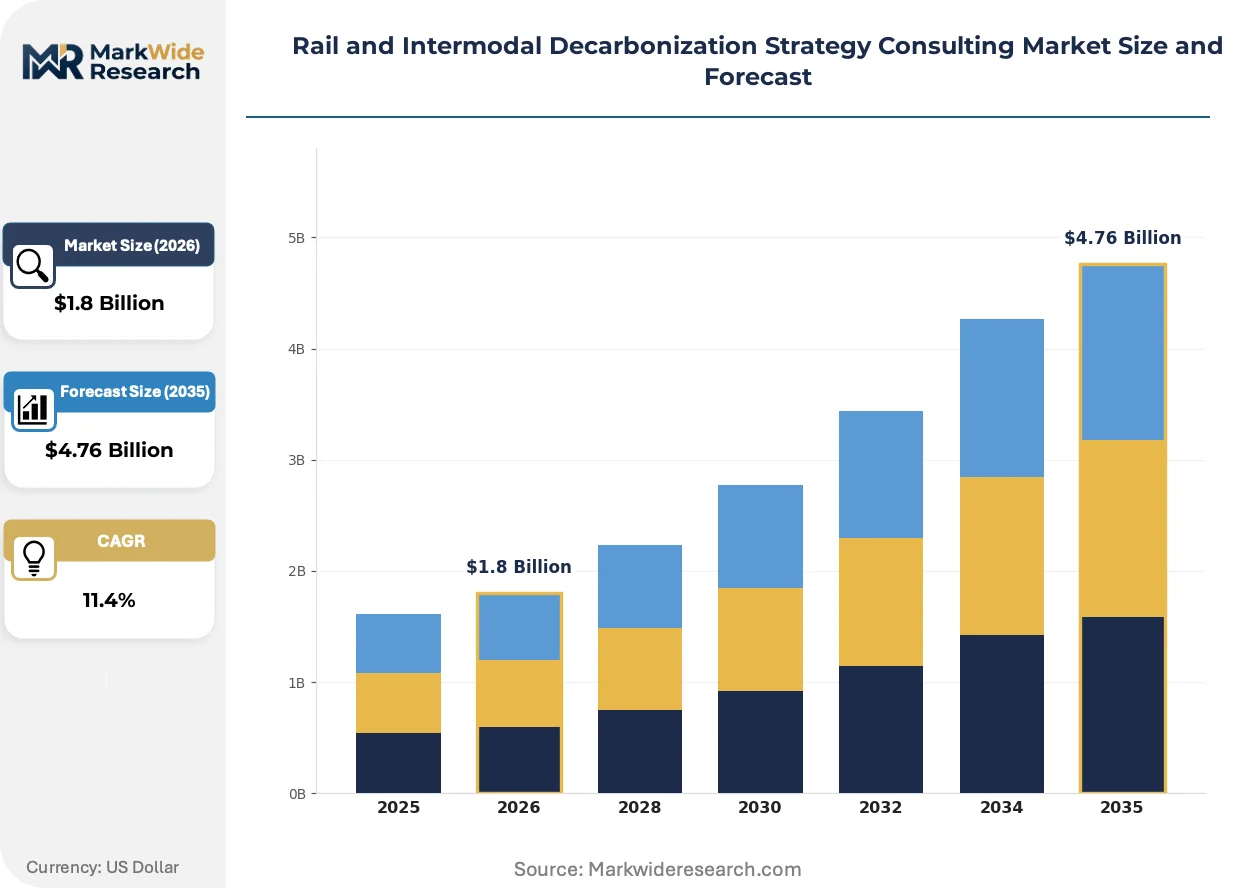
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Carbon Footprint Analysis, Emission Reduction Planning, Regulatory Compliance Advisory, Sustainability Benchmarking Client Type: Freight Operators, Terminal Operators, Logistics Providers, Government Agencies Consulting Focus: Renewable Energy Integration, Fuel Efficiency Optimization, Electrification Strategy, Alternative Propulsion Evaluation Project Scope: Network-wide Decarbonization, Asset-Level Assessment, Operational Improvement, Stakeholder Engagement |
| Companies Covered | Oliver Wyman, Roland Berger, Boston Consulting Group, McKinsey & Company, Booz Allen Hamilton, Accenture, Deloitte, PwC, Frost & Sullivan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail and Intermodal Decarbonization Strategy Consulting Market Trends and Innovations
Advisory methodologies are pivoting from static emission baseline reports toward continuous monitoring architectures that embed real-time locomotive telemetry into decarbonization pathway recalibration.
Digital twin platforms for rail network energy modeling are digitizing infrastructure investment planning across European state-owned railways. Deutsche Bahn and SNCF deploy these systems to simulate catenary extension scenarios against freight volume forecasts. The technology is digitizing how operators prioritize electrification sequencing across fragmented ownership structures.
The EU Green Deal's transport decarbonization targets are mandating documented emission abatement pathways as a condition for infrastructure funding access. National rail safety authorities now require lifecycle carbon assessments before approving rolling stock procurement. Freight corridors crossing German-Polish-Czech borders face the most complex compliance layering as each jurisdiction maintains distinct verification protocols.
Freight shippers are unbundling decarbonization advisory from traditional logistics procurement, creating direct contracting relationships with specialized rail sustainability consultants. Large retail and automotive manufacturers now commission independent emission verification for intermodal lane selection. This pattern is most pronounced in Germany and the Netherlands where corporate Scope 3 disclosure requirements have activated supply chain emission scrutiny.
Rail and Intermodal Decarbonization Strategy Consulting Market Segmentation
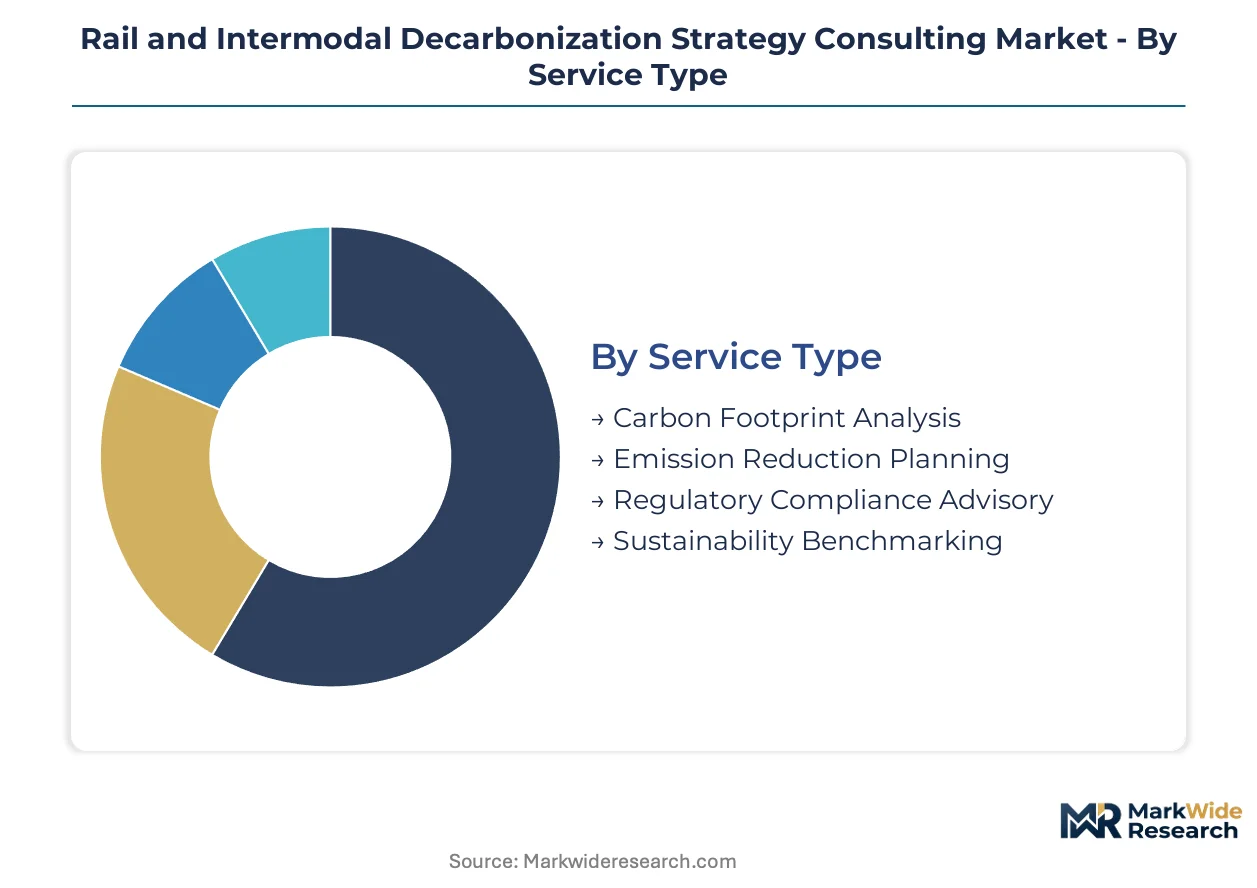
Segmentation in rail and intermodal decarbonization consulting reveals how advisory value concentrates around distinct technical competencies and client risk profiles. Service specialization, client operational complexity, and project scale together determine pricing architecture and engagement duration across this market.
Service Type:
After-sales service intensity varies sharply across service categories, with ongoing pathway recalibration commanding premium retainers against one-time baseline studies.
- Carbon Footprint Analysis:Quantitative greenhouse gas inventory development integrates locomotive telemetry data with multimodal supply chain boundary definitions. Demand concentrates among German freight operators preparing CSRD-aligned disclosures, where Scope 3 intermodal allocation complexity drives procurement of specialized lifecycle assessment expertise.
- Emission Reduction Planning:Abatement pathway modeling combines infrastructure investment sequencing with rolling stock replacement timelines. Deutsche Bahn's accelerated branch line electrification concentrates procurement here, as operators require documented roadmaps for EMA funding approval.
- Regulatory Compliance Advisory:Documentation support for EPA locomotive standards and EU Green Deal transport targets. Relationships with national rail safety authorities determine competitive positioning in mature, stable-margin engagements.
- Sustainability Benchmarking:Peer performance comparison and best practice identification for operator disclosure requirements. Logistics providers in the Netherlands commission these studies to validate intermodal lane carbon claims.
Carbon Footprint Analysis holds the largest share; momentum sits with Emission Reduction Planning.
Client Type:
Cost tier stratification separates enterprise-scale network operators from asset-specific terminal engagements, with procurement authority residing at different organizational levels.
- Freight Operators:Class I railroads and national freight carriers commission network-wide decarbonization programs. Union Pacific and BNSF procurement teams direct advisory spend toward electrification feasibility for high-volume corridors.
- Terminal Operators:Intermodal yard and port facility managers require asset-level emission baselines and yard-switching electrification studies. Demand clusters around Los Angeles-Long Beach and Rotterdam port complexes.
- Logistics Providers:Third-party intermodal coordinators seek multimodal carbon accounting integration. DHL and Kuehne+Nagel drive procurement for supply chain emission verification services.
- Government Agencies:National transport ministries and regional development bodies fund corridor-level decarbonization studies. Poland's infrastructure ministry represents expanding procurement for hydrogen freight pilot planning.
Freight Operators dominate current revenue; Government Agencies are expanding most quickly.
Consulting Focus:
Application maturity separates proven electrification methodologies from emerging alternative propulsion advisory where technical uncertainty commands risk premiums.
- Electrification Strategy:Catenary infrastructure planning, traction power system design, and grid interconnection feasibility for mixed-traffic networks. SNCF and Deutsche Bahn procurement concentrates demand in this segment.
- Alternative Propulsion Evaluation:Hydrogen fuel cell and battery-electric locomotive corridor assessment for non-electrified routes. German-Polish border freight corridors present white space for specialized advisory.
- Renewable Energy Integration:On-site solar and wind procurement for traction power supply and depot operations. Spanish freight operators advance this focus amid high grid carbon intensity.
- Fuel Efficiency Optimization:Operational modeling for diesel locomotive consumption reduction in transition periods. North American Class I railroads commission these studies to compress EPA compliance timelines.
Electrification Strategy holds the largest share; Alternative Propulsion Evaluation shows steepest expansion trajectory.
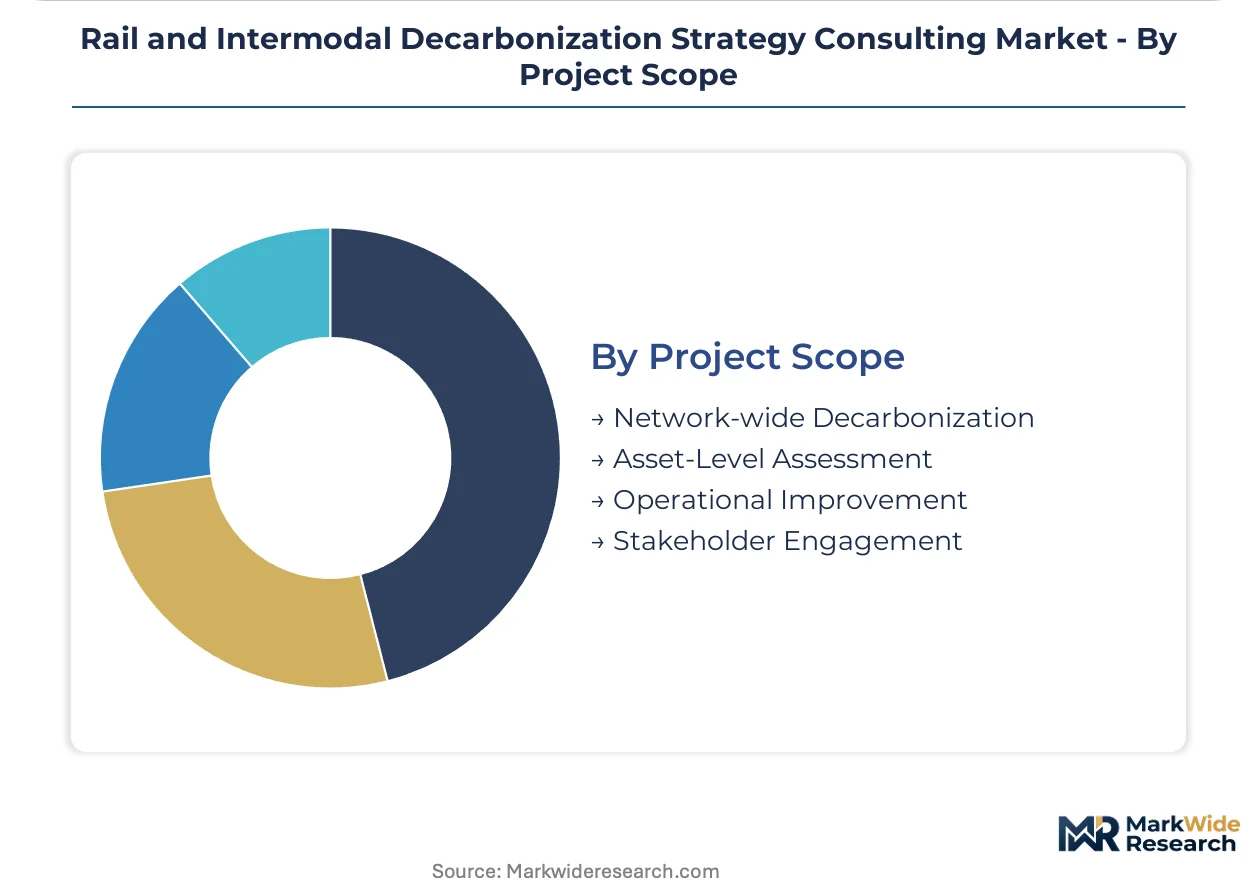
Project Scope:
Volume concentration favors network-wide mandates where multi-year advisory retainers displace discrete project fees.
- Network-wide Decarbonization:System-level transformation programs spanning infrastructure, rolling stock, and operational protocols. State-owned railways in France and Germany anchor procurement for decade-long advisory partnerships.
- Asset-Level Assessment:Facility-specific emission baselines and abatement planning for individual terminals or corridor segments. Port authorities in Hamburg and Antwerp commission these focused engagements.
- Operational Improvement:Energy consumption optimization through scheduling, speed management, and load factor enhancement. Freight operators deploy these studies to capture near-term emission reductions.
- Stakeholder Engagement:Supply chain emission disclosure alignment and shipper certification support. Retail and automotive manufacturers in Germany drive demand for independent verification services.
Network-wide Decarbonization commands the largest share; Stakeholder Engagement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advisory capacity clusters where electrification mandates are most stringent. Germany, the United States, France, the United Kingdom, and Poland concentrate procurement for specialized rail decarbonization expertise.
United States
Class I railroads commission electrification feasibility studies for high-volume corridors under EPA locomotive emission standards. The EPA mandates documented NOx and particulate matter abatement roadmaps before infrastructure funding approval. Union Pacific and BNSF procurement teams direct advisory spend toward yard-switching electrification modeling in California and Texas.
Germany
Deutsche Bahn's accelerated branch line electrification concentrates demand for catenary infrastructure advisory services. The EU Green Deal's transport decarbonization targets require lifecycle carbon assessments before EMA rolling stock approval. Freight corridors crossing German-Polish borders in Lower Saxony and North Rhine-Westphalia face complex compliance layering.
France
SNCF deploys digital twin platforms for network energy modeling across state-owned railway infrastructure. The EU Green Deal mandates documented emission abatement pathways as a condition for infrastructure funding access. Paris and Lyon anchor procurement for decade-long network-wide decarbonization advisory partnerships.
United Kingdom
Network Rail commissions operational improvement studies to capture near-term emission reductions on mixed-traffic routes. CSRD-aligned carbon accounting requirements drive procurement for multimodal lifecycle analysis expertise. London and the Midlands concentrate demand for freight corridor decarbonization planning.
Poland
The infrastructure ministry expands procurement for hydrogen freight pilot planning on non-electrified heavy routes. Variable EU Green Deal national implementation timelines create planning uncertainty for cross-border corridor strategies. Silesian freight corridors present white space for alternative propulsion infrastructure advisory.
Rail and Intermodal Decarbonization Strategy Consulting Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with traction power modeling and lifecycle carbon accounting tools. The vendor base organizes around three archetypes: global strategy firms with rail operator relationships, specialized infrastructure engineering boutiques, and Big Four advisory practices with regulatory compliance depth. Consolidation pressure runs through M&A targeting electrification engineering talent and strategic partnerships anchoring multi-year network transformation programs.
Within the global strategy tier, Oliver Wyman, Roland Berger, and Boston Consulting Group occupy positions shaped by European rail operator mandates. Oliver Wyman leverages relationships across national networks to anchor decarbonization programs. Roland Berger exemplifies differentiation through alternative propulsion evaluation frameworks for freight corridors. Boston Consulting Group sits within the large-scale program design segment for state-owned railways. These three represent how advisory value concentrates around specialized technical competencies and documented traction power system experience.
| Leading Market Players |
|---|
| Oliver Wyman |
| Roland Berger |
| Boston Consulting Group |
| McKinsey & Company |
| Booz Allen Hamilton |
| Accenture |
| Deloitte |
| PwC |
| Frost & Sullivan |
| Others |
Pricing and Supply Chain Analysis
German traction power engineering talent pools anchor margin capture downstream, concentrating premium advisory rates with firms holding documented catenary infrastructure design experience for mixed-traffic networks.
Pricing Analysis
The EPA's locomotive emission standards dictate the pricing tier structure across North American engagements, separating premium pathway recalibration retainers from discrete baseline study fees. Pricing stratifies across network-wide program mandates, corridor-specific feasibility assessments, and asset-level terminal studies, with after-sales intensity commanding sustained margin pools. Cost compression in standardized carbon footprint analysis is intensifying because Big Four advisory practices replicate methodology at scale. Government agencies exhibit highest price sensitivity due to procurement oversight, while Class I railroads demonstrate lowest sensitivity given regulatory compliance timelines.
Supply Chain Analysis
Export controls on traction power simulation software limit flows from German engineering boutiques to non-EU advisory practices, fragmenting specialized capacity access. Supply concentrates in Germany, France, and the United Kingdom for catenary infrastructure modeling expertise, while North American demand draws from limited cross-Atlantic talent mobility. Raw material dependencies span copper and aluminum for overhead catenary system cost forecasting, alongside lithium-ion battery chemistry data for yard-switching electrification studies. Single-source vulnerability sits with boutique firms holding exclusive relationships with national rail safety authorities. Distribution runs through direct procurement relationships with state-owned railway planning departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rail and intermodal decarbonization strategy consulting sits in early-cycle expansion, with EPA locomotive standards and EU Green Deal transport targets activating advisory procurement that previously operated on discretionary sustainability budgets.
For Market Incumbents: Entrench differentiation by acquiring traction power engineering boutiques in Germany and Poland before alternative propulsion evaluation frameworks commoditize. Deepen vertical integration into real-time locomotive telemetry data partnerships to lock in continuous pathway recalibration revenue streams against emerging SaaS-based competitors. For New Entrants and Emerging Players: Polish hydrogen freight corridor planning presents the most penetrable white space, with Silesian routes lacking specialized advisory capacity for fuel cell infrastructure feasibility. Battery-electric locomotive lifecycle cost modeling for Class I railroad yard operations offers a second entry point. Lead with CSRD-aligned carbon accounting integration as the go-to-market angle to bypass incumbent regulatory compliance relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed infrastructure engineering boutiques holding Deutsche Bahn and SNCF advisory mandates. Long-term viability hinges on electrification timeline acceleration rather than alternative propulsion technology risk. Watch for EMA funding approval protocol harmonization across German-Polish-Czech borders as the inflection signal for cross-border corridor strategy consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Traction Power Engineering Boutique | Captures scarce German catenary infrastructure design capacity before competitor consolidation. |
| Real-Time Telemetry Data Partnership | Enables continuous decarbonization pathway recalibration services beyond static baseline reports. |
| Hydrogen Corridor Feasibility Framework Development | Positions advisory capability for Polish and German non-electrified heavy freight routes. |
| CSRD-Aligned Carbon Accounting Platform Launch | Addresses Scope 3 supply chain emission tracking requirements for German freight operators. |
| Cross-Border Compliance Protocol Harmonization | Reduces planning uncertainty for German-Polish-Czech freight corridor strategies under variable EU Green Deal timelines. |
Research Methodology
A spread of perspectives from rail operator sustainability directors, national transport ministry procurement officers, traction power engineering consultants, and intermodal terminal operations managers converged on the working assumptions. Primary interview data combined with secondary validation from EPA regulatory filings, EU Green Deal implementation documents, EMA funding approval records, and Deutsche Bahn procurement disclosures. Bottom-up engagement sizing triangulated against top-down market aggregation across service type, client type, consulting focus, and project scope dimensions.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation modeling captured service type specialization, client operational complexity tiers, consulting focus maturity levels, and project scale hierarchies. CAGRs derived from advisory engagement volume trajectories indexed to electrification infrastructure investment cycles and rolling stock replacement timelines. Forecast inputs incorporated locomotive energy consumption telemetry adoption curves and national rail safety authority staffing capacity for compliance documentation review.
Practitioners should monitor EPA locomotive standard enforcement timing, EU Green Deal national implementation variance, and copper-aluminum commodity price volatility for early signals. Forecasts reflect assumptions on regulatory compliance timeline adherence and specialized engineering talent pool expansion. Material shifts in cross-border corridor funding protocol harmonization or battery-electric locomotive prototype deployment acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Electro-Pneumatic Train Brakes Market
Railway
Rail Glazing Market
Railway
Railway Axle Market
Railway
Locomotive Maintenance Market
Railway
Hydrogen Trains Market
Railway
Railway Track Market
Railway
Rail Brace Market
Railway
Railway Telematics Market
Railway
Railway Automated Inspection Equipment Market
Railway
France Rail Freight Transport Market
Railway
Rail Brake Frame Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
Tugger Trains Market
Railway
Rail Seat Market
Railway
Automatic Train Operation System Market
Railway
Rolling Stocks Market