
 France Connected Rail Market | 2026-2036
France Connected Rail Market Size, Share, and Industry Trends Forecast 2026-2036
France Connected Rail Market Insights
The EU Green Deal's modal shift mandate is recalibrating capital allocation across French rail infrastructure. Alstom SA leverages its digital mobility portfolio to anchor signaling and train control modernization programs. Siemens Mobility competes through integrated IoT platforms that link rolling stock with trackside analytics.
Connected rail encompasses sensor networks, communication systems, and data platforms that monitor train performance, track conditions, and passenger flows in real time using 4G/5G, Wi-Fi, and satellite links. Its primary purpose is to enhance safety, optimize capacity utilization, and reduce unplanned downtime across passenger and freight operations. IoT Solutions and AI Integration lead technology investment as operators pursue predictive capabilities, while Remote Monitoring and Predictive Maintenance command the service model margin pool. Cloud-based Deployment Models gain traction among urban transit authorities seeking scalable infrastructure without heavy capital commitment.
France's national rail regulator, the EPSF, enforces safety certification standards that shape vendor qualification timelines and system interoperability requirements. The EU's F-Gas Regulation and national decarbonization targets under the SNCF's "Plan Vert" framework mandate energy-efficient connected systems. Stakeholders must monitor how ANSM's cybersecurity directives for critical infrastructure intersect with rail-specific standards.
Market Dynamics
EU Green Deal modal shift mandates are redirecting French rail capital toward electrification and digital signaling infrastructure, compressing procurement timelines while elevating interoperability requirements across SNCF and RATP networks.
Growth Catalysts
- EU Green Deal modal shift targets:Binding passenger and freight rail volume mandates are accelerating SNCF's "Plan Vert" electrification investments and connected system deployments across TGV corridors.
- Île-de-France network density:RATP and SNCF's interconnected urban operations generate concentrated demand for real-time passenger flow monitoring and predictive maintenance platforms.
- 5G-Rail standardization:ETSI and UIC specifications for railway-specific 5G are enabling next-generation train-to-ground communication architectures for ETCS Level 3 signaling.
Market Restraints
- Copper and rare earth input volatility:Sensor networks and power electronics depend on concentrated supply chains for neodymium and high-purity copper, exposing operators to price swings.
- EPSF certification timelines:France's national rail safety regulator enforces extended validation periods for digital signaling systems, stretching vendor qualification cycles.
- Road freight substitution pressure:Liberalized European trucking markets and last-mile logistics platforms retain cost advantages for time-sensitive cargo.
Strategic Opportunities
- Regional network digitization:Secondary TGV lines and TER networks outside Paris-Île-de-France remain underpenetrated for ETCS and connected maintenance systems.
- F-Gas Regulation compliance services:EU mandates for refrigerant phase-down in train HVAC systems create retrofit demand for IoT-enabled leak detection and energy monitoring.
- AI-IoT convergence:Edge computing platforms integrating machine vision for track inspection with cloud-based fleet analytics offer untapped predictive capability.
Industry Challenges
- Cyber-physical systems integration:ANSM cybersecurity directives for critical infrastructure intersect with CENELEC rail standards, complicating unified compliance frameworks.
- Legacy signaling migration:SNCF's mixed fleet of classic and digital train control requires transitional architectures that maintain safety during staged upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Connected Rail Market |
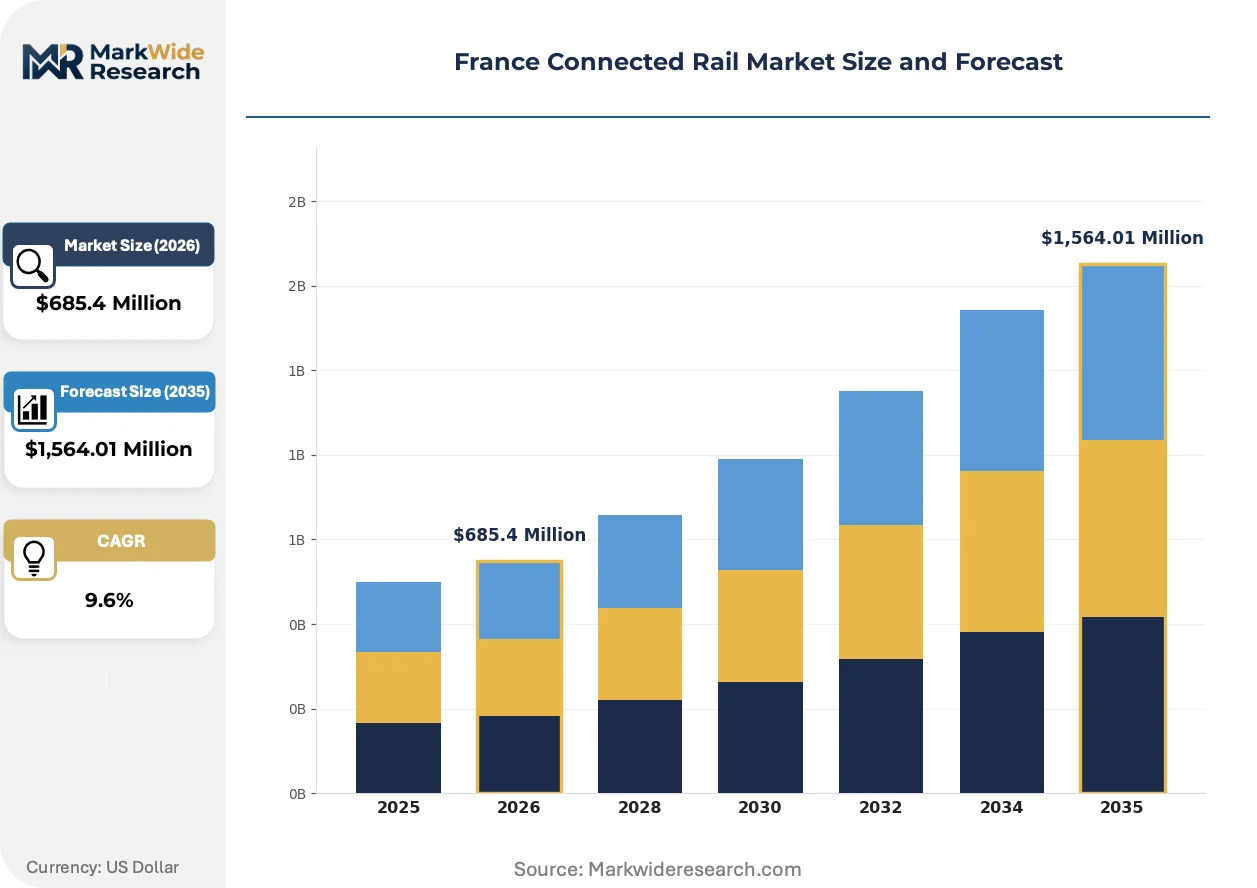
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,564.01 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: IoT Solutions, Cloud Computing, Data Analytics, AI Integration Service Model: Remote Monitoring, Predictive Maintenance, Fleet Management, Network Optimization End User: Rail Operators, Government Agencies, Freight Companies, Urban Transit Authorities Deployment Model: On-premise, Hybrid, Cloud-based, Managed Services |
| Companies Covered | SNCF, Trimble Inc., Alstom SA, Nokia, Robert Bosch GmbH, Siemens Mobility, Hitachi Rail Limited, Huawei Technologies Co., Ltd., Thales GTS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Connected Rail Market Trends and Innovations
Digital twin architectures are replacing siloed maintenance databases across French rail operators, unifying track geometry, rolling stock condition, and passenger demand signals into continuous simulation models.
Edge AI inference engines for real-time wheel-rail interaction monitoring are consolidating distributed sensor networks into centralized predictive platforms. SNCF's freight and passenger divisions are deploying these systems on TGV Duplex and Regio 2N fleets to compress fault detection-to-response cycles from hours to seconds. The technology is consolidating vendor relationships around integrated hardware-software providers capable of full-stack deployment.
France's transposition of the EU AI Act into rail-specific guidance through EPSF and ANSM coordination is mandating risk classification for automated decision systems in traffic management. Operators must now document algorithmic transparency for safety-critical AI deployments, affecting procurement specifications for signaling modernization. The Île-de-France region's dense RATP-SNCF interoperability zone faces the steepest compliance curve.
Performance-based maintenance contracting is displacing fixed-schedule service agreements as SNCF and regional transport authorities seek to align vendor payments with availability metrics. Infrastructure managers in Auvergne-Rhône-Alpes and Hauts-de-France are piloting contracts where suppliers assume downtime risk, transferring operational accountability to equipment providers. This restructuring is most advanced on high-speed lines where unplanned outages carry the highest passenger revenue impact.
France Connected Rail Market Segmentation
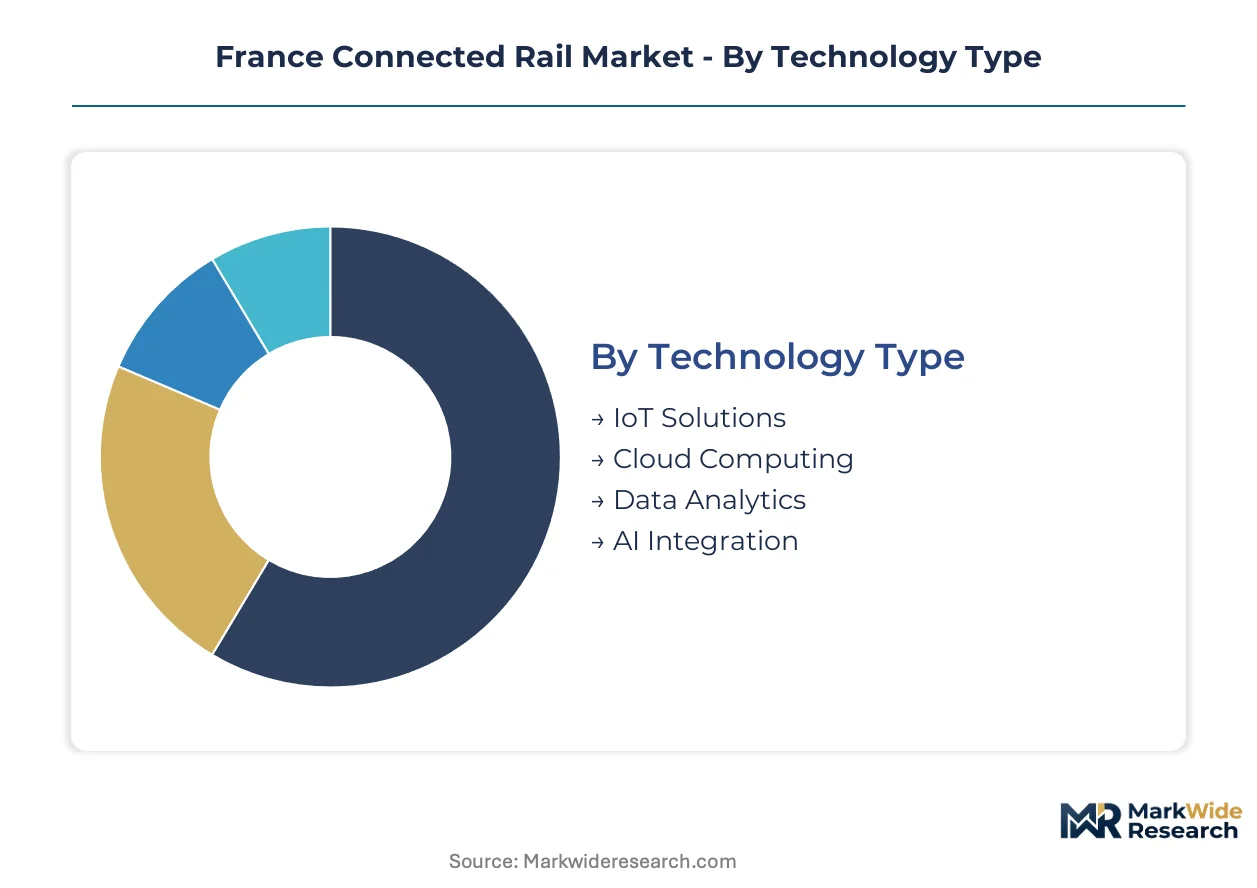
Technology architecture determines vendor qualification pathways and procurement specifications across French rail networks. Each segmentation axis reveals distinct investment priorities among SNCF, RATP, and regional operators navigating EPSF certification requirements.
Technology Type:
Sensor-to-cloud architectures define competitive positioning among French system integrators bidding on SNCF modernization programs.
- IoT Solutions:Distributed sensor networks capture wheel-rail interaction, pantograph wear, and HVAC performance metrics via 4G/5G and satellite uplinks. SNCF's TGV Duplex fleet deploys these systems most densely on Paris-Lyon and Paris-Marseille corridors where downtime costs peak.
- AI Integration:Machine learning models process multi-source telemetry to forecast component failures before threshold breaches trigger alerts. The Île-de-France region concentrates demand as RATP and SNCF interoperability requirements create complex traffic pattern prediction challenges.
- Cloud Computing:Elastic infrastructure supports demand spikes during peak commuting periods without stranded capital.
- Data Analytics:Visualization platforms consolidate maintenance records with real-time condition monitoring for unified fleet oversight.
Mature deployment sits with IoT Solutions. Newer deployment is concentrated in AI Integration.
Service Model:
Outcome-based contracting reshapes how French operators procure operational technology, shifting risk to vendors.
- Predictive Maintenance:Algorithmic failure forecasting replaces calendar-based servicing, compressing mean-time-to-repair across TER regional networks. Auvergne-Rhône-Alpes and Hauts-de-France pilot contracts where suppliers assume availability risk, transferring accountability from SNCF infrastructure managers to equipment providers.
- Remote Monitoring:Continuous telemetry streams enable centralized control centers to dispatch maintenance crews before passenger-visible disruptions occur. Secondary TGV lines outside Paris-Île-de-France show fastest adoption as legacy staffing models prove uneconomical on lower-density routes.
- Fleet Management:Integrated scheduling and maintenance optimization balances asset utilization against reliability targets.
- Network Optimization:Dynamic capacity allocation responds to real-time demand fluctuations across interconnected RATP-SNCF nodes.
Remote Monitoring commands the established revenue base. Predictive Maintenance is gaining share fastest among new procurements.
End User:
Procurement authority fragmentation across French rail governance layers creates multiple entry points for technology vendors.
- Rail Operators:SNCF Réseau and SNCF Voyageurs drive standardization through centralized technical specifications that cascade to regional branches. Their consolidated purchasing power shapes interoperability requirements that smaller vendors struggle to meet.
- Urban Transit Authorities:RATP's autonomous procurement function within Paris-Île-de-France generates concentrated demand for passenger flow analytics and platform crowding management distinct from intercity priorities.
- Government Agencies:EPSF safety mandates and ANSM cybersecurity directives constrain system architecture choices regardless of commercial preferences.
- Freight Companies:Private operators on liberalized corridors seek asset tracking and terminal efficiency solutions outside SNCF's integrated passenger-focused platforms.
Volume concentration rests with Rail Operators. Policy influence is expanding through Government Agencies.
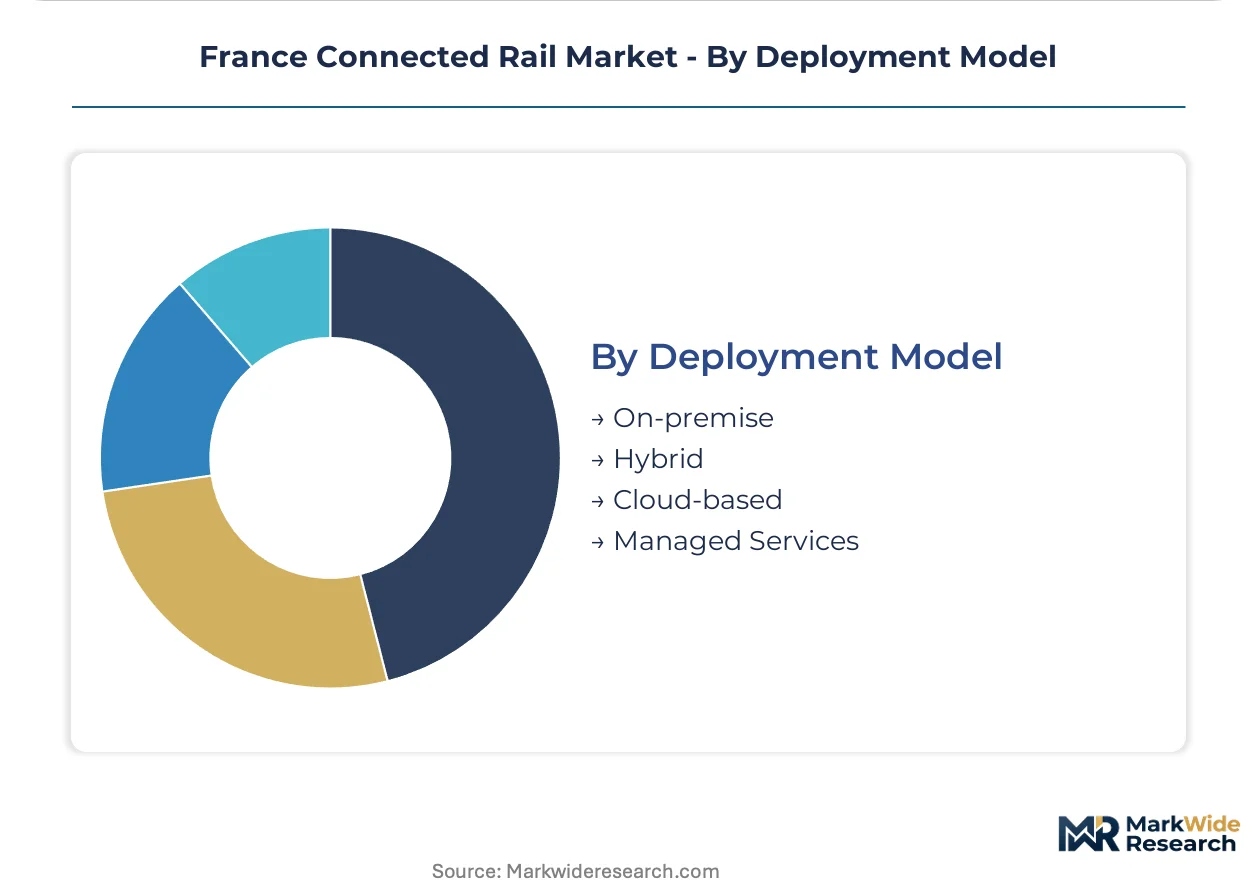
Deployment Model:
Capital constraint severity varies across French public sector budget cycles, driving infrastructure ownership preferences.
- Cloud-based:Scalable subscription models appeal to urban transit authorities facing political pressure to limit capital commitments while expanding digital capabilities. RATP's phased migration to cloud-native passenger information systems demonstrates operational feasibility for safety-adjacent workloads.
- Hybrid:Sensitive operational data remains on-premise while analytics workloads burst to cloud infrastructure, addressing ANSM cybersecurity concerns without sacrificing computational elasticity. SNCF's mixed fleet modernization relies on this architecture during transitional signaling upgrades.
- On-premise:Air-gapped systems persist where ETCS Level 2 safety certification requires deterministic response times.
- Managed Services:Full outsourcing bundles operational responsibility with technology provision for resource-constrained regional operators.
Hybrid architectures dominate current procurement. Cloud-based models show steepest expansion trajectory among new awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris-Île-de-France generates the densest concentration of connected rail investment in France, with RATP and SNCF operating Europe's most intensively monitored urban rail network.
Île-de-France
RATP's Metro and RER lines deploy real-time passenger flow analytics and platform crowding management systems across 14 metro lines and 5 RER corridors. The region's Grand Paris Express construction integrates ETCS Level 2 signaling with IoT-enabled infrastructure monitoring from project inception. Saint-Denis and La Défense host the primary control centers coordinating SNCF-RATP interoperability.
Auvergne-Rhône-Alpes
Lyon's TGV hub and extensive TER regional network drive predictive maintenance platform deployment across mixed passenger and freight corridors. The regional transport authority pilots performance-based maintenance contracts where suppliers assume availability risk on high-speed lines. Grenoble's tram-train interconnections create demand for unified fleet management systems spanning urban and interurban modes.
Provence-Alpes-Côte d'Azur
Marseille's port-rail intermodal terminals require asset tracking and terminal efficiency solutions for freight operators on liberalized corridors. The LGV Méditerranée extension toward Nice concentrates ETCS modernization investment. Toulon's naval-industrial cluster generates specialized demand for cybersecurity-hardened communication systems.
Hauts-de-France
Lille's position as a Channel Tunnel rail gateway drives cross-border interoperability investment for Eurostar and freight operators. The region's coal-phase transition legacy infrastructure requires extensive signaling retrofit. Calais-Dunkerque port corridors concentrate demand for remote monitoring on lower-density routes where legacy staffing models prove uneconomical.
Nouvelle-Aquitaine
Bordeaux's TGV Atlantique terminus and extensive rural TER network create bifurcated demand between high-speed digital signaling and cost-constrained regional connectivity. The LGV Sud Europe Atlantique extension toward Spain mandates cross-border ETCS harmonization. Biarritz-Bayonne border crossings test Franco-Spanish interoperability standards.
France Connected Rail Market Competitive Landscape
The competitive structure tilts toward integrated system providers capable of spanning signaling, rolling stock, and digital infrastructure. Vendor relationships consolidate around full-stack deployment capabilities as operators seek unified accountability. Three archetypes dominate: European rail specialists with legacy signaling expertise, diversified industrial conglomerates with IoT platforms, and telecommunications equipment providers with 5G-Rail credentials. Strategic moves center on portfolio diversification into predictive maintenance services and geographic expansion through EU cross-border project participation.
Among France-based rail specialists, Alstom SA and Thales GTS anchor the domestic vendor tier, representing integrated mobility portfolios that span digital signaling through fleet analytics. Siemens Mobility occupies a position exemplifying the diversified industrial archetype with cross-border European reach. Nokia and Huawei Technologies Co., Ltd. sit within the telecommunications equipment tier, competing on 5G-Rail infrastructure deployment.
| Leading Market Players |
|---|
| SNCF |
| Trimble Inc. |
| Alstom SA |
| Nokia |
| Robert Bosch GmbH |
| Siemens Mobility |
| Hitachi Rail Limited |
| Huawei Technologies Co., Ltd. |
| Thales GTS |
| Others |
Pricing and Supply Chain Analysis
High-purity copper and neodymium feedstock costs cascade through sensor network manufacturing into tiered system pricing for SNCF and RATP procurement teams, with EPSF certification premiums separating qualified vendors from commodity hardware suppliers.
Pricing Analysis
Availability-based contracting anchors vendor pricing to train uptime guarantees rather than equipment unit costs. Three-tier pricing structure across premium, standard, and economy levels reflects ETCS certification grade and after-sales service bundling. Cost compression in standard-tier hardware is intensifying because Chinese sensor manufacturers are expanding European distribution. Regional TER operators show highest price sensitivity due to constrained public budgets, while TGV corridor projects demonstrate lowest sensitivity given passenger revenue at risk.
Supply Chain Analysis
Specialized rail electronics manufacturing in Germany, France, and Switzerland faces acute engineering workforce constraints that extend component lead times. Supply chains draw from Malaysian semiconductor packaging, Chinese rare earth processing, and Romanian cable assembly. Single-source vulnerability concentrates in gallium nitride power semiconductors for 5G-Rail base stations. Distribution runs through SNCF-certified system integrators who bundle hardware with EPSF compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
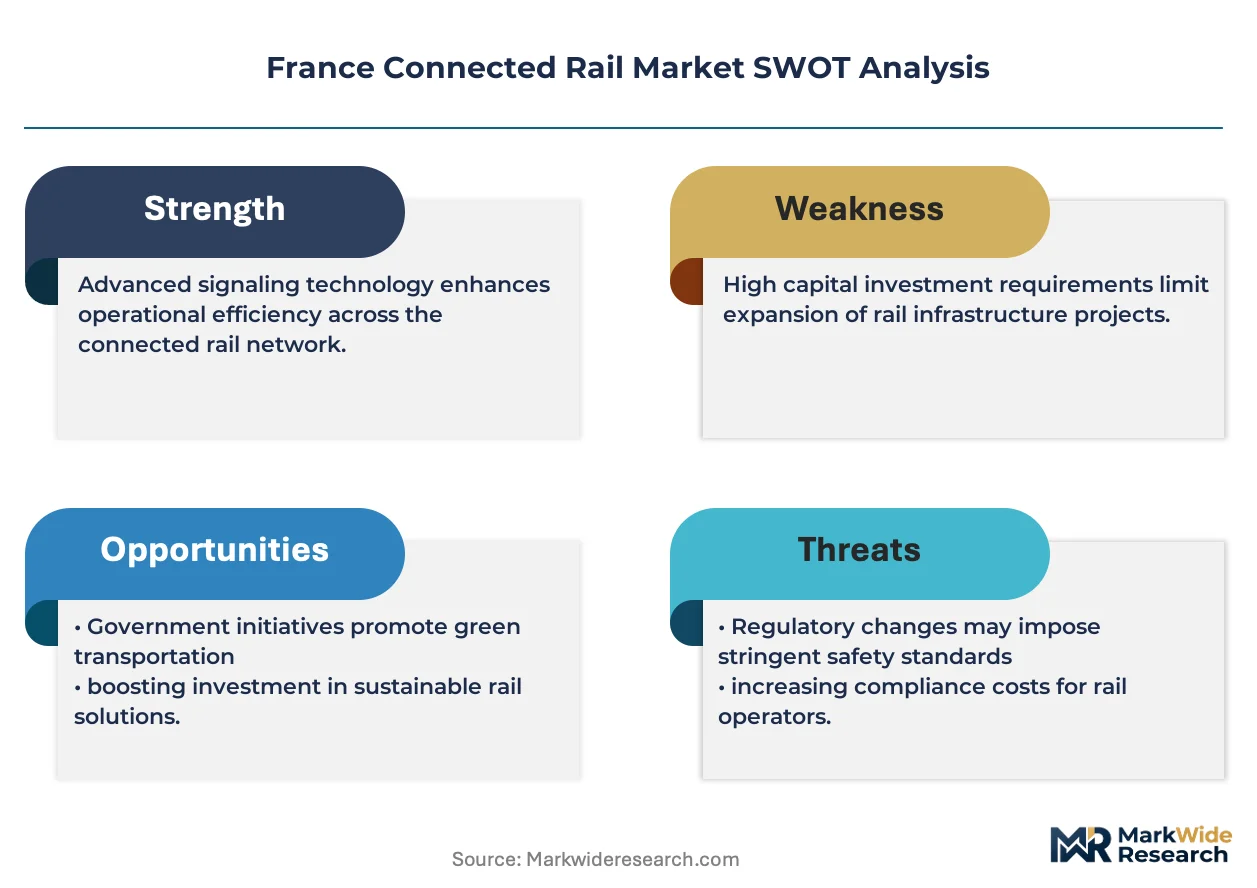
France's connected rail market operates as a cost-of-compliance arena where EPSF safety certification timelines create a 12-18 month barrier-to-entry moat favoring incumbent vendors with established validation track records.
For Market Incumbents: Lock in regional operator relationships through performance-based maintenance contracts that transfer availability risk from SNCF infrastructure managers to equipment providers. Deepen backward integration into edge AI inference hardware to reduce dependency on Nvidia-dominated GPU supply chains. Alstom and Thales GTS should prioritize cybersecurity-hardened communication modules ahead of ANSM critical infrastructure directives tightening.
For New Entrants and Emerging Players: Secondary TGV lines and TER networks outside Paris-Île-de-France represent the most penetrable buyer archetype, as legacy staffing models prove uneconomical on lower-density routes. Target freight operators on liberalized corridors seeking asset tracking solutions outside SNCF's integrated passenger platforms. Lead with cloud-native remote monitoring platforms that bypass capital-intensive on-premise deployment requirements.
For Investors and Strategic Acquirers: EPSF's publication of AI Act transposition guidance for rail-specific risk classification is the leading indicator that algorithmic transparency documentation capabilities will separate acquisition targets from stranded assets. Favor vendors with full-stack deployment capabilities spanning signaling hardware through predictive maintenance software. Watch for SNCF Réseau centralizing technical specifications that cascade procurement standards to regional branches.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Maintenance Contracting | Suppliers assume downtime risk on Auvergne-Rhône-Alpes high-speed lines, transferring accountability from SNCF. |
| 5G-Rail Infrastructure Deployment | ETSI and UIC specifications enable next-generation train-to-ground communication for ETCS Level 3 signaling. |
| Edge AI Platform Integration | Real-time wheel-rail interaction monitoring compresses fault detection-to-response cycles from hours to seconds. |
| Cybersecurity Certification Investment | ANSM directives for critical infrastructure intersect with CENELEC standards, requiring unified compliance frameworks. |
| Regional Network Digitization | Secondary TGV and TER corridors outside Paris-Île-de-France remain underpenetrated for connected maintenance systems. |
Research Methodology
Multi-period observation of SNCF capital expenditure disclosures, RATP procurement announcements, and EPSF certification timelines anchored the trend analysis, supplemented by interviews with rail signaling engineers, infrastructure maintenance directors, urban transit procurement managers, and telecommunications equipment specialists. Secondary validation drew from EU Transport Scoreboard data, UIC statistical reports, ETSI standardization documents, and ANSM cybersecurity guidance. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the French rail sector.
Input-output matrices mapped technology adoption curves against regulatory compliance deadlines, service model transitions, and deployment architecture preferences across the projection horizon. Segmentation dimensions included technology type, service model, end-user category, and deployment approach, with geographic concentration within France's regional transport authorities. CAGRs were derived from regression analysis of historical investment patterns and announced modernization program scopes, incorporating ETCS rollout schedules and Green Deal modal shift targets as demand-side drivers.
Revisions become necessary when EPSF certification timelines extend beyond modeled durations, ANSM cybersecurity directives impose unanticipated architectural constraints, or rare earth supply disruptions alter hardware cost assumptions. Forecasts reflect documented assumptions about regulatory stability and technology standardization progress. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railcar Vehicle Toilet Market
Railway
Rail Bellows Market
Railway
Freight Cars Market
Railway
Solar Train Market
Railway
Railroads Market
Railway
Maglev Train Market
Railway
Locomotive Market
Railway
Railway Buffer Stops Market
Railway
Rail Damper Market
Railway
Road-Rail Vehicles Market
Railway
Train Exterior Lighting Market
Railway
Global Smart Locomotive Market
Railway
Rail Brake Frame Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Europe 40-Foot Platform Wagons Market
Railway
Locomotive Doors Market