
 Smart Mobility Market | 2026-2036
Smart Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Mobility Market Intelligence
Modular subscription bundling of vehicles, charging, and insurance into single contracts is pivoting buyer choice away from traditional ownership models. Bolt leverages its ride-hailing density to anchor urban fleet electrification across European capitals. ZeroAvia specializes in hydrogen-electric propulsion systems for regional aviation, competing on zero-emission range credentials. IZI Electric sustains its position through compact two-wheeler designs purpose-built for dense Southeast Asian streets.
Smart mobility encompasses digitally integrated transportation systems combining AI-driven routing, IoT-enabled vehicle telemetry, and V2X communication protocols to optimize traffic flow, reduce emissions, and enable multimodal trip coordination. Its primary commercial purpose is replacing fragmented, asset-heavy transit with connected, on-demand services that improve utilization rates. Ride-hailing platforms currently capture the largest margin pools due to network effects and dynamic pricing infrastructure. E-scooter sharing remains the fastest-expanding vehicle type segment, though profitability hinges on unit economics and regulatory caps on fleet sizes.
FAA certification pathways for urban air mobility and EU Green Deal emissions benchmarks are tightening operational requirements for new entrants. NHTSA's V2X mandates and ECHA battery recycling rules under REACH are reshaping component sourcing and end-of-life obligations. Stakeholders must monitor which regulatory jurisdiction's compliance timeline becomes the binding constraint for cross-border service deployment.
Market Dynamics
AI-powered fleet orchestration is compressing operator margins while expanding service density, forcing asset-light platform models to absorb vehicle ownership costs previously borne by individual drivers.
Growth Catalysts
- EU Green Deal emissions benchmarks:Binding carbon reduction targets for urban transit fleets are accelerating electrification procurement timelines across municipal authorities.
- V2X communication protocols:NHTSA mandates for vehicle-to-infrastructure connectivity are unlocking real-time traffic optimization in dense US metropolitan corridors.
- Seoul's municipal transit expansion:AI-powered fleet deployments by Korean authorities are demonstrating scalable models for predictive maintenance and dynamic routing.
Market Restraints
- Lithium-ion supply concentration:Cathode precursor refining clusters in select Asian geographies create input cost volatility for battery pack assembly.
- FAA certification pathways:Urban air mobility operators face extended validation timelines that compress first-mover advantage windows.
- Legacy internal combustion fleets:Residual asset values and sunk maintenance infrastructure slow fleet turnover rates for commercial operators.
Strategic Opportunities
- German urban corridor demand:Concentrated electrification requirements in high-density transit zones create premium service tiers for integrated mobility providers.
- Modular subscription bundling:Single-contract vehicle, charging, and insurance packaging is displacing traditional ownership financing for fleet buyers.
- REACH battery recycling rules:ECHA end-of-life obligations are generating closed-loop material recovery revenue streams for certified processors.
Industry Challenges
- AI/ML systems integration talent:Shortage of specialists capable of deploying real-time routing algorithms across heterogeneous fleet data architectures.
- Multimodal platform interoperability:Fragmented API standards between ride-hailing, transit, and micro-mobility operators complicate unified trip planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Mobility Market |
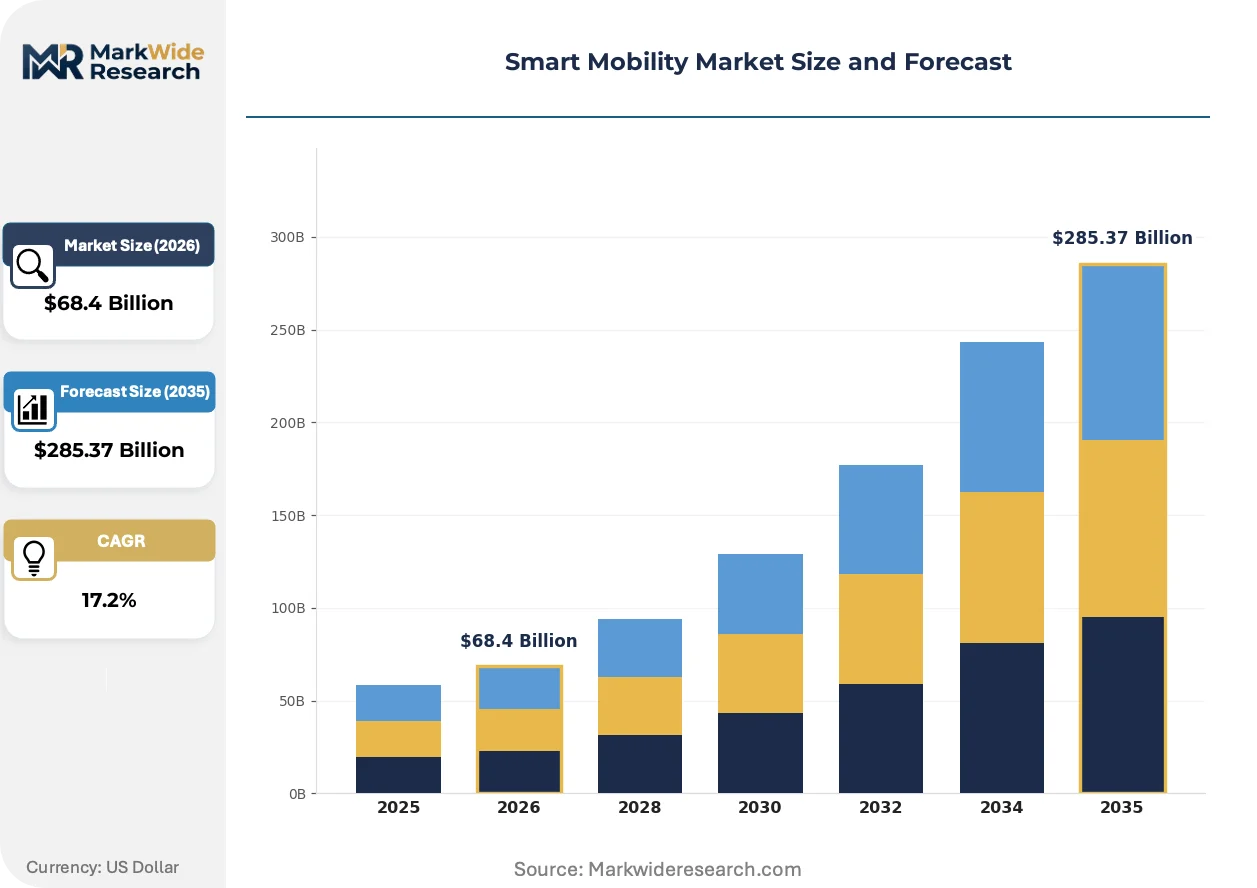
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $285.37 Billion |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AI, IoT, Blockchain, V2X Vehicle Type: Passenger Cars, Buses, Two-Wheelers, E-Scooters Service Type: Ride-Hailing, Car-Sharing, Public Transport, Fleet Management End User: Commute, Logistics, Tourism, Delivery Services |
| Companies Covered | Xplor, Cerebrum Sensor Technologies, Bolt, Cowboy, Vammo, Metropolis, ZeroAvia, IZI Electric, Devamapp Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Mobility Market Strategic Shifts & Innovations
Digital integration across transportation modes is collapsing the boundary between public transit and on-demand services, with platform economics now dictating infrastructure investment priorities.
Solid-state battery chemistry is rewriting range and safety parameters for electric fleet deployment. Commercial operators in Japan are piloting silicon-anode configurations that halve charging dwell times. This compression of energy replenishment cycles is rewriting utilization rate assumptions for high-frequency urban services.
CSRD sustainability disclosure requirements are mandating granular emissions reporting across mobility value chains. Fleet operators must now track Scope 3 data from vehicle manufacturing through end-of-life processing. European capital deployment is shifting toward providers with certified circular supply chain documentation.
Corporate mobility budgets are consolidating around integrated travel platforms that subsume individual mode subscriptions. Large enterprises in Germany are replacing separate rail, ride-hail, and rental contracts with unified spend-management tools. This procurement concentration favors platforms demonstrating multimodal API depth over single-service specialists.
Smart Mobility Market Segmentation
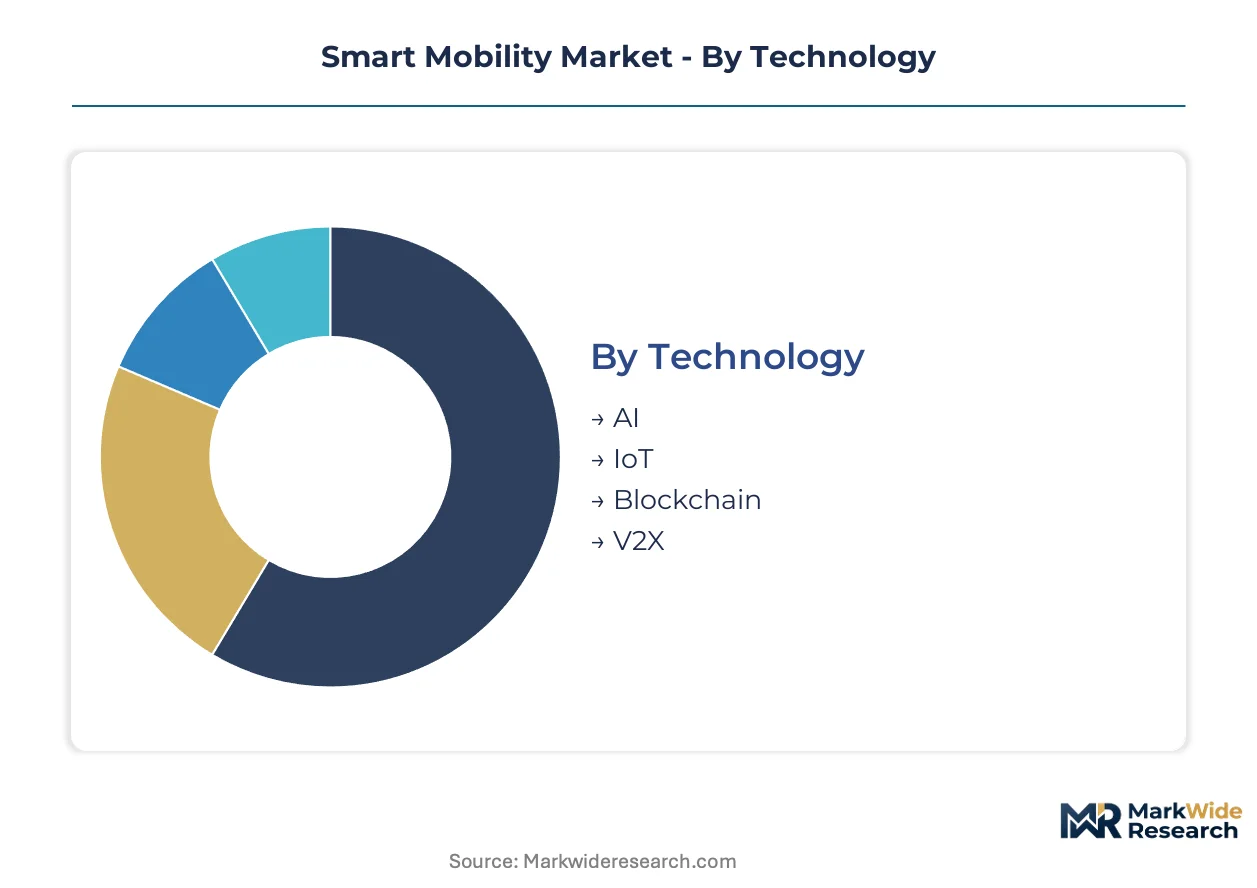
Smart mobility segmentation reveals how regulatory certification burdens cluster around specific technology stacks and vehicle classes. Procurement decisions increasingly hinge on which segments carry lighter compliance overhead for cross-border deployment.
Technology:
FAA certification timelines govern AI flight systems, while NHTSA V2X mandates and EU AI Act conformity assessments create divergent approval pathways for connected vehicle technologies.
- AI:Machine learning models power predictive fleet routing and autonomous navigation systems. Demand concentrates in Seoul's municipal transit expansions where Korean authorities mandate AI-driven predictive maintenance for public bus networks.
- IoT:Sensor networks enable real-time vehicle telemetry and infrastructure monitoring. German urban corridors drive procurement as fleet operators seek CSRD-compliant emissions tracking across multimodal trip chains.
- Blockchain:Distributed ledger architectures secure mobility transaction records and vehicle identity verification. Pilot deployments focus on corporate mobility budget consolidation in enterprise procurement.
- V2X:Vehicle-to-everything protocols enable direct communication between vehicles, infrastructure, and pedestrians. NHTSA mandates are accelerating US metropolitan corridor deployments despite heterogeneous spectrum allocation.
Leading the category by volume: IoT. Growing fastest: V2X.
Vehicle Type:
Cost tier stratification separates premium electrified fleets from asset-light micro-mobility units, with battery chemistry choices driving depreciation schedules.
- Passenger Cars:Electrified sedans and SUVs dominate subscription bundling models combining vehicles, charging, and insurance. German corporate fleets are consolidating procurement around unified mobility platforms.
- Buses:High-capacity electric and hydrogen-electric configurations serve fixed-route municipal transit. EU Green Deal emissions benchmarks are compressing diesel fleet replacement timelines across European capitals.
- Two-Wheelers:Compact electric motorcycles and mopeds optimize dense urban penetration. IZI Electric sustains market position through purpose-built designs for Southeast Asian street geometries.
- E-Scooters:Dockless shared micro-mobility units face regulatory caps on fleet sizes in most jurisdictions. Unit economics hinge on battery swap logistics and vandalism loss rates.
Highest deployment density: Passenger Cars. Steepest expansion trajectory: E-Scooters.
Service Type:
Margin structure varies sharply between asset-heavy fleet ownership and platform-mediated access models.
- Ride-Hailing:On-demand passenger transport platforms capture premium margins through dynamic pricing algorithms. Network effects concentrate demand in Bolt's European capital density.
- Car-Sharing:Station-based and free-floating vehicle access models serve intermittent mobility needs. Municipal parking privileges determine competitive positioning.
- Public Transport:Digitally integrated bus and rail services with AI-powered fleet orchestration. Seoul's deployments demonstrate scalable predictive maintenance models.
- Fleet Management:Commercial vehicle oversight combining telematics, routing optimization, and compliance tracking. REACH battery recycling rules are reshaping end-of-life obligations.
Dominant revenue pool: Ride-Hailing. Gaining share fastest: Fleet Management.
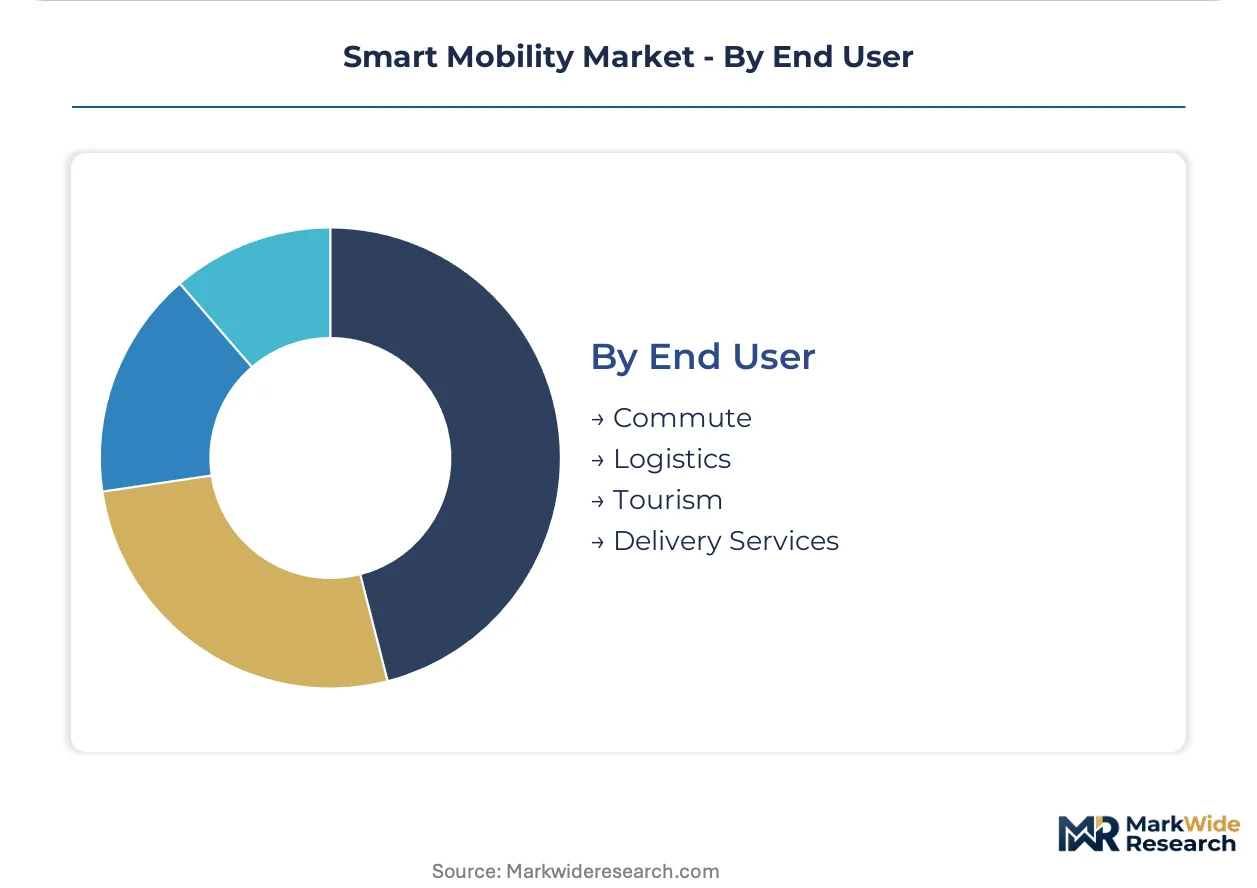
End User:
Customer type segmentation maps directly to trip frequency patterns and willingness-to-pay for integrated multimodal coordination.
- Commute:Regular daily travel patterns favor subscription models and transit pass integration. German enterprises are replacing separate mode contracts with unified spend-management tools.
- Logistics:Commercial freight and last-mile delivery services prioritize route efficiency over passenger comfort. Solid-state battery pilots in Japan target dwell time reduction for high-frequency operations.
- Tourism:Intermittent leisure travel drives demand for flexible, non-committed access models. Airport connectivity and city center penetration determine platform selection.
- Delivery Services:Food and parcel courier fleets operate under gig-economy cost structures. Two-wheeler electrification dominates Southeast Asian market development.
Largest addressable base: Commute. Expanding most quickly: Delivery Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart mobility production clusters concentrate in East Asian battery supply chains while consumption gravity shifts toward European and North American urban corridors with stringent emissions mandates. This geographic split creates procurement dependencies that shape fleet operator investment timelines.
Germany
Corporate fleet electrification and municipal transit procurement drive German demand concentration. The EU Green Deal's binding emissions benchmarks compress diesel replacement schedules for urban bus networks. Berlin and Munich anchor integrated mobility platform deployments where unified spend-management tools consolidate multimodal contracts.
South Korea
AI-powered fleet orchestration and predictive maintenance systems dominate Korean municipal procurement priorities. Seoul's transit authority mandates machine learning-driven routing for public bus networks under national smart city directives. The capital region demonstrates scalable models that neighboring Asian metros are replicating.
United States
NHTSA V2X mandates unlock real-time traffic optimization investments across dense metropolitan corridors. FAA certification pathways for urban air mobility create extended validation timelines that compress operator first-mover windows. California and Texas lead state-level deployments with divergent spectrum allocation approaches.
Japan
Solid-state battery pilots target dwell time reduction for high-frequency commercial operations. METI funding programs accelerate silicon-anode configuration testing in Osaka and Nagoya industrial zones. Domestic OEMs leverage captive cell production to secure supply for next-generation fleet electrification.
India
Last-mile delivery electrification and two-wheeler fleet conversion dominate Indian demand patterns. PLI scheme incentives for advanced chemistry cell manufacturing reshape domestic battery pack assembly economics. Maharashtra and Karnataka host emerging EV component clusters serving Southeast Asian export markets.
Smart Mobility Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across technology layers and service modalities. Market structure tilts toward platform-mediated network effects in ride-hailing and asset-heavy fleet ownership in electrified transit. Three archetypes dominate: integrated mobility platforms bundling multimodal access, battery-electric vehicle OEMs with captive charging infrastructure, and AI-native routing software vendors. Competitive intensity centers on geographic density accumulation and strategic partnerships with municipal procurement authorities.
Among European mobility platforms, Bolt exemplifies network-effect concentration through ride-hailing density anchoring urban fleet electrification. ZeroAvia occupies a position within hydrogen-electric propulsion specialists targeting regional aviation certification pathways. IZI Electric represents compact two-wheeler designers purpose-built for dense Southeast Asian street geometries.
| Leading Market Players |
|---|
| Xplor |
| Cerebrum Sensor Technologies |
| Bolt |
| Cowboy |
| Vammo |
| Metropolis |
| ZeroAvia |
| IZI Electric |
| Devamapp Mobility |
| Others |
Cost & Logistics Intelligence
Solid-state battery chemistry transitions are simultaneously compressing energy replenishment costs and redrawing cathode precursor procurement maps as silicon-anode configurations halve charging dwell times for high-frequency fleet operators.
Pricing Analysis
Margin tightening in electrified fleet tiers reflects lithium-ion cell cost volatility and REACH compliance overhead for end-of-life processing. Three-tier pricing structure across premium, standard, and economy levels separates AI-native routing platforms from legacy telematics providers from asset-light micro-mobility units. Cost-down pressure on battery pack assembly accelerates because cathode precursor refining clusters concentrate in select Asian geographies. Municipal transit authorities demonstrate lowest price sensitivity due to EU Green Deal procurement mandates, while gig-economy delivery fleets operate under highest cost compression.
Supply Chain Analysis
Cathode precursor supply rests on South Korean, Chinese, and Japanese specialty chemical producers with captive refining capacity. Lithium carbonate, nickel sulfate, and cobalt hydroxide feed from Chilean brine operations, Indonesian laterite mines, and DRC artisanal clusters. Single-source vulnerability concentrates in high-purity electrolyte solvents where three producers dominate global volume. Distribution runs through Tier 1 battery pack assemblers serving OEM direct contracts and aftermarket retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Mobility Market functions as a cost-of-compliance arena where EU Green Deal emissions benchmarks and FAA certification pathways erect regulatory moats favoring players with documented circular supply chain credentials.
For Market Incumbents: Deepen backward integration into battery cell production to secure supply for next-generation fleet electrification and anchor margin defense against emerging AI-native routing software vendors. Fortify municipal procurement relationships through predictive maintenance platform deployments that demonstrate quantified uptime improvements under CSRD disclosure requirements. For New Entrants and Emerging Players: API-first integration layers offer the most penetrable entry vector for corporate mobility budget consolidation in German enterprise accounts. White-space concentrates in multimodal trip orchestration where fragmented standards between ride-hailing, transit, and micro-mobility operators complicate unified planning. Target fleet management software for logistics operators seeking REACH-compliant battery lifecycle tracking. For Investors and Strategic Acquirers: Re-rating potential sits with hydrogen-electric propulsion specialists given FAA certification pathway acceleration for regional aviation zero-emission range credentials. Long-term viability favors asset-light platform models with demonstrated network-effect density in European capital corridors. Watch NHTSA V2X mandate implementation timelines as inflection indicator for real-time traffic optimization infrastructure spend.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cathode precursor offtake from South Korean refiners for fleet electrification scale. |
| Platform Integration | Unifies multimodal API access for German corporate mobility budget consolidation. |
| Charging Infrastructure Partnership | Deploys silicon-anode fast-charging networks across Japan's Osaka industrial corridor. |
| Regulatory Certification Pathway | Accelerates FAA validation for urban air mobility hydrogen-electric propulsion systems. |
| Geographic Manufacturing Footprint | Establishes battery pack assembly in Maharashtra to serve Southeast Asian two-wheeler demand. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fleet operations directors, municipal procurement officers, battery supply chain managers, and AI systems integration specialists. Bottom-up unit economics modeling triangulated against top-down sector spend estimates from EU transport authority disclosures, NHTSA rulemaking dockets, and ECHA REACH implementation guidance.
Data-stream reconciliation across vehicle deployment databases, charging infrastructure registries, and platform transaction records informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include vehicle type, service modality, technology stack, and end-use application, with CAGRs derived from installed base turnover rates and procurement timeline compression under emissions mandates. Forecast inputs incorporated solid-state battery pilot results from Japanese METI programs and Seoul municipal AI fleet orchestration performance data.
Inputs from Korean smart city directive filings and German corporate mobility spend surveys were available through the study window; gaps in real-time V2X deployment metrics and urban air mobility certification timelines introduce uncertainty bands around network-effect timing assumptions. Forecasts reflect documented assumptions on regulatory compliance cost trajectories and battery chemistry transition curves. A small set of named triggers—including NHTSA spectrum allocation decisions, EU AI Act conformity assessment timelines, and lithium carbonate price volatility—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
North America Vehicle Tolling System Market
Smart Transportation Solutions
Middle East and Africa Passenger Information System Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Intelligent Airways Transportation Market
Smart Transportation Solutions
Scooter Sharing Market
Smart Transportation Solutions
Advanced Traffic Management System (ATMS) Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Traffic Signal Controller Market