
 Rail Transit Traction Converter Market | 2026-2036
Rail Transit Traction Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Transit Traction Converter Market Insights
EN 50207 qualification is unwinding the competitive landscape for European traction converter suppliers. ABB leverages its broad power electronics portfolio to serve multiple rail electrification standards across continents. Siemens anchors its position through deep integration with rolling stock platforms and signaling systems. CRRC dominates procurement within China's state-directed rail ecosystem, competing primarily on manufacturing scale and domestic supply chain control.
A rail transit traction converter transforms and conditions electrical power between the catenary supply and traction motors, typically handling input voltages from 15 kV AC to 25 kV AC or 1.5 kV DC to 3 kV DC while regulating output frequency and voltage for precise motor torque control. Static converters lead product category revenue due to widespread deployment in mainline electrification, while inverter converters represent the fastest-growing segment as light rail operators seek regenerative braking and energy recovery capabilities. IGBT technology remains the installed base standard, though MOSFET technology is capturing design wins in next-generation onboard systems where efficiency and thermal density priorities are intensifying.
FRA safety standards and EU F-Gas Regulation are tightening material and cooling system specifications for North American and European traction converter deployments. China's GB/T standards and NMPA-aligned rail certification processes govern domestic procurement requirements, while India's CEA grid codes and BIS electromagnetic compatibility rules shape converter interface obligations for metro projects. Stakeholders must track semiconductor supply resilience and evolving efficiency mandates across certification jurisdictions to align R&D roadmaps with procurement timelines.
Market Dynamics
Silicon carbide semiconductor substitution is compressing converter form factors while tightening thermal management requirements across rolling stock platforms. This materials transition is redrawing supplier qualification hierarchies and forcing cooling system redesigns at the subsystem level.
Growth Catalysts
- India's CEA Grid Code Alignment:Metro electrification mandates in Mumbai, Delhi, and Bangalore are mandating regenerative braking compatibility, pulling demand for advanced inverter architectures.
- Silicon Carbide Traction Modules:Wide-bandgap semiconductors are cutting switching losses by half versus IGBT baselines, enabling lighter onboard power electronics for high-speed rail.
- China's Dual Carbon Goals:State-directed rail electrification targets are accelerating fleet replacement cycles and expanding procurement windows for domestic converter suppliers.
Market Restraints
- Silicon Carbide Substrate Concentration:Wafers for traction-grade MOSFETs concentrate among Japanese and US substrate growers, exposing supply continuity risk.
- EU F-Gas Cooling System Phase-Down:Fluorinated gas restrictions are forcing refrigerant transitions in liquid-cooled converter designs before alternative thermal architectures mature.
- Copper and Rare Earth Magnet Cost Volatility:Traction motor integration costs swing with commodity markets, compressing converter-motor system margins.
Strategic Opportunities
- Southeast Asia Urban Rail Buildout:Vietnam, Indonesia, and Thailand are tendering first-generation metro systems without legacy electrification lock-in.
- Digital Twin Predictive Maintenance:Converter health monitoring platforms are opening recurring revenue streams separate from hardware procurement cycles.
- India's PLI Scheme for Rail Components:Domestic manufacturing incentives are creating localized supply chain slots for foreign converter technology licensors.
Industry Challenges
- EN 50207 Certification Timeline Compression:European qualification protocols for new semiconductor architectures extend development cycles beyond typical procurement windows.
- Embedded Software Functional Safety:ISO 26262-aligned toolchains for rail traction control are scarce, constraining SIL-rated firmware development capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Transit Traction Converter Market |
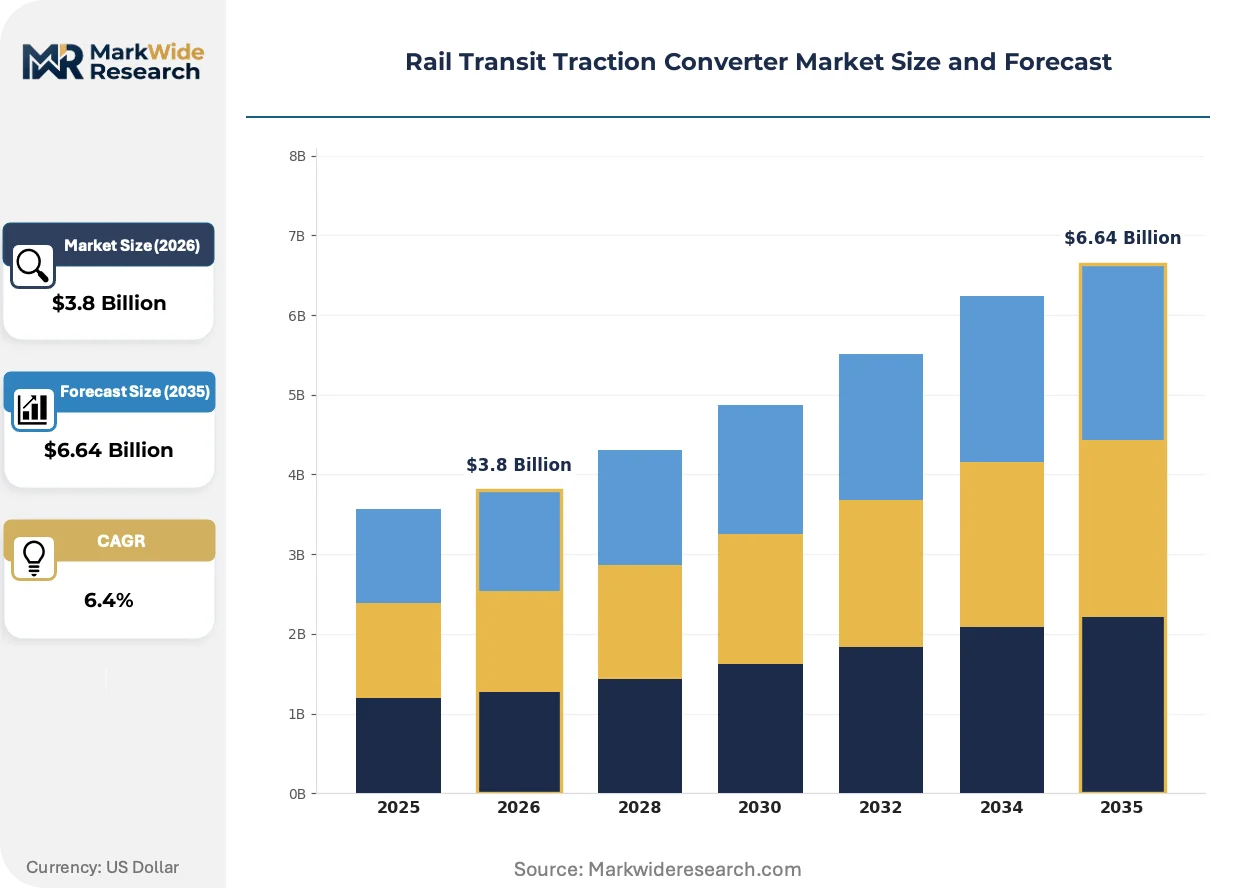
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Converters, Inverter Converters, DC-DC Converters, Traction Power Supply Application: Electric Locomotives, Light Rail Vehicles, High-Speed Trains, Freight Trains Installation: Onboard Systems, Ground-Based Systems, Hybrid Systems, Retrofitted Units Technology: IGBT Technology, MOSFET Technology, Thyristor Technology, Others |
| Companies Covered | ABB, Siemens, CRRC, Alstom, Mitsubishi Electric, Hitachi, Toshiba, Ingeteam, CAF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Transit Traction Converter Market Trends and Innovations
Power semiconductor architecture is pivoting from silicon IGBT dominance toward wide-bandgap materials, while regulatory pressure on cooling chemistries and thermal efficiency is tightening design constraints simultaneously.
Silicon carbide MOSFET traction modules are miniaturizing onboard converter footprints while sustaining higher switching frequencies. Japanese and European rolling stock OEMs are qualifying these devices for mainline deployments starting with auxiliary power units. The technology is miniaturizing cooling system mass by thirty to forty percent versus equivalent IGBT designs, freeing underframe space for battery integration.
The EU F-Gas Regulation is banning high-global-warming-potential refrigerants in liquid-cooled traction equipment from 2030. Converter suppliers must redesign thermal loops around CO2 or hydrofluoroolefin alternatives before qualification cycles complete. European metro operators in Germany and France are specifying F-Gas-compliant cooling in current tenders to avoid mid-life retrofit liability.
Outcome-based availability contracts are displacing unit-price procurement for traction power electronics. Rail operators in the UK and Nordic markets are contracting converter performance per train-kilometer rather than capital expenditure, transferring operational risk to subsystem suppliers. This restructures supplier cash flows toward long-term service revenue and demands predictive maintenance infrastructure investment.
Rail Transit Traction Converter Market Segmentation
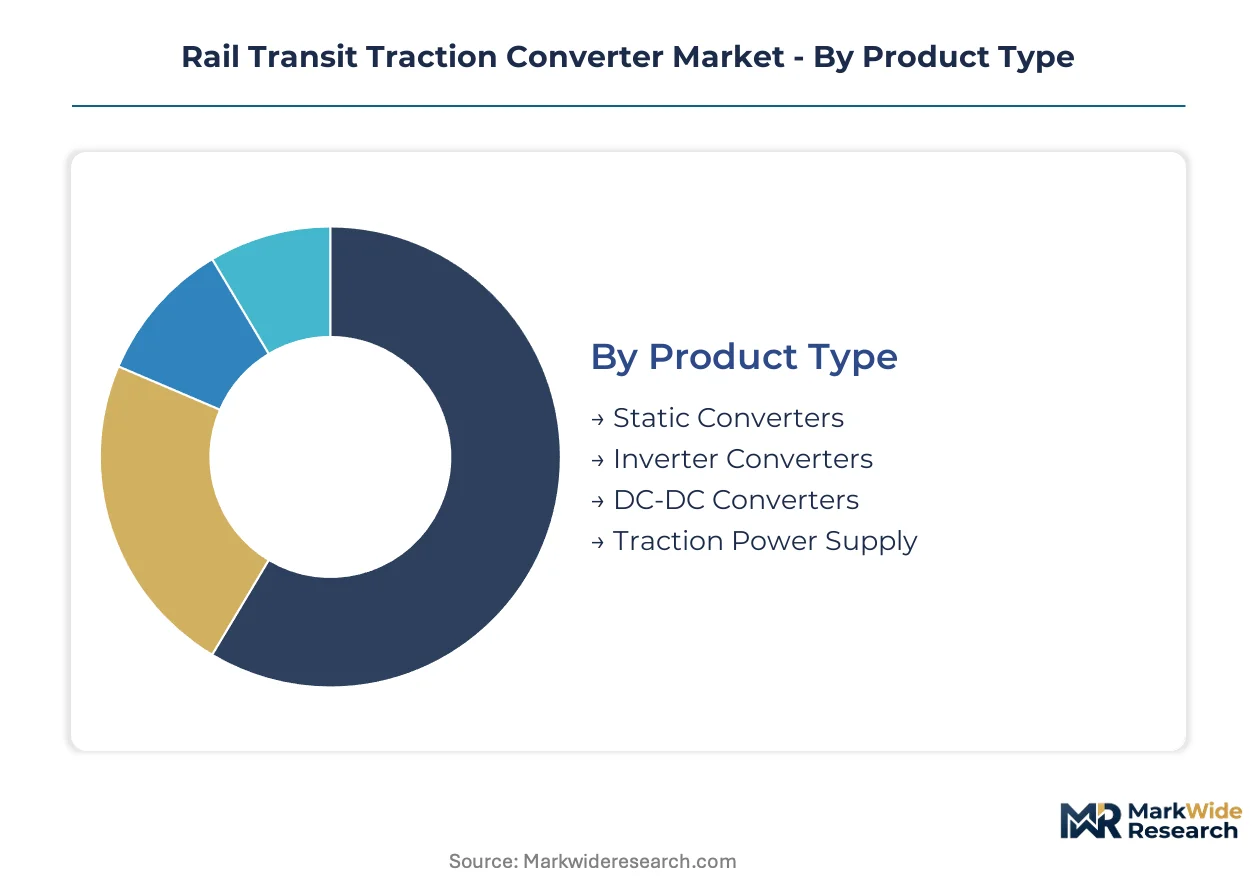
Traction converter procurement patterns diverge sharply across electrification architectures and rolling stock platforms. Semiconductor technology transitions and cooling system regulations are fragmenting supplier qualification pathways by segment.
Product Type:
EN 50207 and GB/T standards impose divergent efficiency and electromagnetic compatibility thresholds across converter architectures, forcing technology-specific certification investments.
- Static Converters:These units transform fixed-frequency catenary supply into variable-frequency output for AC traction motors using diode or thyristor rectification stages. Mainline operators in Germany and France specify static converters for 15 kV AC electrification corridors where regenerative braking recovery remains secondary to capital cost control.
- Inverter Converters:Four-quadrant inverter architectures enable bidirectional power flow between catenary and traction motors, capturing braking energy for network redistribution. Metro procurement in Mumbai, Delhi, and Bangalore mandates inverter compatibility under CEA grid code alignment, pulling demand from light rail electrification programs.
- DC-DC Converters:Voltage step-down units interface battery energy storage with traction bus architectures in hybrid locomotives.
- Traction Power Supply:Wayside rectifier substations feed third-rail or overhead contact systems in urban tunnel networks.
Established volume favors static converters; emerging adoption favors inverter converters.
Application:
Operating speed regimes and duty cycles dictate thermal management complexity and semiconductor switching frequency requirements.
- Electric Locomotives:Heavy-haul platforms operating 25 kV AC corridors require megawatt-scale converter capacity with sustained overload tolerance for gradient climbing. Indian Railways' freight electrification push under the Dedicated Freight Corridor Corporation concentrates procurement for 12-axle locomotives hauling 6,000-tonne consists.
- Light Rail Vehicles:Low-floor tram designs impose severe height and mass constraints on onboard power electronics, favoring silicon carbide MOSFET integration. Czech and Polish tram operators are specifying liquid-cooled inverter packages under 400 kg for 100% low-floor architectures.
- High-Speed Trains:Traction converters for 300+ km/h operation prioritize switching loss minimization and aerodynamic packaging.
- Freight Trains:Hybrid diesel-electric and battery-tender configurations are creating demand for multi-source power management converters.
Revenue concentration sits with electric locomotives; technology innovation concentrates in light rail vehicles.
Installation:
Retrofit economics versus new-build procurement timelines are reshaping supplier engagement models across installation modes.
- Onboard Systems:Underframe-mounted converter packages must survive shock, vibration, and thermal cycling across climate zones from Saudi Arabia's desert corridors to Nordic winter operations. China's Fuxing high-speed fleet specifies IP54-enclosed onboard converters with 30-year design life.
- Ground-Based Systems:Wayside traction substations eliminate onboard mass penalties but require heavy copper feeder cable infrastructure and sectioning station complexity.
- Hybrid Systems:Dual-mode locomotives switching between diesel-electric and electric traction demand seamless converter reconfiguration.
- Retrofitted Units:Mid-life locomotive modernization programs in Eastern Europe and Latin America are creating aftermarket demand for drop-in IGBT replacements of legacy thyristor equipment.
New-build procurement dominates ground-based systems; fleet renewal cycles drive retrofitted unit demand.
Technology:
Wide-bandgap semiconductor maturity is compressing the technology hierarchy that silicon IGBT dominance established over three decades.
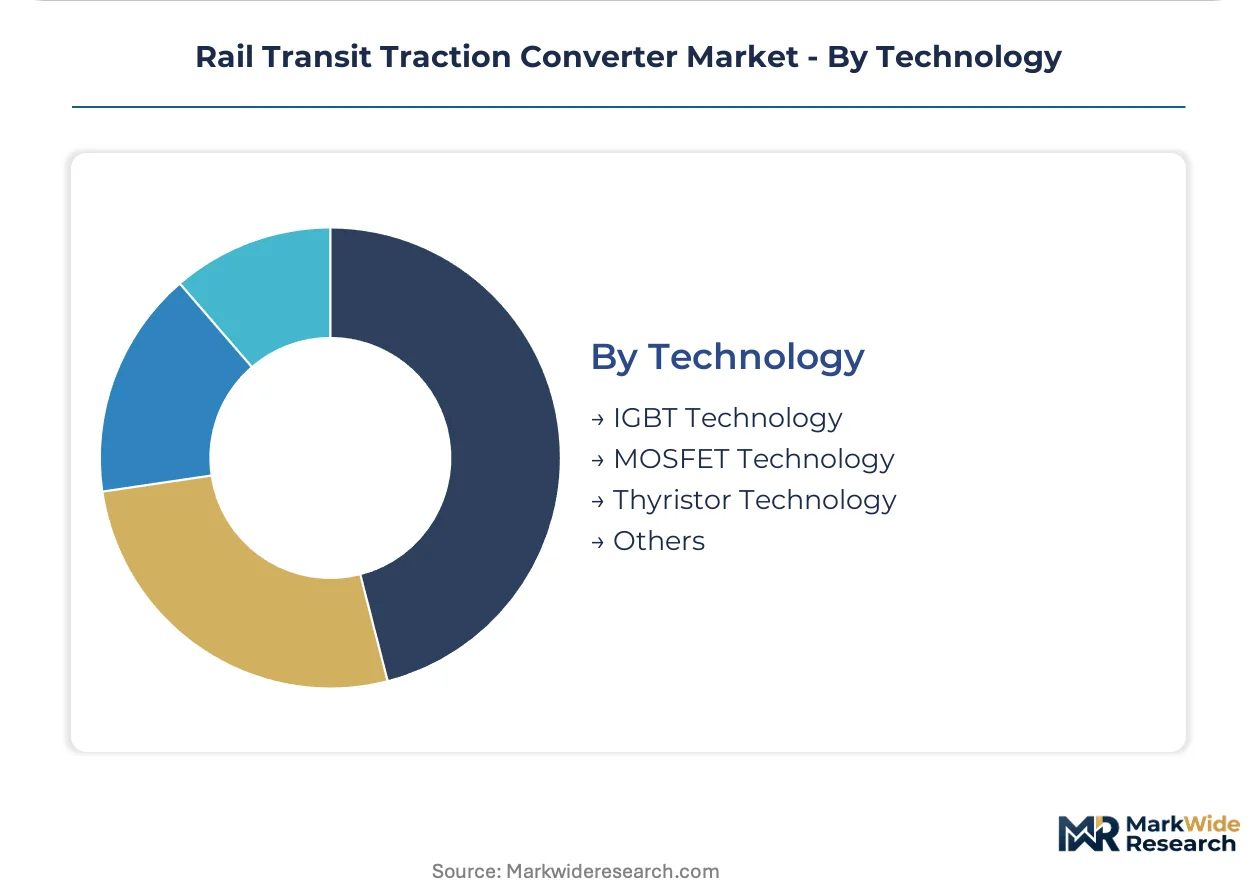
- IGBT Technology:Insulated-gate bipolar transistors remain the installed base standard for traction converters above 1 MW, with mature supply chains and qualified module packaging from Japanese and European suppliers. Indian metro tenders continue specifying IGBT-based traction inverters for 25 kV AC and 750 V DC electrification to leverage established maintenance protocols.
- MOSFET Technology:Silicon carbide MOSFETs enable switching frequencies above 20 kHz versus 1-2 kHz for silicon IGBTs, shrinking filter magnetics and cooling system mass by 35-40%. Japanese rolling stock OEMs are qualifying SiC traction modules for auxiliary power units ahead of mainline deployment.
- Thyristor Technology:Phase-controlled rectifiers persist in legacy locomotive fleets and cost-sensitive freight applications.
- Others:Gallium nitride devices and emerging ultra-wide-bandgap materials remain pre-qualification for traction power levels.
IGBT technology anchors current procurement volume; MOSFET technology is gaining share fastest in next-generation platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-directed rail electrification programs and urban transit expansion mandates are concentrating procurement across Asia-Pacific and European corridors. China's dual carbon targets and India's metro buildout anchor volume, while European F-Gas compliance deadlines reshape supplier qualification requirements.
China
High-speed rail network expansion and fleet replacement cycles under GB/T standards dominate procurement volume. NMPA-aligned rail certification processes govern domestic converter specifications for the Fuxing high-speed fleet. The Yangtze River Delta corridor concentrates manufacturing capacity for silicon carbide traction modules serving 350 km/h operations.
India
Mumbai, Delhi, and Bangalore metro electrification mandates under CEA grid codes require regenerative braking compatibility. The PLI scheme for rail components creates localized manufacturing slots for foreign technology licensors. Maharashtra and Karnataka industrial corridors host emerging converter assembly capacity for 25 kV AC and 750 V DC electrification.
Germany
15 kV AC mainline corridors and EN 50207 qualification standards shape converter efficiency thresholds. The EU F-Gas Regulation accelerates refrigerant transitions in liquid-cooled designs before 2030 deadlines. Bavaria and Baden-Württemberg host rolling stock OEM integration facilities specifying static converters for freight electrification.
Japan
Silicon carbide MOSFET qualification for auxiliary power units precedes mainline traction deployment. METI semiconductor supply chain initiatives address substrate concentration risks among domestic wafer growers. The Kanto and Kansai corridors concentrate OEM engineering centers qualifying wide-bandgap devices for next-generation Shinkansen platforms.
United States
FRA safety standards tighten material and cooling system specifications for commuter rail modernization. Outcome-based availability contracts in Northeast Corridor operations transfer operational risk to subsystem suppliers. The Pacific Northwest and Midwest industrial clusters host retrofit demand for legacy thyristor-to-IGBT conversions.
Rail Transit Traction Converter Market Competitive Landscape
Player mix skews toward diversified electrical engineering conglomerates with power electronics portfolios spanning multiple rail electrification standards. Market structure concentrates around three strategic archetypes: integrated rolling stock OEMs with captive converter divisions, independent power electronics specialists serving multiple OEMs, and state-affiliated manufacturers operating within protected domestic procurement ecosystems. Competitive moves center on silicon carbide semiconductor supply partnerships and cooling system redesigns to meet F-Gas phase-down timelines.
Within the diversified conglomerate tier, ABB and Siemens occupy positions defined by cross-continental electrification standard coverage and deep rolling stock platform integration. CRRC exemplifies the state-affiliated archetype, anchoring procurement within China's GB/T-governed domestic ecosystem. Mitsubishi Electric and Hitachi represent Japanese-based specialists qualifying wide-bandgap traction modules for auxiliary power applications ahead of mainline deployment.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| CRRC |
| Alstom |
| Mitsubishi Electric |
| Hitachi |
| Toshiba |
| Ingeteam |
| CAF |
| Others |
Pricing and Supply Chain Analysis
EN 50207 qualification gates simultaneously determine supplier eligibility and price positioning tiers across European traction converter procurement, compressing margins for unqualified vendors while enabling certified specialists to capture service-integrated premiums. Buyers in Germany and France face extended lead times for qualified suppliers, tightening price negotiation leverage for converter-motor system packages.
Pricing Analysis
Certification level under EN 50207 and GB/T standards creates the primary spread between premium and standard pricing tiers. Three-tier pricing structure across EN 50207-certified, GB/T-compliant, and non-certified economy levels separates rolling stock OEM integrated suppliers from independent power electronics specialists. Cost compression in the economy tier is intensifying because Indian and Southeast Asian metro operators prioritize first-cost minimization over lifecycle efficiency. State-affiliated rail ecosystems in China exhibit lowest price sensitivity due to captive procurement channels, while private light rail operators in Poland and Czech Republic drive hardest bargain on per-unit converter pricing.
Supply Chain Analysis
Strategic stockpiling of silicon carbide substrates and rare earth magnet precursors dominates inventory strategy among Japanese and European converter suppliers confronting wafer supply concentration. Manufacturing concentration centers on China, Japan, and Germany for traction-grade power modules, with substrate growth anchored in Japanese and US facilities. Converter assembly draws from copper busbar suppliers in Germany, ceramic substrate fabricators in Japan, and magnet wire producers in China. Single-source vulnerability in silicon carbide wafer supply exposes qualification timelines to disruption. Distribution runs through rolling stock OEM captive channels and independent subsystem suppliers serving aftermarket modernization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sustains defensive moats through regulatory entrenchment—EN 50207 and GB/T certification timelines create switching costs that lock qualified suppliers into multi-year platform relationships and deter rapid competitive entry.
For Market Incumbents: Shield installed base revenue by deepening silicon carbide semiconductor partnerships before Japanese substrate growers allocate capacity to automotive EV demand. Secure captive cooling system redesign capabilities ahead of EU F-Gas 2030 phase-down deadlines. Prioritize certification investment in India's CEA grid code alignment to capture PLI scheme localization slots.
For New Entrants and Emerging Players: Lead with digital twin predictive maintenance platforms as a service wedge, targeting UK and Nordic rail operators already contracting availability per train-kilometer. Southeast Asia's first-generation metro buildout in Vietnam, Indonesia, and Thailand offers most penetrable geography given absence of legacy electrification lock-in. Partner with established semiconductor distributors to bypass direct qualification barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon carbide traction module sub-segments as substrate qualification investments compound. Long-term viability over the next decade favors suppliers with demonstrated EN 50207 track records and integrated cooling system capabilities. Target acquisition archetype: mid-tier power electronics specialists with pending GB/T certification and established relationships with CRRC or Indian Railways. Signal to monitor: Japanese METI semiconductor supply chain initiative disbursement rates indicating domestic wafer capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Qualification | EN 50207 certification for wide-bandgap devices opens premium tier positioning against IGBT incumbents. |
| F-Gas Compliant Cooling Redesign | CO2 thermal loop deployment ahead of 2030 EU deadlines secures German and French metro tender eligibility. |
| India PLI Localization Partnership | Domestic assembly slots under CEA grid code alignment capture Mumbai and Delhi metro procurement windows. |
| Digital Twin Platform Development | Predictive maintenance infrastructure enables outcome-based availability contracts in UK and Nordic markets. |
| Southeast Asia Distribution Buildout | First-mover positioning in Vietnam, Indonesia, and Thailand metro electrification tenders avoids legacy lock-in. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and OEM technical specifications to validate market sizing and competitive positioning assessments. Primary interviews engaged rolling stock platform engineers, traction power electronics procurement managers, rail operator maintenance directors, and semiconductor supply chain specialists across China, India, Germany, Japan, and the United States. Secondary validation incorporated EN 50207 certification registries, GB/T standard documentation, EU F-Gas Regulation implementation guidance, Indian CEA grid code amendments, and customs trade data for power semiconductor imports. Bottom-up unit economics modeling triangulated against top-down rail electrification investment forecasts.
Segmentation dimensions modeled span product type, application, installation mode, and semiconductor technology across the projection horizon. Analytical framework derived CAGRs from rolling stock delivery schedules, fleet replacement cycles, and electrification program commitments without reliance on macroeconomic extrapolation. Industry-specific forecast inputs incorporated silicon carbide substrate supply pipeline visibility and EN 50207 qualification timeline compression effects on new entrant market access.
The analysis sits within stated boundaries; outcomes outside sustained rail electrification policy support or stable semiconductor supply continuity would require recalibration. Forecasts reflect documented assumptions regarding certification protocol stability and cooling system technology transition rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Train Bogie Market
Railway
Rail Glazing Market
Railway
Global Train Brake Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Railroad Brake Shoe Market
Railway
Rail Seat Market
Railway
Automatic Train Supervision Market
Railway
Locomotive Radiator Fan Market
Railway
Railroad Tie Market
Railway
Train Suspension System Market
Railway
Locomotive Maintenance Market
Railway
Freight Cars Market
Railway
Solar Train Market
Railway
Automatic Train Control Market
Railway
Connected Rail Market
Railway
Rolling Stock Management Market