
 Latin America Container Terminal Operations Market | 2026-2036
Latin America Container Terminal Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Container Terminal Operations Market Foresight
ISO 28000 supply chain security certification is rotating competitive access across Latin American container terminals, filtering concession bids and operator qualifications. DP World leverages its integrated logistics platform across regional hubs to sustain multi-country coordination. Brasil Terminal Portuário S.A. anchors Brazil's largest container gateway at Santos with dedicated berth infrastructure. APM Terminals Callao competes on Peru's Pacific corridor through specialized cold chain handling capabilities.
Container terminal operations encompass the mechanized transfer, staging, and documentation of intermodal freight units between vessel and hinterland transport modes, utilizing gantry cranes with 40-65 metric ton lifting capacity and terminal operating systems processing 30+ moves per crane hour. The terminal type dimension shows deep water facilities commanding premium throughput fees while transshipment nodes capture growing Panama Canal relay volumes. Automation technology segments reveal RFID-tracked yard management outpacing IoT sensor deployment due to faster implementation cycles and clearer ROI thresholds.
Brazil's national port regulator ANTAQ enforces concession compliance standards that dictate minimum cargo handling efficiency benchmarks and environmental mitigation protocols. Peru's OSINERGMIN and Colombia's Superintendencia de Puertos maintain parallel frameworks governing tariff structures and service level agreements. Stakeholders must monitor evolving concession renewal timelines and automation investment thresholds to secure operational continuity across the region's fragmented regulatory landscape.
Market Dynamics
Panama Canal expansion protocols and Brazilian port modernization mandates under the PLI-equivalent concession framework are compressing investment timelines while elevating automation thresholds across Latin American container terminals. These dual pressures are forcing operators to reconfigure capital deployment strategies ahead of concession renewal cycles.
Growth Catalysts
- Refrigerated container volumes:Brazilian agribusiness exporters are expanding cold chain throughput through Santos and Paranaguá terminals, driven by soybean and meat export mandates.
- ANTAQ concession compliance:Brazil's national port regulator enforces minimum cargo handling efficiency benchmarks that accelerate berth infrastructure upgrades.
- RFID-tracked yard management:Faster implementation cycles and clearer ROI thresholds are outpacing IoT sensor deployment in terminal automation investments.
Market Restraints
- Deep water facility concentration:Premium throughput fees concentrate at Santos and Sepetiba Bay, limiting mid-size port competitiveness across Brazil's Southeast corridor.
- Environmental mitigation protocols:ANTAQ-mandated coastal protection and emissions controls add compliance layers that extend project approval timelines.
- Legacy gantry crane fleets:40-65 metric ton lifting capacity equipment at older terminals creates technical bottlenecks for ultra-large container vessel handling.
Strategic Opportunities
- Colombia's Pacific corridor:Buenaventura port expansion offers underpenetrated capacity for transshipment relay volumes displaced from saturated Caribbean routes.
- ISO 28000 certification gaps:Supply chain security credential shortages among mid-tier operators create competitive access rotation for qualified bidders.
- Terminal operating system convergence:Integration of automated gate systems with vessel stowage planning software is compressing vessel turnaround windows at greenfield developments.
Industry Challenges
- Automation technician scarcity:Crane automation and TOS integration require specialized skill sets that outpace regional vocational training output.
- Concession renewal alignment:Fragmented timelines across ANTAQ, OSINERGMIN, and Superintendencia de Puertos jurisdictions complicate multi-country operator portfolio planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Container Terminal Operations Market |
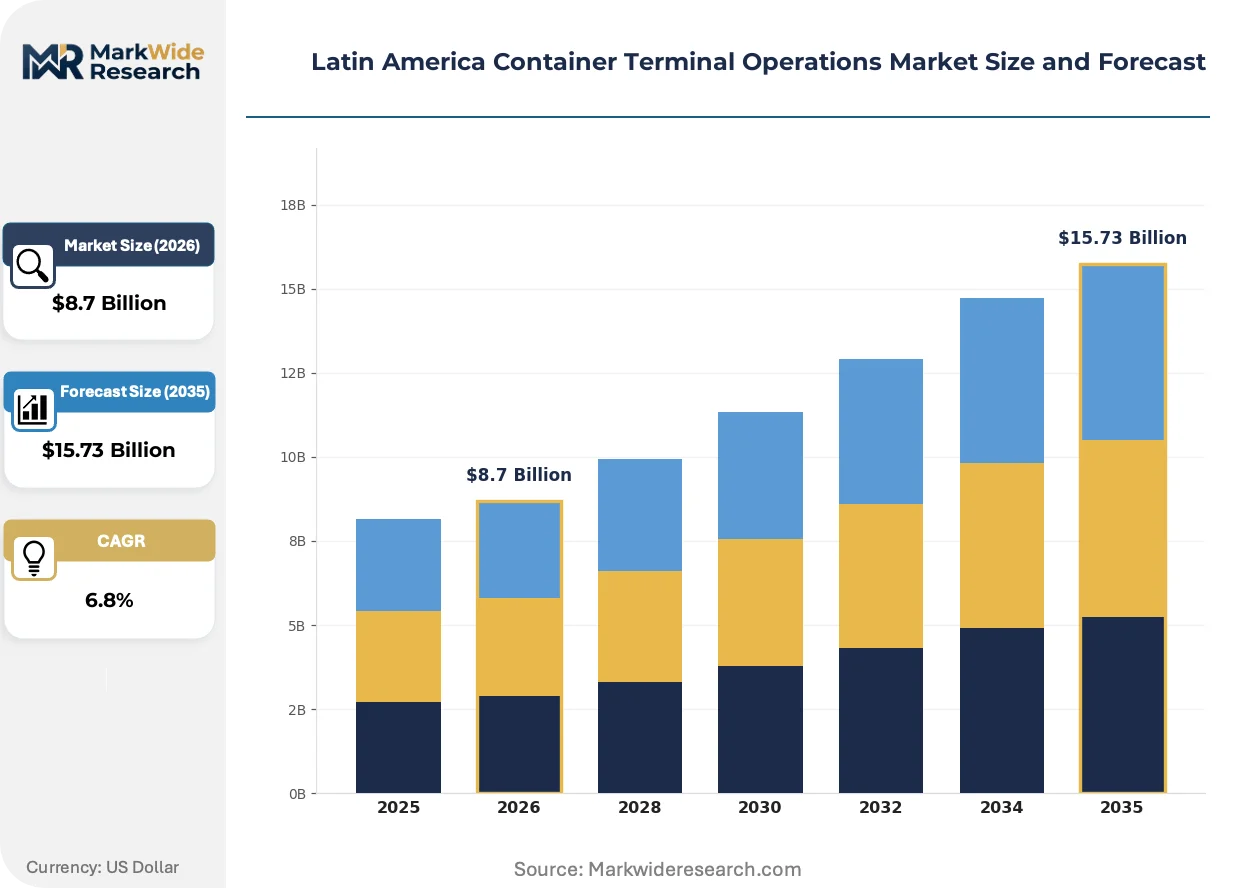
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Loading, Unloading, Maintenance, Storage Terminal Type: Deep Water, Transshipment, Regional, Inland Technology: Automation, RFID, IoT, Cloud Computing End User: Shipping Lines, Freight Forwarders, Logistics Providers, Importers |
| Companies Covered | The Port of Cartagena Organization, DP World, Brasil Terminal Portuário S.A., San Lorenzo Port Authority, Hutchinson Ports PPC, Santos Brasil Participacoes S/A, Maranhense Port Administration Company (EMAP), Kingston Wharves Limited, APM Terminals Callao, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Container Terminal Operations Market Shifts & Advancements
Automation technology deployment is accelerating across Latin American container terminals as operators face compressed concession renewal windows and elevated efficiency benchmarks. The competitive divide is widening between RFID-enabled facilities and legacy manual operations.
Automated stacking cranes equipped with optical character recognition are supplanting rubber-tired gantry systems at Brazil's greenfield terminal developments. DP World and regional operators are deploying these systems at Santos and Callao to achieve 30+ moves per crane hour. The technology is compressing labor cost structures while extending operational windows beyond traditional shift limitations.
ANTAQ's PLI-equivalent port concession framework is mandating minimum automation investment thresholds as a condition of bid qualification. The regulation is disqualifying undercapitalized bidders from Brazil's Southeast corridor renewals. Operators are responding by front-loading capex into terminal operating system upgrades and automated gate infrastructure.
Integrated logistics procurement models are consolidating hinterland transport contracts under single-operator umbrellas. Brazilian agribusiness exporters are shifting from fragmented trucking and rail negotiations to bundled vessel-to-warehouse agreements. This concentration is most visible in São Paulo state's soybean export corridors, where end-to-end service level agreements now dominate tender specifications.
Latin America Container Terminal Operations Market Segmentation
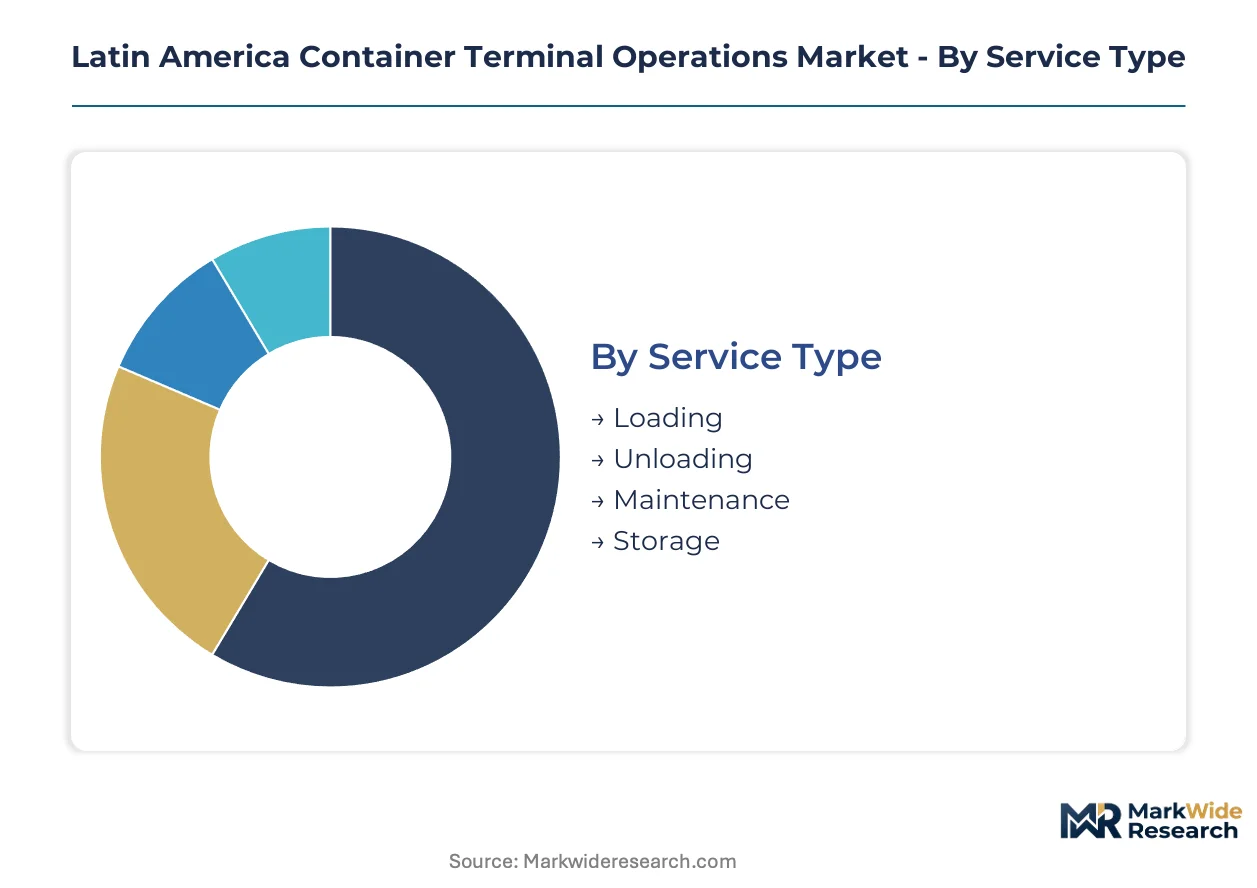
Container terminal operations in Latin America fragment across service tiers, infrastructure depth, and technology maturity. Each segment channels distinct cargo volumes through specific regulatory and investment pathways across Brazil, Peru, Panama, and Colombia.
Service Type:
Loading and unloading services flow through Santos and Callao as primary revenue channels, while maintenance and storage capture ancillary value from dwell-time extensions and equipment servicing contracts.
- Loading:Gantry crane operations transferring containers from vessel to shore with 40-65 metric ton lifting capacity. Demand concentrates at Santos where Brazilian agribusiness exporters push soybean volumes through dedicated refrigerated berths under ANTAQ efficiency mandates.
- Unloading:Reverse cargo flow operations handling import containers for São Paulo industrial corridors. Sepetiba Bay terminals capture growing consumer goods volumes as Rio de Janeiro's manufacturing hinterland expands.
- Maintenance:Crane servicing, berth dredging, and equipment calibration contracts. Panama Canal relay terminals prioritize this segment to minimize vessel turnaround delays.
- Storage:Yard stacking and dwell-time management services. Paranaguá's cold chain facilities extract premium fees from meat export seasonal peaks.
Loading dominates installed base. Unloading is where expansion concentrates.
Terminal Type:
Cost tier stratification separates premium deep water fees from inland terminal economies, with transshipment nodes capturing relay arbitrage between vessel size classes.
- Deep Water:Facilities accommodating ultra-large container vessels with draft exceeding 15 meters. Santos anchors this tier with dedicated berth infrastructure commanding premium throughput fees from Asia-Pacific trade lanes.
- Transshipment:Relay nodes transferring containers between mainline and feeder vessels. Panama's Pacific terminals capture growing volumes displaced from saturated Caribbean routes under Canal expansion protocols.
- Regional:Mid-size ports serving single-country hinterlands. Colombia's Buenaventura expansion targets this tier for Pacific corridor development.
- Inland:Riverine and dry port extensions extending terminal reach. Brazil's Paraguay-Paraná waterway terminals feed into Santos export corridors.
Deep Water commands margin premiums. Transshipment is climbing the fastest.
Technology:
Implementation cycles and ROI clarity determine which automation layers deploy first, with RFID outpacing sensor networks due to faster payback periods.
- Automation:Automated stacking cranes and terminal operating systems achieving 30+ moves per crane hour. Santos greenfield developments deploy these systems to satisfy ANTAQ concession bid thresholds.
- RFID:Radio-frequency identification for container and equipment tracking. Callao terminals leverage this for yard management with clearer ROI benchmarks than alternative sensor networks.
- IoT:Sensor networks monitoring crane performance and environmental conditions. Deployment lags RFID due to extended integration timelines with legacy gantry fleets.
- Cloud Computing:Centralized data platforms for vessel stowage planning and gate automation. Brazilian operators front-load capex here to compress concession renewal windows.
RFID dominates installed base. Automation is gaining share fastest.
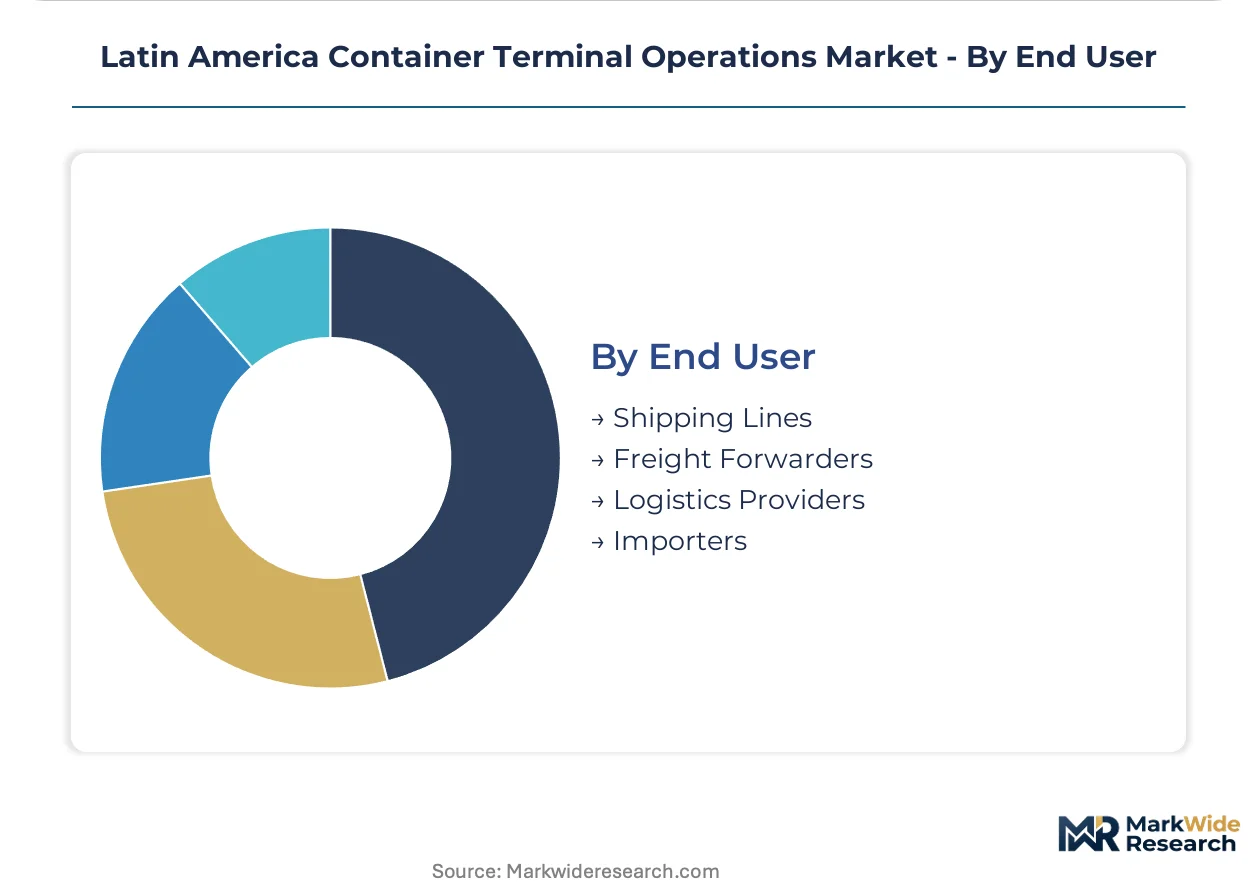
End User:
Customer type fragmentation reflects procurement consolidation trends, with integrated logistics platforms displacing fragmented trucking and rail negotiations.
- Shipping Lines:Ocean carriers contracting terminal capacity on long-term agreements. Maersk and MSC anchor demand at Santos through dedicated terminal partnerships.
- Freight Forwarders:Intermediaries bundling multimodal services. São Paulo soybean exporters increasingly shift from fragmented negotiations to bundled vessel-to-warehouse tenders.
- Logistics Providers:End-to-end supply chain operators. DP World's integrated platform spans regional hubs to sustain multi-country coordination.
- Importers:Direct cargo owners contracting terminal services. Rio de Janeiro manufacturing clusters drive this segment at Sepetiba Bay.
Shipping Lines dominate installed base. Logistics Providers is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANTAQ's PLI-equivalent port concession framework is compressing investment timelines across Latin American container terminals, elevating automation thresholds as a bid qualification condition. Brazil anchors regional throughput volumes while Peru, Panama, Colombia, and Mexico capture transshipment arbitrage from Canal expansion protocols.
Brazil
Soybean and meat export mandates are expanding refrigerated container volumes through Santos and Paranaguá terminals. ANTAQ enforces minimum cargo handling efficiency benchmarks that accelerate berth infrastructure upgrades. São Paulo state's Southeast corridor concentrates deep water facilities commanding premium throughput fees from Asia-Pacific trade lanes.
Peru
Specialized cold chain handling capabilities at Callao terminals capture Pacific corridor agribusiness flows from the Andean highlands. OSINERGMIN governs tariff structures and service level agreements for port operators. Lima's manufacturing hinterland drives import container volumes through Sepetiba Bay-equivalent facilities on the central coast.
Panama
Canal expansion protocols are displacing relay volumes from saturated Caribbean routes into Pacific terminal nodes. The national maritime authority aligns concession timelines with international shipping lane optimization. Panama City anchors transshipment operations transferring containers between mainline and feeder vessel classes.
Colombia
Buenaventura port expansion targets underpenetrated Pacific corridor capacity for transshipment relay volumes. The Superintendencia de Puertos maintains frameworks governing environmental mitigation protocols and coastal protection standards. Valle del Cauca's agricultural export clusters feed container demand through the city's deepening draft facilities.
Mexico
Lázaro Cárdenas and Manzanillo terminals capture Asia-Pacific trade diversion from US West Coast congestion. The Secretariat of Communications and Transportation coordinates port modernization mandates with nearshoring manufacturing relocation. Guadalajara's industrial corridor extends container demand inland through multimodal rail connections.
Latin America Container Terminal Operations Market Competitive Landscape
Player mix skews toward integrated global terminal operators with multi-country coordination platforms. Market structure concentrates around three to five dominant concessionaires controlling premium deep water berths at Santos, Callao, and Cartagena. Strategic archetypes include global logistics integrators deploying end-to-end supply chain platforms, national champions anchoring single-country throughput dominance, and regional specialists capturing transshipment relay arbitrage. Competitive moves center on concession renewal pre-positioning through automation capex front-loading and integrated logistics procurement model consolidation.
Among global integrated operators, DP World and APM Terminals exemplify the multi-hub coordination archetype spanning regional port networks. Brasil Terminal Portuário S.A. and Santos Brasil Participacoes occupy positions within Brazil's national champion tier, anchoring Southeast corridor throughput concentration. Hutchinson Ports PPC represents the transshipment specialist model capturing Canal relay volume displacement.
| Leading Market Players |
|---|
| The Port of Cartagena Organization |
| DP World |
| Brasil Terminal Portuário S.A. |
| San Lorenzo Port Authority |
| Hutchinson Ports PPC |
| Santos Brasil Participacoes S/A |
| Maranhense Port Administration Company (EMAP) |
| Kingston Wharves Limited |
| APM Terminals Callao |
| Others |
Supply & Pricing Matrix
ISO 28000 supply chain security certification gates both operator qualification and price differentiation across Latin American container terminals, filtering concession access while stratifying service premiums between certified and non-certified facilities.
Pricing Analysis
Certification level creates the primary spread between premium and standard throughput tiers. Three-tier pricing structure across ISO 28000-certified premium, ANTAQ-compliant standard, and legacy economy levels dominates contract structures. Price differentiation stems from automation investment thresholds and cold chain handling capabilities. Cost compression in economy tiers intensifies because legacy gantry fleets cannot accommodate ultra-large container vessels. Freight forwarders bundling multimodal services exhibit highest price sensitivity; shipping lines with dedicated terminal partnerships show lowest.
Supply Chain Analysis
Strategic stockpiling of crane components and terminal operating system licenses prevails over just-in-time procurement given concession renewal deadlines. Equipment manufacturing concentrates in China, South Korea, and Germany. Automation hardware draws from Chinese steel fabrication, German control systems, and South Korean sensor networks. Single-source vulnerability runs through specialized crane automation software providers. Distribution runs through OEM-direct contracts with terminal operators, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America container terminal operations are entering a cyclical upswing driven by Brazilian agribusiness export volume expansion through Santos and Paranaguá corridors.
For Market Incumbents: Consolidate berth infrastructure control through ANTAQ concession renewal pre-positioning. Defend against emerging automation-focused bidders by front-loading capex into RFID-tracked yard management and automated gate systems. Secure vertical integration into hinterland rail contracts to lock in São Paulo soybean corridor volumes.
For New Entrants and Emerging Players: Mid-tier operator ISO 28000 certification gaps open white-space access for qualified bidders. Target Colombia's Pacific corridor at Buenaventura where transshipment relay capacity remains underpenetrated. Enter through integrated logistics procurement models bundling vessel-to-warehouse services rather than competing on standalone terminal handling.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automation-mandated greenfield developments. Five-to-ten year viability favors concessionaires with multi-country coordination platforms and existing ANTAQ relationships. Watch for Panama Canal volume displacement patterns as inflection signal for Pacific terminal asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Concession Renewal Pre-Positioning | ANTAQ compliance thresholds disqualify undercapitalized bidders from Brazil's Southeast corridor. |
| Automated Stacking Crane Deployment | Optical character recognition systems at Santos achieve 30+ moves per crane hour. |
| Integrated Logistics Platform Expansion | DP World's multi-hub coordination captures bundled vessel-to-warehouse tender growth. |
| Cold Chain Infrastructure Investment | Paranaguá refrigerated berths extract premium fees from meat export seasonal peaks. |
| ISO 28000 Certification Acceleration | Supply chain security credentials filter competitive access across mid-tier operators. |
Research Methodology
The analysis maps deep water terminal operations, transshipment relay nodes, and inland port extensions, each validated through terminal operations directors, ANTAQ regulatory affairs specialists, shipping line procurement managers, and agribusiness logistics coordinators. Primary fieldwork combined with secondary validation from customs trade databases, ANTAQ concession filings, SEC 10-K terminal operator disclosures, and Panama Canal Authority transit statistics. Bottom-up volume modeling triangulated against top-down regional trade flow projections.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include service type, terminal depth tier, technology maturity level, and end-user procurement consolidation pattern. CAGRs were derived from historical throughput trajectories and concession investment cycle timing. Forecast inputs incorporated Brazilian soybean export mandate volumes and Panama Canal expansion protocol relay displacement assumptions.
Underlying assumptions cover ANTAQ concession renewal timelines and automation capex deployment rates, with deviation risk concentrated in regulatory approval delays and automation technician availability. Revision becomes warranted when Brazilian agribusiness export volume growth or Panama Canal transit fee structures cross material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Vietnam Express Delivery Services Market
Logistics and Shipping
Peru Logistics Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
North America Last Mile Delivery Market