
 Respiratory Pathogen Testing Kits Market | 2026-2036
Respiratory Pathogen Testing Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Pathogen Testing Kits Market Analysis
Hospital procurement is tilting toward integrated supply contracts that bundle respiratory panels with service agreements. Thermo Fisher Scientific leverages its diagnostics platform breadth to anchor long-term contracts with large health systems. Abbott Laboratories competes through point-of-care specialization that reduces laboratory turnaround bottlenecks. Roche Diagnostics sustains premium positioning in molecular testing through automated workflow integration.
Respiratory pathogen testing kits are in vitro diagnostic devices designed to detect viral and bacterial agents causing acute respiratory infections, typically employing nucleic acid amplification or immunoassay chemistries with sensitivity thresholds ranging from 10² to 10⁴ copies per milliliter. Their primary commercial purpose is enabling clinicians to differentiate infectious etiologies and guide antimicrobial stewardship decisions within clinically relevant timeframes. PCR tests occupy the highest-margin tier of the product type landscape due to their diagnostic accuracy in hospital settings, while rapid tests extend market reach into pharmacies and urgent care clinics where speed outweighs laboratory confirmation. Point-of-care testing represents the fastest-growing application segment as decentralized health delivery models expand diagnostic access beyond traditional laboratory infrastructure.
The FDA's emergency use authorization pathway and Clinical Laboratory Improvement Amendments proficiency standards shape product development timelines and commercial launch strategies for kit manufacturers seeking US market access. The European Union's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements that extend certification cycles and elevate compliance costs for multinational suppliers. ISO 13485 quality management certification serves as a baseline market access credential across major jurisdictions. Stakeholders must monitor evolving payer coverage determinations for multiplex respiratory panels as reimbursement policy increasingly dictates adoption velocity in ambulatory settings.
Market Dynamics
Hospital consolidation into mega-systems is compressing procurement cycles and forcing kit manufacturers to restructure pricing around multi-year enterprise contracts rather than transactional sales.
Growth Catalysts
- Antimicrobial stewardship mandates:CMS reimbursement penalties for hospital-acquired infections drive demand for rapid pathogen identification. Clinical microbiology departments expand testing menus to avoid bundled payment penalties.
- Point-of-care decentralization:Urgent care chains and retail health clinics adopt cartridge-based molecular platforms. This bypasses centralized laboratory bottlenecks during respiratory virus season surges.
- FDA emergency use authorization pathway:Accelerated review timelines for novel respiratory targets compress product development cycles. Manufacturers leverage EUA precedents for seasonal variant updates.
Market Restraints
- Reagent supply concentration:Taq polymerase and modified nucleotide production concentrates among three specialty chemical suppliers. Any disruption propagates through PCR kit manufacturing within weeks.
- IVDR clinical evidence requirements:European Union In Vitro Diagnostic Regulation demands prospective validation studies for Class C devices. Certification cycles extend 18-24 months beyond previous CE-mark timelines.
- Antigen test substitution:Low-cost lateral flow devices capture symptomatic patient volume in pharmacy settings. Molecular kit manufacturers cede price-sensitive segments to immunoassay alternatives.
Strategic Opportunities
- Home-based respiratory surveillance:Telehealth platforms integrate self-collected nasal swab workflows with remote result interpretation. This opens ambulatory channels outside traditional laboratory networks.
- Multiplex panel expansion:Convergence of PCR and next-generation sequencing chemistries enables 20+ pathogen detection from single specimens. Reference laboratories differentiate through comprehensive respiratory plus sexually transmitted infection combinations.
- Indian diagnostic infrastructure buildout:The country's PLI scheme for medical devices attracts contract manufacturing investment. Domestic production capacity addresses import dependency for seasonal surge response.
Industry Challenges
- Bioinformatics pipeline integration:Next-generation sequencing-based kits require laboratory information system upgrades. Many hospital IT departments lack specialized personnel for variant calling algorithm validation.
- Proficiency testing logistics:CLIA regulations mandate external quality assessment for molecular testing. Smaller reference laboratories struggle with shipping temperature requirements for frozen proficiency specimens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Pathogen Testing Kits Market |
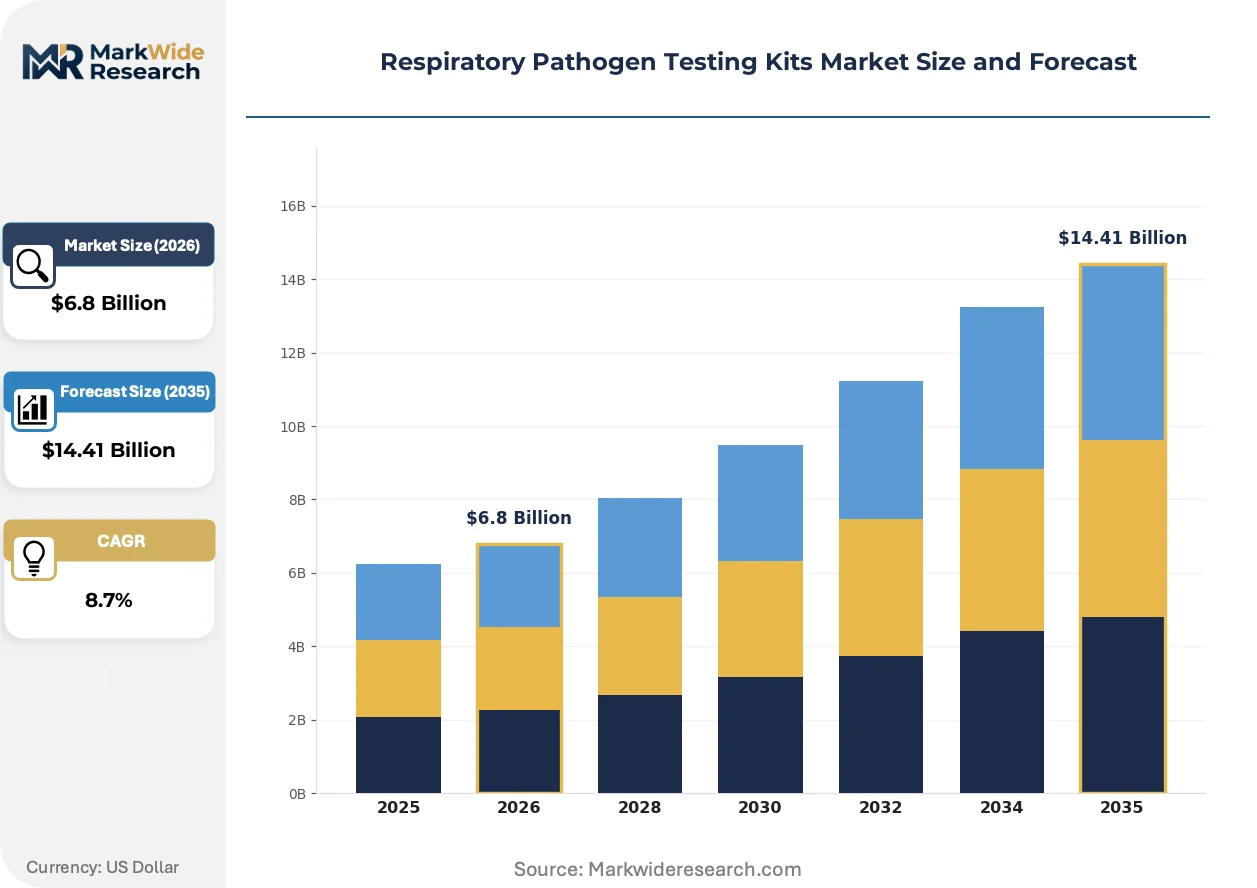
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antigen Tests, PCR Tests, Molecular Tests, Rapid Tests Application: Laboratory Testing, Point-of-Care Testing, Home Testing, Field Testing End User: Hospitals, Diagnostic Laboratories, Clinics, Emergency Services Technology: Isothermal Nucleic Acid Amplification, Enzyme Immunoassays, Next-Generation Sequencing, Microarray Technology |
| Companies Covered | Thermo Fisher Scientific, Abbott Laboratories, Roche Diagnostics, bioMérieux, Danaher Corporation, Becton Dickinson and Company, Qiagen, Altona Diagnostics, Cepheid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Pathogen Testing Kits Market Emerging Trajectories
Respiratory diagnostics is fragmenting into distinct performance tiers as speed, accuracy, and cost trade-offs reshape where testing occurs across the care continuum.
CRISPR-based detection chemistry is hybridizing with traditional PCR workflows. Reference laboratories in academic medical centers pilot this combination for point-mutation identification in influenza antiviral resistance screening. The technology is compressing turnaround times for targeted sequencing applications previously requiring separate platforms.
Europe's In Vitro Diagnostic Regulation recalibrated evidence standards for companion diagnostic claims. Manufacturers now conduct prospective clinical studies linking pathogen detection to therapeutic decision outcomes. High-complexity molecular laboratories absorb compliance costs through extended service contracts with health systems.
Integrated delivery networks now unbundle respiratory panel pricing from capital equipment leases. Hospital supply chain executives negotiate reagent rental agreements that shift instrument ownership to manufacturers. This procurement restructuring is most visible among nonprofit health systems in the Upper Midwest seeking balance sheet relief.
Respiratory Pathogen Testing Kits Market Segmentation
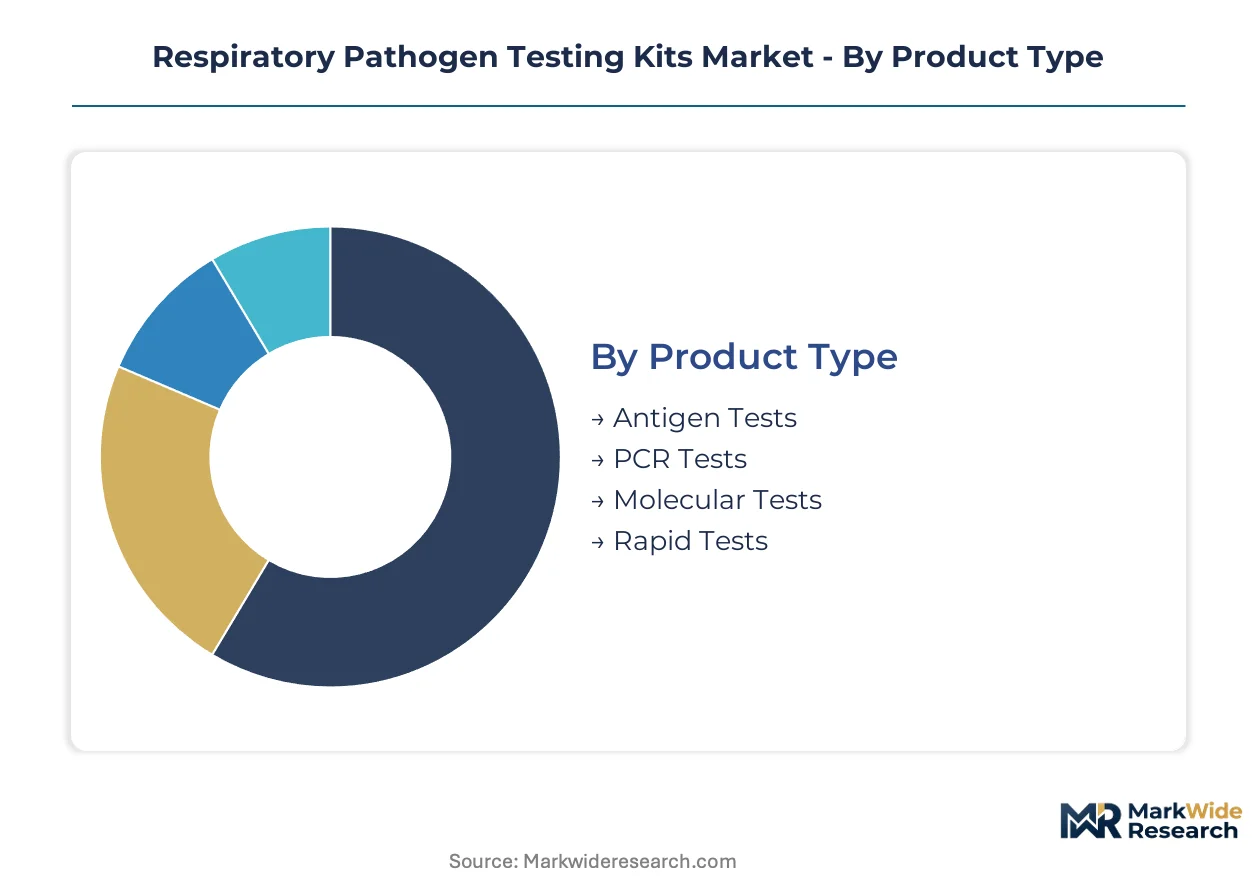
Respiratory pathogen testing kits fragment across performance tiers that trade speed against sensitivity, determining where each format deploys across the care continuum. Procurement patterns diverge sharply between centralized laboratory networks seeking comprehensive panels and decentralized sites prioritizing turnaround velocity.
Product Type:
Clinical workflows span a use-case spectrum from high-complexity molecular confirmation to rapid triage screening.
- PCR Tests:Nucleic acid amplification chemistry delivers sensitivity thresholds of 10² to 10³ copies per milliliter, making these the reference standard for hospital microbiology departments. Demand concentrates in academic medical centers where antimicrobial stewardship committees mandate definitive pathogen identification before narrowing empiric therapy.
- Rapid Tests:Lateral flow immunoassays generate results in under 30 minutes without laboratory infrastructure, extending diagnostic access into urgent care chains and retail pharmacy clinics. Volume concentrates in symptomatic screening during respiratory virus season surges where speed outweighs analytical sensitivity.
- Antigen Tests:Direct viral protein detection offers lowest-cost screening for high-prevalence settings.
- Molecular Tests:Cartridge-based platforms hybridize PCR sensitivity with simplified workflow for near-patient deployment.
Established volume favors PCR Tests; emerging adoption favors Rapid Tests.
Application:
Site-of-care economics reshape which formats gain procurement priority as health systems unbundle testing from central laboratory monopoly.
- Point-of-Care Testing:CLIA-waived molecular platforms and antigen devices enable diagnostic decision-making during the clinical encounter, bypassing send-out delays. Deployment concentrates in emergency departments and urgent care networks where throughput pressure peaks during winter respiratory surges.
- Laboratory Testing:High-complexity molecular laboratories run multiplex respiratory panels with 15+ pathogen targets, supporting epidemiological surveillance and resistance monitoring. Reference laboratories in integrated delivery networks anchor enterprise contracts through comprehensive menu breadth.
- Home Testing:Self-collected nasal swab workflows paired with telehealth interpretation open ambulatory channels outside traditional laboratory networks.
- Field Testing:Portable thermal cycler units support outbreak response in remote or resource-limited settings.
Laboratory Testing captures the revenue concentration; Point-of-Care Testing climbs the fastest.
End User:
Purchasing authority consolidation into mega-systems compresses vendor selection around multi-year enterprise agreements.
- Diagnostic Laboratories:Commercial reference laboratories and hospital-affiliated microbiology departments drive volume through high-throughput automated platforms. Large national chains negotiate preferred vendor status through exclusive reagent rental contracts that shift capital equipment ownership to manufacturers.
- Hospitals:Inpatient units and emergency departments demand rapid turnaround for infection control and isolation decisions. CMS reimbursement penalties for hospital-acquired infections intensify procurement focus on same-day pathogen identification.
- Clinics:Federally qualified health centers and specialty respiratory practices seek CLIA-waived options.
- Emergency Services:Prehospital screening programs pilot rapid antigen deployment for ambulance diversion decisions.
Diagnostic Laboratories anchor procurement volume; Hospitals drive fastest format migration toward point-of-care.
Technology:
Chemistry platforms differentiate on workflow integration, bioinformatics burden, and regulatory pathway complexity.
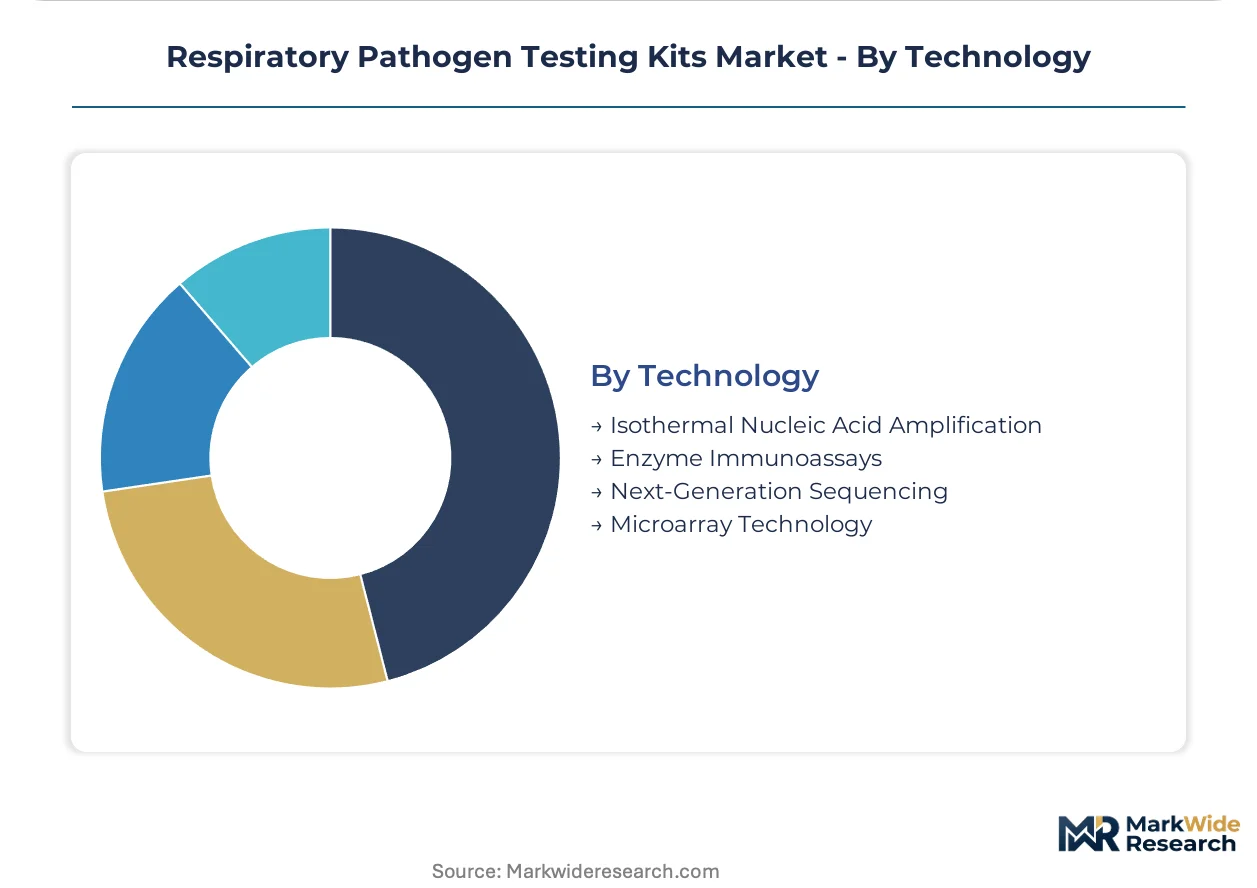
- Isothermal Nucleic Acid Amplification:Loop-mediated amplification and recombinase polymerase amplification operate without thermal cycling infrastructure, enabling cartridge-based near-patient deployment. Simplified instrumentation reduces capital barriers for smaller clinics entering molecular testing.
- Next-Generation Sequencing:Metagenomic detection identifies novel or variant pathogens without target-specific primer design, supporting reference laboratory differentiation through comprehensive respiratory plus sexually transmitted infection panels. Academic medical centers absorb bioinformatics infrastructure costs for antiviral resistance surveillance.
- Enzyme Immunoassays:Established lateral flow and ELISA formats dominate lowest-cost screening tiers.
- Microarray Technology:Solid-phase hybridization enables medium-plex detection with simplified workflow.
Isothermal Nucleic Acid Amplification commands expanding installed base; Next-Generation Sequencing gains share fastest in reference settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA emergency use authorization frameworks and CMS antimicrobial stewardship mandates are concentrating procurement authority within integrated US health systems, while the European Union's In Vitro Diagnostic Regulation extends certification timelines for multinational suppliers seeking CE-mark access.
United States
Hospital consolidation into mega-systems drives centralized purchasing of multiplex respiratory panels through multi-year enterprise contracts. The FDA's EUA pathway accelerates seasonal variant updates for kit manufacturers. The Boston-Cambridge corridor anchors molecular diagnostics R&D concentration with academic medical center pilot programs.
Germany
Reference laboratories in Baden-Württemberg and Bavaria absorb IVDR compliance costs through extended service contracts with statutory health insurers. The country's national pharmaceutical regulator enforces stricter clinical evidence standards for Class C devices. The Rhine-Main cluster around Frankfurt hosts proficiency testing logistics providers serving smaller hospital laboratories.
China
Domestic production capacity expansion under the country's medical device PLI scheme addresses import dependency for seasonal surge response. NMPA streamlined review pathways compress registration timelines for isothermal amplification platforms. The Yangtze River Delta manufacturing belt concentrates cartridge-based platform assembly for near-patient deployment.
India
The PLI scheme for medical devices attracts contract manufacturing investment from multinational kit suppliers seeking cost-competitive production bases. CDSCO harmonization with ISO 13485 standards accelerates import substitution for PCR reagents. The Mumbai-Pune corridor anchors diagnostic infrastructure buildout with reference laboratory network expansion.
Japan
PMDA quality management requirements sustain premium positioning for automated workflow integration in hospital microbiology departments. METI funding for infectious disease preparedness drives point-of-care platform adoption in regional medical centers. The Kansai region around Osaka concentrates specialized chemical suppliers for modified nucleotide production.
Respiratory Pathogen Testing Kits Market Vendor Landscape
On the supply side, the industry is consolidating around integrated diagnostics platforms that bundle respiratory panels with multi-year service agreements. Thermo Fisher Scientific leverages breadth across analytical instruments and consumables to anchor enterprise contracts. Abbott Laboratories competes through point-of-care specialization that reduces laboratory turnaround bottlenecks. Roche Diagnostics sustains premium positioning in molecular testing through automated workflow integration. Dominant competitive moves include strategic partnerships for bioinformatics pipeline development and geographic expansion through contract manufacturing in cost-competitive jurisdictions.
Among the named players in this market, Thermo Fisher Scientific and Abbott Laboratories exemplify contrasting strategic archetypes. Thermo Fisher Scientific occupies a position representing integrated platform breadth, while Abbott Laboratories exemplifies point-of-care velocity specialization. Roche Diagnostics anchors the premium-tier molecular testing segment. These three companies collectively represent the competitive tension between centralized laboratory consolidation and decentralized diagnostic access that is reshaping procurement patterns across health systems.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Roche Diagnostics |
| bioMérieux |
| Danaher Corporation |
| Becton Dickinson and Company |
| Qiagen |
| Altona Diagnostics |
| Cepheid |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing belt anchors cartridge-based platform assembly for near-patient deployment, with capacity utilization rates directly transmitting into OEM pricing leverage during seasonal respiratory surges. Taq polymerase and modified nucleotide supply concentration among three specialty chemical suppliers creates asymmetric bargaining power that propagates through PCR kit manufacturing within weeks.
Pricing Analysis
Certification level creates the primary spread between premium molecular platforms and economy antigen tiers, with FDA emergency use authorization and IVDR CE-marking cycles adding compliance cost premiums. Three-tier pricing structure across premium, standard, and economy levels reflects automation depth and pathogen target breadth, with diagnostic laboratories negotiating reagent rental agreements that shift instrument ownership to manufacturers. Cost compression in the rapid test tier is intensifying because antigen test substitution captures symptomatic pharmacy volume. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers absorb premium positioning for antimicrobial stewardship compliance.
Supply Chain Analysis
Contract manufacturing concentrates among domestic Chinese assemblers serving the NMPA streamlined review pathway and Indian PLI scheme beneficiaries near the Mumbai-Pune corridor. Raw material dependencies center on Taq polymerase from Japanese specialty chemical suppliers, modified nucleotides from Rhine-Main cluster producers, and nitrocellulose membrane for lateral flow devices. Single-source vulnerability in recombinant enzyme supply creates propagation risk for PCR kit production. Distribution runs through integrated delivery network procurement committees negotiating multi-year enterprise contracts with national reference laboratory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Respiratory pathogen testing kits sit in early-cycle expansion as point-of-care decentralization penetrates urgent care networks previously captive to centralized laboratory monopolies. Antimicrobial stewardship mandates and telehealth platform integration create durable adoption tailwinds beyond pandemic-era demand spikes.
For Market Incumbents: Build switching-cost moats through bioinformatics pipeline integration that locks hospital IT departments into proprietary variant calling workflows. Anchor enterprise contracts with integrated delivery networks by bundling respiratory panels with extended service agreements covering CLIA proficiency testing logistics. Defend against antigen test substitution by accelerating cartridge-based molecular platform deployment into retail health clinics.
For New Entrants and Emerging Players: Establish a beachhead in home-based respiratory surveillance by partnering with telehealth platforms for self-collected nasal swab result interpretation. Target the Indian diagnostic infrastructure buildout under the PLI scheme for medical devices, where contract manufacturing investment addresses import dependency. Pursue isothermal nucleic acid amplification chemistry to bypass thermal cycling infrastructure barriers for smaller clinic entry.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because hospital procurement centralization into mega-systems compresses vendor selection around multi-year enterprise agreements. Acquisition target archetype: mid-cap specialists with CLIA-waived molecular platforms and established urgent care channel relationships. Watch FDA EUA pathway velocity for seasonal variant updates as inflection indicator for manufacturer R&D productivity.
| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Panel Expansion | Convergence of PCR and next-generation sequencing chemistries enables 20+ pathogen detection from single specimens in reference laboratories. |
| CE Marking Pathway | IVDR clinical evidence requirements for Class C devices extend certification cycles and elevate compliance costs for multinational suppliers. |
| Hospital System Partnership | Integrated delivery networks unbundle respiratory panel pricing from capital equipment leases through reagent rental agreements. |
| Software Companion Development | Bioinformatics pipeline integration requires laboratory information system upgrades for variant calling algorithm validation. |
| Reimbursement Strategy | Payer coverage determinations for multiplex respiratory panels dictate adoption velocity in ambulatory settings. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA EUA submissions, CMS reimbursement databases, and GPO contract filings. Primary interviews engaged hospital procurement managers, clinical microbiology directors, diagnostic laboratory executives, and biomedical engineers at integrated delivery networks. Secondary validation drew from hospital procurement databases, CLIA proficiency testing records, and regulatory filing repositories. Bottom-up demand modeling triangulates against top-down market sizing across product type, application, and technology dimensions.
Forecast inputs incorporate antimicrobial stewardship mandate penetration rates, point-of-care platform adoption curves, and seasonal respiratory surge frequency. Segmentation dimensions span product type chemistry tiers, site-of-care deployment models, end-user purchasing authority structures, and regional regulatory framework clusters. CAGRs derive from installed base growth trajectories and average revenue per test trends across the projection horizon. Industry-specific inputs include FDA EUA pathway velocity and IVDR certification cycle timelines.
Sensitivities concentrate around reagent supply disruptions, antigen test substitution acceleration, and reimbursement policy shifts for multiplex panels. Forecasts embed assumptions regarding hospital consolidation trajectories and telehealth platform integration velocity. Quarterly review of FDA EUA submission volumes and GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Epilepsy Diagnosis and Treatment Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Middle East and Africa Liver Cancer Diagnostics Market
Diagnostics
Swine Disease Diagnostic Kit Market
Diagnostics
Sperm Density Testing Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Creatinine Test Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Shrimps Disease Diagnostics Market
Diagnostics
Immunodiagnostics Market