

Luer Lock Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Luer Lock Connector Market Insights
Dialysis clinics are repositioning toward higher-grade safety connectors as patient volumes expand and infection protocols tighten. Becton, Dickinson and Company leverages its vertical integration in polymer molding to dominate hospital-system contracts. B. Braun Melsungen AG anchors European supply through specialized cleanroom manufacturing in Germany. Terumo Corporation competes across Asia-Pacific with differentiated regional product portfolios.
A luer lock connector is a standardized tapered fitting with helical threads that creates a secure, leak-resistant seal between medical devices, typically manufactured through precision injection molding of medical-grade polymers with tolerances measured in hundredths of a millimeter. Its primary purpose is to prevent accidental disconnection during fluid transfer in high-pressure clinical environments. Safety luer lock variants command premium positioning as healthcare systems mandate needlestick prevention, while polypropylene dominates material selection for its chemical resistance and gamma sterilization compatibility. Intravenous therapy remains the largest application segment, though dialysis represents the fastest-growing margin pool as chronic kidney disease prevalence rises.
FDA enforcement of ISO 80369-7 small-bore connector standards is eliminating non-interoperable legacy designs from US distribution channels. The EU Medical Device Regulation (MDR) and CE marking requirements are extending compliance burdens for exporters seeking European market access. Stakeholders must monitor evolving material biocompatibility testing protocols and decide whether to absorb certification costs or cede regulated segments to incumbent specialists.
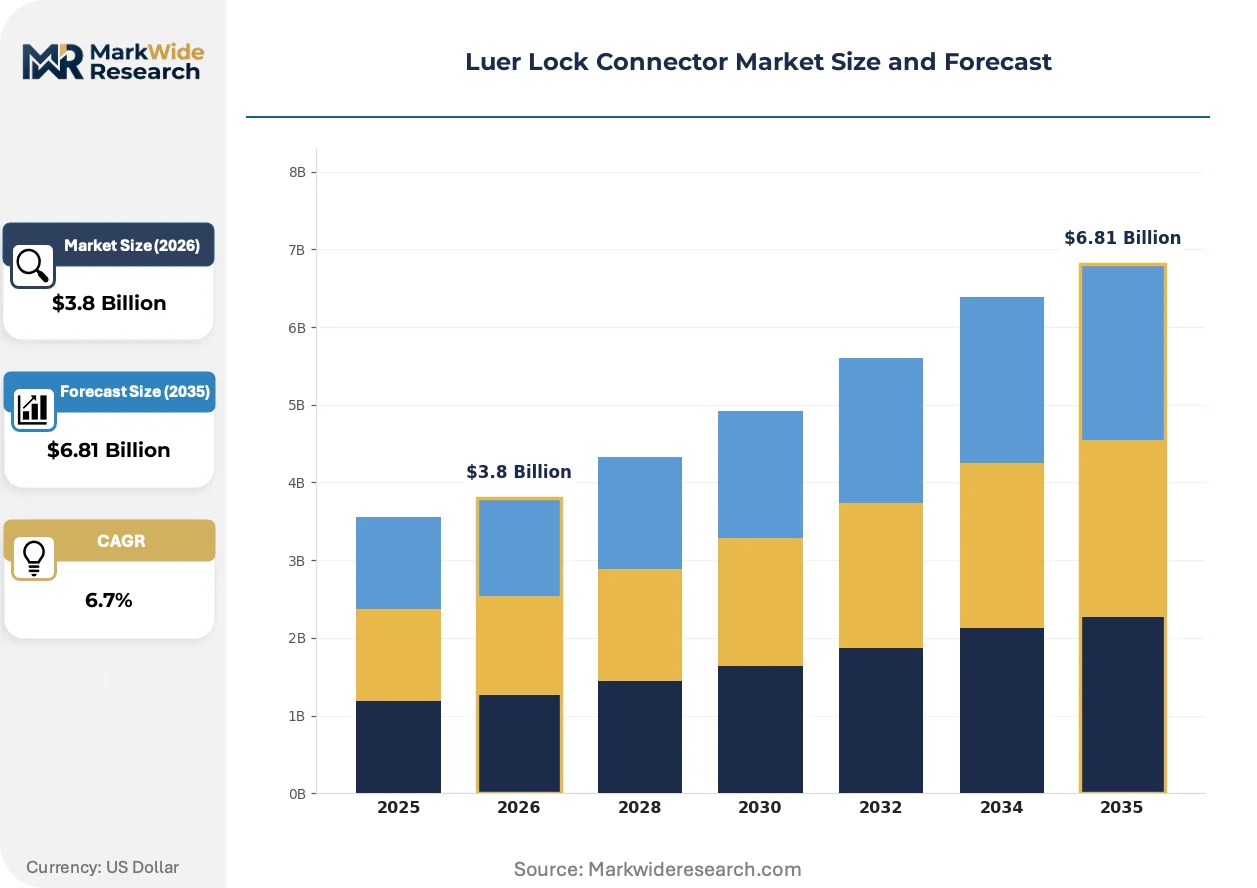
Market Dynamics
FDA enforcement of ISO 80369-7 small-bore connector standards is eliminating non-interoperable legacy designs from US distribution channels, forcing manufacturers to retool precision molding lines and recertify product portfolios.
Growth Catalysts
- ISO 80369-7 Mandates:FDA compliance deadlines are accelerating hospital system replacement cycles for legacy luer connectors, creating immediate demand for safety-engineered variants with needlestick prevention features.
- Dialysis Clinic Expansion:Chronic kidney disease prevalence is driving procurement of specialized connectors that withstand repeated high-pressure fluid exchanges in hemodialysis settings.
- Polymer Molding Advances:Medical-grade polypropylene with enhanced gamma sterilization compatibility is enabling thinner-walled connector designs without sacrificing burst pressure ratings.
Market Restraints
- Specialized Polymer Supply Concentration:Medical-grade polypropylene resin production concentrates among three European petrochemical suppliers, exposing molders to feedstock allocation volatility.
- Cleanroom Certification Barriers:ISO Class 7 cleanroom requirements for connector assembly create capital intensity thresholds that exclude mid-scale entrants from hospital contract bidding.
- Legacy Inventory Stranding:Non-compliant connector stockpiles accumulated pre-ISO 80369-7 enforcement are forcing distributors to absorb write-downs or redirect volumes to unregulated secondary markets.
Strategic Opportunities
- Home Infusion Therapy:Untapped patient-managed care segments in Germany and Japan present demand for simplified, color-coded connector systems with intuitive twist-lock mechanisms.
- Closed-System Transfer Device Convergence:Integration of luer lock interfaces with hazardous drug containment technologies is opening oncology pharmacy applications with premium pricing potential.
- EU MDR Accelerated Pathways:CE marking equivalence agreements for ISO 80369-7 certified products are compressing European market entry timelines for compliant manufacturers.
Industry Challenges
- Precision Tolerance Workforce Scarcity:Injection mold technicians capable of maintaining hundredth-millimeter tolerances in medical polymer processing remain concentrated in Germany and Switzerland, constraining capacity expansion.
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity and sensitization study queues at accredited laboratories are extending product launch timelines by eight to fourteen months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luer Lock Connector Market Trends and Innovations
Active polymer formulation advances and regulatory harmonization efforts are compressing product development cycles while expanding the addressable application set beyond traditional infusion therapy.
Polycarbonate-overmolded luer connectors with integrated RFID traceability chips are overtaking conventional unmarked variants in tertiary hospital systems. Supply chain managers at integrated delivery networks in the United States are mandating lot-level digital tracking to support recall automation. This technology is overtaking basic polypropylene connectors in procurement specifications for high-risk medication lines.
EU Medical Device Regulation (MDR) Article 10 technical documentation requirements are extending conformity assessment timelines for non-European manufacturers seeking CE marking. Notified body capacity constraints in Germany and the Netherlands are creating twelve-to-eighteen-month certification queues. Asian exporters with MDR-authorized representatives in Ireland are securing faster market access than competitors routing through Eastern European notified bodies.
Consolidated procurement through group purchasing organizations is displacing distributor-mediated purchasing for safety-engineered connectors. Hospital systems in China are centralizing luer lock specifications to single-source contracts with molders offering direct technical support. This concentration is most visible in Shanghai and Beijing, where municipal health bureaus have standardized connector color-coding protocols across public hospital networks.
Luer Lock Connector Market Segmentation
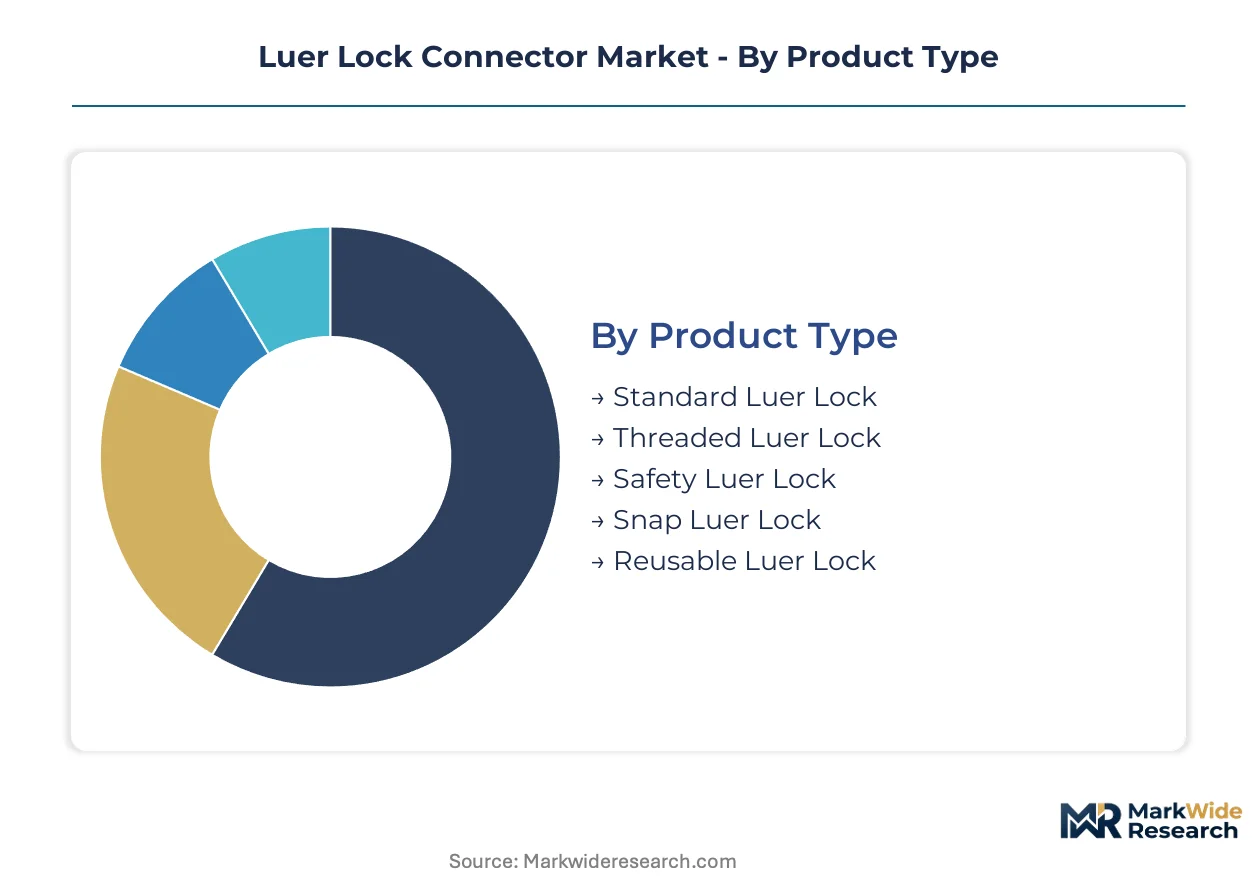
Luer lock connector procurement patterns diverge sharply across clinical settings, with regulatory mandates and infection control protocols reshaping category priorities. Hospital systems now segment purchases by risk tier rather than unit cost, elevating safety-engineered variants while relegating legacy designs to secondary markets.
Product Type:
Replacement cycles for legacy connectors are accelerating as FDA ISO 80369-7 enforcement deadlines eliminate non-compliant inventory from US distribution channels.
- Safety Luer Lock:Integrated needlestick prevention mechanisms with retractable or shielded designs meet OSHA bloodborne pathogen standards. Dialysis clinics in Germany and the United States are mandating these variants for high-frequency fluid exchange procedures to reduce occupational injury liability.
- Standard Luer Lock:The conventional helical-thread tapered fitting remains specified for low-risk gravity-fed infusions where cost sensitivity dominates procurement. Volume placements concentrate in China's county-level hospitals upgrading basic infusion infrastructure under national health system consolidation programs.
- Threaded Luer Lock:Enhanced torque resistance suits high-pressure applications in anesthesia delivery systems.
- Snap Luer Lock:Audible-click confirmation mechanisms serve emergency medicine settings requiring rapid securement.
- Reusable Luer Lock:Stainless-steel variants withstand autoclave sterilization cycles for surgical instrument sets in Japan's university hospitals.
Volume placements concentrate in Standard Luer Lock; the faster expansion belongs to Safety Luer Lock.
Material:
Polymer selection now hinges on sterilization modality compatibility and thin-wall molding feasibility rather than raw material cost alone.
- Polypropylene:Gamma sterilization-stable with excellent chemical resistance to lipids and alcohols, this polymer dominates high-volume disposable production. Medical-grade resin supply concentrates among European petrochemical suppliers, exposing molders to allocation volatility during feedstock disruptions.
- Polycarbonate:Optical clarity and dimensional stability enable overmolding with RFID traceability chips for lot-level digital tracking. Tertiary hospital systems in the United States are specifying polycarbonate-overmolded variants for high-risk medication lines to support automated recall management.
- Stainless Steel:Autoclavable durability suits reusable surgical instrument connectors in German and Swiss operating theaters.
- Nylon:Abrasion resistance benefits mobile infusion pump connectors subject to mechanical wear.
- Polyethylene:Low-cost flexibility serves single-use diagnostic applications with minimal performance requirements.
Polypropylene captures the highest shipment volumes; polycarbonate climbs the fastest as digital traceability mandates spread.
Application:
Application-specific performance requirements are fragmenting procurement specifications, with pressure ratings and connection cycle durability becoming decisive selection criteria.
- Dialysis:Connectors must withstand repeated high-pressure fluid exchanges exceeding 300mmHg in hemodialysis circuits. Chronic kidney disease prevalence is expanding clinic networks in China and India, creating concentrated demand for burst-pressure-rated variants with enhanced thread engagement.
- Intravenous Therapy:The largest installed base of gravity and pump-administered infusions drives standard connector specifications. Hospital systems in the United States are consolidating procurement through group purchasing organizations, displacing distributor-mediated purchasing for basic IV sets.
- Drug Delivery:Closed-system transfer device integration is opening oncology pharmacy applications with premium pricing potential.
- Blood Sampling:Vacuum tube compatibility requires precise luer taper tolerances for reliable seal formation.
- Anesthesia:High-pressure gas delivery demands metal-reinforced connector bodies for safety-critical airway management.
Intravenous Therapy maintains the broadest installed base; dialysis gains share fastest as renal replacement therapy access expands.
End User:
End-user sophistication levels are stratifying the vendor base, with integrated delivery networks demanding direct technical support while independent clinics prioritize distributor availability.
- Dialysis Clinics:Freestanding renal care centers operate under stringent infection control protocols with high daily patient throughput. China's municipal health bureaus in Shanghai and Beijing have standardized connector color-coding protocols across public clinic networks, concentrating procurement with molders offering direct engineering support.
- Pharmaceutical Manufacturers:Aseptic filling operations require validated connector systems for drug containment and transfer. EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for component suppliers seeking CE marking for device-drug combination products.
- Diagnostic Laboratories:High-throughput analyzers demand disposable connectors with consistent lot-to-lot dimensional stability.
- Ambulatory Care Centers:Cost-conscious procurement favors simplified twist-lock designs with intuitive handling for rotating clinical staff.
- Specialty Clinics:Pain management and infusion centers specify premium safety variants for outpatient parenteral therapy.
Pharmaceutical Manufacturers generate the highest per-unit margins; dialysis clinics are expanding procurement most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Shanghai are concentrating medical device molding capacity for export markets. These zones offer VAT rebates and streamlined customs clearance that attract polymer compounders serving hospital supply chains. Manufacturers within these zones supply ISO 80369-7 certified connectors to dialysis clinic networks across three continents.
United States
FDA enforcement deadlines for ISO 80369-7 compliance are accelerating hospital system replacement cycles. Group purchasing organizations in the Midwest and Southeast are consolidating procurement specifications for safety-engineered connectors. The Research Triangle in North Carolina hosts specialized polymer testing laboratories supporting biocompatibility certification for domestic molders.
Germany
CE marking requirements under EU MDR Article 10 are extending conformity assessment timelines for connector manufacturers. Notified bodies in Berlin and Munich are processing twelve-to-eighteen-month certification queues for ISO 80369-7 validated products. Cleanroom manufacturing clusters in Baden-Württemberg supply precision-molded components to pharmaceutical filling operations across the continent.
China
Municipal health bureaus in Shanghai and Beijing have standardized connector color-coding protocols across public hospital networks. NMPA alignment with ISO 80369 standards is eliminating non-interoperable legacy designs from domestic distribution. The Yangtze River Delta hosts the highest concentration of gamma-sterilization-compatible polypropylene compounders serving Asia-Pacific dialysis clinic expansion.
Japan
PMDA quality management system inspections are tightening documentation requirements for reusable stainless-steel surgical connectors. University hospitals in Tokyo and Osaka are specifying autoclave-durable variants for instrument sets with high sterilization cycle demands. METI subsidies for domestic medical device production are supporting precision molding facility upgrades in the Chubu region.
Luer Lock Connector Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital-system contracts favoring vertically integrated molders while diagnostic applications tolerate distributor-mediated sourcing. The vendor base organizes into three tiers: multinational device conglomerates with captive polymer molding, regional specialists with cleanroom certification depth, and commodity molders serving unregulated secondary markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, as certification backlogs favor incumbents with established notified body relationships.
Among diversified medical technology conglomerates, Becton, Dickinson and Company, B. Braun Melsungen AG, and Terumo Corporation exemplify distinct geographic anchoring strategies. The New Jersey-based entity represents North American hospital-system contracting dominance through direct technical support capabilities. The German limited liability company occupies a position as the European supply anchor through specialized cleanroom manufacturing. The Japanese corporation sits within the Asia-Pacific regional specialist tier with differentiated product portfolios calibrated to local regulatory requirements.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| Baxter International |
| ICU Medical |
| Vygon |
| CODAN Companies |
| Terumo Corporation |
| Fresenius Kabi |
| Merit Medical Systems |
| Others |
Pricing and Supply Chain Analysis
Dialysis clinic procurement concentration in China's municipal health networks and US group purchasing organizations drives contract-based long-term offtake pricing with volume-scaled discounts. Safety-engineered variants with ISO 80369-7 certification command premium positioning over legacy designs facing regulatory obsolescence.
Pricing Analysis
Short lead-time premiums dominate pricing for safety luer lock connectors as ISO 10993 biocompatibility testing backlogs extend product launch timelines by eight to fourteen months. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated safety variants from basic polypropylene connectors and non-compliant legacy stock. Cost compression in standard connectors is intensifying because China's county-level hospitals prioritize unit economics over performance specifications. Dialysis clinics exhibit lowest price sensitivity due to liability exposure from needlestick injuries, while diagnostic laboratories remain most cost-conscious in high-throughput disposable procurement.
Supply Chain Analysis
Medical-grade polypropylene resin supply rests on European petrochemical producers in Germany, Belgium, and the Netherlands, exposing molders to feedstock allocation volatility during energy market disruptions. Gamma-sterilization-compatible compounding capacity concentrates in the Yangtze River Delta and Baden-Württemberg cleanroom clusters. Single-source vulnerability persists for ISO Class 7 cleanroom-certified assembly operations in Germany and Switzerland, where precision mold technicians capable of hundredth-millimeter tolerances remain scarce. Distribution runs through hospital group purchasing organizations in the United States and direct municipal contracts in China, displacing traditional distributor-mediated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom manufacturing capacity scarcity in precision polymer molding props pricing for certified connectors, creating durable margin pools for incumbents with established notified body relationships.
For Market Incumbents: Hedge against biocompatibility testing backlog risks by securing dedicated laboratory capacity at accredited ISO 10993 facilities in North Carolina's Research Triangle. Deepen backward integration into medical-grade polypropylene compounding to offset European feedstock concentration. Prioritize capacity addition in China's Yangtze River Delta free trade zones to capture VAT rebate advantages for Asia-Pacific dialysis clinic expansion. For New Entrants and Emerging Players: EU MDR Article 10 in Germany opens a window for specialized cleanroom operators with existing ISO 80369-7 validation to capture CE marking equivalence agreements. Target home infusion therapy segments in Japan and Germany with simplified color-coded connector systems requiring lower capital intensity than hospital-grade variants. Pursue direct technical support partnerships with China's municipal health bureaus in Shanghai and Beijing as the fastest path to volume placement. For Investors and Strategic Acquirers: The window for entry favors regional specialists with notified body relationships in Germany and the Netherlands. Acquire mid-scale molders possessing ISO Class 7 certification depth but lacking global distribution reach, as certification queues protect incumbent economics. Watch biocompatibility testing queue lengths at accredited laboratories as the inflection indicator for product launch velocity and working capital intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance compresses European market entry timelines for ISO 80369-7 validated manufacturers. |
| Hospital System Partnership | Direct technical support contracts with China's Shanghai and Beijing municipal health bureaus displace distributor channels. |
| Backward Integration | In-house medical-grade polypropylene compounding mitigates European petrochemical supplier concentration risk. |
| Capacity Expansion | Gamma-sterilization-compatible molding lines in Yangtze River Delta free trade zones capture Asia-Pacific dialysis clinic demand. |
| Software Companion Development | RFID traceability chip integration in polycarbonate-overmolded connectors meets US integrated delivery network recall automation mandates. |
Research Methodology
FDA 510(k) filings, EU MDR Article 10 technical documentation, and hospital procurement databases formed the secondary backbone of this analysis. Primary interviews with biomedical engineers, GPO contracts managers, dialysis clinic procurement directors, and precision mold technicians combined with secondary validation through customs trade data and SEC 10-K disclosures. Bottom-up and top-down triangulation cross-validated segment-level volume estimates against macro healthcare expenditure trends.
Bottom-up modeling anchored forecasts to installed base replacement cycles and dialysis clinic expansion trajectories across the projection horizon. Segmentation dimensions included product type, material grade, application pressure rating, and end-user sophistication tier. CAGRs derived from regression analysis of historical procurement patterns and regulatory compliance deadline impacts. Industry-specific inputs encompassed ISO 80369-7 enforcement timelines and chronic kidney disease prevalence projections.
Caveats apply where biocompatibility testing queue extensions or notified body capacity constraints could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization pace and polymer feedstock allocation stability. A small set of named triggers warrants ongoing watch: ISO 10993 laboratory capacity, EU MDR notified body processing times, and NMPA alignment with international connector standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.