
 Europe Arthroscopy Devices Market | 2026-2036
Europe Arthroscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Arthroscopy Devices Market Foresight
Hospital procurement consortia across Western Europe is fragmenting as national tender platforms and regional buying groups multiply contract structures. Arthrex Inc. leverages direct-to-surgeon training programs to sustain brand loyalty among sports medicine specialists. Karl Storz GmbH & Co. KG anchors its position through in-house optical manufacturing and rigid endoscope craftsmanship. Smith & Nephew PLC competes on fluid management system integration with shaver handpiece ecosystems.
Arthroscopy devices encompass visualization systems, powered instruments, and irrigation pumps designed for minimally invasive joint examination and intervention, typically operating through 2.7 mm to 4.0 mm portals with saline distension at 50-150 mmHg pressure. These systems enable diagnostic tissue assessment and therapeutic meniscal or ligament repair without open arthrotomy. Surgical instruments command durable revenue streams from blade and burr replacement cycles, while robotic-assisted systems represent the fastest-expanding technology tier as capital budgets shift toward precision guidance platforms. Wireless imaging modules attract upgrade interest from centers seeking to decouple camera heads from processor towers.
The EU Medical Device Regulation and EMA oversight of device-drug combination products impose extended clinical evidence requirements on novel arthroscopy platforms. CE marking under MDR Article 52 demands renewed technical documentation for legacy instruments, compressing timelines for manufacturers with extensive historical portfolios. Stakeholders must monitor notified body capacity bottlenecks and evolving harmonized standards for reusable device reprocessing validation.
Market Dynamics
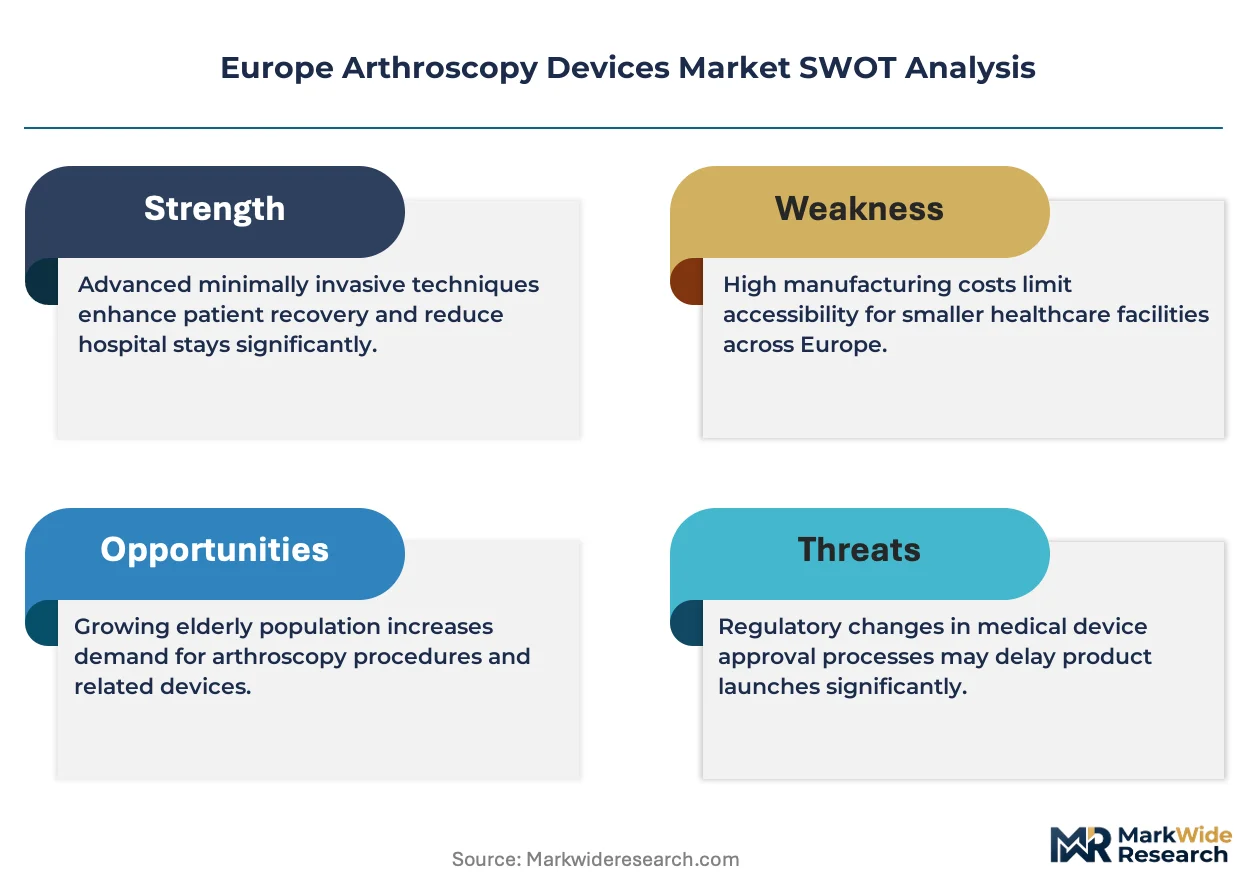
The EU Medical Device Regulation is compressing product lifecycles for legacy arthroscopy portfolios while simultaneously elevating clinical evidence thresholds for novel visualization platforms. MDR Article 52 conformity assessments and notified body capacity constraints are forcing manufacturers to prioritize portfolio rationalization over line extensions.
Growth Catalysts
- Ambulatory migration:Outpatient joint procedures are expanding across Western Europe as hospital procurement networks favor same-day surgical economics. Day-case arthroscopy volumes in Germany and the Netherlands are pulling capital equipment into standalone surgical centers.
- MDR transition window:The 2021-2028 legacy device recertification timeline is creating replacement demand for reusable hand instruments and rigid endoscopes that cannot meet renewed biocompatibility and reprocessing validation requirements.
- Wireless imaging modules:Camera head decoupling from processor towers is enabling modular upgrade paths. Academic medical centers in France and Italy are prioritizing wireless retrofit kits over full system replacements.
Market Restraints
- Notified body scarcity:Only 12 designated bodies hold MDR scope for active implantable accessories and Class III reusable instruments. Certification queues now extend 18-24 months, freezing product pipeline velocity for mid-tier manufacturers.
- Optical component concentration:Sapphire rod lens blanks and fiber optic light guides concentrate in a three-supplier ecosystem across southern Germany and northern Italy. Geopolitical friction or logistics disruption would cascade through endoscope production schedules.
- Capital budget compression:Hospital procurement consortia in Spain and Portugal are extending depreciation cycles for visualization towers from seven to ten years. Shaver system refresh rates are slowing proportionally.
Strategic Opportunities
- Central and Eastern Europe penetration:Poland and Czech Republic orthopedic specialist density remains 40% below Western European averages. Private hospital chains in Warsaw and Prague are building arthroscopy service lines with greenfield equipment purchases.
- Fluid management integration:Convergence of irrigation pump telemetry with shaver handpiece feedback loops enables pressure-automated tissue resection. Integrated ecosystem vendors capture recurring blade revenue through locked consumable protocols.
- Green procurement mandates:EU Green Deal circular economy requirements and national hospital sustainability scorecards in Denmark and Sweden are favoring reprocessable instruments over single-use alternatives. Reusable shaver blade revalidation services represent emerging revenue pools.
Industry Challenges
- Reprocessing technician certification:MDR harmonized standards for reusable device cleaning validation require specialized technician training that outpaces workforce supply in Southern European markets. Spanish and Italian sterile processing departments report 30% vacancy rates.
- Legacy system integration:Wireless camera modules must interface with 5-15 year-old processor towers through proprietary signal protocols. Engineering resources are diverting from next-generation development to backward compatibility testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Arthroscopy Devices Market |
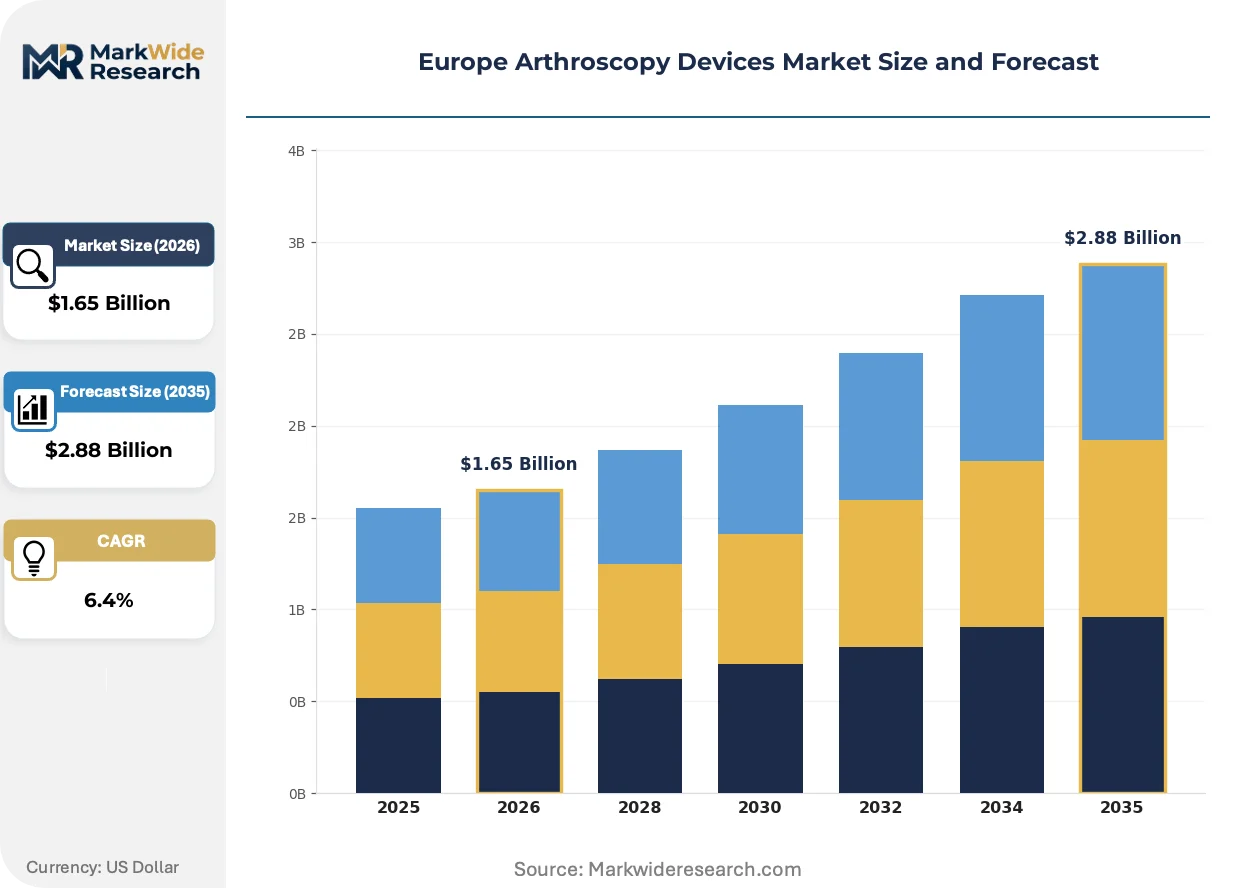
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arthroscopes, Surgical Instruments, Fluid Management Systems, Consumables End User: Hospitals, Ambulatory Surgical Centers, Orthopedic Clinics, Rehabilitation Centers Application: Sports Injuries, Joint Reconstruction, Diagnostic Procedures, Trauma Repair Technology: Wireless Imaging, 3D Visualization, Robotic-Assisted Systems, Conventional Methods |
| Companies Covered | Arthrex Inc., Stryker Corporation, Smith & Nephew PLC, Johnson & Johnson (DePuy Synthes), Conmed Corporation, Karl Storz GmbH & Co. KG, Richard Wolf GmbH, Medtronic PLC, Zimmer Biomet Holdings Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Arthroscopy Devices Market Shifts & Advancements
Robotic precision guidance is penetrating sports medicine procedures as capital budgets rotate toward platforms that reduce meniscal repair variability. Visualization hardware is decoupling from fixed infrastructure, while regulatory evidence requirements are reshaping product development timelines.
4K and 3D visualization systems are migrating from academic flagship hospitals to high-volume community orthopedic centers. German and French ambulatory surgical centers are adopting these platforms to differentiate on diagnostic accuracy for ligament reconstruction referrals. The technology is migrating from capital-intensive tower configurations toward modular camera-head upgrades that preserve existing processor investments.
MDR Article 52 and associated harmonized standards for active implantable accessories are extending clinical evaluation report requirements. Manufacturers must generate post-market clinical follow-up data for legacy shaver systems previously cleared under the Medical Device Directive. Class III reusable instruments face the steepest evidence burden, compressing development resources for novel blade geometries.
Hospital procurement consortia are fragmenting into regional buying groups with divergent technical specifications. National tender platforms in the Netherlands and Belgium are unbundling visualization towers from instrument sets, enabling mix-and-match vendor selection. This pattern is most visible in German university hospital networks, where orthopedic departments now source shaver handpieces and fluid management pumps from separate suppliers to optimize total cost of ownership.
Europe Arthroscopy Devices Market Segmentation
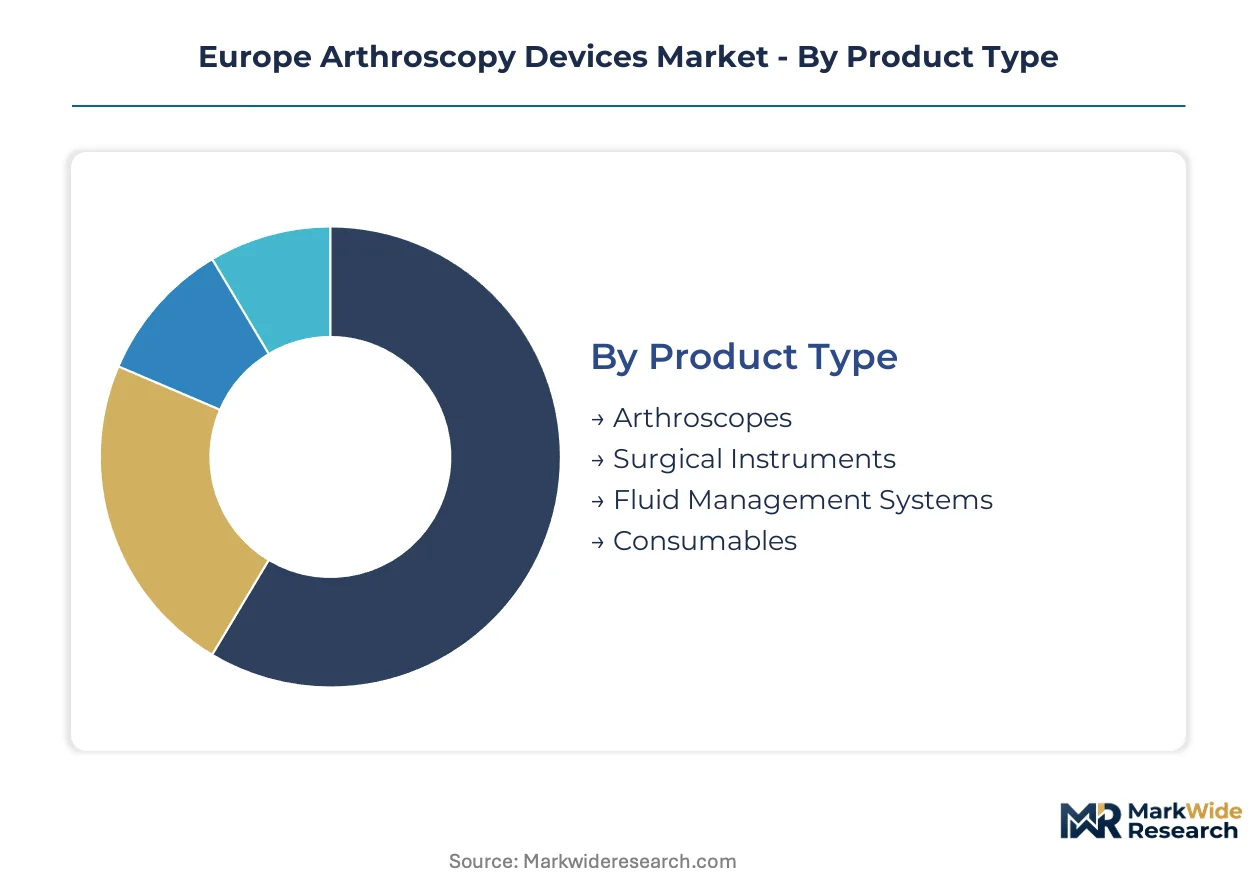
Arthroscopy device procurement patterns diverge sharply across customer settings and procedural applications. Understanding segment turnover velocity helps manufacturers align inventory cycles with replacement demand and MDR recertification timelines.
Product Type:
Replacement cycles stretch from months for disposable blades to decades for optical towers, creating divergent revenue recognition patterns across the installed base.
- Arthroscopes:Rigid endoscopes with rod-lens optical chains and fiber optic illumination bundles. German university hospital networks are prioritizing 4K resolution upgrades over full system replacements as MDR recertification deadlines approach.
- Surgical Instruments:Motorized shaver handpieces, burrs, and blade attachments with standardized autoclavable sterilization protocols. Day-case volume expansion in Dutch ambulatory centers is accelerating handpiece refresh rates.
- Fluid Management Systems:Irrigation pumps maintaining joint distension pressure. Pressure-automated resection integration is pulling upgrade interest from French orthopedic departments.
- Consumables:Single-use blades, cannulas, and drapes. Procurement consortia in Spain are unbundling these from capital equipment tenders to optimize total cost of ownership.
Surgical instruments dominate installed base. Consumables are where expansion concentrates.
End User:
Capital allocation authority varies across settings, with procurement consolidation in hospital networks contrasting against independent purchasing in standalone surgical centers.
- Hospitals:Academic medical centers and community hospitals with centralized sterile processing departments. Extended depreciation cycles in Portuguese public health systems are compressing visualization tower refresh budgets.
- Ambulatory Surgical Centers:Standalone facilities performing same-day joint procedures. Greenfield construction in Warsaw and Prague is driving new equipment demand without legacy system constraints.
- Orthopedic Clinics:Specialist practices with limited procedure volumes. Diagnostic arthroscopy referrals from Italian private clinics are sustaining secondary instrument demand.
- Rehabilitation Centers:Post-operative care facilities with minimal surgical intervention. Equipment needs concentrate on diagnostic visualization for treatment planning.
Hospitals anchor revenue concentration. Ambulatory surgical centers are climbing the fastest.
Application:
Procedure complexity and reimbursement levels shape device specification requirements across therapeutic versus diagnostic indications.
- Sports Injuries:Meniscal and ligament repair procedures in athletic populations. French and German sports medicine specialists are adopting robotic guidance platforms for meniscal suturing.
- Joint Reconstruction:Anterior cruciate ligament reconstruction and rotator cuff repair. Academic centers in Italy are prioritizing 3D visualization for complex multi-ligament knee reconstruction.
- Diagnostic Procedures:Exploratory arthroscopy for unexplained joint pain. Secondary care triage in UK NHS trusts is sustaining baseline arthroscope utilization.
- Trauma Repair:Acute fracture assessment and soft tissue damage evaluation. Emergency department integration in Spanish hospital networks is expanding diagnostic volume.
Joint reconstruction commands premium pricing. Sports injuries are gaining share fastest.
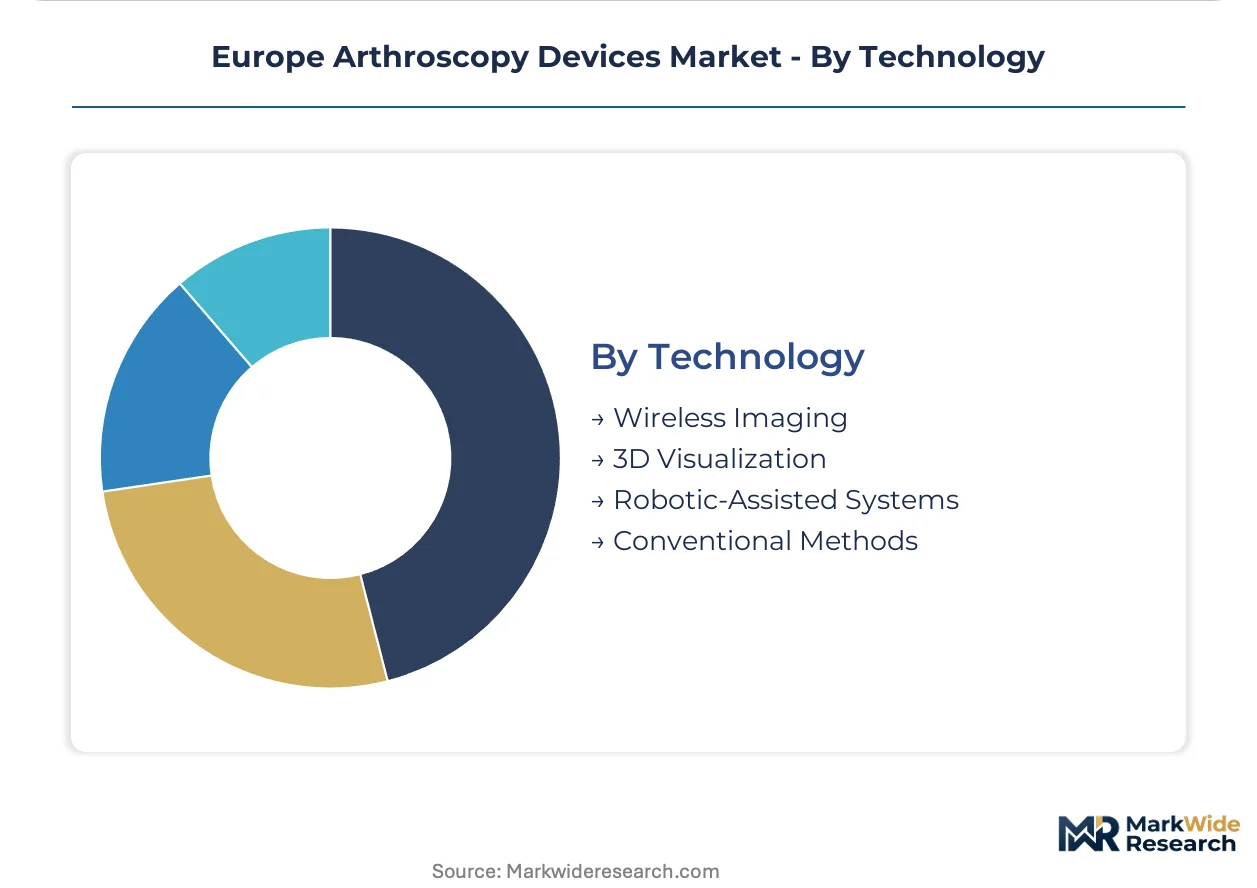
Technology:
Regulatory evidence burdens and capital intensity create tiered adoption timelines across visualization and guidance platforms.
- Wireless Imaging:Camera head decoupling from processor towers via radio frequency transmission. Modular retrofit kits are penetrating Belgian and Dutch centers seeking infrastructure preservation.
- 3D Visualization:Stereoscopic display systems for depth-perception enhancement. French community orthopedic centers are adopting these platforms to differentiate on ligament reconstruction accuracy.
- Robotic-Assisted Systems:Precision guidance platforms for instrument trajectory control. MDR clinical evidence requirements are compressing pipeline velocity for novel platform introductions.
- Conventional Methods:Standard 2D optical chains and manual instrument manipulation. Extended depreciation schedules in Southern European markets are sustaining this installed base.
Conventional methods dominate installed base. Wireless imaging is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Medical Device Regulation recertification timelines are redistributing procurement budgets across national health systems. Hospital networks in Western Europe are accelerating visualization tower replacements ahead of MDR deadlines while Central European greenfield facilities build service lines without legacy constraints.
Germany
University hospital procurement networks in Bavaria and North Rhine-Westphalia are consolidating arthroscopy equipment tenders under regional buying groups. KBA medical device quality standards and MDR Article 52 compliance requirements are compressing supplier qualification timelines. The Stuttgart optical manufacturing cluster anchors rigid endoscope production for domestic and export markets.
France
ANSM post-market surveillance mandates are extending clinical evaluation report requirements for active implantable accessories. Sports medicine specialists in Paris and Lyon are adopting 3D visualization platforms for meniscal repair differentiation. The Île-de-France region concentrates day-case arthroscopy volume in ambulatory surgical centers.
United Kingdom
NHS England procurement frameworks are unbundling visualization towers from instrument sets to optimize total cost of ownership. MHRA recognition of EU MDR certificates is maintaining device market access post-Brexit. The Oxford-Cambridge corridor hosts orthopedic technology clusters developing wireless imaging modules.
Italy
Regional health authorities in Lombardy and Emilia-Romagna are extending depreciation cycles for capital equipment amid budget compression. Italian notified body capacity constraints are delaying MDR certification for mid-tier manufacturers. Milan's private hospital chains are building arthroscopy service lines with greenfield equipment purchases.
Netherlands
Dutch national tender platforms are fragmenting procurement into specialized lots for fluid management systems and shaver handpieces. The country's hospital sustainability scorecards under EU Green Deal circular economy requirements favor reprocessable instruments. Rotterdam and Amsterdam ambulatory centers are expanding day-case joint procedure volumes.
Europe Arthroscopy Devices Market Competitive Landscape
On the supply side, the industry is consolidating around optical manufacturing specialists and integrated system vendors with captive consumable protocols. Tiered competitive dynamics separate premium visualization platform providers from mid-tier instrument manufacturers and regional service specialists. Strategic archetypes include in-house optical craftsmen, fluid management integrators, and direct-to-surgeon training organizations. Dominant competitive moves encompass portfolio rationalization ahead of MDR deadlines and modular wireless imaging retrofits that preserve installed base relationships.
Among German-based optical specialists, Karl Storz GmbH & Co. KG and Richard Wolf GmbH exemplify the craftsmanship archetype anchored in southern German manufacturing clusters. Arthrex Inc. represents the direct-to-surgeon training model that builds specialist loyalty independent of procurement channel control. Smith & Nephew PLC occupies a position within the integrated ecosystem tier where fluid management convergence with shaver handpiece telemetry creates consumable lock-in. These three archetypes illustrate how competitive positioning diverges between optical component mastery, surgeon relationship intensity, and system integration depth.
| Leading Market Players |
|---|
| Arthrex Inc. |
| Stryker Corporation |
| Smith & Nephew PLC |
| Johnson & Johnson (DePuy Synthes) |
| Conmed Corporation |
| Karl Storz GmbH & Co. KG |
| Richard Wolf GmbH |
| Medtronic PLC |
| Zimmer Biomet Holdings Inc. |
| Others |
Supply & Pricing Matrix
Southern German sapphire rod lens blank suppliers and northern Italian fiber optic light guide manufacturers anchor optical component production, concentrating margin capture upstream while endoscope assemblers compete on system integration value. This three-supplier ecosystem for critical optical inputs shapes downstream pricing power distribution across European arthroscopy device markets.
Pricing Analysis
Volume-discount tiering structures separate academic medical center consortia purchasing 50-plus unit annual volumes from standalone ambulatory surgical centers ordering single-digit systems. Pricing stratifies across premium 4K visualization platforms, standard HD tower configurations, and economy-grade refurbished equipment tiers. Cost compression in standard HD tiers is intensifying because Portuguese and Spanish hospital networks are extending depreciation cycles. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraint, while German university hospital networks prioritize performance specifications over unit economics.
Supply Chain Analysis
Contract manufacturing for arthroscope handpiece assemblies concentrates with specialized medical device EMS providers in Ireland, Switzerland, and southern Germany. Optical component sourcing draws from Stuttgart-area rod lens craftsmen, Milan-region fiber bundle fabricators, and Jena-based coating specialists. Single-source vulnerability for sapphire blank supply creates structural risk given limited qualified suppliers. Distribution runs through hospital procurement consortia and regional buying groups rather than direct manufacturer-to-facility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European arthroscopy device markets operate as a defensive-moat industry where MDR regulatory entrenchment creates substantial switching costs for hospital customers recertifying legacy instrument portfolios.
For Market Incumbents: Entrench market position through backward integration into optical component manufacturing and accelerated MDR technical documentation investment for legacy shaver systems. Wireless imaging module development represents the priority R&D lever against modular retrofit competitors. Fluid management ecosystem lock-in through proprietary shaver handpiece telemetry protocols defends recurring blade revenue streams from unbundled procurement trends. For New Entrants and Emerging Players: Central European private hospital construction in Warsaw and Prague offers greenfield penetration without legacy system integration burdens. Polish and Czech orthopedic specialist density gaps 40% below Western European averages present the most penetrable geography. Target day-case arthroscopy service line buildouts through disposable instrument bundling and rapid MDR certification pathways. For Investors and Strategic Acquirers: Capital is best deployed toward optical manufacturing specialists with in-house rod lens craftsmanship and established notified body relationships. Long-term viability hinges on MDR compliance infrastructure rather than product innovation velocity. Monitor notified body capacity expansion announcements as inflection indicator for pipeline velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerated legacy portfolio recertification secures market access ahead of notified body capacity constraints. |
| Wireless Imaging Module Development | Modular retrofit kits preserve installed base relationships while capturing upgrade revenue from infrastructure-constrained centers. |
| Fluid Management Ecosystem Integration | Pressure-automated resection telemetry locks consumable revenue through proprietary shaver handpiece protocols. |
| Central European Geographic Expansion | Greenfield hospital construction in Poland and Czech Republic bypasses legacy system integration barriers. |
| Reprocessable Instrument Revalidation Services | EU Green Deal circular economy compliance creates recurring revenue from reusable blade certification. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of hospital procurement databases, GPO contract filings, and EMA MDR certification records. Orthopedic surgeons, biomedical engineers, hospital purchasing committee chairs, and GPO contracts managers provided qualitative input. Secondary validation drew from ANSM post-market surveillance reports, NHS England procurement frameworks, and German KBA quality standard documentation. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Forecast inputs include procedure volume trajectories, capital equipment replacement cycles, and MDR recertification timeline compression. Segmentation dimensions span product type, end user setting, application complexity, and technology tier across the projection horizon. CAGRs derive from installed base turnover velocity and expansion coefficients for ambulatory surgical center construction. Wireless imaging adoption curves and robotic platform penetration rates inform technology tier forecasts.
Practitioners should monitor notified body designation expansion, MDR harmonized standard revisions, and optical component supplier capacity for early signals. Forecasts reflect assumptions regarding MDR transition timeline adherence and hospital procurement consolidation patterns. Quarterly review of CE marking queue lengths and sapphire blank supply availability is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Advanced Drug Delivery Systems Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Self-Injections Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Radiotherapy Devices Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Organ Care Market
Medical Devices
Biodegradable Stents Market
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
Global Colposcopy Devices Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Portable Dialysis Machines Market
Medical Devices
Spinal Fusion Market
Medical Devices
Global Wedge Pressure Catheter Market