
 Nerve Entrapment Syndrome Therapeutics Market | 2026-2036
Nerve Entrapment Syndrome Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Nerve Entrapment Syndrome Therapeutics Market Foresight
Buyer concentration across hospital procurement networks is broadening as integrated delivery systems consolidate formularies while independent pain clinics and ambulatory surgical centers fragment the outpatient channel. Pfizer Inc. leverages its established neurology portfolio to sustain institutional contracts with large health systems. Eli Lilly and Company anchors its position through biologics development for refractory neuropathic conditions. AbbVie Inc. differentiates via immunology-linked nerve pain research and specialty pharmacy distribution.
Nerve entrapment syndrome therapeutics encompass pharmacologic agents, minimally invasive decompression procedures, and rehabilitative modalities targeting compression-induced ischemia and demyelination of peripheral nerves, with functional parameters including nerve conduction velocity restoration and symptom severity scores. Medications and physiotherapy constitute the mature revenue base, while surgical interventions command premium positioning due to reimbursement complexity and specialist dependency. The pain management therapy area is attracting R&D allocation as clinicians seek alternatives to opioid-based protocols.
The FDA, EMA, and WHO pharmacovigilance frameworks govern clinical trial endpoints, post-market safety monitoring, and bioequivalence standards for generic neuropathic agents. These regulators shape demand by mandating comparative effectiveness data for new molecular entities and restricting certain active ingredients in specific populations. Stakeholders must monitor evolving biosimilar guidance and health technology assessment criteria that will determine formulary placement for next-generation biologic therapies.
Market Dynamics
FDA accelerated approval pathways for neuropathic pain therapies are compressing development timelines and reshaping competitive entry sequences across the nerve entrapment syndrome therapeutics landscape.
Growth Catalysts
- Specialized Nerve Center Expansion:Integrated care networks in the United States are broadening patient access to advanced interventions and decompression procedures.
- EMA Pharmacovigilance Frameworks:Post-market safety monitoring mandates for biologic therapies are elevating clinical evidence standards and accelerating differentiation.
- Minimally Invasive Techniques:Ultrasound-guided decompression and percutaneous approaches are reducing recovery times and expanding outpatient candidacy pools.
Market Restraints
- Specialist Dependency Bottlenecks:Surgical intervention capacity concentrates among fellowship-trained peripheral nerve surgeons, constraining procedure volume scalability.
- Reimbursement Complexity:Medicare's site-of-service differentials and prior authorization requirements for neuromodulation devices create administrative friction.
- Active Ingredient Restrictions:FDA population-specific limitations on certain neuropathic agents narrow prescribing flexibility for pediatric and geriatric cohorts.
Strategic Opportunities
- Ambulatory Surgical Center Channel:Independent ASCs are fragmenting the outpatient channel and creating direct-to-facility distribution pathways bypassing hospital procurement.
- Biologics-Physiotherapy Convergence:Combination protocols pairing anti-inflammatory biologics with targeted rehabilitation are opening premium positioning in refractory cases.
- Health Technology Assessment Tailwinds:NICE and IQWiG comparative effectiveness criteria are creating formulary fast-tracks for agents demonstrating functional parameter restoration.
Industry Challenges
- Electrodiagnostic Specialist Scarcity:The limited pipeline of neurologists with nerve conduction study certification is extending diagnostic bottlenecks.
- Legacy EMR Integration Friction:Ambulatory pain clinics face workflow disruption when incorporating nerve tracking software into existing electronic medical record architectures.
- Biosimilar Patent Thickets:Complex intellectual property layering around biologic neuropathic agents is delaying generic entry and licensing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nerve Entrapment Syndrome Therapeutics Market |
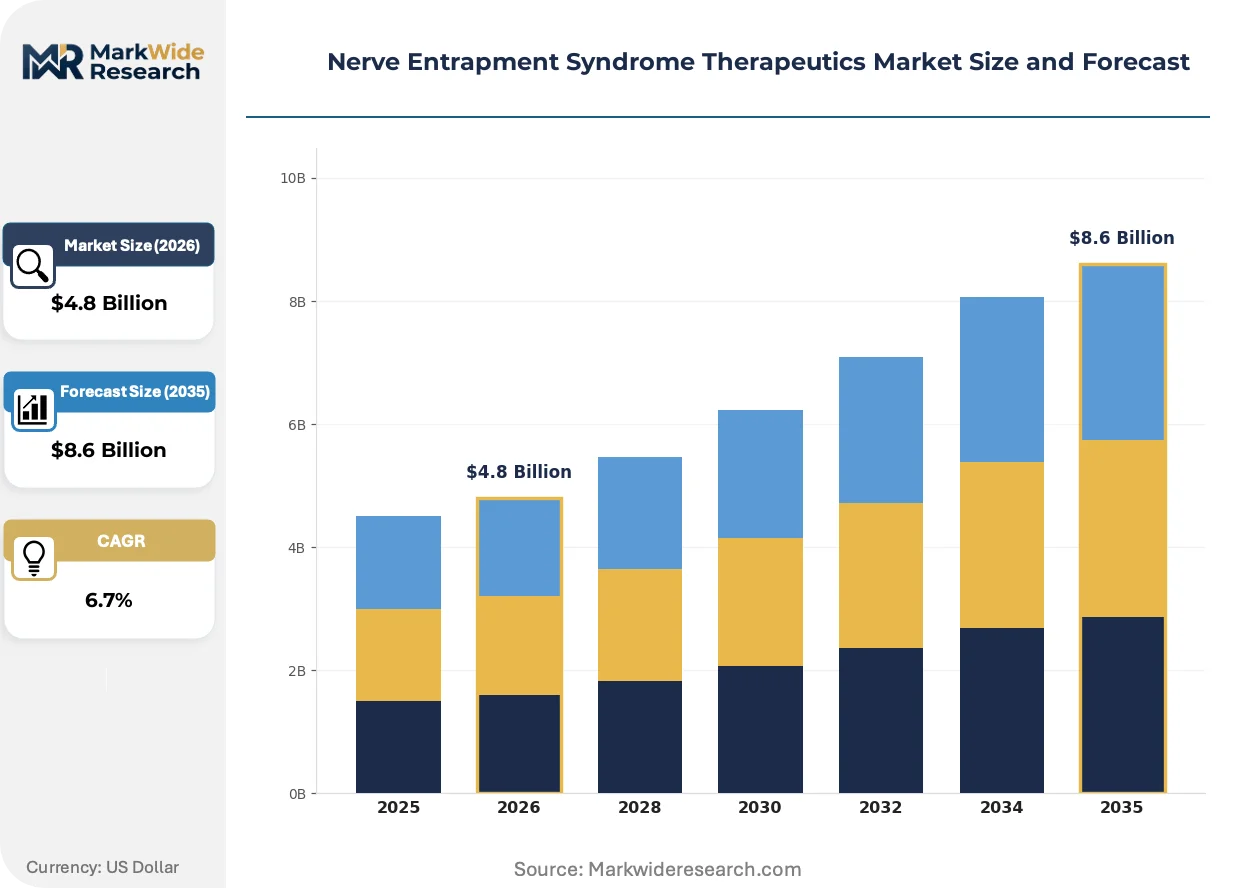
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Surgery, Physiotherapy, Bracing Therapy Area: Neurology, Orthopedics, Pain Management, Rehabilitation End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Oral, Injection, Topical, Surgical |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, AbbVie Inc., Novartis AG, Johnson & Johnson, GlaxoSmithKline, Sanofi, Boehringer Ingelheim, AstraZeneca Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nerve Entrapment Syndrome Therapeutics Market Shifts & Advancements
Neuromodulation device miniaturization and AI-assisted diagnostic platforms are converging to reshape treatment selection protocols and procedural precision standards.
Closed-loop peripheral nerve stimulation systems is unifying real-time feedback mechanisms with implantable pulse generators. Orthopedic clinics and pain management centers are adopting these platforms at accelerating cadence. The technology is unifying symptom monitoring with automated parameter adjustment, compressing the gap between pharmaceutical and interventional therapy boundaries.
The FDA's Breakthrough Device Designation pathway is expediting review timelines for novel neuromodulation hardware. Manufacturers must now submit prospective registry data as a condition of accelerated market entry. Implantable device segments are responding by pre-positioning post-market study infrastructure during pre-submission phases.
Integrated delivery systems are consolidating formularies while fragmenting outpatient access points. Hospital procurement networks are ceding volume to independent pain clinics and specialty ASCs. This bifurcation is most visible in the United States, where Medicare's site-neutral payment policies are accelerating channel migration away from inpatient settings.
Nerve Entrapment Syndrome Therapeutics Market Segmentation
Segmentation in nerve entrapment syndrome therapeutics reveals divergent procurement patterns across institutional buyers, with hospital networks prioritizing formulary consolidation while ambulatory channels fragment around procedure-specific technologies. Understanding these buyer archetypes shapes distribution strategy and R&D allocation for manufacturers navigating reimbursement complexity.
Product Type:
Purchasing committees differentiate segments based on reimbursement tiers and specialist dependency, with premium positioning reserved for interventions requiring fellowship-trained surgical expertise.
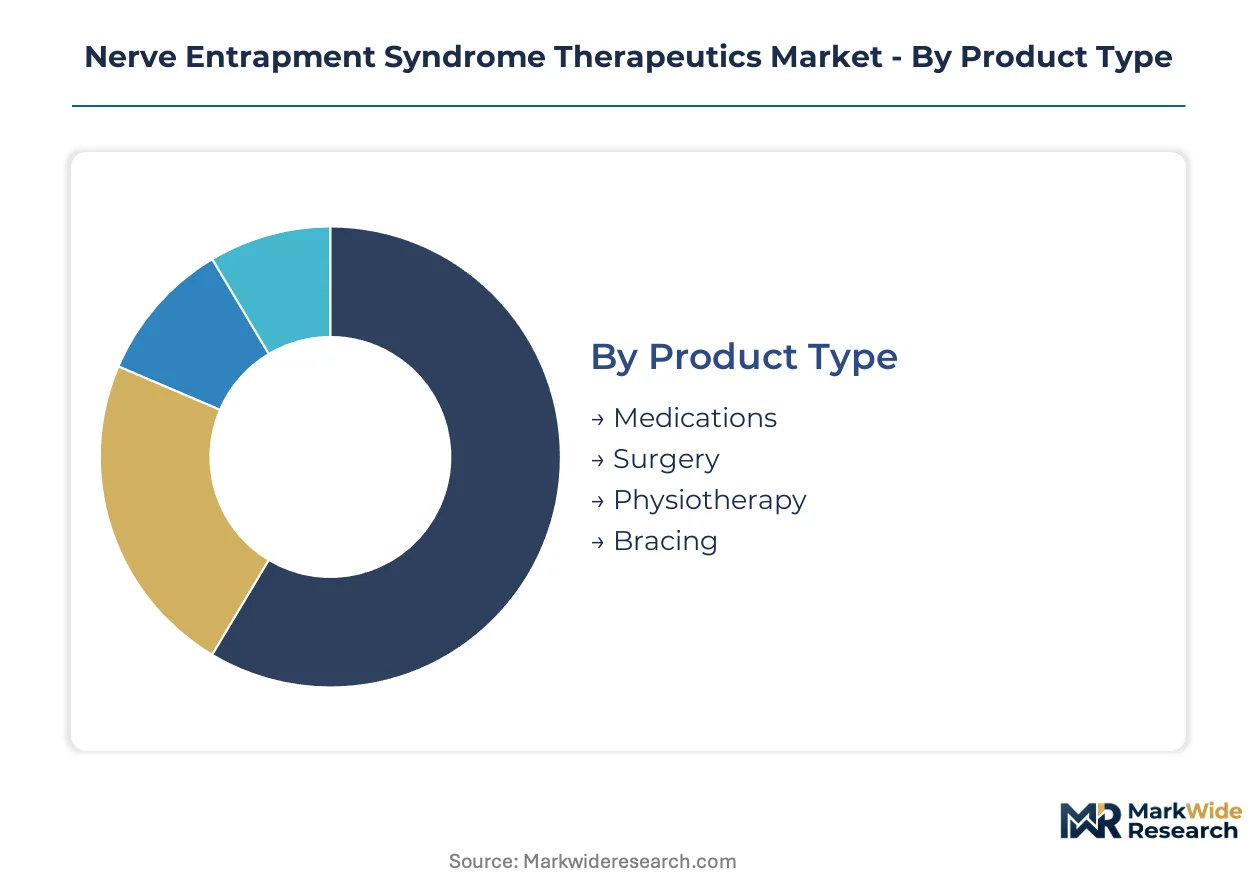
- Medications:Pharmacologic agents span anticonvulsants, tricyclic antidepressants, and topical formulations targeting neuropathic pain pathways. Demand concentrates in Medicare Part D formularies and integrated delivery system protocols, constrained by FDA population-specific restrictions on certain active ingredients in pediatric and geriatric cohorts.
- Surgery:Minimally invasive decompression procedures and open surgical releases address refractory compression-induced ischemia. Adoption accelerates in United States specialized nerve centers where ultrasound-guided techniques reduce recovery times and expand outpatient candidacy pools.
- Physiotherapy:Targeted rehabilitation modalities restore nerve conduction velocity through manual therapy and neuromuscular re-education.
- Bracing:Orthotic devices provide mechanical offloading for entrapment sites at the wrist, elbow, and ankle.
Volume sits with Medications; growth tilts toward Surgery.
Therapy Area:
Clinical evidence requirements vary sharply across therapy areas, with neurology demanding electrodiagnostic documentation and pain management emphasizing functional outcome metrics.
- Neurology:Nerve conduction studies and electromyography guide therapeutic selection in this segment. Electrodiagnostic specialist scarcity in United States academic medical centers extends diagnostic bottlenecks and delays treatment initiation.
- Pain Management:Multimodal protocols integrate pharmacologic and interventional approaches for refractory cases. ASC channel fragmentation in the United States creates direct-to-facility distribution pathways that bypass hospital procurement networks.
- Orthopedics:Structural entrapment at fibro-osseous tunnels drives surgical consultation volumes.
- Rehabilitation:Post-surgical and conservative care protocols emphasize functional parameter restoration.
Orthopedics captures the largest procedure volume; Pain Management is climbing the fastest.
End User:
Site-of-service economics reshape end-user channel dynamics, with Medicare's differential reimbursement steering volume away from inpatient settings toward lower-acuity environments.
- Hospitals:Inpatient and outpatient departments within integrated delivery systems maintain formulary control over high-cost biologics and neuromodulation devices. Procurement network consolidation across United States health systems compresses vendor margins while extending contract duration.
- Clinics:Independent pain clinics and orthopedic specialty practices fragment access points for decompression procedures. Legacy EMR integration friction disrupts workflow when these United States ambulatory sites adopt nerve tracking software.
- Home Care:Self-administered topical agents and bracing solutions serve stable patients post-stabilization.
- Rehabilitation Centers:Dedicated facilities deliver intensive physiotherapy protocols for functional recovery.
Hospitals retain biologic and device volume; Clinics are gaining share fastest.
Delivery Mode:
Regulatory pathway complexity segments delivery modes, with surgical and injectable categories facing steeper evidence thresholds than oral and topical alternatives.
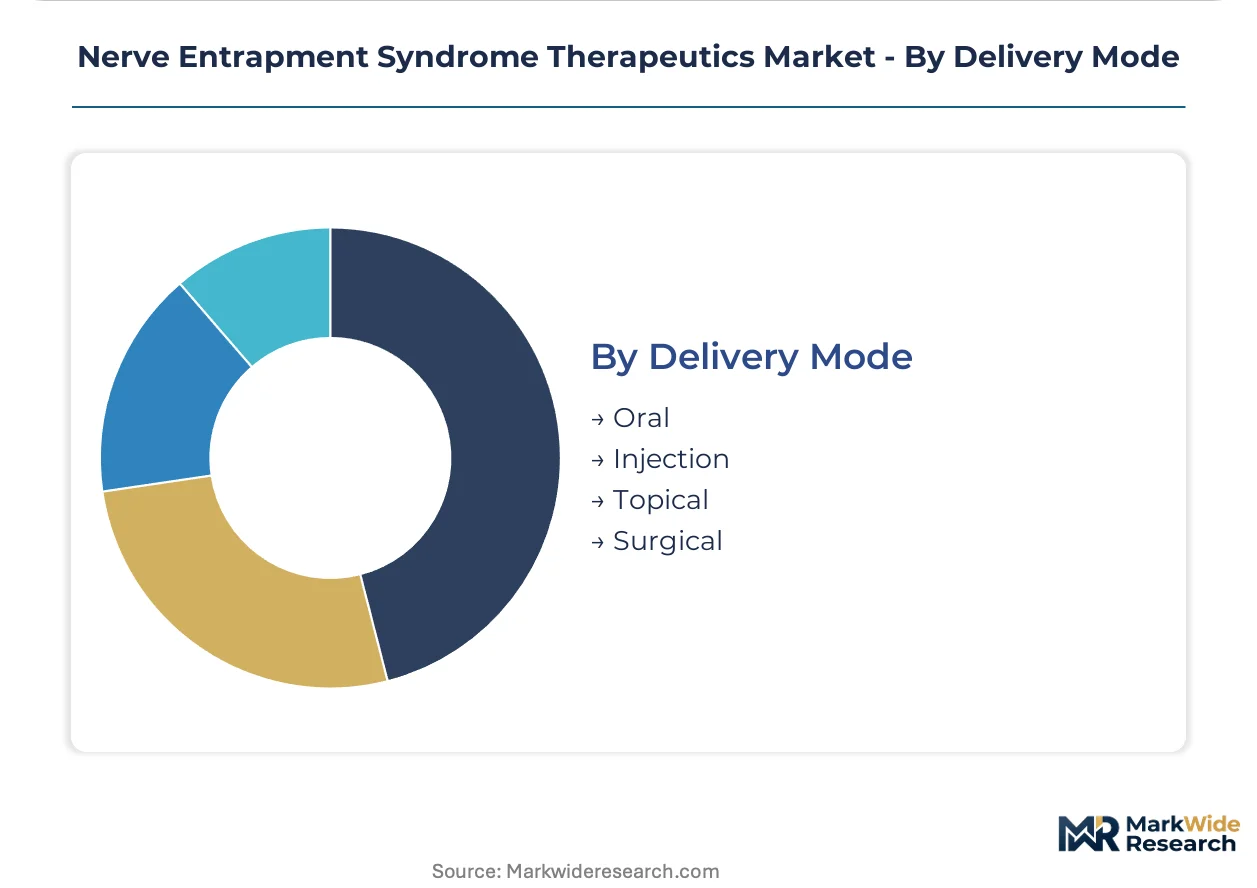
- Oral:Systemic agents including gabapentinoids and SNRIs constitute the mature revenue base for chronic neuropathic pain. FDA accelerated approval pathways for novel neuropathic pain therapies are compressing development timelines for new molecular entities in this category.
- Surgical:Implantable neuromodulation systems and open decompression procedures command premium positioning. FDA Breakthrough Device Designation expedites review timelines for closed-loop peripheral nerve stimulation hardware in United States markets.
- Injection:Corticosteroid and local anesthetic nerve blocks provide intermediate-term symptom relief.
- Topical:Transdermal formulations offer localized action with reduced systemic exposure.
Oral formulations dominate prescription volume; Surgical delivery shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for nerve entrapment syndrome therapeutics concentrates in the United States, where specialized nerve centers and integrated care networks drive procedure volumes and pharmaceutical consumption.
United States
Medicare's site-neutral payment policies accelerate patient migration toward ambulatory surgical centers and independent pain clinics. FDA accelerated approval pathways compress development timelines for novel neuropathic pain therapies. Major metropolitan clusters in the Northeast Corridor and California host the highest density of fellowship-trained peripheral nerve surgeons.
Germany
EMA pharmacovigilance frameworks elevate clinical evidence standards for biologic therapies entering German formularies. IQWiG comparative effectiveness criteria create fast-track pathways for agents demonstrating functional parameter restoration. The Baden-Württemberg region concentrates orthopedic device manufacturing and specialized rehabilitation infrastructure.
Japan
PMDA review timelines for neuromodulation hardware align with METI's healthcare technology export priorities. Aging demographics expand the addressable patient pool for carpal tunnel and cubital tunnel interventions. The Kanto region around Tokyo anchors electrodiagnostic specialist training and peripheral nerve research institutes.
United Kingdom
NICE technology appraisals determine formulary placement for next-generation biologic therapies across NHS integrated care systems. Post-Brexit regulatory divergence from EMA frameworks creates parallel submission requirements for market entry. The Greater Manchester and London clusters concentrate specialized hand surgery units and nerve decompression referral networks.
India
CDSCO streamlined approval pathways for generic neuropathic agents attract multinational manufacturing investment. Rising diabetes prevalence expands the diabetic neuropathy patient base requiring entrapment syndrome management. The Maharashtra and Karnataka corridors host contract research organizations conducting clinical trials for peripheral nerve interventions.
Nerve Entrapment Syndrome Therapeutics Market Competitive Landscape
United States-based pharmaceutical conglomerates anchor one tier; European specialists and diversified healthcare conglomerates hold differentiated positions through regional regulatory expertise and biologics development. The vendor base organizes around three strategic archetypes: neurology-focused majors leveraging institutional contracts, immunology-linked researchers pursuing specialty pharmacy distribution, and diversified healthcare conglomerates spanning device and pharmaceutical portfolios. Competitive maneuvering concentrates on M&A activity targeting neuromodulation hardware capabilities and strategic partnerships with ambulatory surgical center networks.
Within the neurology-focused tier, Pfizer Inc. and Eli Lilly and Company exemplify institutional contract anchoring through established therapeutic portfolios. AbbVie Inc. occupies a position representing immunology-linked nerve pain research specialization. These three entities collectively illustrate the competitive structure: pharmaceutical conglomerates with neurology heritage, biologics developers targeting refractory conditions, and immunology-crossover researchers differentiating via specialty distribution channels.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| AbbVie Inc. |
| Novartis AG |
| Johnson & Johnson |
| GlaxoSmithKline |
| Sanofi |
| Boehringer Ingelheim |
| AstraZeneca Plc |
| Others |
Supply & Pricing Matrix
Active pharmaceutical ingredient spot indices for gabapentinoids and SNRIs cascade through contract manufacturing networks into three-tier pricing structures across premium, standard, and economy levels for finished neuropathic agents. Pharmaceutical procurement committees in United States integrated delivery systems exploit volume concentration to compress margins on oral formulations while surgical device tiers preserve premium positioning through specialist dependency.
Pricing Analysis
Volume concentrates in oral generic gabapentinoids where Medicare Part D formularies drive price compression; margins concentrate in implantable neuromodulation systems where FDA Breakthrough Device Designation creates temporary exclusivity windows. Price differentiation rests on certification tier—FDA PMA-approved devices command 40-60% premiums over 510(k) cleared alternatives—and procedural reimbursement codes. Pricing pressure stems from biosimilar entry into biologic neuropathic pain categories, with cost compression intensifying in the standard tier. Ambulatory surgical centers exhibit highest price sensitivity due to site-of-service reimbursement differentials; academic medical centers show lowest sensitivity where bundled payments obscure unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese API manufacturers supplying gabapentinoid precursors and Indian contract research organizations conducting electrodiagnostic device validation. Finished pharmaceutical production concentrates in United States, Germany, and India; neuromodulation hardware assembly centers on United States and Japan. Raw material dependencies include lithium-ion cells for implantable pulse generators, platinum-iridium electrodes, and medical-grade silicone encapsulants. Supply chain risk centers on tariff exposure for Chinese-sourced rare earth elements in magnet-dependent stimulation components. Distribution runs through specialty pharmacy networks for biologics, direct-to-facility contracts for ASCs, and GPO-negotiated hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nerve entrapment syndrome therapeutics market sits in a technology-transition phase where closed-loop peripheral nerve stimulation systems displace open-loop legacy hardware and pharmacologic monotherapy protocols.
For Market Incumbents: Extend institutional contract duration through integrated care network partnerships that bundle surgical, pharmacologic, and rehabilitation services into single-source agreements. Lock in electrodiagnostic specialist training pipelines to defend against diagnostic bottleneck constraints that delay competitive entry. Prioritize backward integration into implantable pulse generator battery cell supply to mitigate lithium-ion sourcing risk from Asian suppliers. For New Entrants and Emerging Players: Begin with ultrasound-guided decompression device distribution through independent pain clinics in United States metropolitan clusters where hospital procurement network consolidation has ceded outpatient volume. Target the ambulatory surgical center channel with compact, disposable surgical kits that bypass capital equipment procurement committees. Pursue direct-to-facility sales models that circumvent GPO contracting friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor neuromodulation hardware specialists with FDA pre-submission phase closed-loop platforms in United States markets. Long-term viability hinges on reimbursement code acquisition and post-market study infrastructure pre-positioning. Watch for Medicare site-neutral payment policy expansion as the inflection signal accelerating ASC channel migration and compressing inpatient procedure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Accelerated review timelines compress competitive entry windows for closed-loop stimulation hardware. |
| Ambulatory Surgical Center Distribution Partnership | Direct-to-facility contracts bypass hospital GPO procurement networks and capture site-of-service migration. |
| Electrodiagnostic Specialist Training Pipeline Investment | Diagnostic bottleneck alleviation expands addressable patient pools for surgical intervention candidates. |
| Biologics-Physiotherapy Combination Protocol Development | Premium positioning in refractory cases commands formulary placement above generic pharmacologic monotherapy. |
| Post-Market Registry Infrastructure Pre-Positioning | FDA accelerated approval conditions require prospective data submission as mandatory market entry requirement. |
Research Methodology
Multi-period observation of nerve conduction velocity restoration metrics, symptom severity score trajectories, and procedural volume migration patterns anchored the trend analysis, supplemented by interviews with peripheral nerve surgeons, pain management clinic directors, hospital formulary committee members, and ASC procurement officers. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare claims data, ClinicalTrials.gov neuropathic pain study registries, and EMA pharmacovigilance reports. Bottom-up patient flow modeling and top-down pharmaceutical consumption estimates were triangulated against integrated delivery system contract disclosure patterns.
Input-output matrices mapped therapy area demand drivers to product type supply responses across the projection horizon, with segmentation dimensions spanning delivery mode, end-user channel archetype, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity models and pharmaceutical pricing erosion curves. Forecast inputs included Medicare site-of-service reimbursement differential trajectories and FDA review timeline compression factors for breakthrough-designated devices.
Regulatory pathway reversals, biosimilar launch timing accelerations, and electrodiagnostic specialist training pipeline disruptions are the dominant revision risks for therapeutic adoption trajectories. Forecasts embed assumptions around reimbursement stability and specialist capacity expansion that may shift with policy or labor market changes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Buruli Ulcer Treatment Market
Specialty Medicine
Pigmentosa Treatment Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Partial Onset Seizures Market
Specialty Medicine
Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
Atrial Septal Defect Market