
 Global Canes and Crutches Market | 2026-2036
Global Canes and Crutches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Canes and Crutches Market Foresight
Asset-light leasing models for durable medical equipment are rewriting competitive dynamics in mobility aids. Drive DeVilbiss Healthcare leverages direct-to-patient subscription programs to sustain recurring revenue without manufacturing bloat. Medline Industries anchors hospital procurement through integrated supply contracts that bundle canes with broader patient discharge kits. Cardinal Health competes on distribution density, controlling same-day delivery networks that reduce inventory carrying costs for physical therapy clinics.
Canes and crutches are load-bearing assistive devices engineered to redistribute body weight away from impaired lower limbs, with axillary crutches typically rated for users up to 136 kg and forearm variants employing cuff-based stabilization for prolonged ambulation. Folding canes using aircraft-grade aluminum or pultruded carbon fiber dominate retail pharmacy channels due to portability, while platform crutches occupy a narrow but high-margin niche for patients with wrist or hand pathologies. Rehabilitation centers and physical therapy clinics represent the fastest-growing end-user channel as value-based care contracts push post-acute recovery outside hospital walls.
The FDA classifies canes and crutches as Class I medical devices with 510(k) exemption, lowering barriers for new entrants but requiring adherence to ISO 11199-2 durability testing; the EU Medical Device Regulation (MDR) imposes stricter clinical evaluation and post-market surveillance obligations that favor established manufacturers with notified body relationships. Japan's PMDA enforces JIS T 9203 standards for structural integrity that exceed baseline ISO requirements. Stakeholders must monitor how reimbursement coding changes in Medicare and Germany's G-BA affect patient out-of-pocket exposure and channel mix between retail and institutional procurement.
Market Dynamics
Carbon fiber pultrusion is collapsing the traditional aluminum supply chain in premium mobility aids, as Japanese and German manufacturers enforce stricter durability benchmarks that legacy materials cannot satisfy.
Growth Catalysts
- Ambulatory surgical expansion:OECD health systems are routing more orthopedic procedures to outpatient settings, creating immediate post-discharge demand for forearm crutches and folding canes in the United States and Germany.
- METI durability mandates:Japan's Ministry of Economy, Trade and Industry tightened JIS T 9203 structural integrity requirements, accelerating replacement cycles for institutional-grade devices in physical therapy networks.
- Carbon fiber cost curves:Pultruded composite manufacturing achieves economies previously reserved for aerospace, enabling weight reductions below 250 grams in retail pharmacy channels without premium pricing.
Market Restraints
- Aluminum price volatility:Aircraft-grade 6061-T6 aluminum sheet remains the dominant input for economy canes, exposing manufacturers to London Metal Exchange fluctuations that compress margin at the standard tier.
- Notified body scarcity:EU MDR clinical evaluation requirements for Class I assistive devices create bottlenecks as only twelve designated bodies handle orthopedic rehabilitation equipment across the continent.
- Reimbursement coding fragmentation:Medicare HCPCS codes E0100-E0105 and Germany's G-BA Hilfsmittelverzeichnis impose incompatible documentation standards, forcing dual-track product development for transatlantic suppliers.
Strategic Opportunities
- India's geriatric infrastructure gap:The country's national health mission lacks dedicated assistive device procurement protocols for district hospitals, creating first-mover advantage for suppliers establishing institutional relationships before standardization.
- Direct-to-patient subscription models:Leasing platforms bypass retail pharmacy markups by delivering forearm crutches and platform variants to post-surgery patients with inclusive maintenance and upgrade rights.
- ISO 11199-2 harmonization:Convergence between FDA 510(k) exemption pathways and enhanced durability testing protocols enables single-SKU strategies that reduce inventory complexity across North American and European distribution.
Industry Challenges
- Pultrusion technician scarcity:Carbon fiber composite manufacturing requires specialized layup and curing expertise that vocational programs in the United States and Germany have not scaled to meet rehabilitation equipment demand.
- Legacy ERP integration:Hospital procurement systems running on 1990s-era platforms cannot process subscription billing cycles or usage-based depreciation models, forcing manual reconciliation for innovative pricing structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Canes and Crutches Market |
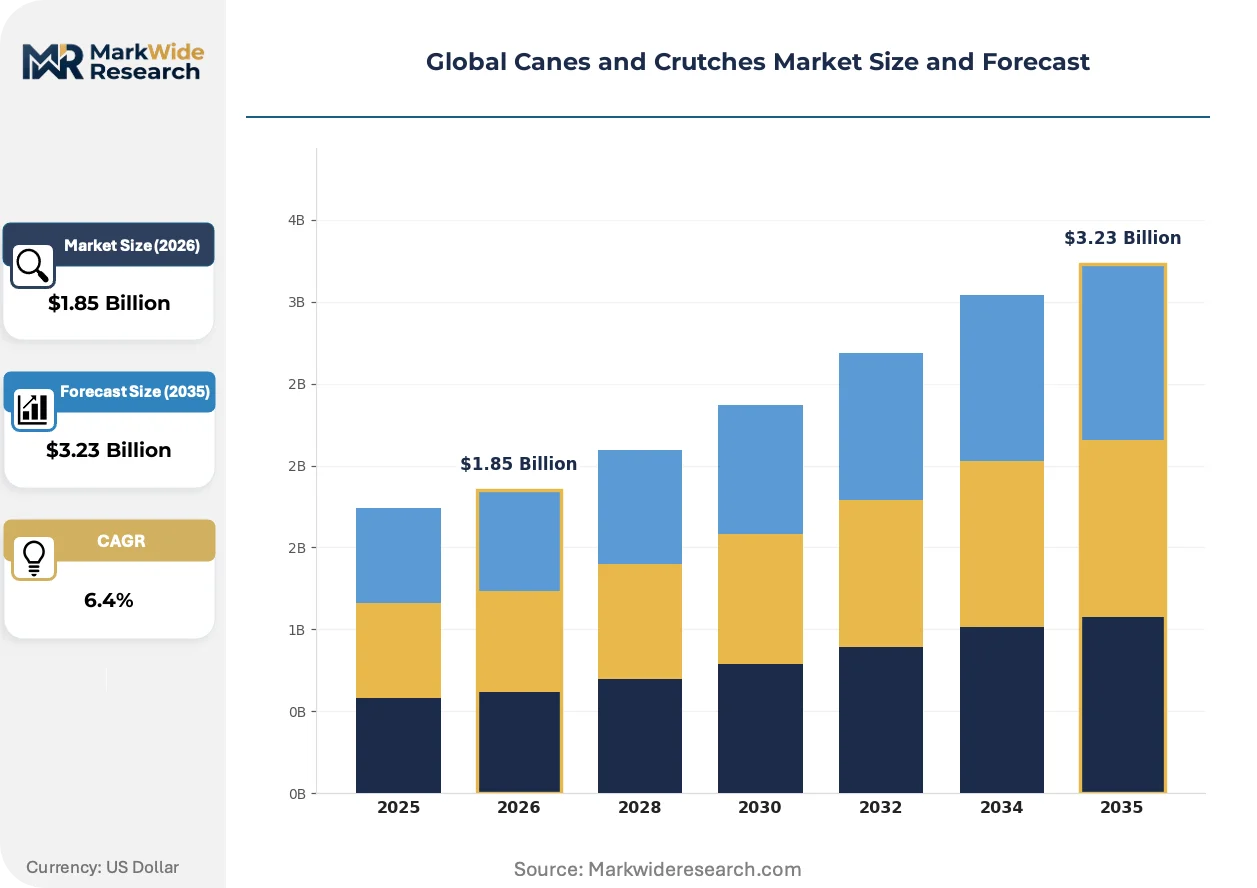
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cane, Quad Cane, Folding Cane, Axillary Crutch, Forearm Crutch, Platform Crutch Material: Wood, Aluminum, Carbon Fiber, Steel, Plastic, Fiberglass End User: Geriatric Patients, Post-Surgery Recoverees, Rehabilitation Centers, Physical Therapy Clinics Application: Mobility Assistance, Injury Recovery, Elderly Support, Rehabilitation Therapy, Balance Improvement |
| Companies Covered | Drive DeVilbiss Healthcare, Medline Industries, Cardinal Health, Invacare Corporation, NOVA Medical Products, Sunrise Medical, GF Health Products, Ossenberg GmbH, Besco Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Canes and Crutches Market Shifts & Advancements
Material substitution and regulatory convergence are compressing product lifecycles while opening new channels that bypass traditional durable medical equipment distribution.
Pultruded carbon fiber construction is collapsing the weight-performance tradeoff that constrained aluminum cane design for decades. Rehabilitation centers in Germany and Japan now specify sub-300-gram forearm variants as standard discharge equipment, forcing retail pharmacy suppliers to source composite components or exit the premium tier entirely. The structural consequence is a bifurcated supply base where captive carbon fiber production determines competitive position.
Japan's PMDA enforcement of JIS T 9203 standards exceeding baseline ISO 11199-2 requirements is redirecting R&D investment toward fatigue-testing infrastructure. Manufacturers serving the Japanese institutional market must maintain in-house structural validation capabilities that add fixed cost but create defensible relationships with Ministry of Health-designated suppliers. Physical therapy clinic chains in Osaka and Tokyo now demand batch-level test documentation that European notified bodies do not require.
Hospital value-based care contracts are unbundling post-acute recovery from inpatient reimbursement, transferring procurement authority to physical therapy networks with distinct technical preferences. These outpatient operators prioritize platform crutches and cuff-stabilized forearm variants over traditional axillary designs, reshaping demand concentration away from retail pharmacy channels toward institutional distributors in the United States and Germany. The shift compresses sales cycles but requires field-based clinical education capabilities that legacy manufacturers lack.
Global Canes and Crutches Market Segmentation
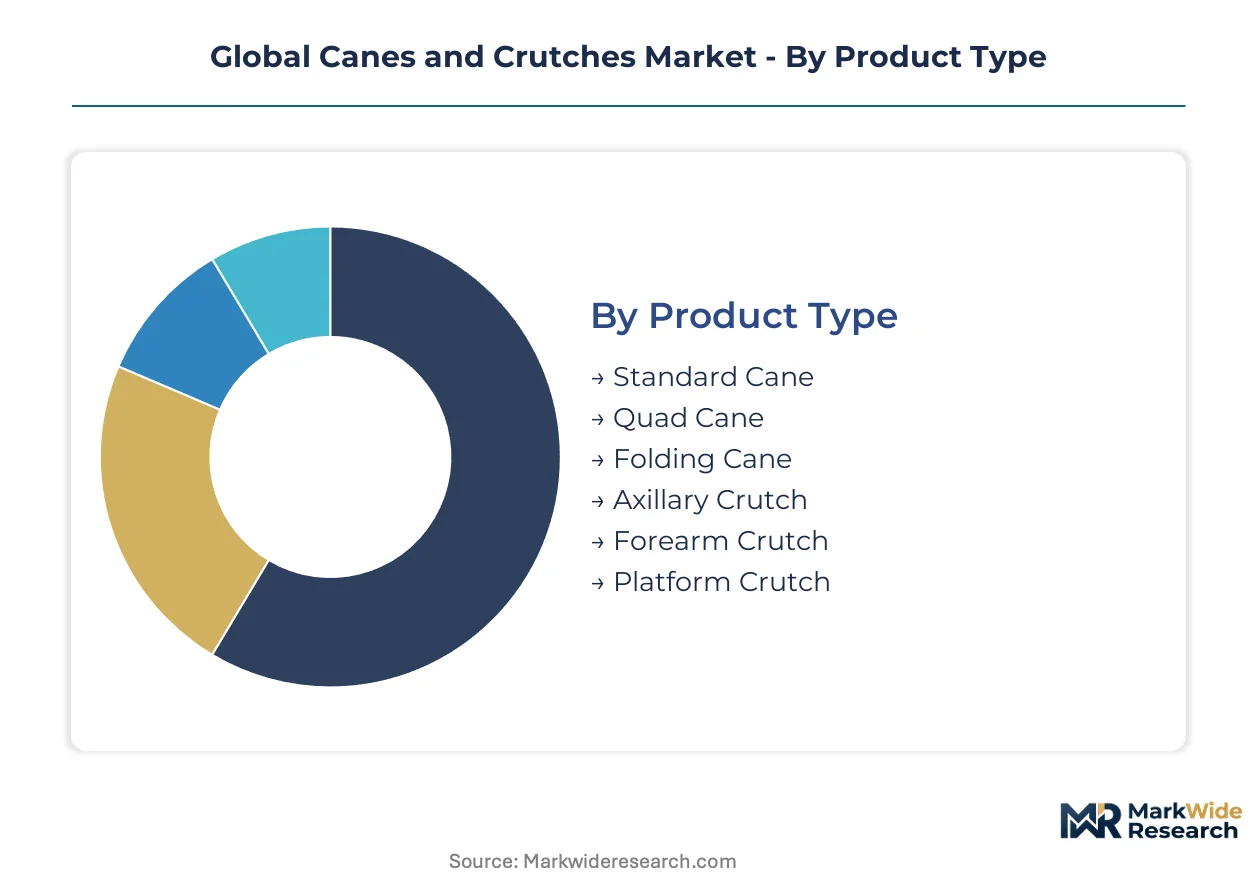
Segmentation in canes and crutches determines service intensity, warranty exposure, and channel economics. Product durability varies dramatically by material and use case, creating divergent aftermarket requirements across each category.
Product Type:
After-sales service intensity escalates with mechanical complexity and patient dependency duration. Axillary and forearm crutches demand higher maintenance cadence than single-point canes due to joint wear and cuff fatigue.
- Standard Cane:Single-shaft aluminum or wood construction with rubber tip interface. German retail pharmacies move volume through this entry tier, though margin compression from private-label competition limits service bundling.
- Quad Cane:Four-point base widens stability footprint for balance-impaired users. Japanese institutional procurement specifies quad bases for stroke rehabilitation discharge, driving replacement tip demand in Osaka and Tokyo clinic networks.
- Folding Cane:Collapsible shaft segments using aircraft-grade aluminum or carbon fiber. Post-surgery recoverees in United States outpatient settings prioritize portability for travel between physical therapy appointments.
- Axillary Crutch:Underarm pad with bilateral shaft configuration supports non-weight-bearing ambulation. Rated to 136 kg user mass per ISO 11199-2, these dominate orthopedic ward discharge in Germany where hospital procurement specifies institutional-grade durability.
- Forearm Crutch:Cuff-based proximal stabilization enables prolonged use without axillary nerve compression. Carbon fiber variants under 250 grams now specify standard in Japanese JIS T 9203 compliance, creating technician-intensive repair networks.
- Platform Crutch:Forearm trough design redistributes load for wrist or hand pathology patients. Narrow volume but highest service attachment rate due to custom fitting requirements in United States physical therapy chains.
By volume, Standard Cane leads. By growth pace, Forearm Crutch is ahead.
Material:
Cost tier stratification separates premium composite supply from commodity metal and polymer channels. Raw material volatility and fabrication complexity determine which segments absorb price shocks versus passing through to end users.
- Wood:Traditional shaft material with aesthetic appeal in retail pharmacy gift segments. Limited structural rating restricts use to sub-100 kg patients, constraining institutional uptake.
- Aluminum:Aircraft-grade 6061-T6 dominates economy and mid-tier production. London Metal Exchange price swings directly compress margin for standard cane and axillary crutch manufacturers serving Medicare reimbursement channels.
- Carbon Fiber:Pultruded composite achieves sub-250 gram forearm crutch weights with superior fatigue resistance. Japanese and German manufacturers now require captive carbon fiber supply to meet institutional durability mandates.
- Steel:Chromoly and stainless variants serve bariatric applications exceeding aluminum ratings. Heavyweight penalty limits retail appeal despite superior load capacity.
- Plastic:Injection-molded components in cuffs, tips, and adjustment mechanisms. Replacement part demand generates recurring revenue streams for distributors with field service capabilities.
- Fiberglass:Intermediate stiffness-to-weight ratio occupies niche between aluminum and carbon fiber. Limited adoption due to splintering risk under cyclic loading.
Aluminum commands volume leadership. Carbon fiber claims the steepest expansion trajectory.
End User:
Customer type dictates procurement authority, technical specification complexity, and pricing negotiation leverage. Institutional buyers consolidate volume while individual patients prioritize accessibility and out-of-pocket cost.
- Geriatric Patients:Independent elderly users purchasing through retail pharmacy or direct-to-patient channels. United States Medicare HCPCS coding determines copay exposure, steering demand toward E0100-E0105 eligible aluminum canes.
- Post-Surgery Recoverees:Orthopedic discharge population requiring temporary ambulatory support. OECD outpatient surgical expansion routes this cohort through physical therapy clinics rather than hospital procurement.
- Rehabilitation Centers:Inpatient and residential facilities with centralized purchasing and equipment pooling. Germany's G-BA Hilfsmittelverzeichnis compliance requirements dominate technical specifications.
- Physical Therapy Clinics:Outpatient operators gaining procurement authority under value-based care unbundling. These networks in United States and Japan now specify platform and forearm variants over traditional axillary designs.
Geriatric Patients generate highest unit volume. Physical Therapy Clinics are climbing the fastest.
Application:
Use case severity determines product lifespan expectations and upgrade cycling frequency. Acute recovery applications tolerate lower durability than chronic support scenarios where device reliability affects daily independence.
- Mobility Assistance:General ambulatory support for mild impairment or fatigue management. Folding canes dominate this broad category across United States retail pharmacy and German drugstore chains.
- Injury Recovery:Temporary weight offloading during fracture or ligament healing. Post-surgery recoverees in OECD systems drive forearm crutch demand with 6-12 week usage windows.
- Elderly Support:Fall prevention and balance augmentation for aging populations. Japanese institutional procurement prioritizes JIS T 9203 certified devices for this chronic-use segment.
- Rehabilitation Therapy:Clinician-supervised functional restoration programs. Physical therapy clinics in Germany specify adjustable platform crutches for wrist-compromised patients.
- Balance Improvement:Proprioceptive training and vestibular rehabilitation applications. Narrow segment with specialized quad cane configurations for neurological conditions.
Mobility Assistance leads in shipment volume. Injury Recovery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for carbon fiber pultrusion components concentrates supply risk in Japanese and German manufacturing clusters, while finished device exports from these centers flow toward United States and Indian distribution networks.
United States
Medicare HCPCS coding E0100-E0105 steers geriatric patient procurement toward aluminum canes with defined copay structures. The FDA's Class I 510(k) exemption pathway enables rapid product iteration for domestic manufacturers. Physical therapy clinic chains in Florida and Texas now specify platform crutches for wrist-compromised post-surgical patients.
Germany
The G-BA Hilfsmittelverzeichnis mandates technical documentation standards that institutional buyers enforce through centralized procurement. EU MDR notified body relationships favor established orthopedic rehabilitation equipment suppliers with clinical evaluation capabilities. Manufacturing clusters in North Rhine-Westphalia produce institutional-grade axillary crutches rated to ISO 11199-2 fatigue specifications.
Japan
METI-enforced JIS T 9203 standards exceed baseline ISO requirements, accelerating replacement cycles in Osaka and Tokyo physical therapy networks. PMDA structural integrity mandates redirect R&D investment toward in-house fatigue-testing infrastructure. Domestic manufacturers maintain captive carbon fiber supply to meet sub-250-gram forearm crutch specifications.
India
The national health mission lacks dedicated assistive device procurement protocols for district hospitals, creating first-mover positioning for suppliers establishing institutional relationships. Central government geriatric infrastructure spending remains fragmented across state-level implementation. Manufacturing concentration in Maharashtra and Gujarat serves export markets while domestic distribution networks mature.
United Kingdom
NHS procurement frameworks bundle canes within broader patient discharge protocols, compressing standalone device margins. MHRA post-Brexit regulatory alignment with EU MDR creates transitional compliance costs for importers. Rehabilitation center networks in Greater London prioritize forearm variants over traditional axillary designs under value-based recovery contracts.
Global Canes and Crutches Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated durable medical equipment distributors with captive logistics networks, specialized orthopedic rehabilitation manufacturers with regulatory certification depth, and private-label assemblers serving retail pharmacy channels. Competitive positioning depends on carbon fiber sourcing relationships, notified body access for EU MDR compliance, and field service density for institutional accounts. Dominant moves include backward integration into pultruded composite production and subscription-based leasing platforms that bypass traditional distributor markups.
Among North American distributors, Drive DeVilbiss Healthcare exemplifies the asset-light leasing archetype through direct-to-patient subscription programs. Medline Industries anchors hospital procurement relationships through integrated supply contracts bundling mobility aids within discharge protocols. German manufacturer Ossenberg GmbH occupies a position within the specialized fabrication tier serving institutional durability requirements.
| Leading Market Players |
|---|
| Drive DeVilbiss Healthcare |
| Medline Industries |
| Cardinal Health |
| Invacare Corporation |
| NOVA Medical Products |
| Sunrise Medical |
| GF Health Products |
| Ossenberg GmbH |
| Besco Medical |
| Others |
Supply & Pricing Matrix
Japanese carbon fiber pultrusion capacity concentrates supply power for sub-250-gram forearm crutch components, directing margin capture toward manufacturers with captive composite production rather than aluminum-dependent assemblers in retail pharmacy channels.
Pricing Analysis
Institutional buyers anchor pricing stratification across premium, standard, and economy tiers. Medicare HCPCS coding and Germany's G-BA Hilfsmittelverzeichnis create incompatible documentation standards that force dual-track product development, while carbon fiber certification premiums widen spreads between JIS T 9203-compliant devices and baseline ISO 11199-2 alternatives. Price erosion runs through aluminum-dependent economy canes as London Metal Exchange volatility compresses margins. Post-surgery recoverees through physical therapy clinics show lowest price sensitivity due to reimbursement coverage, whereas independent geriatric patients in United States retail channels face highest out-of-pocket exposure.
Supply Chain Analysis
Tariff exposure between United States and Chinese aluminum suppliers dominates supply risk calculus for economy cane manufacturers. Production gravity centers on Japan, Germany, and United States, with pultruded carbon fiber drawing from Japanese Toray-grade feedstock and aircraft-grade 6061-T6 aluminum resting on London Metal Exchange pricing. Single-source vulnerability concentrates in carbon fiber prepreg supply for institutional-grade forearm crutches. Distribution runs through hospital procurement systems, integrated durable medical equipment distributors, and direct-to-patient subscription platforms that bypass traditional retail pharmacy markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery driven by OECD ambulatory surgical expansion routing post-discharge demand through outpatient physical therapy networks rather than inpatient procurement.
For Market Incumbents: Insulate institutional relationships by deepening backward integration into captive carbon fiber pultrusion capacity, securing JIS T 9203 and ISO 11199-2 dual certification infrastructure, and deploying field-based clinical education teams that platform crutch and forearm variant specifications require. Aluminum price volatility and notified body scarcity for EU MDR compliance represent the primary margin threats demanding defensive positioning.
For New Entrants and Emerging Players: India's district hospital infrastructure gap offers first-mover positioning before national health mission standardization formalizes assistive device procurement protocols. Target subscription-based leasing models that bypass legacy ERP limitations in hospital systems, and prioritize direct-to-patient delivery of forearm crutches with inclusive maintenance rights to capture post-surgery recoverees outside traditional distributor channels.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized orthopedic rehabilitation manufacturers with established notified body relationships and carbon fiber sourcing depth rather than commodity aluminum assemblers. Long-term viability across the projection horizon hinges on regulatory certification moats and institutional channel control. The inflection signal to monitor is Medicare HCPCS coding expansion for platform crutch reimbursement eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Pultrusion | Captive composite supply secures JIS T 9203 compliance and institutional procurement preference in Japan. |
| Direct-to-Patient Subscription Launch | Bypasses legacy hospital ERP limitations while capturing recurring revenue from post-surgery recoverees. |
| Dual Certification Investment (ISO 11199-2 + JIS T 9203) | Enables single-SKU strategies reducing inventory complexity across North American and Japanese distribution. |
| Field Service Network Expansion | Platform crutch custom fitting requirements demand clinical education capabilities that legacy manufacturers lack. |
| Physical Therapy Clinic Partnership Program | Value-based care unbundling transfers procurement authority to outpatient networks specifying forearm variants. |
Research Methodology
Operator-level perspectives from hospital procurement managers, physical therapy clinic directors, biomedical engineers, and durable medical equipment distributors anchored the qualitative base. Primary interview findings combined with secondary validation against FDA 510(k) exemption filings, CMS Medicare HCPCS coding databases, Japan's PMDA device registrations, and EU MDR notified body documentation. Customs trade data for carbon fiber composite imports and aluminum sheet shipments provided material flow triangulation. Bottom-up unit economics from institutional procurement contracts and top-down market sizing from ambulatory surgical volume trends were reconciled.
Scenario-bracketing around ambulatory surgical expansion rates, carbon fiber cost curve trajectories, and reimbursement coding changes shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, material grade tier, end-user channel, and regional regulatory cluster. CAGRs derived from patient discharge volume projections, replacement cycle assumptions for institutional-grade devices, and penetration rate modeling for subscription-based delivery models. Pultrusion technician availability constraints and legacy ERP integration barriers served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in aluminum commodity pricing, yen-euro exchange rates affecting carbon fiber import costs, or Medicare reimbursement rate adjustments would shift the trajectory. Forecasts reflect documented assumptions regarding ambulatory surgical routing, METI enforcement continuity, and notified body capacity expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
UHD Surgical Display Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Bandage Contact Lenses Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Slip Disc Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
General Surgical Devices Market
Medical Devices
Ultrasound Probe Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market