
 Global Gait Analysis System Market | 2026-2036
Global Gait Analysis System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gait Analysis System Market Foresight
Artificial intelligence integration into motion-capture pipelines is reshaping how gait analysis systems process kinematic data in real time. Vicon Motion Systems leverages proprietary camera-to-software architectures to sustain premium positioning in optical motion capture. Qualisys anchors Nordic research demand through university partnerships across Sweden and Denmark. Tekscan differentiates via pressure-mapping insoles that extend gait assessment beyond laboratory settings into ambulatory monitoring.
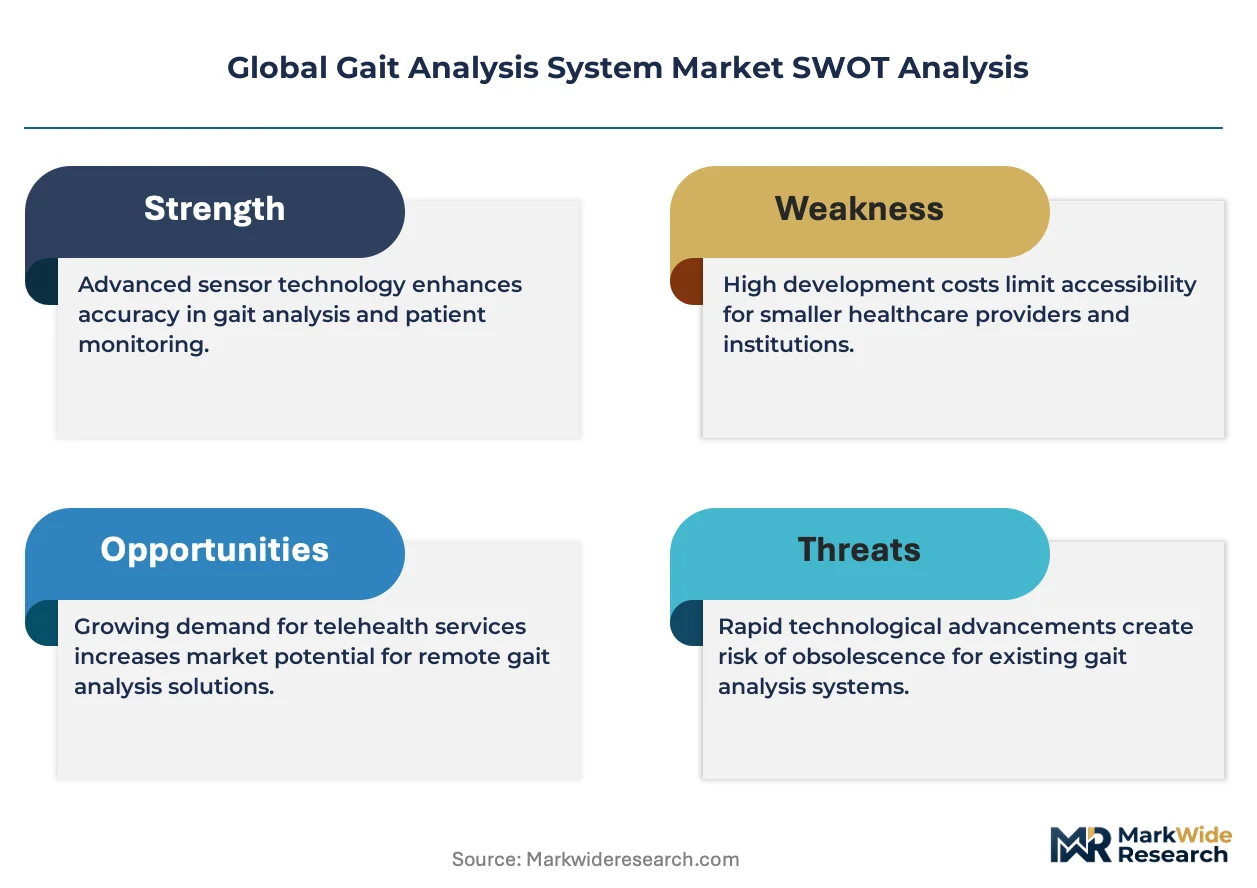
A gait analysis system comprises hardware and software platforms that measure, record, and interpret human locomotion patterns through optical markers, inertial measurement units, pressure plates, or surface electromyography, typically capturing temporal-spatial parameters at sampling rates exceeding 100 Hz to support clinical diagnosis and athletic optimization. Optical systems dominate installed base value due to gold-standard accuracy in multi-camera laboratory configurations, while wearable devices represent the fastest-expanding category as miniaturized inertial sensors enable community-based and longitudinal studies. Rehabilitation therapy applications command sustained procurement volume from hospital outpatient departments, whereas sports performance segments concentrate margin pools through customized athlete-biomechanics contracts.
The FDA regulates gait analysis software with diagnostic claims as Class II medical devices, requiring 510(k) premarket notification and driving vendors toward rigorous clinical validation protocols. The EU Medical Device Regulation mandates notified-body conformity assessment for systems deployed in European clinical settings, while ISO 9001 and ISO 13485 quality management frameworks govern manufacturing consistency across international supply chains. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring, as payor decisions will determine whether cloud-connected gait platforms achieve sustainable clinical economics outside research budgets.
Market Dynamics
Artificial intelligence integration into motion-capture pipelines is compressing the time from raw kinematic capture to clinical decision support, forcing vendors to rearchitect software validation protocols around real-time algorithmic outputs.
Growth Catalysts
- FDA 510(k) pathway maturation:Clearance precedents for gait analysis software with diagnostic claims are accelerating hospital procurement cycles in the United States.
- Pressure-mapping insole miniaturization:Wearable sensor advances are extending gait assessment from laboratory confinement into ambulatory monitoring applications.
- Veterans' hospital infrastructure buildout:Dedicated motion analysis laboratories across United States federal healthcare facilities are generating sustained equipment demand.
Market Restraints
- Optical system capex concentration:Multi-camera laboratory configurations require substantial upfront investment, limiting penetration beyond academic medical centers and elite sports institutes.
- EU MDR conformity assessment bottlenecks:Notified-body capacity constraints are elongating market access timelines for European clinical deployments.
- Sensor calibration labor intensity:Inertial measurement unit drift characteristics necessitate frequent recalibration protocols that inflate total cost of ownership.
Strategic Opportunities
- Community-based longitudinal studies:Wearable device form factors are unlocking ambulatory gait monitoring outside traditional laboratory settings.
- Remote therapeutic monitoring reimbursement:Evolving payor codes in the United States may enable sustainable clinical economics for cloud-connected gait platforms.
- AI-IMU fusion architectures:Machine learning integration with inertial sensor arrays is creating predictive gait analytics for fall-risk populations.
Industry Challenges
- Biomechanist talent scarcity:Specialized expertise in clinical movement science and engineering is concentrating at a limited number of academic institutions.
- Interoperability fragmentation:Proprietary data formats across optical, inertial, and pressure-sensing modalities complicate multi-system integration in research laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gait Analysis System Market |
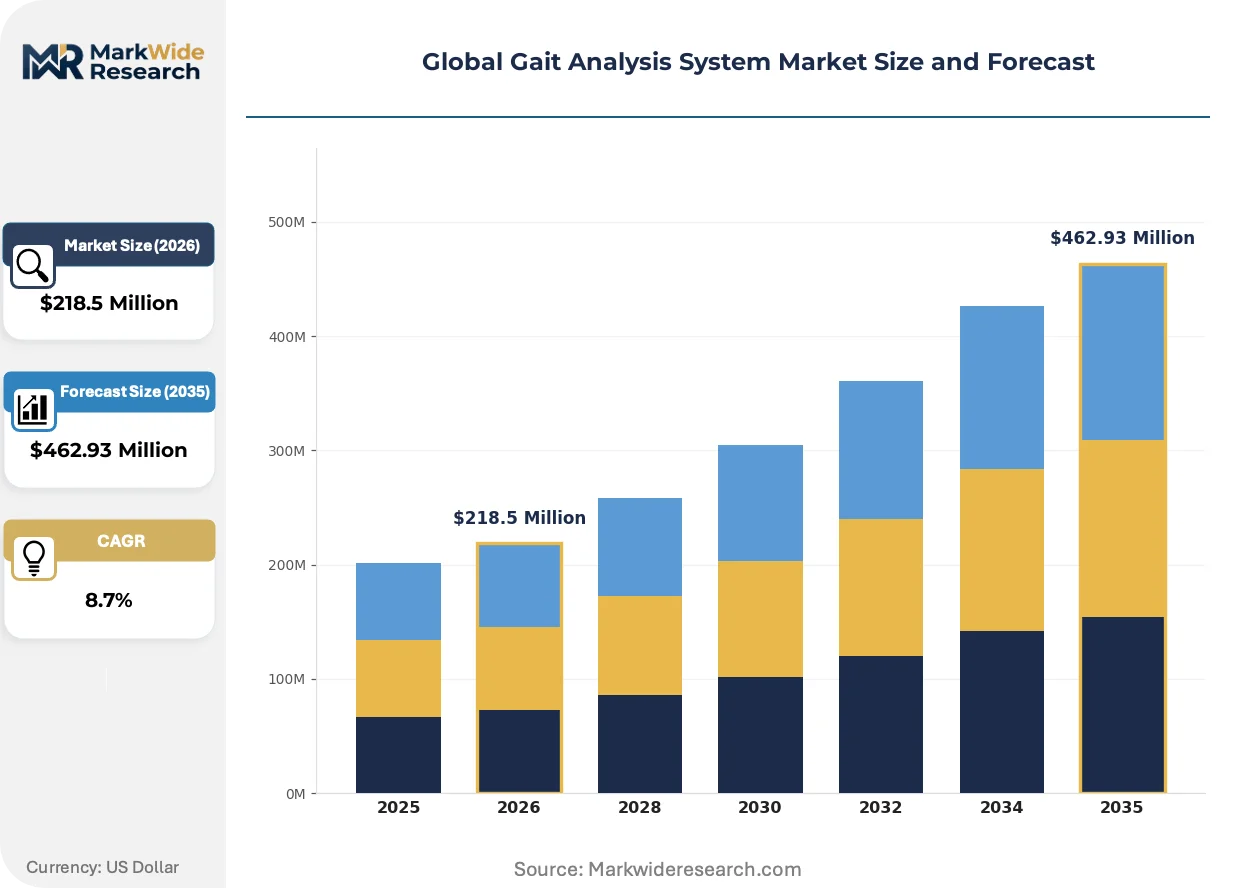
| Market Size in 2026 | $218.5 Million |
| Market Size in 2035 | $462.93 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Optical Systems, Pressure Sensors, Inertial Sensors, Electromyography Systems Application: Sports Performance, Biomechanical Research, Rehabilitation Therapy, Fall Risk Assessment, Ergonomic Studies End User: Research Institutes, Rehabilitation Centers, Sports Academies, Orthopedic Clinics, Military Training Facilities Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Mobile Platforms |
| Companies Covered | Vicon Motion Systems, Qualisys, BTS Bioengineering, Motion Analysis Corporation, Noraxon USA, Tekscan, Zebris Medical GmbH, Kistler Group, BioSensics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gait Analysis System Market Shifts & Advancements
Real-time kinematic processing architectures are displacing batch-mode analysis workflows, while regulatory frameworks on both sides of the Atlantic tighten software validation requirements for diagnostic-grade platforms.
Deep learning algorithms applied to markerless video capture are digitizing motion analysis by extracting three-dimensional joint kinematics from standard camera feeds without specialized laboratory infrastructure. Sports medicine clinics in Germany and Japan are piloting these systems for rapid athlete screening. The technology is digitizing competitive positioning by collapsing the cost barrier between research-grade and point-of-care gait assessment.
The EU Medical Device Regulation's software-as-a-medical-device classification criteria are redefining conformity assessment obligations for gait analysis platforms deployed in European clinical settings. Systems with diagnostic algorithmic outputs now require notified-body intervention where previous self-certification sufficed. Rehabilitation centers in Sweden and Denmark are prioritizing vendors with established MDR technical documentation.
Subscription-based software licensing is displacing perpetual license models among academic research consortia, unbundling hardware procurement from analytics platform access. University laboratories in the United States and Denmark are negotiating multi-site enterprise agreements that include cloud data storage and algorithmic update streams. This shift is most visible in longitudinal aging studies requiring decade-spanning data continuity without capital refresh cycles.
Global Gait Analysis System Market Segmentation
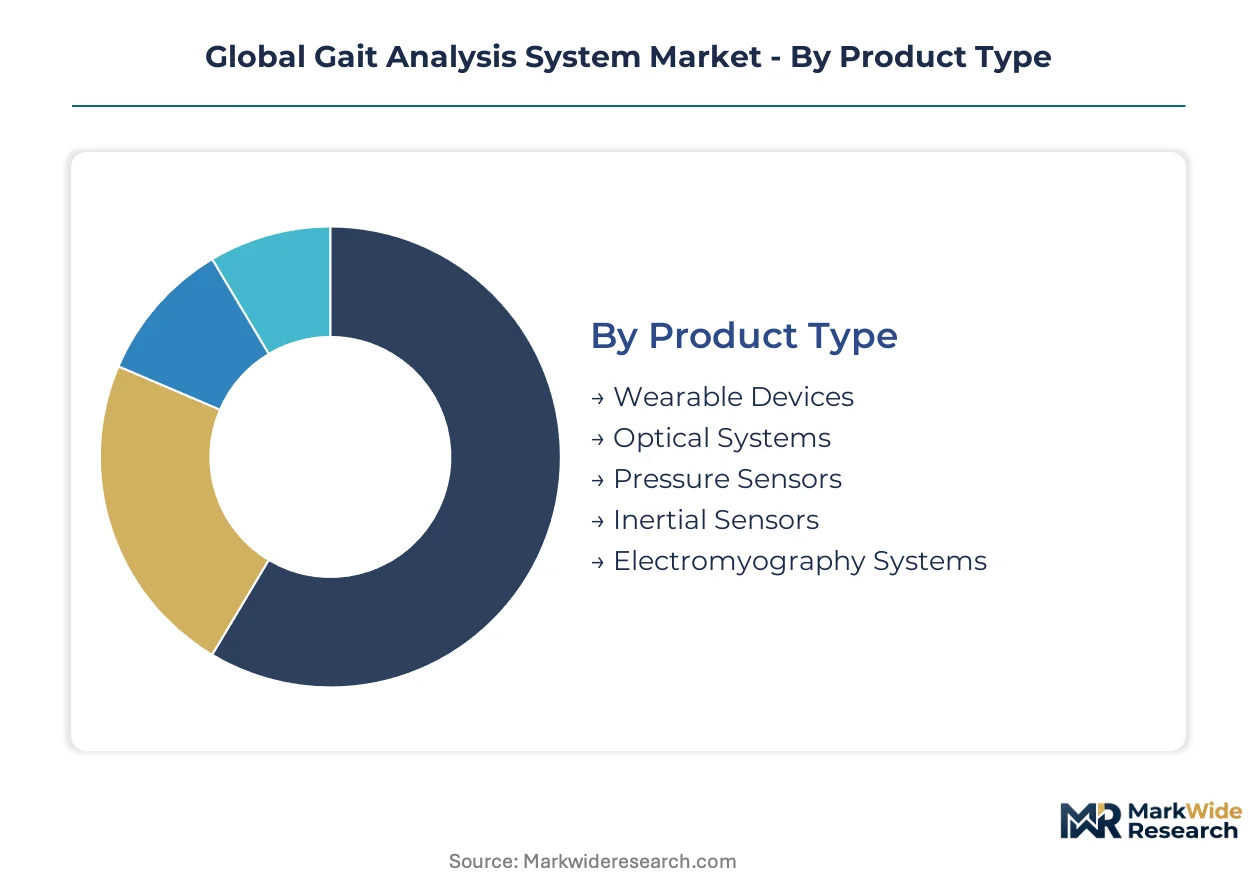
Gait analysis systems fragment across multiple technical and commercial dimensions, with procurement patterns varying sharply by institutional budget tier and clinical versus research mission. Understanding these segment boundaries clarifies why vendors pursue radically different go-to-market architectures for laboratory installations versus ambulatory deployments.
Product Type:
Cost tier stratification across hardware categories determines addressable customer base width, with premium optical configurations commanding capital budgets an order of magnitude above wearable alternatives.
- Optical Systems:Multi-camera laboratory configurations with marker-based tracking deliver sub-millimeter positional accuracy at sampling rates exceeding 200 Hz. Academic medical centers in the United States and veterans' hospitals sustain procurement volume despite six-figure capital requirements.
- Wearable Devices:Miniaturized inertial measurement units and pressure-mapping insoles enable longitudinal monitoring outside controlled environments. Rehabilitation centers in Germany and Japan are expanding ambulatory assessment programs using these form factors.
- Pressure Sensors:Force plate and insole arrays quantify ground reaction forces and plantar pressure distribution.
- Inertial Sensors:Accelerometer-gyroscope packages capture segmental kinematics without camera infrastructure.
- Electromyography Systems:Surface electrode arrays measure muscle activation timing and intensity during locomotion.
Optical systems command the established base. The steepest expansion runs through wearable devices.
Application:
Application focus shapes regulatory pathway complexity and reimbursement feasibility, with diagnostic claims triggering FDA 510(k) requirements that sports performance contracts avoid entirely.
- Rehabilitation Therapy:Post-stroke and post-surgical gait retraining protocols demand precise temporal-spatial metrics for insurance documentation. Hospital outpatient departments in the United States represent concentrated procurement volume.
- Sports Performance:Customized athlete biomechanics contracts generate margin concentration through recurring consulting relationships. Elite training facilities in Germany and Japan commission bespoke motion analysis installations.
- Biomechanical Research:Longitudinal aging studies and disease progression trials require decade-spanning data continuity.
- Fall Risk Assessment:Geriatric screening programs in Nordic countries deploy portable systems for community-based evaluation.
- Ergonomic Studies:Workplace movement analysis supports occupational health interventions and injury prevention protocols.
Rehabilitation therapy absorbs the largest capital allocation. Sports performance delivers the highest margin per installation.
End User:
Customer type determines purchasing cycle length and technical support intensity, with research institutes tolerating experimental configurations that clinical settings reject.
- Research Institutes:University laboratories prioritize data export flexibility and algorithmic customization over turnkey operation. Multi-site consortia in Denmark and Sweden negotiate enterprise software licensing across distributed camera networks.
- Rehabilitation Centers:Clinical workflow integration and EMR connectivity dominate procurement criteria. German rehabilitation chains are consolidating vendor relationships to standardize outcome measurement.
- Sports Academies:Rapid athlete throughput demands automated reporting pipelines.
- Orthopedic Clinics:Pre-operative planning and post-operative monitoring applications require diagnostic-grade validation.
- Military Training Facilities:Load carriage and injury prevention studies drive specialized procurement.
Research institutes maintain the deepest installed base. Rehabilitation centers are expanding procurement most aggressively.
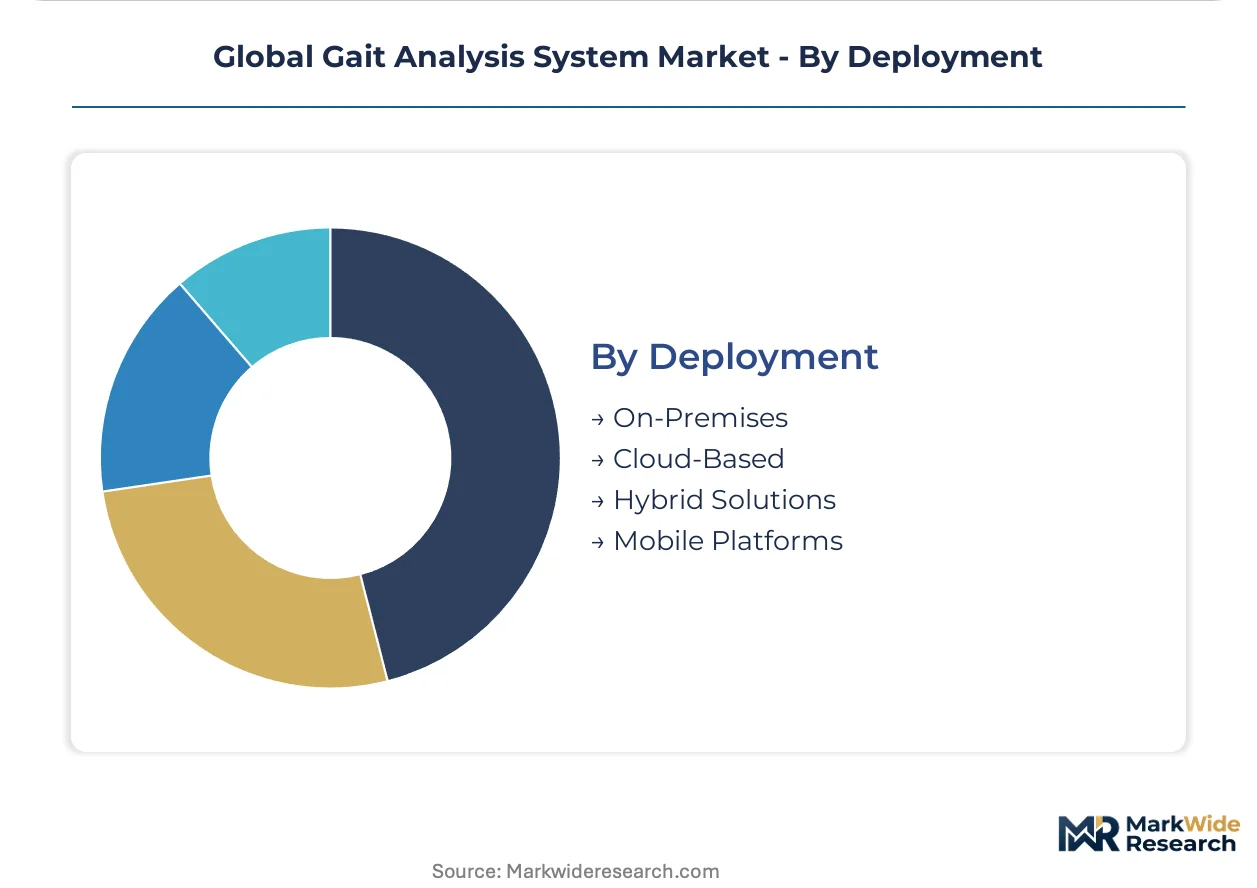
Deployment:
Delivery architecture selection reflects institutional IT maturity and data sovereignty requirements, with cloud migration accelerating among academic consortia but stalling in clinical settings.
- On-Premises:Local server installations preserve raw kinematic data control and minimize latency for real-time biofeedback applications. Veterans' hospitals in the United States mandate this architecture for security classification compliance.
- Cloud-Based:Centralized storage and algorithmic update streams support multi-site longitudinal studies. University laboratories in Denmark have pioneered this model for aging research spanning decades.
- Hybrid Solutions:Edge processing with cloud archival balances immediate analytics against long-term preservation requirements.
- Mobile Platforms:Smartphone-connected sensor arrays collapse cost barriers for point-of-care screening.
On-premises deployment retains dominant share. Cloud-based delivery is climbing the fastest among new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and veterans' hospitals concentrate procurement in the United States, while rehabilitation chains in Germany and university consortia in Nordic countries expand installed base.
United States
Federal healthcare facilities and academic medical centers drive equipment demand through dedicated motion analysis laboratories. FDA 510(k) clearance precedents accelerate hospital procurement cycles for diagnostic-grade platforms. Veterans' hospitals mandate on-premises deployments for security compliance, sustaining capital investment in optical configurations.
Germany
Rehabilitation centers expand ambulatory assessment programs using wearable sensor form factors. EU Medical Device Regulation conformity assessment requirements shape vendor selection criteria for clinical settings. Bavarian rehabilitation chains consolidate vendor relationships to standardize outcome measurement protocols across facilities.
Japan
Elite sports training facilities commission bespoke motion analysis installations for athlete biomechanics contracts. METI industrial standards influence equipment certification pathways for clinical deployment. Tokyo-area sports medicine clinics pilot markerless video capture systems for rapid athlete screening applications.
Sweden
University laboratories negotiate multi-site enterprise agreements spanning distributed camera networks. EU MDR technical documentation requirements prioritize established vendors for rehabilitation center procurement. Lund and Uppsala research consortia pioneer cloud-based delivery models for longitudinal aging studies.
Denmark
Academic consortia deploy cloud-connected platforms for decade-spanning data continuity in longitudinal research. Subscription-based software licensing displaces perpetual models among university laboratories. Copenhagen-area research institutes drive demand for algorithmic customization and data export flexibility.
Global Gait Analysis System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across laboratory installations and ambulatory deployments. The vendor base organizes around three strategic archetypes: optical system specialists sustaining premium positioning through camera-to-software integration, wearable sensor developers collapsing cost barriers for community-based monitoring, and pressure-mapping innovators extending assessment beyond laboratory confines. Competitive moves concentrate on strategic partnerships for algorithmic development and portfolio diversification into AI-integrated analytics platforms.
Within the optical system tier, Vicon Motion Systems and Qualisys exemplify premium positioning through proprietary hardware-software architectures. Tekscan occupies a position among pressure-mapping specialists, while Zebris Medical GmbH represents European-based rehabilitation-focused developers. These anchors illustrate how geographic origin and company structure correlate with archetype specialization across the competitive landscape.
| Leading Market Players |
|---|
| Vicon Motion Systems |
| Qualisys |
| BTS Bioengineering |
| Motion Analysis Corporation |
| Noraxon USA |
| Tekscan |
| Zebris Medical GmbH |
| Kistler Group |
| BioSensics |
| Others |
Supply & Pricing Matrix
Freiburg's precision optics cluster anchors high-end camera sensor production for laboratory-grade motion capture systems, with capacity allocation decisions at Zeiss and Basler factories directly shaping margin structures for downstream gait analysis vendors. German component shortages in 2023-2024 forced optical system manufacturers to extend delivery timelines, compressing pricing power for mid-tier configurations while premium installations maintained cost-plus indexation.
Pricing Analysis
Cost-plus contracts with quarterly semiconductor price indexation dominate procurement agreements for optical motion capture systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic platforms from research-grade configurations and wearable sensor kits. Pricing pressure stems from IMU commoditization flooding ambulatory monitoring segments with sub-$500 alternatives. Academic medical centers exhibit lowest price sensitivity due to grant-funded capital cycles, while independent physical therapy clinics face acute budget constraints.
Supply Chain Analysis
Upstream feedstock for optical systems draws from German precision glass, Japanese CMOS sensors, and Taiwanese semiconductor packaging. Inertial measurement units rest on MEMS foundry capacity concentrated in Taiwan and South Korea. Pressure-sensitive polymers and conductive inks for smart insoles source from specialty chemical producers in Germany and the United States. Single-source vulnerability around Sony's image sensor allocation creates bottleneck risk for multi-camera laboratory installations. Distribution runs through authorized dealer networks for clinical sales and direct enterprise contracts for research consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gait analysis market sits at a platform-economics inflection where proprietary data format lock-in is collapsing under pressure from HL7 FHIR interoperability mandates and open-source biomechanics toolkits. Vendors must choose between defending integrated hardware-software stacks or unbundling into analytics platforms agnostic to sensor origin.
For Market Incumbents: Pre-empt markerless video capture disruption by acquiring computer vision startups before diagnostic-grade validation thresholds are crossed. Incumbents should deepen backward integration into MEMS sensor design to escape foundry allocation volatility threatening wearable device margins. FDA 510(k) clearance for AI-derived gait metrics represents the priority defensive moat against software-only entrants. For New Entrants and Emerging Players: Scandinavian rehabilitation chains present the most penetrable white-space for cloud-native platforms with EU MDR technical documentation already assembled. Japan's aging population and METI digital health subsidies create a secondary beachhead for fall-risk assessment tools. A direct-to-clinic subscription model bypassing capital equipment procurement committees unlocks faster traction than competing for hospital RFP cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical specialists with FDA-cleared algorithms over hardware-agnostic software layers vulnerable to sensor commoditization. Acquisition targets should demonstrate recurring revenue from longitudinal research contracts rather than one-time laboratory installations. The signal to watch is CMS reimbursement code finalization for remote therapeutic monitoring, which would validate clinical economics for cloud-connected platforms. Cross-checking against hospital capital expenditure surveys and veterans' affairs procurement databases is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Integrated Software Platform Development | FDA 510(k) clearance for real-time kinematic algorithms differentiates diagnostic-grade vendors from research-only competitors. |
| EU MDR Technical Documentation Investment | Notified-body conformity assessment capability unlocks rehabilitation center procurement across Germany, Sweden, and Denmark. |
| Cloud Data Architecture Deployment | Subscription licensing with multi-site enterprise agreements captures longitudinal aging study budgets in academic consortia. |
| Wearable Sensor Miniaturization Program | Pressure-mapping insole advances extend gait assessment from laboratory confinement into community-based ambulatory monitoring. |
| Strategic Partnership with Veterans' Health Administration | Federal healthcare facility relationships generate sustained equipment demand through dedicated motion analysis laboratory buildouts. |
Research Methodology
A standing panel of rehabilitation center directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers provided ongoing calibration against procurement database trends. Primary interviews with optical system integrators and wearable sensor developers were cross-referenced against FDA 510(k) filings, EU MDR notified-body registration data, and CMS reimbursement code proposals. Secondary validation drew from hospital capital expenditure surveys, academic research grant disclosures, and veterans' affairs procurement records. Bottom-up installation tracking across university laboratories and clinical facilities was triangulated with top-down vendor revenue segmentation.
Scenario-bracketing around FDA clearance timelines, EU MDR conformity assessment capacity, and remote monitoring reimbursement decisions framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, application focus, end-user category, and deployment architecture. CAGRs were derived from fitted growth curves against historical procurement cycles and adjusted for regulatory pathway probability-weighting. Forecast inputs incorporated sensor cost decline trajectories and cloud infrastructure scaling economics specific to longitudinal biomechanics research.
Practitioners should monitor FDA guidance document revisions, EU MDR notified-body capacity announcements, and CMS remote therapeutic monitoring code finalization for early signals requiring forecast adjustment. Cross-checking against external benchmarks including hospital IT budget surveys and federal healthcare facility capital plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
France Ultrasound Devices Market
Medical Devices
Global Portable Ventilators Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Pulse Lavage Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Organ Preservation Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Europe Manual Resuscitators Market
Medical Devices
Automated CPR Devices Market