
 Smart Home Security Market | 2026-2036
Smart Home Security Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Security Market Intelligence
The move away from custom-designed ASIC hardware towards standardized System-on-Chip (SoC) platforms is decoupling product development costs from manufacturing scale. This shift enables faster innovation cycles for new entrants. SimpliSafe leverages a direct-to-consumer model with modular hardware. In contrast, ADT sustains its market share through professionally installed systems and long-term monitoring contracts, while Ring Alarm dominates the DIY video doorbell segment.
Smart home security comprises a network of internet-connected devices designed for remote monitoring and property protection. These systems utilize protocols like Wi-Fi and Z-Wave, often with AES encryption, to transmit data securely from sensors to a central hub or cloud service. While Video Doorbells and Smart Cameras command the largest share of the product market, the fastest growth is in integrated solutions. The core Intrusion Detection use case is being augmented by advanced capabilities like AI-powered Remote Surveillance and automated Emergency Response.
Market access is governed by a matrix of international standards. In the United States, the FCC regulates wireless device emissions, while the EU’s GDPR imposes strict data privacy rules on consumer information. Concurrently, products sold in China must adhere to specific GB standards for electronics. Future competitive advantage will hinge on navigating this complex regulatory environment while delivering innovative, secure user experiences.
Market Dynamics
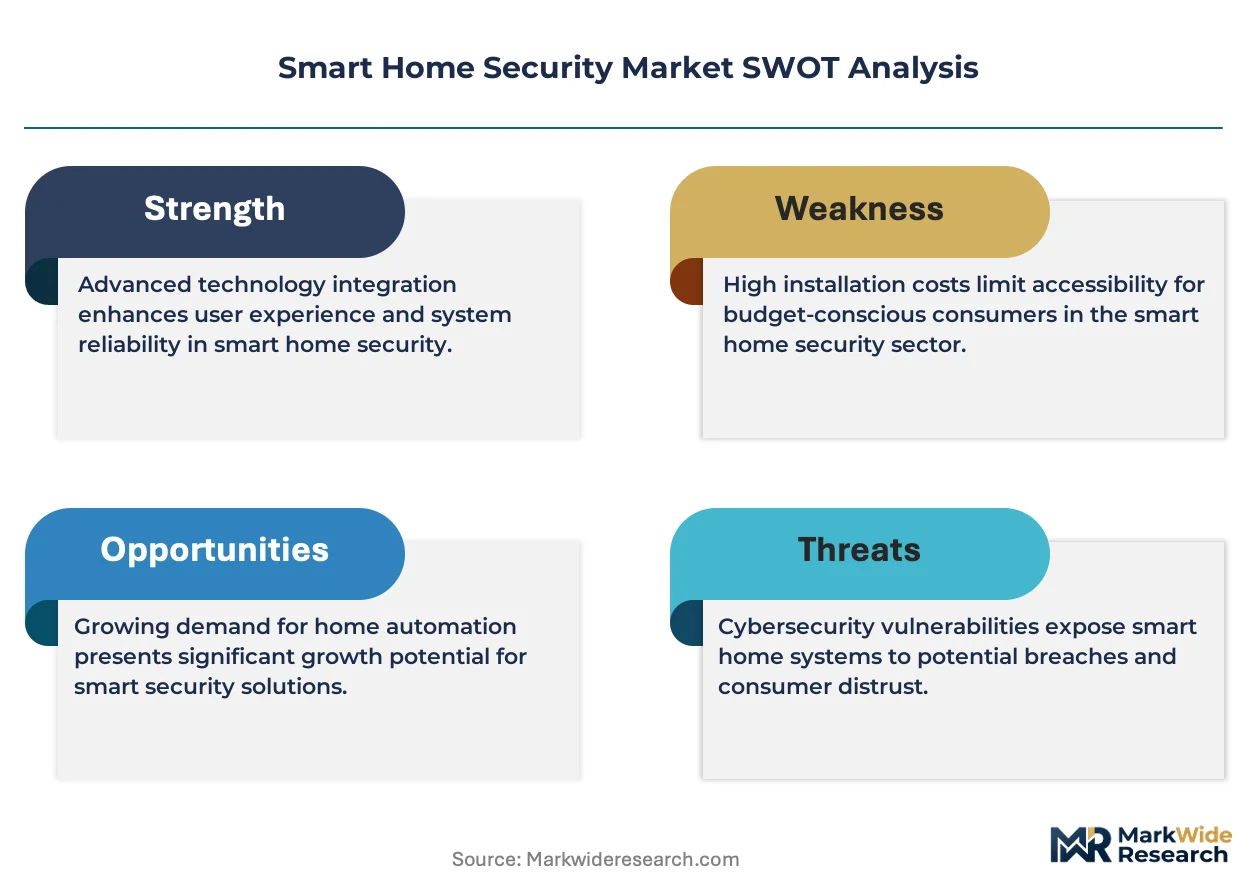
The transition from custom ASIC hardware to standardized System-on-Chip (SoC) platforms is the central force shaping market dynamics. This shift reduces entry barriers and, when combined with expanding 5G network availability, accelerates innovation cycles for new entrants.
Growth Catalysts
- 5G Network Expansion:Proliferation of 5G enhances reliability for real-time video streaming, making advanced remote surveillance more viable for residential and commercial properties.
- Rental Property Management:Large-scale rental firms adopt smart security to manage access control across portfolios, creating concentrated B2B demand.
- Data Privacy Regulation:The EU's GDPR drives demand for systems with on-device processing and robust encryption, minimizing cloud data exposure.
Market Restraints
- Protocol Fragmentation:The coexistence of multiple standards like Wi-Fi and Z-Wave creates interoperability challenges, complicating system integration for consumers.
- Consumer Data Privacy:Apprehension over potential data breaches and unauthorized surveillance by cloud service providers remains a significant barrier to adoption.
- Regulatory Compliance Burden:Navigating divergent regulations, including US FCC rules, EU's GDPR, and China's GB standards, increases development costs and slows market entry.
Strategic Opportunities
- Integrated Service Platforms:Unified platforms combining intrusion detection with automated emergency response create new recurring revenue opportunities beyond hardware sales.
- AI-Driven Video Analytics:Implementing AI to differentiate threats from benign motion reduces false alarms, offering a significant user experience improvement.
- Home Insurance Partnerships:Collaborations with insurers to offer premium discounts for homes with certified security systems can accelerate mainstream consumer adoption.
Industry Challenges
- Integration with Legacy Systems:Integrating modern IP-based devices with existing analog security infrastructure in retrofits presents significant technical and cost hurdles for installers and consumers.
- Cybersecurity Talent Scarcity:A shortage of skilled cybersecurity professionals capable of securing vast IoT networks against sophisticated threats constrains secure product development and long-term support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Security Market |
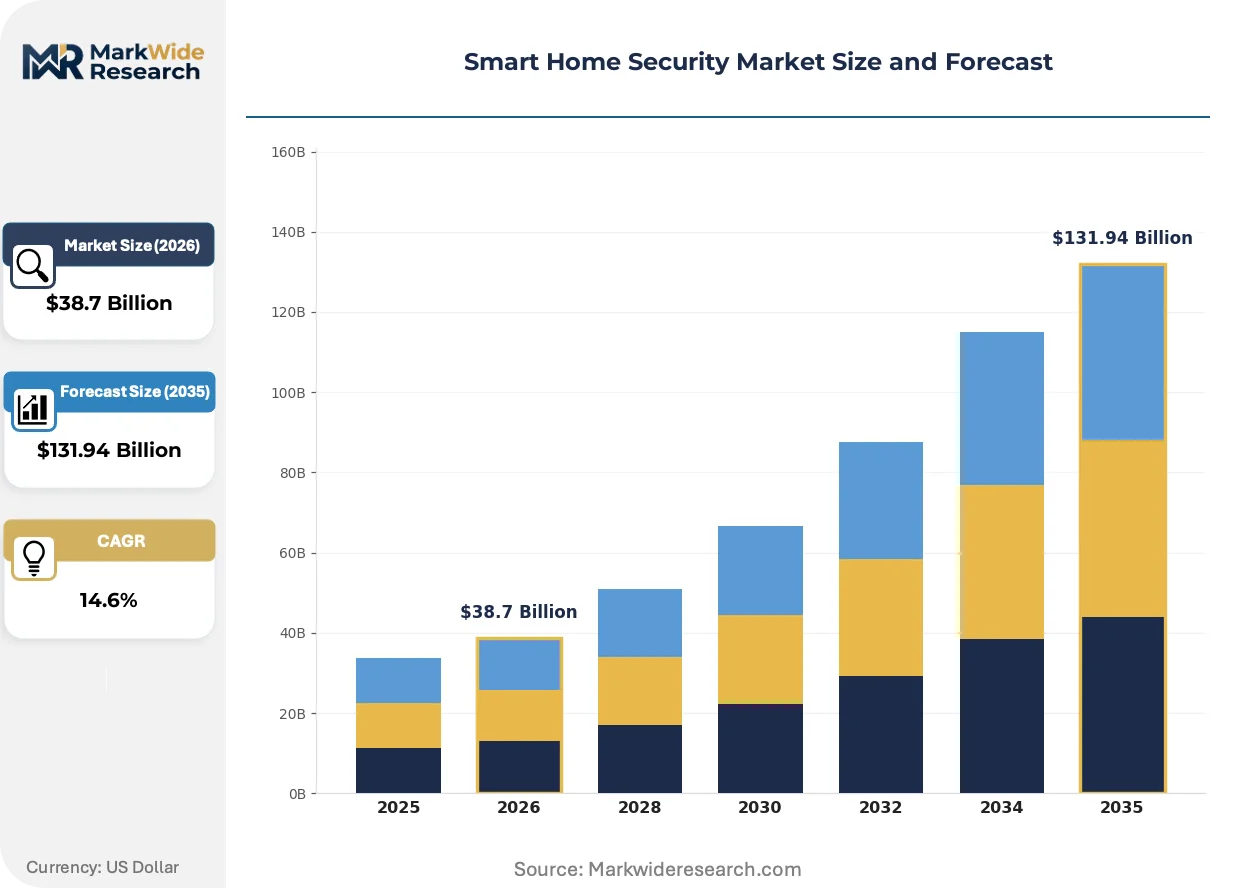
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $131.94 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Cameras, Motion Sensors, Door & Window Sensors, Alarm Systems, Video Doorbells, Smart Locks Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth, Infrared, Cellular Use Case: Intrusion Detection, Fire & Smoke Alert, Environmental Monitoring, Remote Surveillance, Access Control, Emergency Response End User: Homeowners, Property Managers, Rental Property Firms, Small Offices, Vacation Homes |
| Companies Covered | Cove Security, Frontpoint Home Security, ADT, Ring Alarm, Brinks Home Security, SimpliSafe, Alder Security, CPI Security Systems, Vivint Smart Home, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Security Market Strategic Shifts & Innovations
The market is actively shifting from standalone hardware to integrated, intelligent ecosystems. This evolution is driven by advancements in on-device processing and a growing consumer expectation for proactive, rather than reactive, security solutions.
On-device artificial intelligence enables security cameras and sensors to analyze data locally, without sending it to the cloud. Privacy-conscious consumers and users demanding faster event detection are driving its adoption. This edge computing model is overtaking traditional cloud-dependent architectures, reducing network latency, lowering data privacy risks, and decreasing cloud server costs for manufacturers.
The European Union’s forthcoming AI Act establishes a risk-based framework for artificial intelligence systems, directly impacting security products. This legislation imposes strict compliance and transparency requirements on features like AI-powered surveillance, classifying many as high-risk. Consequently, manufacturers targeting the EU are re-architecting systems to prioritize data governance and user control to mitigate regulatory penalties.
A notable demand-side shift sees consumers moving from one-time hardware purchases to subscription-based models for professional monitoring and cloud video storage. This service-centric approach disrupts the traditional retail channel, favoring direct-to-consumer brands that can build long-term customer relationships. This trend is most pronounced in the United States and Western Europe, where recurring revenue models are well-established in consumer technology.
Smart Home Security Market Segmentation
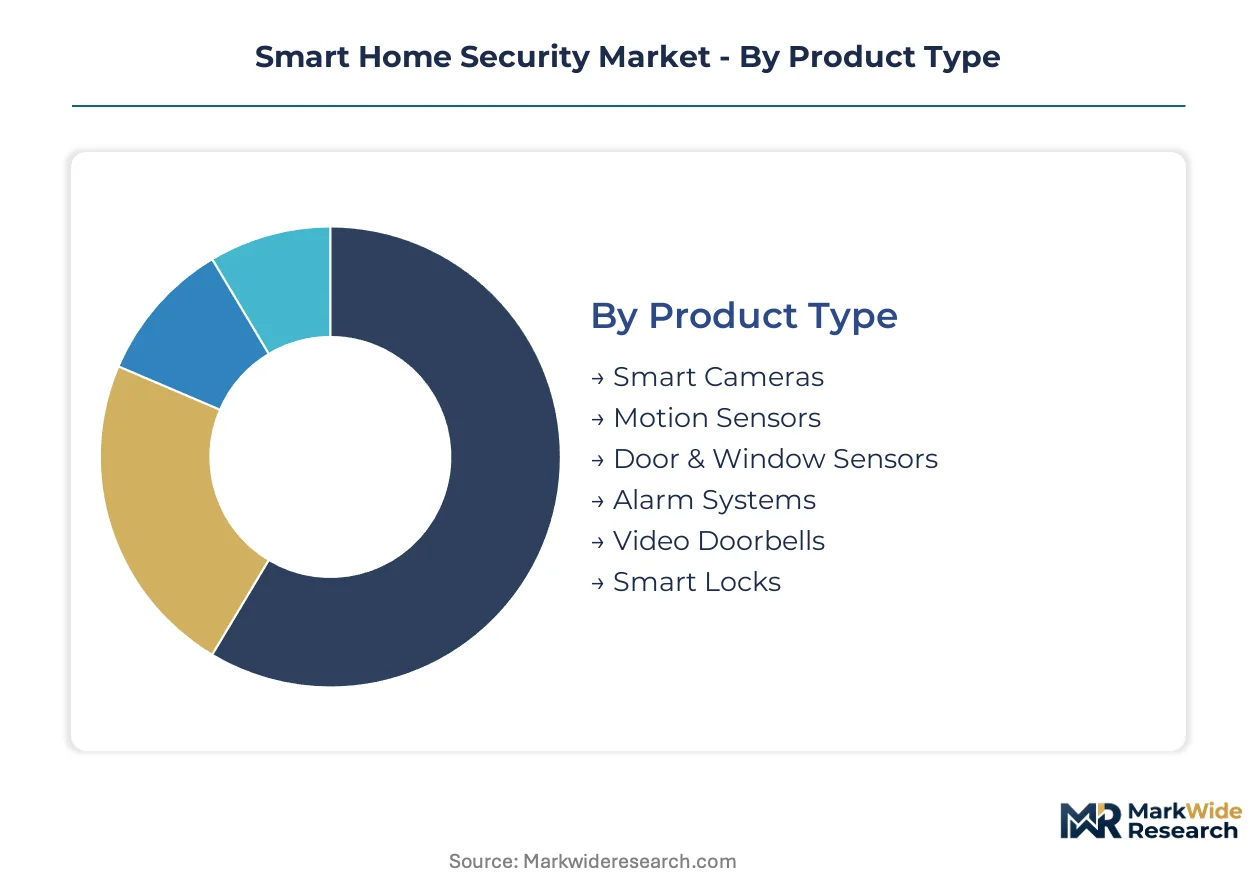
The smart home security market segments across diverse product types, communication technologies, core use cases, and distinct end-user groups. Understanding these divisions reveals specific demand patterns and areas of technological concentration. Each segment addresses unique security needs and operational requirements for property protection.
Product Type:
Supply concentration in product manufacturing often dictates market availability and consumer choice within the smart home security sector.
- Video Doorbells:These devices integrate a camera, microphone, and speaker for remote communication and package monitoring. Demand concentrates in residential homes seeking both convenience and a primary deterrent for porch piracy.
- Smart Cameras:Internet-connected cameras provide real-time video surveillance, often with motion detection and cloud storage. Homeowners in urban areas drive demand, seeking advanced remote monitoring enhanced by AI-powered analytics.
- Alarm Systems:Centralized hubs connect sensors, triggering alerts or professional monitoring services upon event detection.
- Smart Locks:Electronic locks enable keyless entry and remote access control, integrating with smart home ecosystems.
- Motion Sensors:Devices detecting movement within a defined area trigger alerts or activate security components.
- Door & Window Sensors:Magnetic contacts detect when a door or window opens, signaling potential intrusions.
Video Doorbells absorb the bulk of installed capacity; Smart Cameras are expanding most quickly.
Technology:
Functional differentiation across communication protocols directly impacts device interoperability and overall system performance for various security applications.
- Wi-Fi:This ubiquitous wireless standard provides high bandwidth for streaming video and connecting devices directly to home networks. Consumers seeking easy setup and integration with existing internet infrastructure drive Wi-Fi adoption.
- Z-Wave:A low-power wireless mesh network protocol designed for smart home devices, offering reliable short-distance communication. Property managers leverage Z-Wave for robust sensor networks across units, valuing its stability and energy efficiency.
- Zigbee:Low-power mesh network protocol, used for sensors and smart lighting, known for energy efficiency.
- Bluetooth:Short-range wireless technology used for direct device-to-device connections or local control.
- Cellular:Provides a backup communication channel for security systems, ensuring alerts during internet outages.
- Infrared:Utilized in passive infrared (PIR) motion sensors to detect body heat, offering reliable detection.
Wi-Fi technologies command the largest share of system deployments; Cellular connectivity shows the steepest expansion trajectory.
Use Case:
Customer demand patterns reveal distinct priorities for security solutions, from proactive monitoring to reactive emergency response capabilities.
- Intrusion Detection:This core use case identifies unauthorized entry into a protected space using sensors and alarms. Homeowners prioritize intrusion detection for basic property protection, driving consistent demand.
- Remote Surveillance:Enables users to monitor their property visually from anywhere via internet-connected cameras and mobile applications. Rental Property Firms increasingly adopt remote surveillance for managing common areas and tenant safety.
- Fire & Smoke Alert:Smart smoke and carbon monoxide detectors provide immediate alerts to users and emergency services.
- Access Control:Managing entry and exit to a property through smart locks or biometric systems.
- Emergency Response:Automated dispatch of emergency services upon alarm triggers or user activation.
- Environmental Monitoring:Detecting environmental hazards like water leaks or extreme temperatures within the property.
Intrusion Detection remains the foundational use case; Emergency Response capabilities are gaining share fastest.
End User:
The scale and nature of demand vary significantly across different end-user segments, influencing product features and service models.
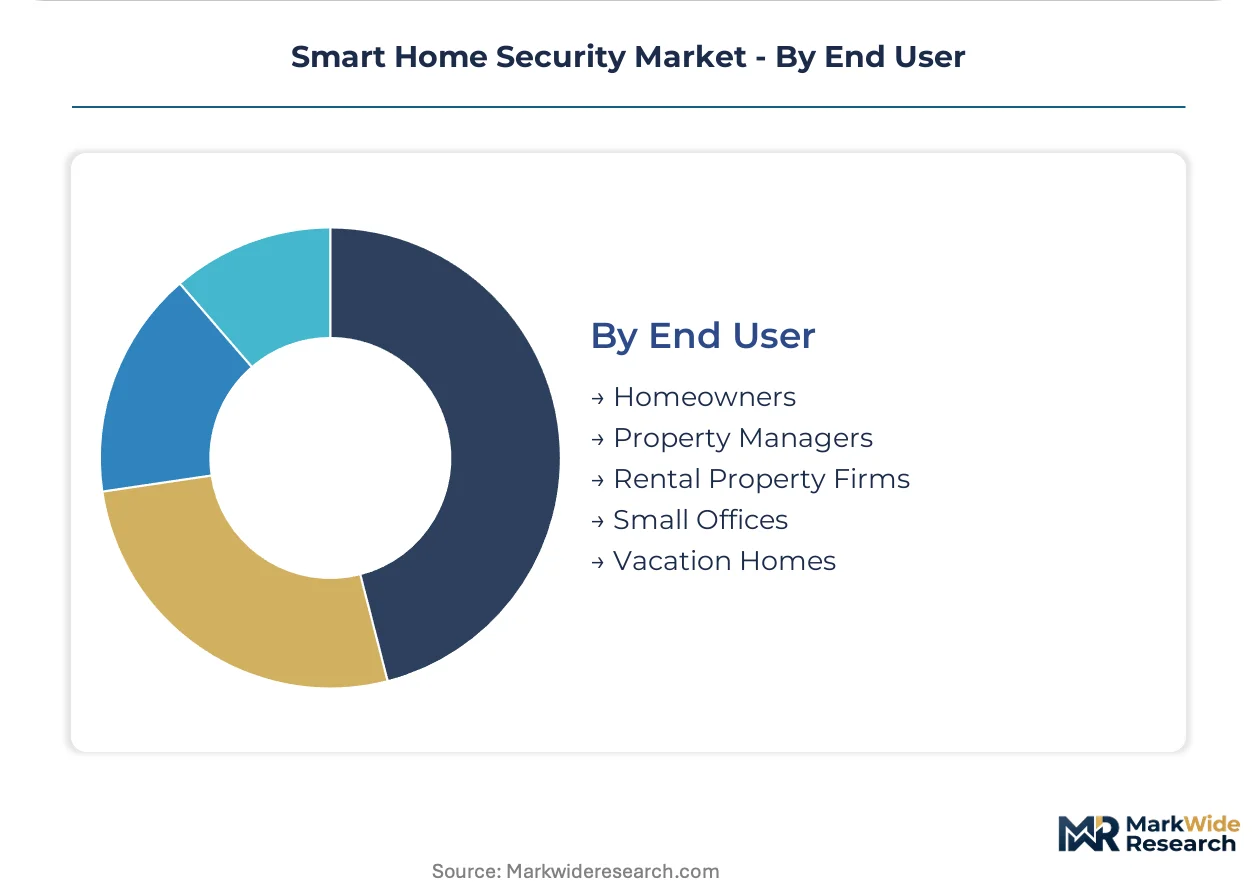
- Homeowners:Individual residents seeking security solutions for their primary residences, often prioritizing ease of installation and user-friendliness. German homeowners show high demand for advanced protection for high-value assets.
- Rental Property Firms:Companies managing multiple residential units, requiring scalable solutions for access control and property monitoring. These firms drive concentrated B2B demand for systems manageable across large property portfolios.
- Small Offices:Businesses with limited premises require cost-effective security for asset protection and employee safety.
- Vacation Homes:Properties used periodically need remote monitoring and access management due to extended vacancy.
Homeowners constitute the largest end-user segment; Rental Property Firms exhibit the most rapid demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for smart home security solutions concentrates in developed economies, driven by consumer wealth and property value. Homeowners prioritize advanced protection for their assets, alongside convenience and remote monitoring. Rental property firms also contribute significantly, seeking scalable access management across their portfolios.
Germany
German homeowners exhibit strong demand for smart home security, particularly for advanced systems protecting high-value assets. The EU’s GDPR significantly influences product design, driving demand for solutions with robust data privacy. Technology hubs like Munich are developing AI-powered surveillance systems compliant with European regulations.
United States
The United States market shows robust demand for smart home security, characterized by a preference for subscription-based monitoring and DIY solutions. FCC regulations govern wireless device emissions, ensuring product compliance. Silicon Valley clusters continue to develop advanced AI-driven video analytics and integrated security platforms.
China
China's smart home security sector is expanding, driven by a vast consumer market and rapid urbanization. Products sold in the country must adhere to specific GB standards for electronics, ensuring quality. Shenzhen, a major electronics manufacturing hub, actively produces smart cameras and video doorbells for domestic consumption.
United Kingdom
Homeowners in the United Kingdom increasingly adopt smart security systems, favoring subscription models for professional monitoring and cloud storage. Data privacy regulations, similar to GDPR, shape product development, emphasizing user control. London's vibrant tech scene fosters innovation in integrated service platforms and AI-driven security solutions.
India
India's smart home security market is experiencing significant expansion, fueled by a growing middle class and rising concerns over property protection. BIS standards for electronic goods ensure quality and safety, influencing product design. Bengaluru, a prominent IT hub, sees rising development of affordable and connected security devices for local needs.
Smart Home Security Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure for smart home security. The sector comprises established security providers offering professional installation, technology giants leveraging existing ecosystems, and nimble direct-to-consumer startups disrupting traditional channels. These archetypes compete through strategic partnerships to expand service offerings and portfolio diversification into integrated solutions, aiming for comprehensive user experiences.
Among providers offering professionally installed systems and long-term monitoring contracts, ADT exemplifies a market incumbent sustaining its share through established service networks and comprehensive monitoring solutions. SimpliSafe represents the direct-to-consumer model, focusing on modular hardware and accessible installation, appealing to homeowners seeking flexible security options. Ring Alarm, meanwhile, occupies a dominant position in the DIY video doorbell segment, leveraging its integration within a broader smart home ecosystem and strong brand recognition.
| Leading Market Players |
|---|
| Cove Security |
| Frontpoint Home Security |
| ADT |
| Ring Alarm |
| Brinks Home Security |
| SimpliSafe |
| Alder Security |
| CPI Security Systems |
| Vivint Smart Home |
| Others |
Cost & Logistics Intelligence
Semiconductor prices, particularly for System-on-Chip (SoC) platforms, cascade through the smart home security supply chain, influencing hardware costs and ultimately impacting end-user pricing tiers. This dynamic links component availability and manufacturing efficiency directly to market competitiveness and consumer affordability.
Pricing Analysis
Volume sales in the smart home security market compete for market share, while premium offerings prioritize margin through advanced features. The market operates on a hybrid subscription and transactional model, combining one-time hardware purchases with recurring service fees. Price differentiation stems from brand premium and comprehensive after-sales service, including professional monitoring. Pricing softness in the DIY segment reflects intense competition and the commoditization of basic hardware. Homeowners seeking advanced protection show lower price sensitivity for integrated, secure solutions.
Supply Chain Analysis
Regional distribution centers facilitate the movement of smart home security devices, employing hub-and-spoke patterns for efficient last-mile delivery. Geographic supply concentration centers on China for component manufacturing, particularly in hubs like Shenzhen, and the United States for advanced design and software integration. Key raw material dependencies include SoCs, various sensors, and communication modules. Single-source vulnerability for specialized SoC components represents a significant supply chain risk. Distribution runs through both direct-to-consumer channels and established professional installation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart home security market is poised for consolidation, with the complex regulatory compliance burden from the EU AI Act and GDPR forcing weaker players out.
For Market Incumbents:
Extend existing service networks to offer integrated solutions encompassing automated emergency response and AI-driven video analytics. This strategy defends market share against new entrants leveraging SoC platforms and direct-to-consumer models. Invest in securing critical cybersecurity talent for cloud infrastructure and on-device processing. Prioritize certification investments for compliance with evolving data privacy regulations like the EU's GDPR.
For New Entrants and Emerging Players:
The EU AI Act in Europe opens a window for privacy-by-design security solutions utilizing on-device processing. Target Rental Property Firms with scalable B2B offerings for access control and remote surveillance. Focus on developing protocol-agnostic integration platforms to overcome interoperability challenges. A go-to-market angle emphasizing subscription-based models with robust data governance will attract privacy-conscious consumers.
For Investors and Strategic Acquirers:
Distressed-cycle entries favor vertically integrated specialists in Europe, where regulatory compliance costs are rising. The long-term viability centers on recurring revenue models from integrated ecosystems and AI-powered services. Identify acquisition targets among niche AI analytics firms or companies specializing in secure communication protocols. Consolidation among smaller hardware manufacturers serves as an inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI-Driven Video Analytics | Reduces false alarms and enhances threat detection for homeowners, improving user experience. |
| Expand Subscription-Based Monitoring | Generates recurring revenue streams beyond hardware sales, fostering long-term customer relationships. |
| Develop GDPR-Compliant Solutions | Mitigates regulatory penalties and builds trust with privacy-conscious consumers in Europe. |
| Partner with Home Insurance Providers | Accelerates mainstream consumer adoption through premium discounts for certified security systems. |
| Invest in Protocol-Agnostic Platforms | Addresses interoperability challenges, simplifying system integration for diverse end-users. |
Research Approach
Document review covered publicly available FCC filings, EU GDPR impact assessments, Chinese GB standards publications, and industry association reports, complemented by interviews. Primary research involved discussions with security system integrators, product development leads, rental property managers, and regulatory compliance officers. This approach ensured a balanced perspective, triangulating insights from both bottom-up market observations and top-down strategic analyses.
The quantitative model produced granular market volume and value projections across the analysis window. Our analytical framework integrated segmentation dimensions including product type, technology, use case, end-user, and regional regulatory compliance tiers. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Industry-specific forecast inputs included 5G network rollout data and smart home penetration rates.
Caveats apply where geopolitical events impacting supply chains or unforeseen regulatory changes could materially shift the outlook. Forecasts reflect assumptions regarding technological adoption curves and consumer spending patterns. Major cybersecurity breach incidents or significant economic downturns represent specific risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Airport Security Market
Security and Surveillance
Seaport Security Management Market
Security and Surveillance
Proactive Security Market
Security and Surveillance
Security and Surveillance Equipment Market
Security and Surveillance
Shock Sensor Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Underwater Security (Systems and Services) Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
Global Acoustic Hailing Devices Market
Security and Surveillance
Middle East and Africa Cargo Inspection Market
Security and Surveillance
Consumer Security Market
Security and Surveillance
Global Police and Law Enforcement Equipment Market
Security and Surveillance
Surveillance Radars Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
Anti-Piracy Protection Market