
 Anti-Piracy Protection Market | 2026-2036
Anti-Piracy Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Piracy Protection Market Analysis
The EU Digital Services Act is pivoting content distribution platforms toward proactive piracy detection obligations. Red Points leverages automated brand protection scanning across e-commerce marketplaces. Irdeto anchors premium video security through conditional access and watermarking patents. Synamedia competes in credential sharing detection and streaming piracy disruption.
Anti-piracy protection encompasses technologies and services that authenticate, encrypt, monitor, and enforce intellectual property rights across digital distribution channels, employing forensic watermarking, cryptographic scrambling, and real-time traffic analysis to identify unauthorized redistribution. The primary purpose is to preserve revenue streams for content owners by degrading the quality or accessibility of pirated copies while maintaining legitimate viewer experience. Monitoring Services capture early-stage leakage through automated web crawling and peer-to-peer network surveillance, whereas Watermarking commands premium positioning due to its evidentiary value in litigation and its irreversible embedding into content frames. Cloud-based deployment is gaining traction among streaming services seeking elastic capacity during release windows, while On-premises configurations persist among major studios with legacy infrastructure and data sovereignty requirements.
The Federal Communications Commission in the United States enforces signal protection standards for broadcast and cable distribution, while the European Union's Digital Services Act imposes content monitoring duties on platform intermediaries. China's National Radio and Television Administration mandates integrated encryption for all licensed streaming operations, shaping product certification requirements for vendors entering that market. India's Telecom Regulatory Authority has issued consultation papers on digital piracy remediation that signal forthcoming compliance expansion. Stakeholders must monitor regulatory divergence across jurisdictions to align product architectures with varying enforcement intensities and liability frameworks.
Market Dynamics
The EU Digital Services Act is forcing streaming platforms toward proactive piracy detection obligations, compressing deployment timelines for forensic watermarking and real-time traffic analysis systems.
Growth Catalysts
- Conditional Access Mandates:China's National Radio and Television Administration requires integrated encryption for all licensed streaming operations, expanding vendor certification pipelines.
- Live Sports Protection:Premium broadcasters deploy forensic watermarking to trace leakage sources within minutes of unauthorized redistribution.
- Credential Sharing Crackdowns:Streaming services in the United States, Germany, and South Korea invest in behavioral analytics to detect account misuse at scale.
Market Restraints
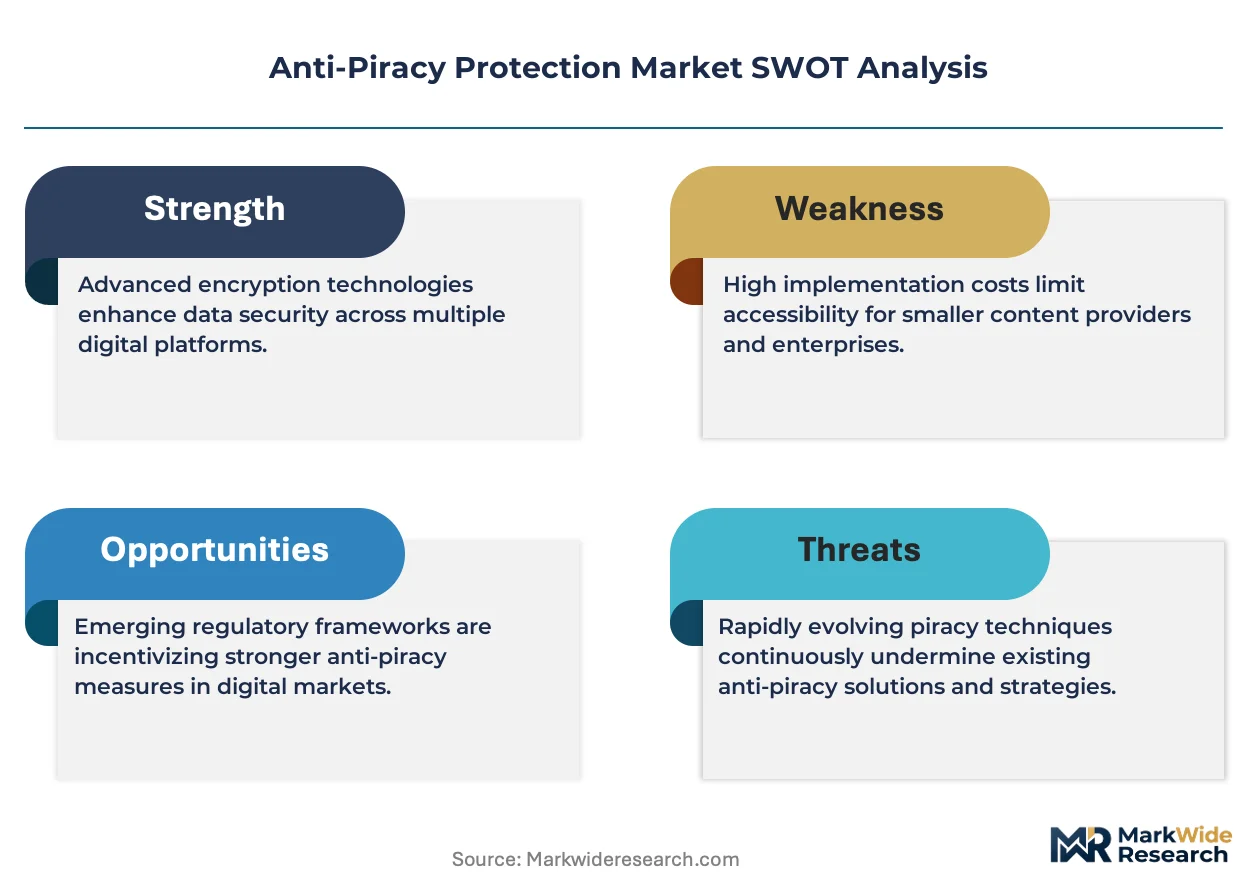
- Implementation Cost Barriers:Cloud-based forensic watermarking requires sustained capex commitments that mid-tier content distributors struggle to absorb.
- Encryption Standard Fragmentation:Divergent national requirements across China, the European Union, and India force vendors to maintain multiple product architectures.
- Open-Source Decryption Tools:Widely distributed circumvention utilities degrade the effectiveness of cryptographic scrambling in consumer-facing applications.
Strategic Opportunities
- India's Regulatory Expansion:The Telecom Regulatory Authority's consultation papers on digital piracy remediation signal forthcoming compliance mandates for domestic streaming platforms.
- AI-Generated Content Provenance:Synthetic media detection creates demand for authentication layers that verify content origin and distribution chain integrity.
- Edge Computing Integration:Watermark embedding at content delivery network nodes reduces latency while enabling real-time piracy disruption.
Industry Challenges
- Forensic Analyst Talent Scarcity:Specialized expertise in steganography and signal processing commands premium compensation, constraining vendor scaling.
- Legacy Infrastructure Compatibility:Studios with on-premises conditional access systems face integration friction when adopting cloud-native monitoring services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Piracy Protection Market |
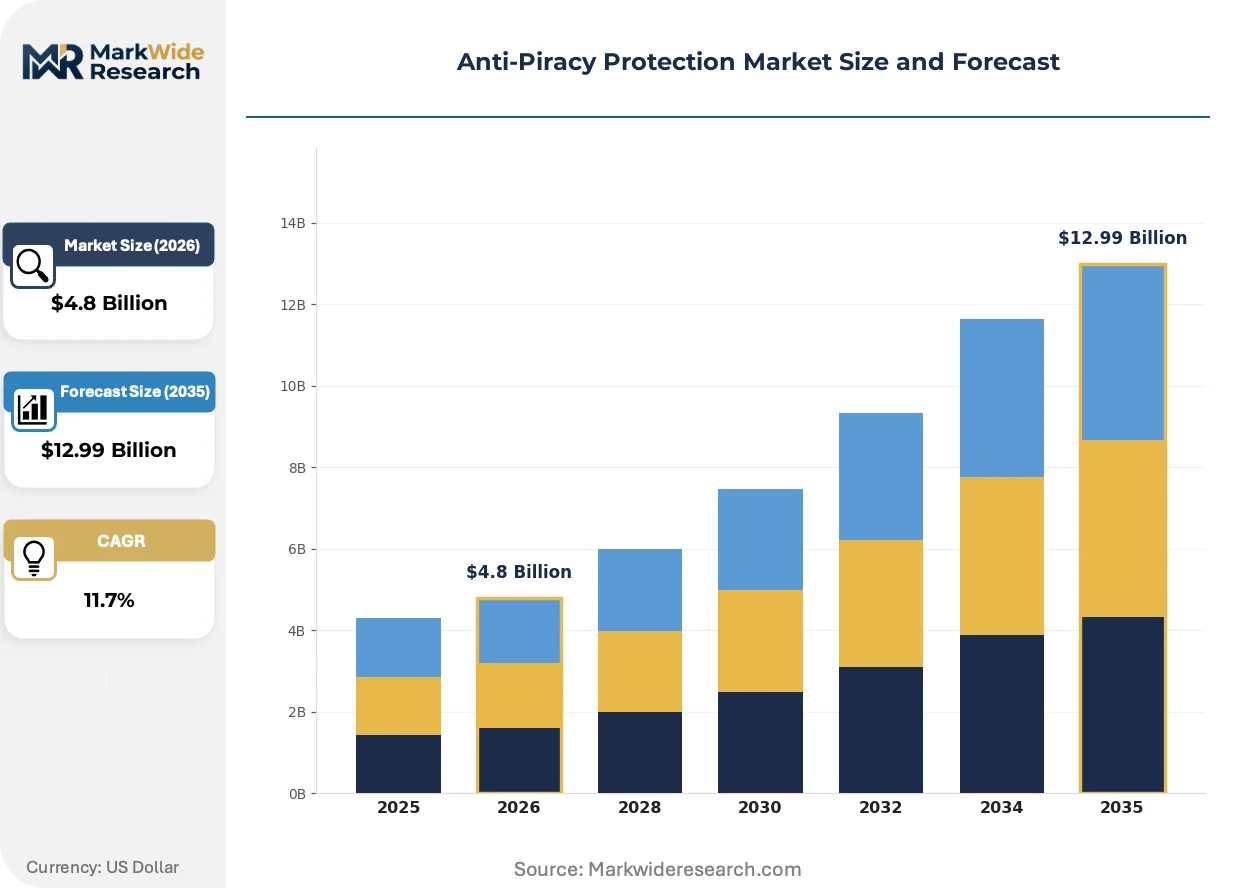
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Digital Rights Management, Watermarking, Monitoring Services, Cybersecurity Solutions Deployment Model: Cloud-based, On-premises, Hybrid, Dedicated Server Industry Vertical: Media & Entertainment, Software, E-commerce, Telecommunications End User: Content Owners, Distributors, Publishers, Streaming Services |
| Companies Covered | Red Points, Irdeto, MarqVision, Verimatrix, Synamedia, MUSO, NAGRA NexGuard, Harvel, PACE Anti-Piracy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Piracy Protection Market Emerging Trajectories
Machine learning is automating piracy detection workflows, compressing response times from hours to seconds while reshaping vendor competitive positioning around algorithmic accuracy.
Forensic watermarking is automating source identification through frame-level embedding that survives compression, transcoding, and camcording attacks. Major studios and sports leagues deploy these systems across theatrical release windows and live event broadcasts. The technology is automating evidence generation for litigation, reducing reliance on manual infringement documentation.
The EU AI Act imposes transparency requirements on automated content moderation systems, including piracy detection algorithms deployed by platform intermediaries. Vendors must document training data provenance and decision audit trails to maintain compliance. Streaming services operating across European Union member states are restructuring procurement specifications to incorporate these accountability frameworks.
Subscription bundling is compressing buyer decision cycles as streaming platforms consolidate anti-piracy spending into enterprise-wide security contracts. Independent watermarking specialists face margin pressure from integrated platform vendors offering bundled detection and disruption services. This consolidation is most visible in the United States, where major studio procurement teams prioritize single-vendor accountability over best-of-breed component sourcing.
Anti-Piracy Protection Market Segmentation
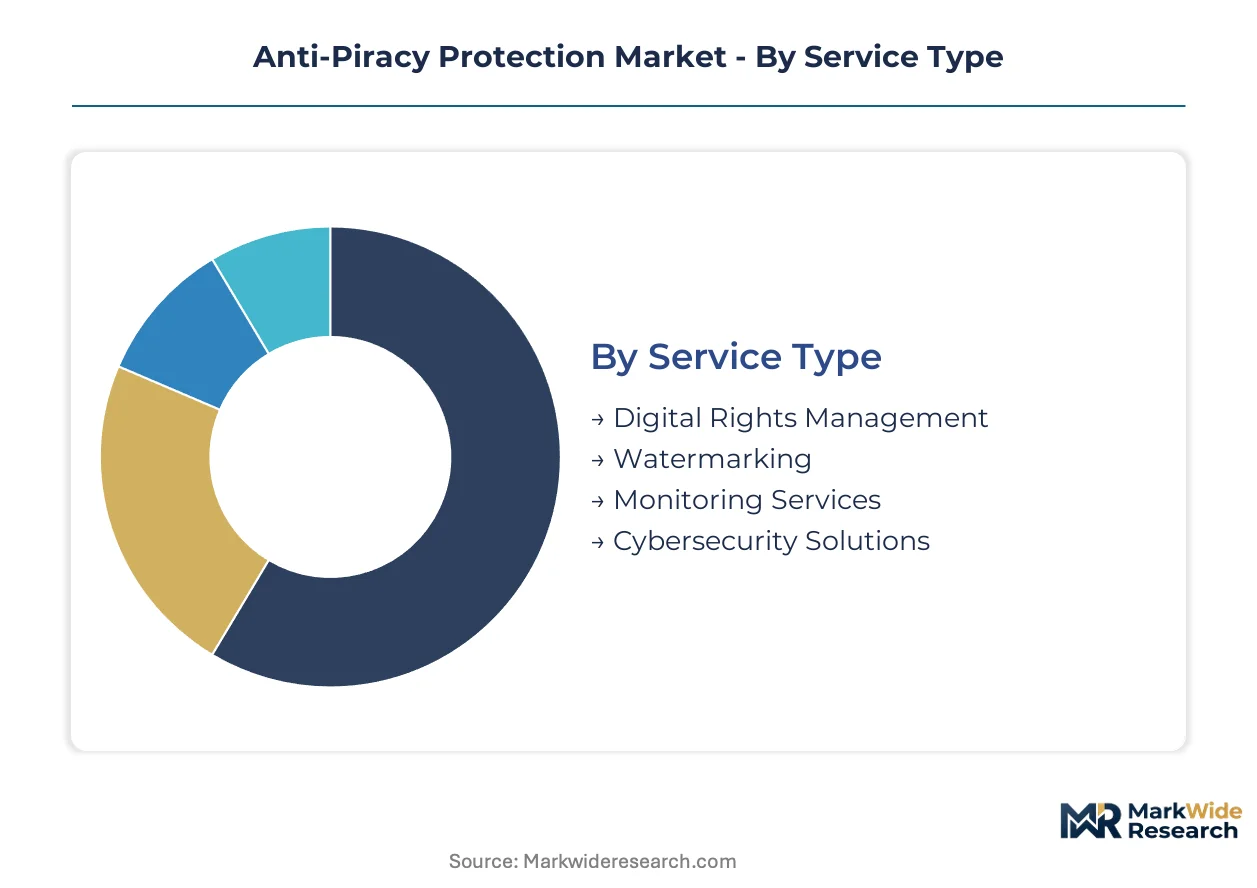
Anti-piracy protection vendors configure product architectures around distinct operational requirements. Deployment constraints, content sensitivity levels, and regulatory compliance obligations shape procurement decisions across buyer segments.
Service Type:
Standardized encryption modules compete with bespoke forensic systems across this spectrum, with customization intensity rising toward litigation-ready evidence generation.
- Digital Rights Management:Cryptographic access control systems enforce playback authorization through license servers and secure key exchange protocols. Hollywood studios and major streaming services in the United States mandate DRM integration for theatrical release windows.
- Watermarking:Frame-embedded forensic identifiers survive transcoding, compression, and camcording attacks to trace leakage sources. Sports leagues and premium broadcasters in Germany deploy these systems for live event protection where rapid source identification compresses response windows.
- Monitoring Services:Automated web crawling and peer-to-peer network surveillance detect unauthorized distribution channels.
- Cybersecurity Solutions:Endpoint protection and threat intelligence platforms secure content production environments.
Most installed capacity flows through Digital Rights Management. Expansion is steepest in Watermarking.
Deployment Model:
Cost tier stratification dominates this category, with capital intensity and operational control trading off across infrastructure choices.
- Cloud-based:Elastic compute resources scale watermark embedding and traffic analysis capacity during peak release windows. Streaming services in South Korea favor this model for rapid deployment without data center investment.
- On-premises:Dedicated hardware maintains cryptographic key sovereignty and audit trail control. Major studios with legacy conditional access infrastructure in the United States retain this configuration for theatrical distribution security.
- Hybrid:Split architectures process sensitive operations locally while leveraging cloud analytics.
- Dedicated Server:Single-tenant hardware meets data residency requirements in regulated jurisdictions.
Cloud-based deployment captures the majority of new installations. Hybrid configurations are gaining share fastest among mid-tier content distributors.
Industry Vertical:
Application-specific threat profiles drive divergent protection intensity across verticals, with live content commanding premium security layers.
- Media & Entertainment:Motion picture studios, broadcast networks, and music labels deploy multi-layer protection across production, distribution, and exhibition stages. Content owners in the United States and South Korea concentrate spending here due to high-value intellectual property exposure.
- Software:Application publishers implement license enforcement and code obfuscation against reverse engineering. German industrial software vendors anchor European demand for these protections.
- E-commerce:Brand protection scanning targets counterfeit merchandise and unauthorized reseller channels.
- Telecommunications:Carriers integrate content protection into managed video services and network-level filtering.
Media & Entertainment absorbs the largest protection budgets. Software verticals are expanding most quickly as SaaS publishers harden subscription models.
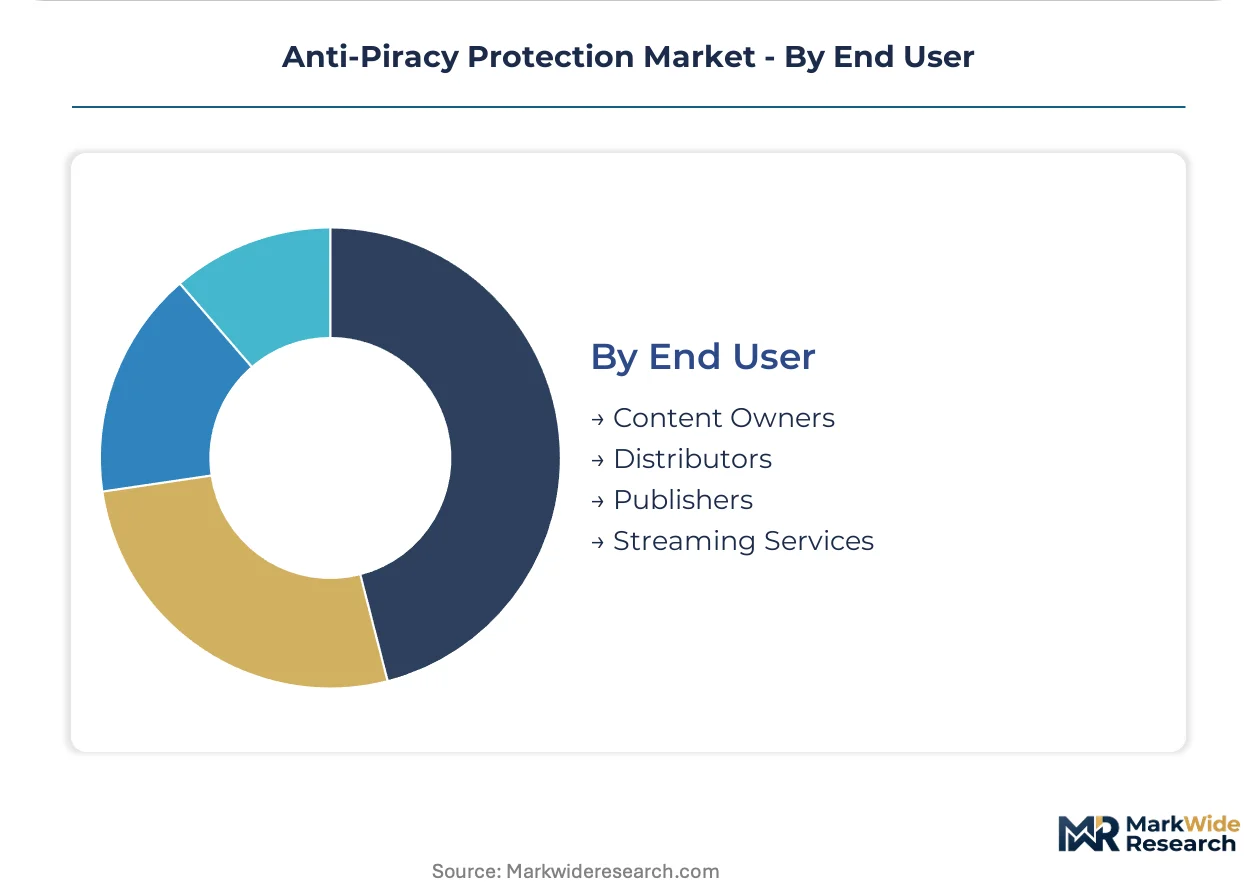
End User:
Customer type segmentation reflects divergent accountability structures, with direct revenue exposure correlating to security investment intensity.
- Content Owners:Studios, production companies, and rights holders bear primary infringement losses and drive forensic watermarking procurement. Major Hollywood and South Korean production houses mandate source-tracing capabilities for all distribution partners.
- Streaming Services:Subscription platforms invest in credential sharing detection and real-time piracy disruption to reduce churn. United States-based services lead deployment of behavioral analytics for account misuse identification.
- Distributors:Cable operators and satellite broadcasters implement conditional access for linear content protection.
- Publishers:Digital text and software publishers enforce access control for document and application distribution.
Streaming Services represent the fastest-growing end user category. Content Owners retain the deepest forensic watermarking penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forensic analysts and signal processing specialists cluster in Germany, South Korea, and the United States, anchoring regional capability concentrations for watermarking and encryption development.
United States
Hollywood studios and major streaming platforms drive forensic watermarking procurement for theatrical release windows. The Federal Communications Commission enforces signal protection standards for broadcast and cable distribution. Los Angeles and New York host the densest concentrations of content protection vendors serving premium video markets.
Germany
Premium broadcasters and sports leagues deploy live event protection systems requiring rapid source identification. The country's national media regulator imposes content monitoring duties on platform intermediaries. Berlin and Munich anchor European development centers for conditional access and credential sharing detection technologies.
South Korea
Streaming services favor cloud-based deployment for rapid scaling without data center investment. The national broadcasting authority mandates integrated encryption for licensed streaming operations. Seoul's digital media cluster concentrates vendor partnerships between platforms and forensic technology providers.
China
Licensed streaming operators face mandatory encryption requirements expanding vendor certification pipelines. The National Radio and Television Administration shapes product certification for market entry. Beijing and Shanghai host domestic encryption specialists serving state-affiliated content distribution networks.
India
Domestic streaming platforms anticipate compliance mandates following regulatory consultation on digital piracy remediation. The Telecom Regulatory Authority signals forthcoming expansion of platform obligations. Mumbai and Bengaluru concentrate content production and technology development activity.
Anti-Piracy Protection Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the anti-piracy protection market, with integrated platform vendors holding scale advantages over component specialists. The vendor base stratifies between Hollywood-studio-aligned encryption providers and streaming-native behavioral analytics firms. Three archetypes dominate: forensic watermarking patent holders, cloud-native monitoring services, and conditional access legacy incumbents. Consolidation pressures intensify as subscription bundling compresses buyer decision cycles and procurement teams prioritize single-vendor accountability.
Within the integrated platform tier, Synamedia and Irdeto exemplify scale-driven positioning across credential sharing detection and premium video security. Red Points occupies a position among automated brand protection specialists scanning e-commerce marketplaces. These three entities represent divergent strategic postures: streaming piracy disruption, conditional access patent leverage, and marketplace enforcement automation.
| Leading Market Players |
|---|
| Red Points |
| Irdeto |
| MarqVision |
| Verimatrix |
| Synamedia |
| MUSO |
| NAGRA NexGuard |
| Harvel |
| PACE Anti-Piracy |
| Others |
Supply Flow & Price Mechanics
Specialized semiconductor pricing for forensic watermarking chipsets cascades through three distinct vendor tiers, compressing margins for independent component suppliers while integrated platform vendors capture bundling premiums.
Pricing Analysis
The bundled-vs-unbundled service split separates forensic watermarking specialists from integrated platform vendors. SaaS-tiered subscription models dominate cloud-based monitoring services, while on-premises conditional access commands project-based licensing with customization premiums. Price differentiation rests on certification depth for EU AI Act compliance and forensic evidence admissibility standards. Pricing pressure stems from subscription bundling as major studios consolidate vendor relationships. Mid-tier streaming services exhibit acute price sensitivity, whereas Hollywood studios prioritize single-vendor accountability over cost optimization.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor foundries fabricating specialized encryption chipsets for conditional access modules. Hardware components concentrate in Taiwan, South Korea, and Germany, while cloud infrastructure draws from hyperscaler regions in the United States and Ireland. Raw material dependencies include silicon wafers, cryptographic processors, and steganographic signal processing units. Supply chain risk centers on export control restrictions for dual-use encryption technologies. Distribution runs through direct enterprise sales teams serving major studios and streaming platforms, supplemented by systems integrators for mid-market deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in cloud-native watermarking tiers, where automation compresses delivery costs while regulatory mandates sustain premium pricing power.
For Market Incumbents: Extend forensic watermarking patent portfolios into synthetic media authentication, where AI-generated content provenance creates adjacent revenue streams. Consolidate credential sharing detection capabilities through targeted capability acquisitions, responding to streaming platform demands for unified piracy disruption. Deepen vertical integration into edge computing infrastructure, embedding watermarking at CDN nodes to reduce latency and displace component vendors. For New Entrants and Emerging Players: Behavioral analytics for credential sharing detection offers a technology-first wedge into the streaming services segment, where incumbent platforms lack specialized account misuse expertise. India's anticipated regulatory expansion presents the most penetrable geography, with domestic streaming platforms lacking forensic capabilities ahead of TRAI compliance mandates. Pursue partnership-based go-to-market positioning with regional systems integrators already embedded in content distributor procurement cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native monitoring services possessing automated takedown workflows, as the EU Digital Services Act accelerates platform procurement timelines. Long-term viability favors vendors with demonstrated forensic evidence generation capabilities, sustaining pricing power through litigation-ready audit trails. Acquisition targets should demonstrate watermarking algorithm accuracy above industry benchmarks and established relationships with sports leagues or premium broadcasters. Watch for inflection signals in India's regulatory consultation outcomes, which would trigger compliance-driven procurement waves across domestic streaming platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Forensic Watermarking Patent Expansion | Secures litigation-ready evidence generation for EU AI Act compliance and sports league contracts. |
| Edge Computing Infrastructure Partnership | Embeds watermarking at CDN nodes to reduce latency for live sports protection in Germany and South Korea. |
| Credential Sharing Detection Platform Launch | Captures streaming service budgets consolidating anti-piracy spending into unified security contracts. |
| India Market Entry with Regulatory-Aligned Certification | Positions ahead of TRAI-mandated compliance requirements for domestic streaming platforms. |
| Synthetic Media Authentication Development | Addresses emerging demand for AI-generated content provenance verification across distribution chains. |
Methodological Framework
Coverage spans the United States, Germany, South Korea, China, and India, with primary inputs from each market informing demand-side validation. The analysis combines structured interviews with content protection technology executives, streaming platform security officers, broadcast engineering directors, and regulatory compliance leads with secondary validation from SEC filings, EU regulatory databases, and national broadcasting authority technical specifications. Bottom-up sizing of vendor deployments triangulates against top-down market aggregation across service type and deployment model segments.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include service type, deployment architecture, end-user category, and regional regulatory intensity. CAGRs derive from fitted growth curves anchored to disclosed vendor bookings and platform procurement cycle timing. Industry-specific forecast inputs incorporate theatrical release window patterns, live sports broadcast schedules, and streaming subscriber growth trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory enforcement divergence and encryption standard fragmentation. Forecasts reflect documented assumptions regarding platform consolidation rates and forensic analyst labor supply. Specific risk factors that could revise projections include open-source decryption tool proliferation degrading cryptographic effectiveness and sudden shifts in China's encryption certification requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Europe Security Testing Market
Security and Surveillance
North America Cargo and Vehicle Screening Market
Security and Surveillance
Security Inspection Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
5G-Enhanced Surveillance Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
Maritime Security Market
Security and Surveillance
Asia-Pacific Urban Security Screening Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Speed Limit Radar Signs Market
Security and Surveillance
Mass Transit Security Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
North America Security Testing Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Europe Baggage and Parcel Screening Market