
 Surveillance Radars Market | 2026-2036
Surveillance Radars Market Size, Share, and Industry Trends Forecast 2026-2036
Surveillance Radars Market Intelligence
Multi-source procurement of gallium nitride transmit/receive modules is broadening as prime contractors diversify beyond captive foundries. Thales Group leverages its European semiconductor partnerships to secure non-United States wafer supply for active array radars. RTX Corporation sustains dual-source qualification for airborne fire control backends across its Arizona and Massachusetts facilities. Hensoldt AG anchors German Bundeswehr programs with in-house radar software-defined signal processing while competing for NATO shared early warning contracts.
Surveillance radars are detection and tracking systems operating across L-band through Ku-band frequencies, typically generating three-dimensional target data via pulse-Doppler or electronic beam-steering architectures with instrumented ranges exceeding 400 kilometers for strategic air defense applications. These systems serve military and civil operators by providing persistent area coverage against aircraft, missiles, unmanned systems, and surface vessels under all weather conditions. Ground-based radar and phased array radar command the largest current revenue pools given mature air defense network refresh cycles across Europe and the Middle East, while space-based radar and synthetic aperture radar represent the fastest-expanding technology-application intersections driven by low Earth orbit constellation deployments and all-weather terrestrial imaging requirements. Maritime security applications concentrate margin in integrated coastal and offshore platform programs where shipborne and mobile radar variants converge.
FAA airworthiness standards, NATO STANAG waveform interoperability mandates, and ITU-R radio regulations collectively constrain frequency allocation, emission control, and cross-border data sharing protocols for surveillance radar deployments. United States EPA energy efficiency guidelines and emerging EU Green Deal procurement criteria now factor into military and civil radar source selection, favoring solid-state transmitters over vacuum tube legacy systems. Stakeholders must monitor gallium nitride substrate supply concentration and allied export control harmonization as these determine both cost trajectories and program eligibility across integrated defense markets.
Market Dynamics
The displacement of mechanically scanned radar architectures by solid-state active electronically scanned arrays constitutes the central structural force reshaping procurement patterns, foundry capacity allocation, and electromagnetic spectrum management across defense and civil aviation authorities.
Growth Catalysts
- NATO STANAG waveform mandates:Interoperability requirements for allied air defense networks accelerate replacement of legacy analog systems with digital beam-forming architectures.
- Gallium nitride substrate availability:Maturation of wide-bandgap semiconductor fabrication expands transmitter efficiency and thermal performance envelopes for long-range detection missions.
- Indo-Pacific maritime patrol expansion:Coastal surveillance and exclusive economic zone monitoring programs sustain shipborne radar modernization budgets across littoral states.
Market Restraints
- Gallium nitride wafer supply concentration:Non-captive foundry dependence creates vulnerability to export control harmonization delays between United States and allied semiconductor authorities.
- ITU-R spectrum reallocation friction:Compressed L-band and S-band allocations for 5G terrestrial services encroach on legacy radar operating windows.
- Vacuum tube obsolescence costs:Magnetron and traveling-wave tube maintenance infrastructure retirement imposes transitional capital burdens on operators with mixed fleets.
Strategic Opportunities
- Low Earth orbit synthetic aperture radar constellations:Commercial space-based imaging platforms create dual-use architectures for maritime domain awareness and disaster response.
- EU Green Deal defense procurement criteria:Energy efficiency mandates favor solid-state transmitter retrofits in European air defense network refresh programs.
- Software-defined signal processing convergence:Cognitive radar algorithms enable spectrum sharing and electronic counter-countermeasure adaptation without hardware replacement.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave and phased array design expertise concentrates within aging workforce cohorts and select defense research establishments.
- Airworthiness certification timelines:FAA and EASA software-intensive system validation protocols extend development cycles for civil-military dual-use radar variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surveillance Radars Market |
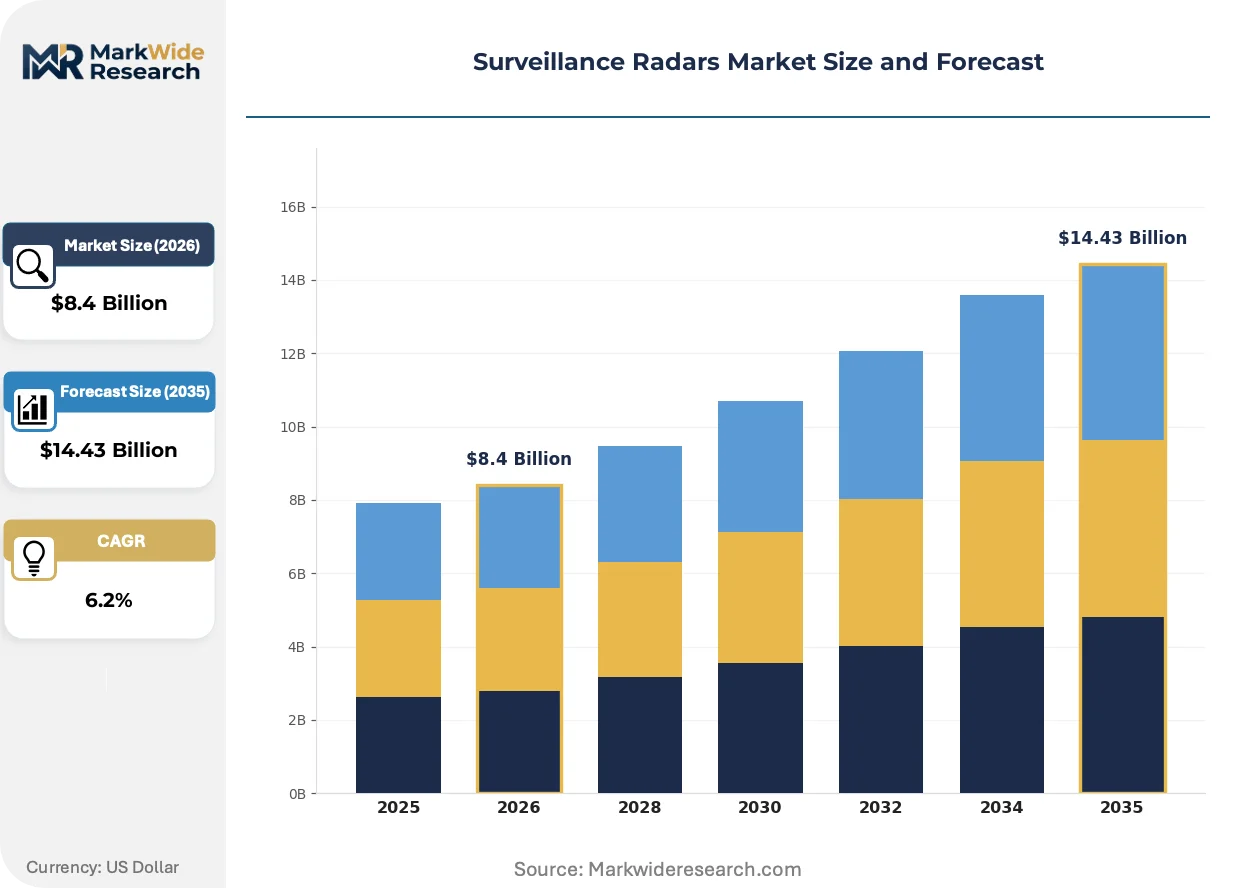
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground-Based Radar, Airborne Radar, Space-Based Radar, Shipborne Radar, Mobile Radar Technology: Doppler Radar, Phased Array Radar, Pulsed Radar, Continuous Wave Radar, Synthetic Aperture Radar Application: Border Surveillance, Maritime Security, Air Traffic Control, Coastal Monitoring, Disaster Management End User: Defense Forces, Homeland Security Agencies, Civil Aviation Authorities, Disaster Response Teams, Maritime Authorities |
| Companies Covered | Thales Group, Leonardo S.p.A., RTX Corporation, Israel Aerospace Industries Ltd., Hensoldt AG, Lockheed Martin Corporation, BAE Systems, Saab AB, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surveillance Radars Market Strategic Shifts & Innovations
Electromagnetic spectrum congestion and modular open systems architectures are redefining radar design priorities, with software-defined functionality displacing hardware-dependent performance differentiation across procurement categories.
Digital beam-forming with gallium nitride transmit/receive modules is converging with artificial intelligence-enabled target classification algorithms. Naval and ground-based air defense operators are adopting these architectures for simultaneous multi-mission tracking. The technology is converging with legacy mechanical radar replacement cycles to compress procurement decision timelines and consolidate supplier qualification pools.
United States EPA energy efficiency guidelines and emerging EU Green Deal procurement criteria now constrain military source selection for radar transmitters. Solid-state architectures gain preference over vacuum tube systems in contract evaluation scoring. European air defense network refresh programs and United States Federal Aviation Administration terminal radar replacement initiatives represent the most affected procurement streams.
Defense procurement offices are unbundling hardware acquisition from sustainment and upgrade services. Original equipment manufacturers face pressure to deliver open architecture interfaces enabling third-party software integration. This pattern concentrates in NATO member state integrated air and missile defense programs where interoperability mandates override single-source vendor preferences.
Surveillance Radars Market Segmentation
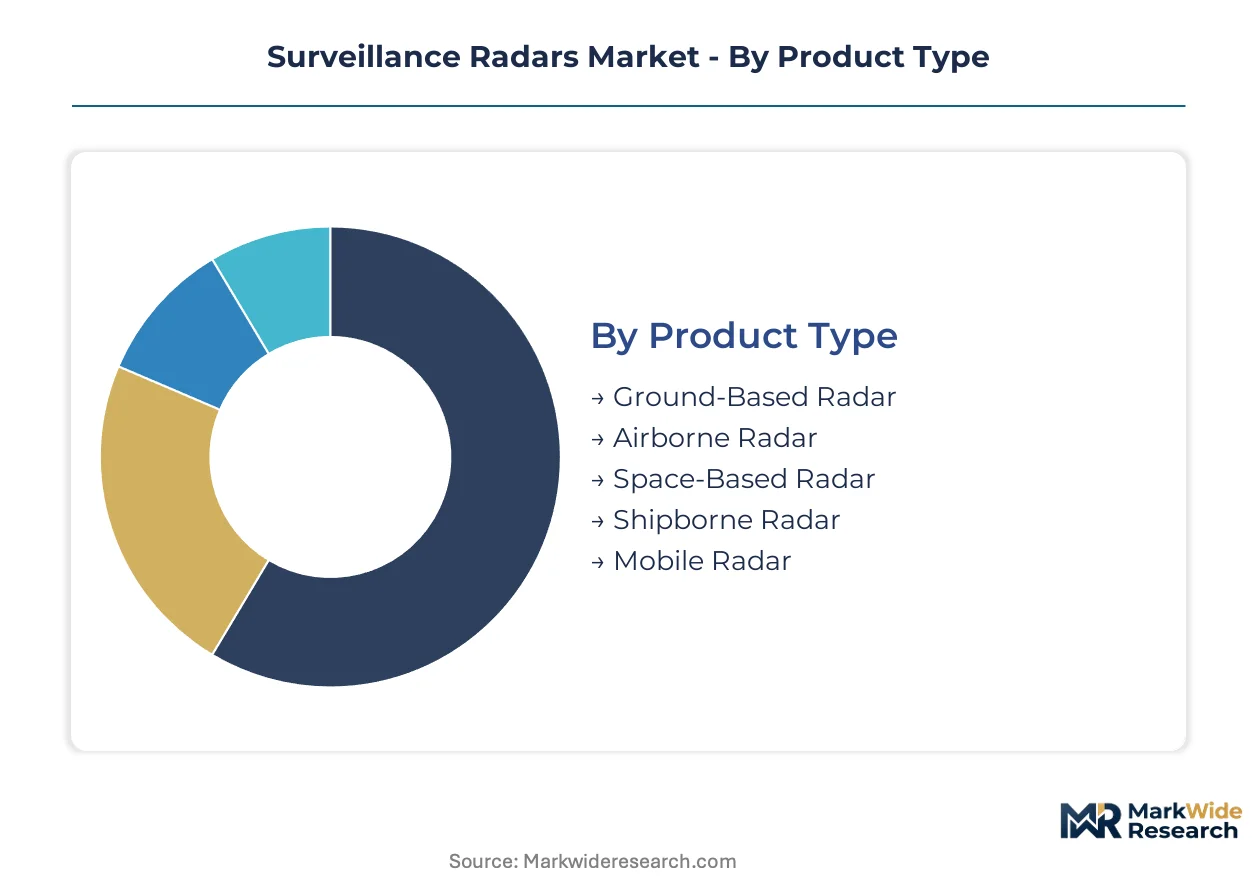
Surveillance radar procurement decisions diverge sharply across operational domains, with platform constraints and mission endurance requirements dictating technology selection. Buyers prioritize detection range, spectrum efficiency, and interoperability certification when evaluating category alternatives.
Product Type:
Platform mobility and power availability determine procurement budgets and lifecycle costs for defense and civil operators.
- Ground-Based Radar:Fixed-site installations with active electronically scanned arrays dominate NATO integrated air defense networks. German and Polish military procurement programs prioritize these systems for persistent territorial coverage against cruise missile and drone threats.
- Airborne Radar:Fighter fire-control and airborne early warning platforms demand compact, high-power gallium nitride transmit/receive modules. South Korean and Japanese fighter modernization programs concentrate demand for multi-mode airborne variants with simultaneous air-to-air and surface surveillance capability.
- Space-Based Radar:Low Earth orbit synthetic aperture constellations enable all-weather maritime domain awareness. Commercial satellite operators and defense agencies share launch costs for dual-use reconnaissance architectures.
- Shipborne Radar:Naval combat management systems integrate rotating and fixed-face arrays for horizon search and fire control. Littoral state coast guard expansion programs sustain demand for medium-range surface surveillance variants.
- Mobile Radar:Rapidly deployable truck-mounted systems serve expeditionary forces and disaster response coordination. Lightweight packaging and quick-erection masts differentiate competitive offerings for humanitarian relief agencies.
Ground-based systems lead on scale; space-based architectures lead on momentum.
Technology:
Spectral efficiency mandates and thermal performance thresholds drive foundry investment toward wide-bandgap semiconductor architectures.
- Phased Array Radar:Electronically steered beams enable simultaneous multi-target tracking and frequency agility. FAA terminal radar replacement and European air defense refresh programs mandate solid-state active arrays over mechanically scanned legacy systems.
- Synthetic Aperture Radar:Coherent processing of radar returns generates high-resolution imagery independent of weather or illumination. Commercial Earth observation constellations and military intelligence platforms converge on this technology for persistent terrestrial and maritime monitoring.
- Doppler Radar:Velocity measurement via frequency shift detection supports weather monitoring and low-altitude aircraft tracking. Civil aviation authorities deploy these systems for terminal area wind shear alerting.
- Pulsed Radar:High-peak-power transmission enables long-range detection with established vacuum tube or solid-state transmitters. Mixed fleets retain pulsed architectures for cost-sensitive perimeter surveillance applications.
- Continuous Wave Radar:Unmodulated carrier transmission supports short-range applications including proximity fuzing and automotive collision avoidance. Low probability of intercept characteristics attract special operations force applications.
Phased array platforms command procurement volume; synthetic aperture systems expand most quickly.
Application:
Mission-specific detection requirements determine waveform selection, antenna configuration, and data processing architecture.
- Border Surveillance:Persistent wide-area monitoring demands ground-based and aerostat-mounted radars with moving target indication. United States Customs and Border Protection and European Frontex operations sustain demand for integrated sensor networks spanning remote terrain.
- Maritime Security:Exclusive economic zone enforcement requires over-the-horizon detection of surface vessels and low-flying aircraft. Indo-Pacific littoral states prioritize shipborne and coastal radar modernization for territorial water integrity.
- Air Traffic Control:Terminal and en-route surveillance radars operate under strict FAA and Eurocontrol certification protocols. Primary and secondary surveillance radar replacement cycles concentrate procurement in North American and Western European civil aviation authorities.
- Coastal Monitoring:Harbor approach and offshore platform protection integrate radar with automatic identification system correlation. Port authorities and energy infrastructure operators specify all-weather detection capability for vessel traffic services.
- Disaster Management:Rapid deployment requirements favor lightweight mobile radars for search coordination and flood monitoring. Emergency management agencies specify interoperability with satellite communication backhaul for austere environment operations.
Air traffic control leads on installed base; maritime security climbs the fastest.
End User:
Procurement authority and funding mechanisms create distinct specification and certification pathways across buyer categories.
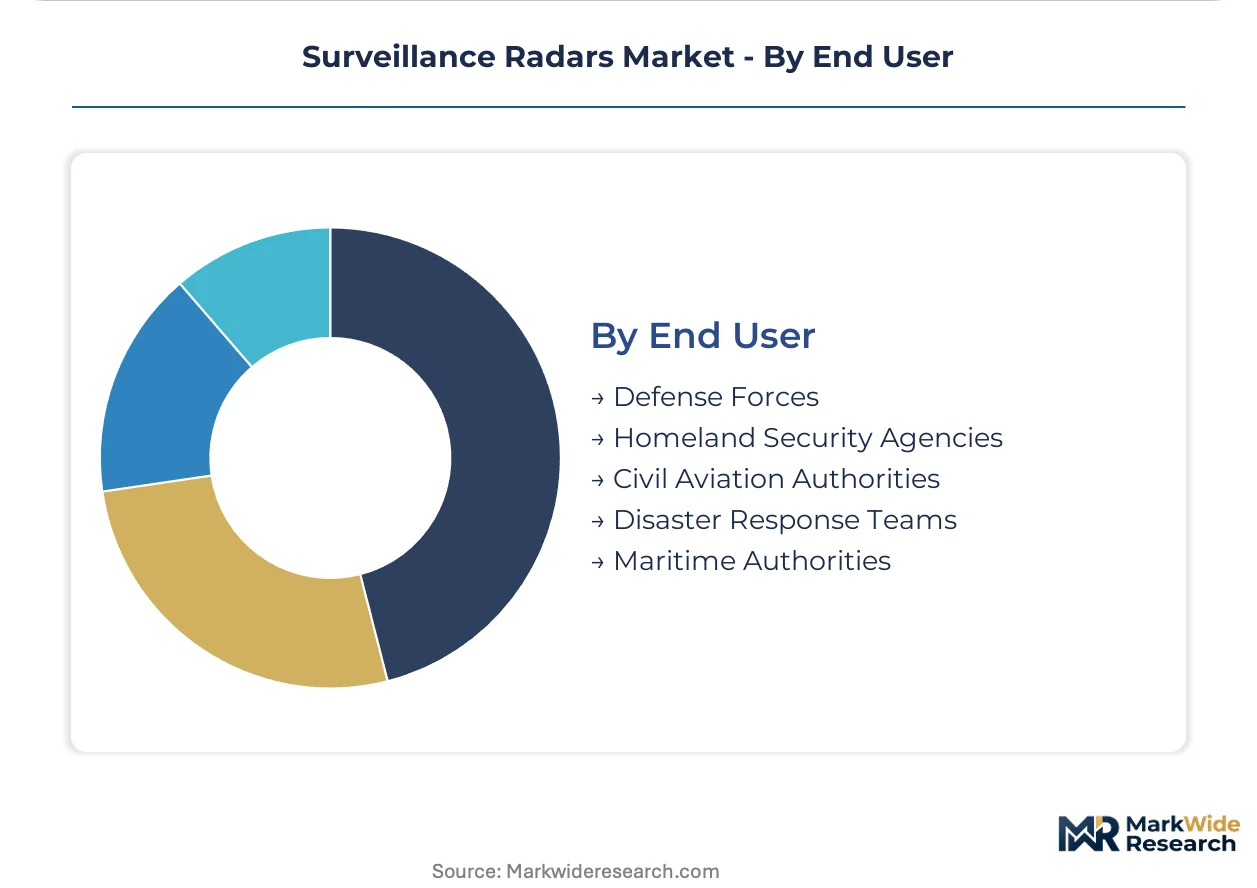
- Defense Forces:Military operators specify encrypted waveforms, electronic counter-countermeasures, and NATO STANAG interoperability. Pentagon and allied defense ministries dominate volume through multi-year program-of-record acquisitions.
- Homeland Security Agencies:Domestic law enforcement and border protection authorities balance detection performance with civil liberties compliance. United States Department of Homeland Security and European interior ministries fund integrated border surveillance networks.
- Civil Aviation Authorities:Air navigation service providers operate under ICAO standards and national regulator certification. FAA and EASA oversight shapes system validation timelines and software-intensive product acceptance.
- Disaster Response Teams:Humanitarian and emergency management organizations prioritize rapid deployment and minimal infrastructure dependency. United Nations agencies and national civil defense corps specify battery-operable and solar-compatible variants.
- Maritime Authorities:Coast guard and port state control agencies enforce safety of life at sea regulations through vessel traffic services. Classification society standards influence equipment qualification for offshore installation.
Defense forces lead on procurement value; civil aviation authorities gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting radar component sourcing toward jurisdictions with harmonized export controls and mature semiconductor fabrication ecosystems. Producers migrate gallium nitride module qualification programs to regions offering dual-use technology licensing clarity and allied defense procurement access.
United States
Pentagon integrated air and missile defense programs drive demand for ground-based active electronically scanned arrays. FAA terminal radar replacement initiatives operate under strict software-intensive system validation protocols. Arizona and Massachusetts host dual-source qualification facilities for airborne fire control backends.
Germany
Bundeswehr territorial coverage requirements sustain procurement of fixed-site phased array systems against cruise missile threats. EU Green Deal procurement criteria favor solid-state transmitter retrofits in air defense network refresh programs. Hensoldt AG anchors radar software-defined signal processing capabilities in the southern industrial corridor.
South Korea
Fighter modernization programs concentrate demand for multi-mode airborne variants with simultaneous air-to-air and surface surveillance. MFDS electromagnetic spectrum allocation rules tighten under coordinated ITU-R compliance frameworks. Seoul-based defense electronics clusters support indigenous active array development.
Japan
Maritime patrol expansion across the East China Sea sustains shipborne radar modernization budgets. METI industrial policy coordinates gallium nitride substrate supply security with allied semiconductor authorities. Nagoya-area precision manufacturing bases produce compact transmit-receive modules for airborne platforms.
United Kingdom
RAF integrated early warning network upgrades prioritize NATO STANAG waveform interoperability. Civil aviation authorities under CAA oversight enforce Eurocontrol certification alignment for terminal surveillance systems. Scottish aerospace clusters contribute to synthetic aperture radar payload integration for space-based programs.
Surveillance Radars Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue software-defined signal processing and low Earth orbit synthetic aperture constellations. The supplier base concentrates among defense primes with captive semiconductor partnerships and allied government program access. Three archetypes dominate: integrated systems houses with in-house foundry relationships, specialist radar component suppliers, and space-platform integrators. Competitive moves center on dual-source qualification for critical transmit-receive modules and open architecture interface standardization.
Within the integrated systems tier, Thales Group, RTX Corporation, and Hensoldt AG represent archetypal positioning. Thales leverages European semiconductor partnerships to secure non-United States wafer supply. RTX sustains dual-source qualification across Arizona and Massachusetts facilities. Hensoldt anchors German defense programs while competing for NATO shared early warning contracts. These three exemplify the premium-tier concentration around allied defense procurement access and electromagnetic spectrum regulatory alignment.
| Leading Market Players |
|---|
| Thales Group |
| Leonardo S.p.A. |
| RTX Corporation |
| Israel Aerospace Industries Ltd. |
| Hensoldt AG |
| Lockheed Martin Corporation |
| BAE Systems |
| Saab AB |
| Northrop Grumman Corporation |
| Others |
Cost & Logistics Intelligence
Captive gallium nitride foundry partnerships anchor supply positioning and pricing power for prime contractors serving NATO integrated air defense networks. Thales Group and RTX Corporation leverage in-house or dual-source wafer qualification to buffer procurement costs against export control harmonization delays between United States and allied semiconductor authorities.
Pricing Analysis
Distributor margins on gallium nitride transmit/receive modules compress as prime contractors pursue direct-to-foundry contracting. Three-tier pricing structure across ITAR-restricted, NATO-cleared, and commercial-off-the-shelf tiers reflects certification grade and end-use jurisdiction. Cost compression in vacuum tube replacement programs intensifies because EU Green Deal energy efficiency criteria weight solid-state architectures in contract scoring. Defense ministries exhibit lowest price sensitivity given program-of-record funding mechanisms, while civil aviation authorities face budget caps under national air navigation service provider tariffs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Pentagon and allied defense ministry procurement offices, bypassing component distributors for active array backend systems. Gallium nitride substrate supply concentrates in United States, Japan, and South Korea, with silicon carbide alternatives emerging from European semiconductor partnerships. Raw material dependencies span high-purity gallium metal, silicon carbide wafers, and rare-earth permanent magnets for antenna positioning systems. Single-source vulnerability in ITU-R spectrum allocation compliance creates procurement friction for multi-national programs. Distribution runs through defense primes with captive software-defined signal processing capabilities rather than independent component vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surveillance radars function as a stable compounder anchored by NATO STANAG waveform interoperability mandates that force predictable replacement cycles across allied air defense networks.
For Market Incumbents: To counter gallium nitride wafer supply concentration risks, RTX Corporation and Thales Group should deepen backward integration into European semiconductor partnerships for non-United States substrate sourcing, while Hensoldt AG expands dual-source qualification for airborne fire control backends across additional allied fabrication facilities. Certification investment in EU Green Deal compliance scoring solidifies position in German and Polish territorial coverage programs. For New Entrants and Emerging Players: Software-defined cognitive radar algorithms offer entry leverage into maritime security applications where littoral states seek spectrum-sharing capabilities without hardware replacement. Mobile radar variants for disaster response coordination present the most penetrable segment given minimal incumbent qualification pools and rapid deployment requirements. Go-to-market positioning through United Nations agency procurement frameworks bypasses defense prime qualification barriers. For Investors and Strategic Acquirers: Roll-up economics work for specialist radar component suppliers because NATO interoperability mandates consolidate vendor qualification pools around allied government program access. Five-to-ten year viability hinges on gallium nitride substrate supply security and electromagnetic spectrum regulatory alignment. Acquisition targets should show dual-use technology licensing clarity and existing FAA or EASA certification pathways. The signal to monitor is ITU-R spectrum reallocation negotiations affecting L-band and S-band operating windows.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source GaN Module Qualification | RTX Corporation sustains production continuity across Arizona and Massachusetts despite export control friction. |
| EU Green Deal Compliance Certification | Hensoldt AG secures preferred scoring in German air defense network refresh programs. |
| LEO SAR Constellation Partnership | Commercial space operators share launch costs with defense agencies for maritime domain awareness. |
| Open Architecture Interface Standardization | Defense procurement offices unbundle hardware from sustainment services across NATO programs. |
| Indo-Pacific Coastal Surveillance Expansion | South Korean and Japanese fighter modernization drives multi-mode airborne radar demand. |
Research Approach
Coverage spans United States, Germany, South Korea, Japan, and United Kingdom, with primary inputs from each defense procurement office and civil aviation authority. Primary interviews incorporated radar systems engineers at Thales Group and Hensoldt AG, Pentagon program office directors, FAA terminal radar replacement managers, and Indo-Pacific coast guard procurement leads. Secondary validation drew from NATO STANAG documentation, ITU-R spectrum allocation filings, EPA energy efficiency guidelines, SEC 10-K disclosures from RTX Corporation and Lockheed Martin, and EU Green Deal procurement criteria drafts. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Granularity-level modeling disaggregated revenue across ground-based, airborne, space-based, shipborne, and mobile platform categories, with technology splits for phased array, synthetic aperture, Doppler, pulsed, and continuous wave architectures. Application dimensions spanned border surveillance, maritime security, air traffic control, coastal monitoring, and disaster management. End-user segmentation captured defense forces, homeland security agencies, civil aviation authorities, disaster response teams, and maritime authorities. CAGRs derived from replacement cycle analysis, procurement pipeline visibility, and regulatory mandate enforcement timelines. Industry-specific inputs included gallium nitride substrate supply forecasts and ITU-R spectrum reallocation negotiation status.
The model holds under sustained NATO defense spending commitments and allied export control harmonization; deviation in electromagnetic spectrum allocation rulings or gallium nitride supply disruptions would shift procurement timelines and cost trajectories. Forecasts reflect assumptions regarding FAA terminal radar replacement pacing and Indo-Pacific maritime patrol expansion budgets. Periodic stress-testing of base assumptions against ITU-R negotiation outcomes and EU Green Deal enforcement is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Perimeter Security Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market
Security and Surveillance
Middle East and Africa Cargo Inspection Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Security Intelligence Market
Security and Surveillance
Global Alarm Monitoring Market
Security and Surveillance
Specialized Threat Analysis and Protection Market
Security and Surveillance
Russian Intelligent Eavesdropping Detection System Market
Security and Surveillance
Europe Border Security Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Anti-Piracy Protection Market
Security and Surveillance
Middle East and Africa Baggage and Parcel Screening Market
Security and Surveillance
Security Operations Center Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Door and Window Alarm Market