
 Driving Protection Gear Market | 2026-2036
Driving Protection Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Driving Protection Gear Market Analysis
Market Context
Asset-light leasing models for premium racing suits and track-day equipment is narrowing the competitive field to firms with strong balance sheets and brand equity. Alpinestars leverages its vertical integration in leather tanning and cut-and-sew operations to sustain margin control across price tiers. Dainese anchors its position through intensive R&D in composite armor systems, while Fox Head Inc. competes aggressively in off-road channels where seasonal demand fluctuates.
Technical Definition and Segment Structure
Driving protection gear encompasses purpose-built apparel and equipment—helmets with multi-density EPS liners, abrasion-resistant garments with Aramid fiber reinforcement, and impact-absorbing joint protectors—engineered to mitigate kinetic energy transfer during vehicular incidents. The primary commercial purpose centers on occupant survivability across motorsport, commercial transport, and recreational driving contexts. Helmets command the largest value pool due to mandatory wear laws and replacement cycles tied to impact events, while Kevlar-based materials capture expanding share as riders prioritize slide protection over traditional leather. CE Certified products dominate European distribution channels, though DOT Approved helmets retain structural importance in North American mass retail.
Regulatory Frame and Outlook
DOT, ECE R22.06, and Snell Memorial Foundation standards collectively define helmet performance benchmarks, with ECE's updated rotational-impact protocols forcing redesigns of legacy models. ISO 13232 motorcycle helmet testing and CE marking under EU PPE Regulation 2016/425 shape market access requirements for cross-border suppliers. Stakeholders must monitor evolving state-level mandates in emerging markets where enforcement consistency determines actual replacement demand.
Market Dynamics
Mandatory helmet laws in India and tightening CE certification under EU PPE Regulation 2016/425 are accelerating replacement cycles and compressing product development timelines across the value chain.
Growth Catalysts
- Urban two-wheeler commuting:Dense traffic congestion in Indian and Southeast Asian megacities is pushing commuters toward motorcycles as primary transport, expanding the addressable rider base for daily-use protection equipment.
- ECE R22.06 rotational-impact protocols:Updated testing standards in Europe are forcing manufacturers to redesign legacy helmet architectures, creating upgrade demand among safety-conscious riders.
- Aramid fiber reinforcement:Kevlar-based abrasion panels in jackets and pants are displacing traditional leather in slide-protection applications, opening premium price tiers for textile-based gear.
Market Restraints
- Raw material concentration:High-grade EPS liner foam and Aramid fiber production concentrates in China and the United States, exposing manufacturers to input cost volatility and supply disruption.
- Certification fragmentation:DOT, ECE, and Snell standards operate without mutual recognition, forcing parallel testing and inventory duplication for cross-border suppliers.
- Seasonal demand fluctuation:Off-road and track-day equipment sales collapse in winter months across temperate climates, straining working capital for distributors.
Strategic Opportunities
- Asset-light leasing models:Premium racing suit rental services for track-day enthusiasts are emerging in Germany and the United Kingdom, reducing customer acquisition costs for high-end brands.
- Smart helmet integration:Convergence of heads-up displays with Bluetooth communication systems is creating new electronics partnerships in the premium segment.
- State-level mandate expansion:Unenforced helmet laws in Brazilian and Indonesian provinces present whitespace as local governments align with federal safety directives.
Industry Challenges
- Composite armor R&D timelines:Dainese and Alpinestars are compressing development cycles for viscoelastic protectors that meet ECE Level 2 standards without sacrificing flexibility.
- Multi-standard testing capacity:Third-party laboratories face backlogs for simultaneous DOT, ECE, and Snell certification, delaying product launches by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driving Protection Gear Market |
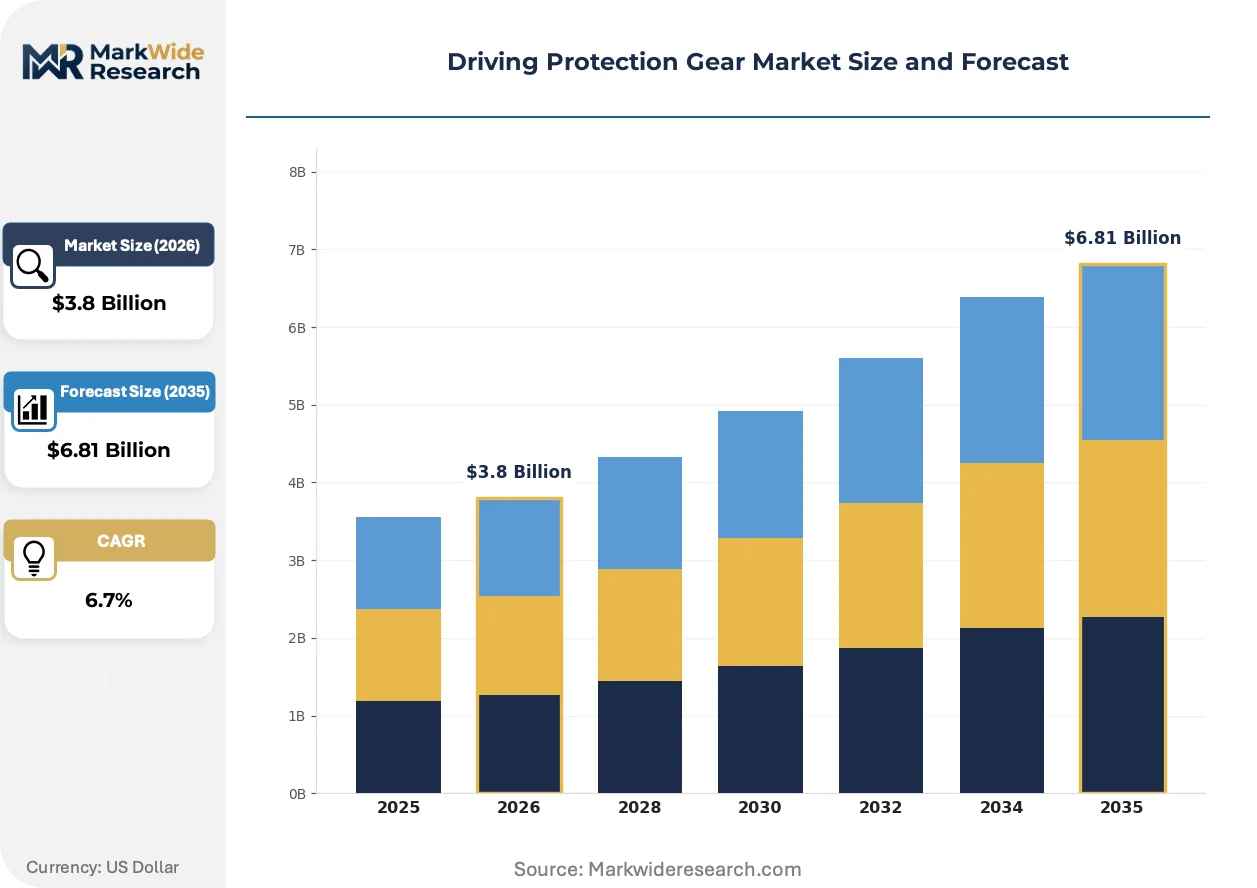
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Helmets, Vests, Knee Pads Material: Leather, Nylon, Kevlar, Foam End User: Motorcyclists, Delivery Personnel, Off-Road Drivers, Racing Enthusiasts Certification: CE Certified, DOT Approved, ISO Compliant, Snell Rated |
| Companies Covered | Alpinestars, Dainese, Fox Head Inc., SCOTT Sports SA, Leatt Corporation, Sparco S.p.A, REV'IT!, Arai Helmets, EVS Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driving Protection Gear Market Emerging Trajectories
Active safety systems and connected rider technologies are redefining protection from passive impact absorption toward predictive hazard mitigation and real-time biometric monitoring.
Multi-density EPS liners with shear-away outer shells are rendering obsolete single-density foam architectures that fail rotational-impact tests. Premium helmet manufacturers in Italy and Japan are adopting these designs for 2024 model year releases. The technology is compressing market share for legacy DOT-only certified products in European distribution channels.
ECE R22.06's rotational-impact testing mandate is forcing redesigns of legacy helmet models across European markets. Manufacturers must retool molding equipment and reformulate foam densities to meet the new standard. The regulation most affects modular and open-face helmet categories, where structural complexity complies poorly with oblique-impact protocols.
Subscription-based gear replacement programs are displacing traditional retail purchase cycles for high-abrasion items like gloves and knee sliders. Track-day operators in the United Kingdom and California are bundling equipment refresh into annual membership fees. This model concentrates most visibly among amateur racing enthusiasts who prioritize consistent protection over long-term ownership.
Driving Protection Gear Market Segmentation
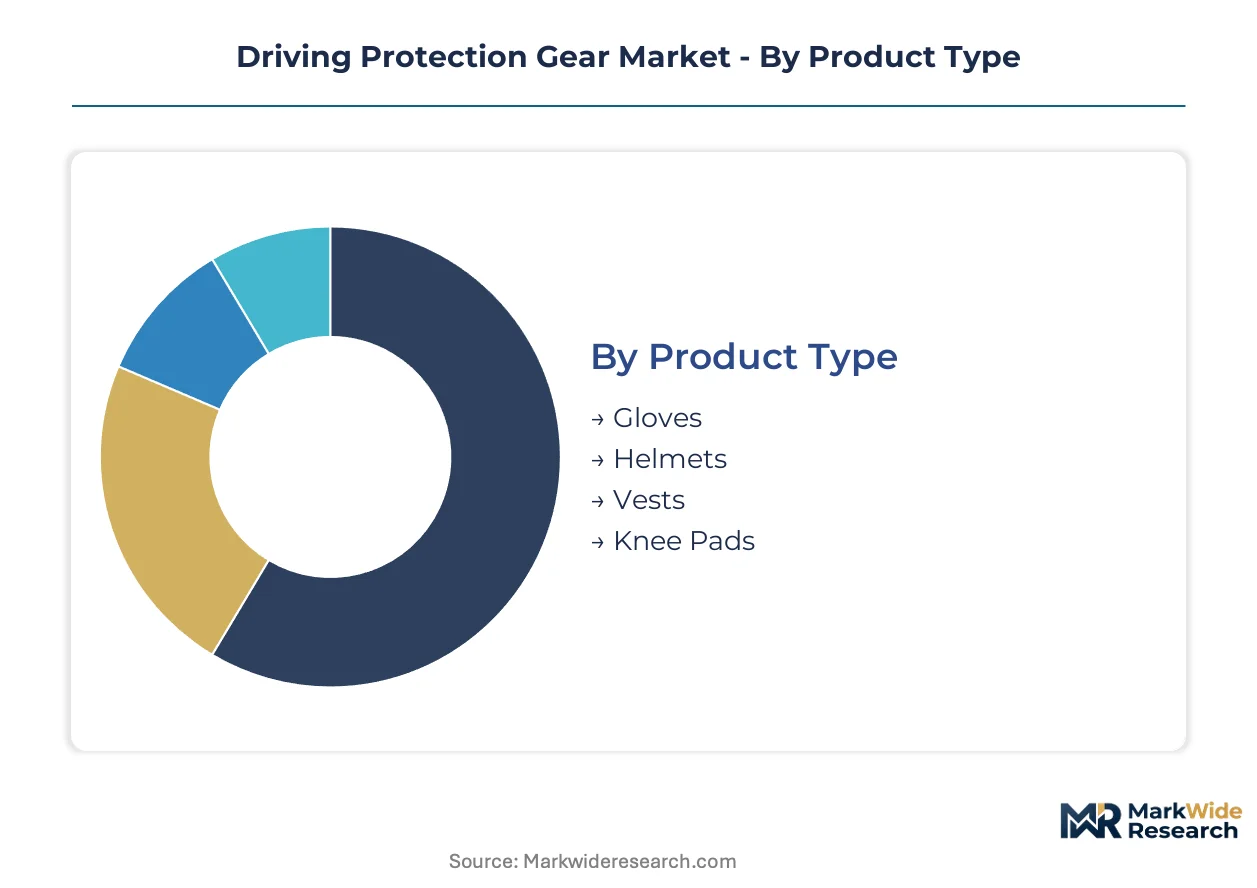
Segmentation in driving protection gear reveals how safety mandates, material science advances, and use-case intensity fragment demand across price-performance tiers. Manufacturers optimize inventory and certification strategies around these divides.
Product Type:
Cost tier differentiation separates disposable consumables from capital-equipment purchases with multi-year replacement cycles.
- Helmets:Multi-density EPS liners with shear-away shells dominate R&D investment. ECE R22.06 rotational-impact compliance in Germany and Italy forces architecture redesigns, compressing margins for legacy DOT-only producers.
- Gloves:Aramid-reinforced palms and conductive fingertips for smartphone operation define premium specifications. Indian delivery fleets generate volume demand for abrasion-resistant daily-wear variants.
- Vests:Back protectors with viscoelastic armor address spine-impact scenarios. CE Level 2 certification separates professional racing supply from recreational retail.
- Knee Pads:Composite sliders and hinged joint systems protect against torsional forces. Off-road channels in California and Queensland concentrate seasonal purchasing.
Helmets hold installed capacity. Gloves are rotating up the share rankings.
Material:
Application intensity determines whether riders prioritize slide distance, breathability, or impact absorption in their gear selection.
- Kevlar:Aramid fiber panels deliver superior abrasion resistance at one-third the weight of leather. Textile-based jackets with Kevlar reinforcement gain preference among urban commuters in Mumbai and Jakarta.
- Leather:Full-grain cowhide and kangaroo variants retain dominance in track-day and professional racing contexts. Alpinestars and Dainese maintain captive tanning operations to secure premium hide supply.
- Nylon:Ballistic-grade polyamide shells with waterproof membranes serve all-weather touring segments. Cordura-based construction dominates mid-price touring jackets.
- Foam:Multi-density EPS and viscoelastic formulations absorb kinetic energy in helmet liners and joint protectors. Chinese chemical producers control high-grade EPS precursor supply.
Kevlar is climbing the fastest. Leather retains brand equity premiums.
End User:
Volume concentration varies dramatically between daily commuters with mandated compliance and discretionary purchasers seeking performance optimization.
- Motorcyclists:Urban two-wheeler commuters in Indian megacities constitute the largest addressable base. State helmet mandates in Maharashtra and Karnataka accelerate replacement cycles.
- Delivery Personnel:Last-mile logistics workers require abrasion-resistant daily-wear gear with high visibility. Food delivery aggregators in São Paulo and Mexico City subsidize protective equipment.
- Off-Road Drivers:Motocross and enduro participants purchase roost guards and knee braces seasonally. Australian and Californian retail channels concentrate demand in spring quarters.
- Racing Enthusiasts:Amateur track-day participants lease premium one-piece suits through subscription models. German and UK operators bundle equipment refresh into annual membership fees.
Motorcyclists hold installed capacity. Delivery personnel are rotating up the share rankings.
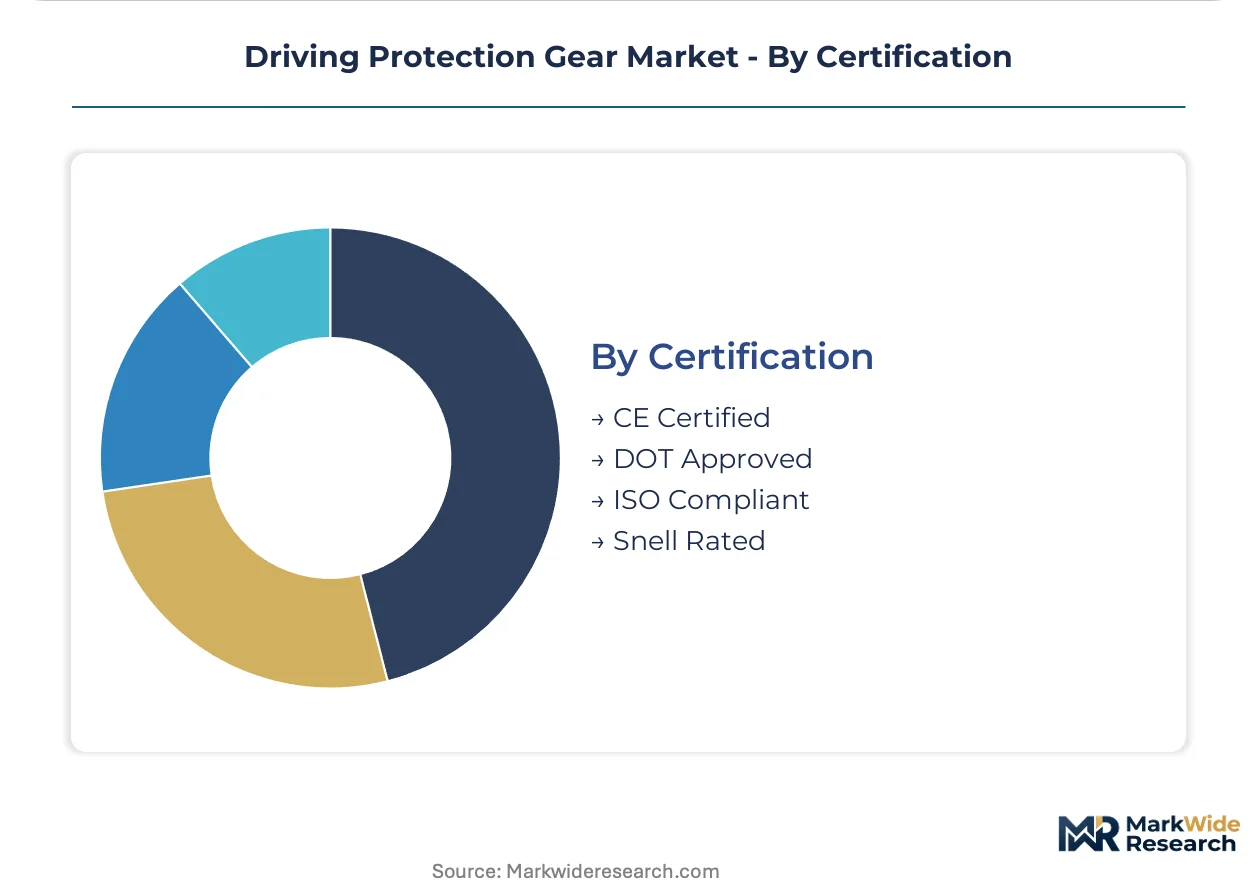
Certification:
Geography determines which testing protocols govern market access, with mutual recognition absent between major regulatory regimes.
- CE Certified:EU PPE Regulation 2016/425 mandates third-party conformity assessment for protective garments and helmets. ECE R22.06 rotational-impact testing tightens requirements for European distribution.
- DOT Approved:FMVSS 218 compliance suffices for US highway use but lacks reciprocity with European standards. Mass retail channels in Texas and Florida stock predominantly DOT-certified inventory.
- ISO Compliant:ISO 13232 motorcycle helmet testing provides baseline impact benchmarks. Manufacturers seeking multi-market access use ISO protocols as reference standards.
- Snell Rated:Snell Memorial Foundation criteria exceed government minimums for impact attenuation. Racing organizations in California and Japan specify Snell certification for competition entry.
CE Certified holds installed capacity. DOT Approved is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helmet mandates and safety standard upgrades are redirecting procurement flows across major motorcycle markets. State enforcement of protective equipment laws is tightening in high-volume jurisdictions, while rotational-impact testing protocols are reshaping product approval pathways in developed economies.
India
Maharashtra and Karnataka state governments enforce mandatory helmet laws for two-wheeler riders, accelerating replacement cycles in Mumbai and Bangalore urban corridors. The Bureau of Indian Standards mandates ISI certification for all protective headgear sold domestically. Manufacturing clusters in Pune and Chennai supply abrasion-resistant jackets to food delivery fleets operating under aggregator-mandated safety programs.
United States
NHTSA administers FMVSS 218 certification for highway-legal helmets, though state-level enforcement varies between universal mandate and partial exemption regimes. California and Florida represent opposing regulatory poles, with the former mandating full protective equipment and the latter permitting adult helmet choice. Track-day operators in Southern California and Arizona concentrate seasonal demand for premium racing suits and composite armor systems.
Germany
KBA enforces ECE R22.06 rotational-impact protocols that disqualify legacy helmet architectures from type approval. The updated standard forces manufacturers to reformulate multi-density EPS liner densities. Industrial concentration in Bavaria and Baden-Württemberg hosts R&D facilities for viscoelastic armor systems, with Munich-area firms pioneering smart helmet integration with heads-up display modules.
Italy
CE marking under EU PPE Regulation 2016/425 governs market access for protective garments and helmets distributed through European channels. The regulation's third-party conformity assessment requirements favor established manufacturers with testing laboratory relationships. Racing equipment specialists concentrate in the Motor Valley corridor between Modena and Bologna, supplying professional motorsport teams and amateur track-day participants.
Brazil
ANVISA oversees medical device classifications for protective equipment with biometric monitoring capabilities, creating regulatory overlap for smart helmet categories. State-level helmet mandates in São Paulo and Rio de Janeiro contrast with unenforced federal guidelines in northern provinces. Last-mile delivery growth in São Paulo metro and Belo Horizonte generates volume demand for abrasion-resistant daily-wear gear subsidized by logistics aggregators.
Driving Protection Gear Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered certification and price-performance segments. The market structure concentrates around vertically integrated manufacturers with captive material supply and design-intensive specialists with outsourced production. Three archetypes dominate: leather-processing heritage houses with tanning operations, composite armor R&D laboratories, and electronics-integrating smart equipment developers. Competitive moves center on backward integration into raw material supply and multi-standard testing capacity expansion.
Within the vertically integrated tier, Alpinestars and Dainese exemplify manufacturers with in-house control over leather processing and cut-and-sew operations. Fox Head Inc. occupies a position among off-road specialists with seasonal demand exposure. These three companies represent distinct strategic postures: heritage leather craftsmanship, composite protection engineering, and action sports channel dominance.
| Leading Market Players |
|---|
| Alpinestars |
| Dainese |
| Fox Head Inc. |
| SCOTT Sports SA |
| Leatt Corporation |
| Sparco S.p.A |
| REV'IT! |
| Arai Helmets |
| EVS Sports |
| Others |
Supply Flow & Price Mechanics
The Shenzhen-Port of Los Angeles freight corridor's rate volatility directly shapes margin structures for Aramid fiber importers, concentrating pricing power among manufacturers with captive EPS foam production while forcing spot-market buyers into three-tier spreads across certification grades.
Pricing Analysis
Certification level creates the primary spread between mass retail and professional racing tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with ECE R22.06 compliance commanding substantial premiums over DOT-only equivalents. Price differentiation hinges on composite armor R&D investment and multi-standard testing capacity. Cost compression in entry-level helmets is intensifying because Chinese EPS precursor suppliers face energy input volatility. Fleet procurement managers for Indian delivery aggregators exhibit highest price sensitivity, while amateur racing enthusiasts leasing track-day equipment show lowest.
Supply Chain Analysis
Contract manufacturing capacity for cut-and-sew assembly concentrates in Vietnam, Bangladesh, and southern China's Guangdong province. Raw material sourcing draws from Chinese chemical producers for high-grade EPS precursors, Italian tanneries for full-grain racing hides, and DuPont-licensed facilities for Kevlar fiber. Single-source vulnerability in rotational-impact testing laboratory capacity creates certification bottlenecks. Distribution runs through specialty motorsport retailers in developed markets and OEM bundling agreements with two-wheeler manufacturers in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturers possessing in-house multi-density EPS formulation capabilities command structural advantage as ECE R22.06 redesigns compress development timelines for competitors dependent on external laboratories.
For Market Incumbents: Build regulatory certification moats by expanding parallel DOT-ECE-Snell testing capacity before laboratory backlogs worsen. Secure captive Aramid fiber supply through long-term offtake agreements with Chinese chemical producers. Alpinestars and Dainese already control leather tanning; extending this upstream control into foam precursor supply hedges against input cost spikes from energy-intensive Chinese production. For New Entrants and Emerging Players: Establish a beachhead in Brazilian state-level mandate enforcement whitespace before federal alignment tightens. Target unpenetrated last-mile delivery fleet procurement in São Paulo and Belo Horizonte where logistics aggregators subsidize protective equipment. Pursue white-label manufacturing partnerships with Indian ISI-certified producers to bypass European laboratory queues. For Investors and Strategic Acquirers: Composite armor R&D laboratories with ECE Level 2 viscoelastic formulations represent the most defensible acquisition archetype. Long-term viability rests on smart helmet electronics integration capabilities where Munich-area engineering clusters currently concentrate. Watch for quarterly inflection in Indian state helmet mandate enforcement consistency as replacement cycle acceleration signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Testing Capacity Expansion | Parallel DOT-ECE-Snell certification reduces product launch delays from laboratory backlogs. |
| Backward Integration into EPS Precursor Supply | Captive foam formulation hedges against Chinese energy input cost volatility. |
| Smart Helmet Electronics Partnership | Munich-area HUD integration capabilities open premium pricing tiers. |
| Subscription-Based Gear Replacement Programs | UK and California track-day operators bundle refresh into annual membership fees. |
| State-Level Mandate Enforcement Positioning | Brazilian and Indonesian provincial alignment with federal directives creates volume windows. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, including helmet product managers at Alpinestars and Dainese, procurement leads at Indian food delivery aggregators, third-party testing laboratory directors in Germany and Italy, and specialty motorsport retailers in California and Queensland. Secondary validation drew from NHTSA FMVSS 218 filings, ECE R22.06 type approval databases, KBA regulatory notices, and Indian BIS ISI certification records. Bottom-up demand modeling across end-user segments triangulated against top-down value chain analysis.
Calibration against historical replacement cycle data and regulatory implementation timelines anchored projections across the analysis window. Segmentation dimensions modeled include product type, material composition, end-user intensity, and certification tier. CAGRs derived from regression analysis of helmet mandate enforcement expansion and ECE standard upgrade adoption curves. Industry-specific inputs incorporated seasonal off-road demand fluctuation patterns and smart helmet electronics penetration rates.
Stress conditions across Aramid fiber input costs, laboratory testing capacity constraints, and Indian state enforcement consistency were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of KBA type approval volumes and Maharashtra helmet compliance checkpoint data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Functional Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Combat Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
China Premium Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Emergency Showers Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Gloves Market