
 Security and Surveillance Equipment Market | 2026-2036
Security and Surveillance Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Security and Surveillance Equipment Market Intelligence
A shift from monolithic government contracts towards a more fragmented base of commercial and residential end users is rebalancing market dynamics. Axis Communications leverages its open-platform IP solutions to serve diverse integrators. In contrast, Dahua Technology sustains its position through large-scale manufacturing capabilities. Meanwhile, Verkada differentiates with its integrated, cloud-native hardware and software platform, targeting enterprise clients seeking simplified management.
Security and surveillance equipment encompasses electronic devices designed for monitoring, detection, and access control. These systems often integrate high-resolution cameras, sometimes with resolutions exceeding 4K, and sensor technologies to capture, record, and analyze activity for safety and asset protection. Within the technology segment, IP cameras and cloud-based platforms are the dominant categories, displacing legacy analog systems. Demand from critical infrastructure and commercial facilities represents the largest application segments, requiring sophisticated video analytics and access control integration.
Multiple regulatory frameworks influence market access and product design. The US National Defense Authorization Act (NDAA) restricts procurement of certain foreign-made equipment for federal use. In Europe, GDPR compliance is mandatory for handling personal data captured by surveillance systems, while China's GB standards dictate technical specifications. Navigating evolving cybersecurity certification requirements and data localization mandates is a critical strategic challenge for all vendors.
Market Dynamics
The central tension shaping the market is the conflict between national security-driven procurement restrictions, like the US NDAA, and the deeply integrated global supply chains for electronic components and manufacturing, largely centered in China.
Growth Catalysts
- Smart City Initiatives:Government-led urban infrastructure projects, particularly in countries like India, create large-scale, recurring demand for integrated traffic management, public safety, and smart building surveillance systems.
- Regulatory Mandates:Compliance requirements, such as the EU's GDPR, compel organizations to upgrade legacy systems to modern platforms with robust data protection and privacy-enhancing features.
- Technology Displacement:The performance and feature superiority of IP-based cameras and cloud management platforms continue to drive the replacement of outdated analog CCTV systems across commercial and industrial facilities.
Market Restraints
- Restrictive Trade Policies:The US National Defense Authorization Act (NDAA) explicitly bars federal agencies from procuring or using equipment from specific Chinese manufacturers, fragmenting the market and limiting vendor choice.
- Bandwidth and Storage Costs:The adoption of high-resolution cameras, including 4K and above, imposes significant costs and technical challenges related to network bandwidth and data storage infrastructure for end users.
- Cybersecurity Vulnerabilities:The proliferation of connected IP devices creates a larger attack surface, with frequent discoveries of security flaws deterring adoption among risk-averse enterprises without dedicated IT security teams.
Strategic Opportunities
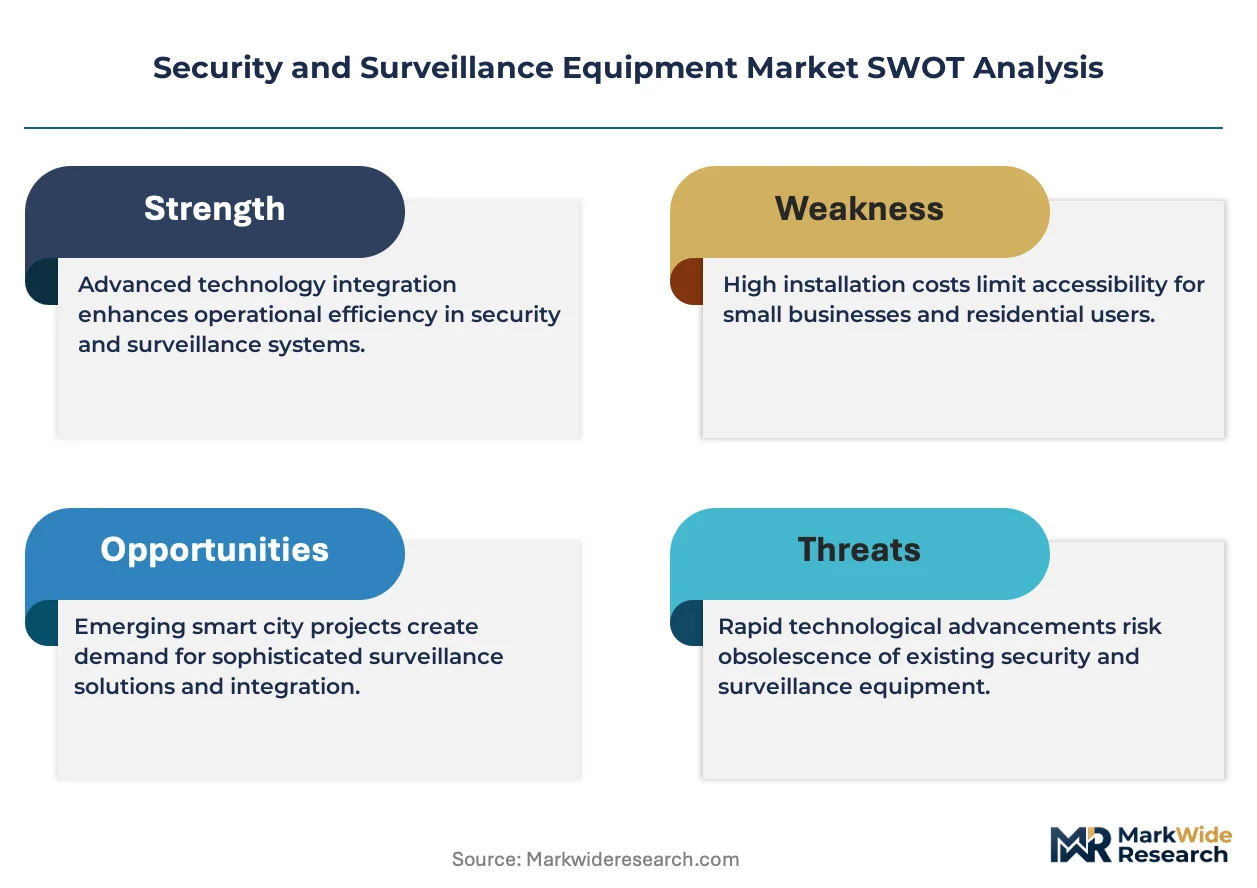
- AI and Analytics Convergence:Integrating AI-powered video analytics with other sensors, such as thermal or acoustic detectors, offers opportunities to provide proactive threat detection and operational intelligence for critical infrastructure protection.
- Vertical-Specific Solutions:Developing tailored surveillance platforms for emerging applications in retail analytics, industrial process monitoring, or healthcare patient safety allows vendors to create higher-margin, differentiated offerings.
- Cloud-Based Access Control:The expansion of cloud-managed services from video surveillance into physical access control provides a significant opportunity for vendors to offer a unified, subscription-based security platform.
Industry Challenges
- Legacy System Integration:A primary operational hurdle for installers is the complexity and cost associated with integrating modern IP-based surveillance systems with entrenched analog equipment in large-scale deployments.
- Data Governance Complexity:Navigating the patchwork of data localization and privacy laws, which vary significantly between jurisdictions like the EU and China, presents a major compliance challenge for global cloud service providers.
- Cybersecurity Certification:Vendors face a continuous challenge in keeping products compliant with evolving cybersecurity standards and certification programs, which can create significant delays in market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security and Surveillance Equipment Market |
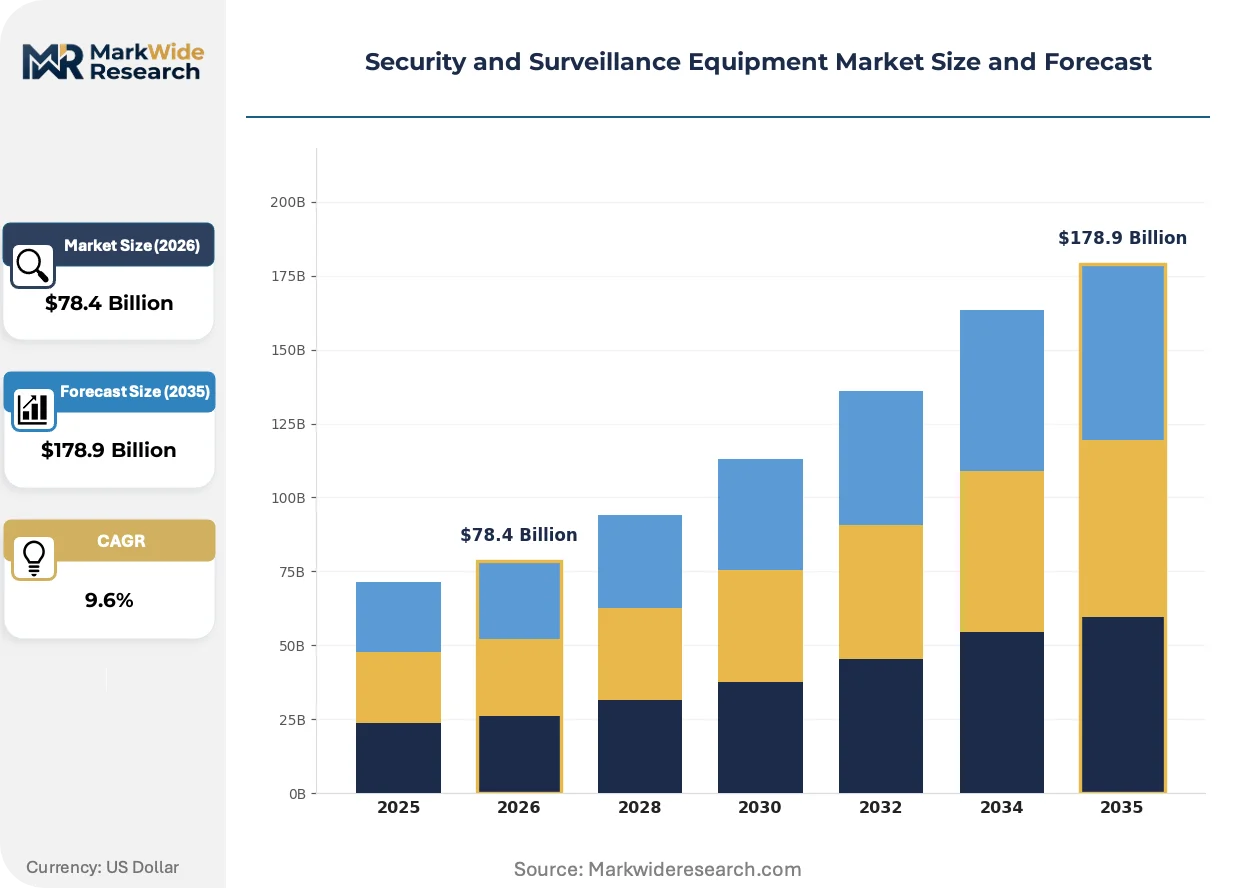
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $178.9 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, Access Control Systems, Intrusion Alarms, Video Analytics Devices, Fire Detection Systems Technology: IP Cameras, Thermal Imaging, Wireless Sensors, Biometric Scanners, Cloud-based Platforms Application: Banking & Financial Services, Transportation Hubs, Commercial Facilities, Critical Infrastructure, Educational Institutions End User: Government Agencies, Industrial Plants, Residential Complexes, Retail Chains, Hospitality Venues |
| Companies Covered | Dahua Technology, Pelco, Hanwha Vision, Avigilon, Panasonic i-PRO, Axis Communications, Bosch Security, Verkada, Hikvision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security and Surveillance Equipment Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental shift from passive evidence collection to active, intelligent data analysis. This transition is driven by advancements in on-device processing, changing regulatory pressures, and new service delivery models.
Edge AI embeds analytics processing directly onto cameras or local network appliances. Enterprise and critical infrastructure sectors are adopting this technology to enable faster, more reliable alerts without overwhelming network resources. This on-device intelligence is electrifying the market by enabling real-time operational decisions and forensic search capabilities that were previously unfeasible.
Europe's AI Act introduces a risk-based framework for artificial intelligence systems, directly impacting video surveillance. The regulation imposes stringent transparency and oversight requirements on high-risk applications, such as AI used for biometric identification in public spaces. Analytics software vendors targeting the EU are now redesigning products to include explainability features and human-in-the-loop safeguards to ensure compliance.
A transition from one-time hardware sales to recurring revenue models like Video-Surveillance-as-a-Service (VSaaS) is reconfiguring the channel. This disrupts traditional integrators focused on project-based installations, as cloud-native providers offer direct subscription packages that bundle hardware, software, and support. This demand-side shift is most prominent in the small and medium-sized enterprise segment in North America.
Security and Surveillance Equipment Market Segmentation
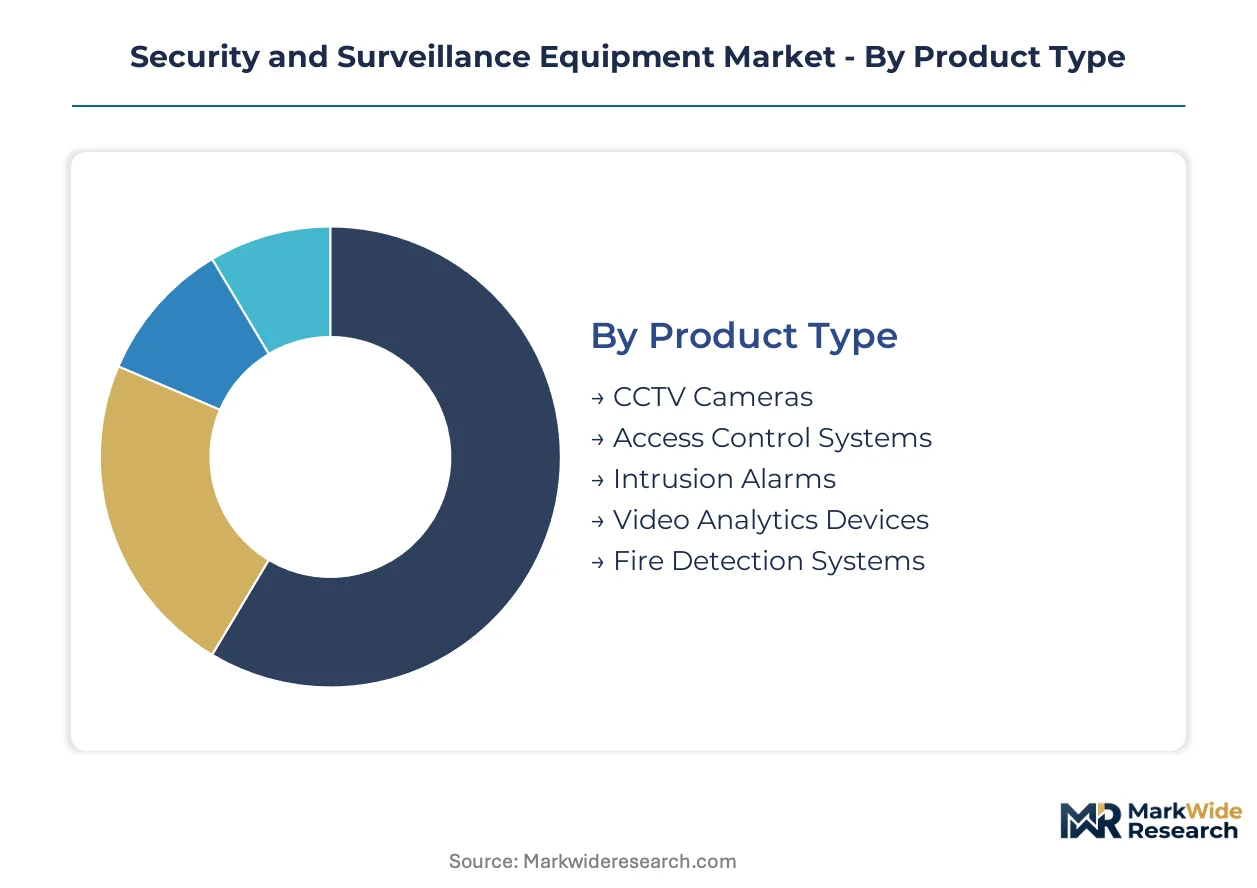
The Security and Surveillance Equipment Market is highly diversified, reflecting the varied needs of end-users across different sectors and geographies. Detailed segmentation clarifies the distinct product categories, technological advancements, application areas, and end-user demands that collectively define the market's structure and growth trajectories.
Product Type:
The product type segmentation reveals a spectrum from highly standardized hardware components to bespoke, integrated solutions tailored for specific security environments.
- CCTV Cameras:High-resolution digital cameras capture video footage for continuous monitoring and forensic analysis. Demand from critical infrastructure projects in India drives upgrades to advanced IP-based systems.
- Access Control Systems:Electronic systems manage entry and exit points using credentials like cards, biometrics, or mobile devices. Commercial facilities in Europe require robust integration for GDPR-compliant data handling.
- Intrusion Alarms:Sensors detect unauthorized entry, triggering alerts and notifications for both residential and commercial properties.
- Video Analytics Devices:Software and hardware analyze video streams for pattern recognition, object detection, and anomaly identification in public safety applications.
- Fire Detection Systems:Sensors identify smoke, heat, or flames, activating alarms and suppression systems to protect lives and assets in industrial settings.
Most installed capacity flows through CCTV Cameras. Expansion is steepest in Video Analytics Devices.
Technology:
The technology segmentation highlights the core innovations driving system capabilities and operational efficiencies across the security landscape.
- IP Cameras:Network-connected digital cameras transmit video over internet protocols, offering superior resolution, remote accessibility, and integrated analytics. Demand from commercial facilities in the US drives replacement of legacy analog systems.
- Cloud-based Platforms:Hosted services provide remote storage, management, and analytics for surveillance data, enabling scalable and flexible deployment models. Small and medium-sized enterprises in North America adopt these for subscription-based security.
- Thermal Imaging:Sensors detect heat signatures, enabling visibility in low-light or obscured conditions for perimeter security and industrial monitoring applications.
- Wireless Sensors:Battery-powered devices transmit data wirelessly, simplifying installation and expanding deployment possibilities for remote monitoring in diverse environments.
- Biometric Scanners:Devices authenticate identity using unique physical characteristics like fingerprints, facial recognition, or iris patterns for high-security access control.
The shift towards modern architectures primarily relies on IP Cameras, with Cloud-based Platforms seeing rapid integration.
Application:
The application segmentation illustrates how diverse sector-specific requirements shape the deployment and feature sets of security solutions.
- Critical Infrastructure:Facilities vital for national security and economy, such as power plants, data centers, and utilities, demand multi-layered security with advanced video analytics and access control. Regulatory mandates in Europe for data protection influence system design in these sensitive areas.
- Transportation Hubs:Airports, seaports, and railway stations require extensive surveillance for passenger safety, traffic management, and asset protection. Integrated security platforms are a significant contributor to market demand in these complex environments.
- Banking & Financial Services:Institutions require robust surveillance for asset protection, fraud prevention, and regulatory compliance in their branches and data centers.
- Commercial Facilities:Office buildings, warehouses, and retail spaces deploy systems for property security, operational monitoring, and employee safety.
- Educational Institutions:Schools and universities utilize surveillance for campus safety, emergency response, and access control to protect students and staff.
Dominant demand originates from Commercial Facilities, while Critical Infrastructure presents substantial growth opportunities.
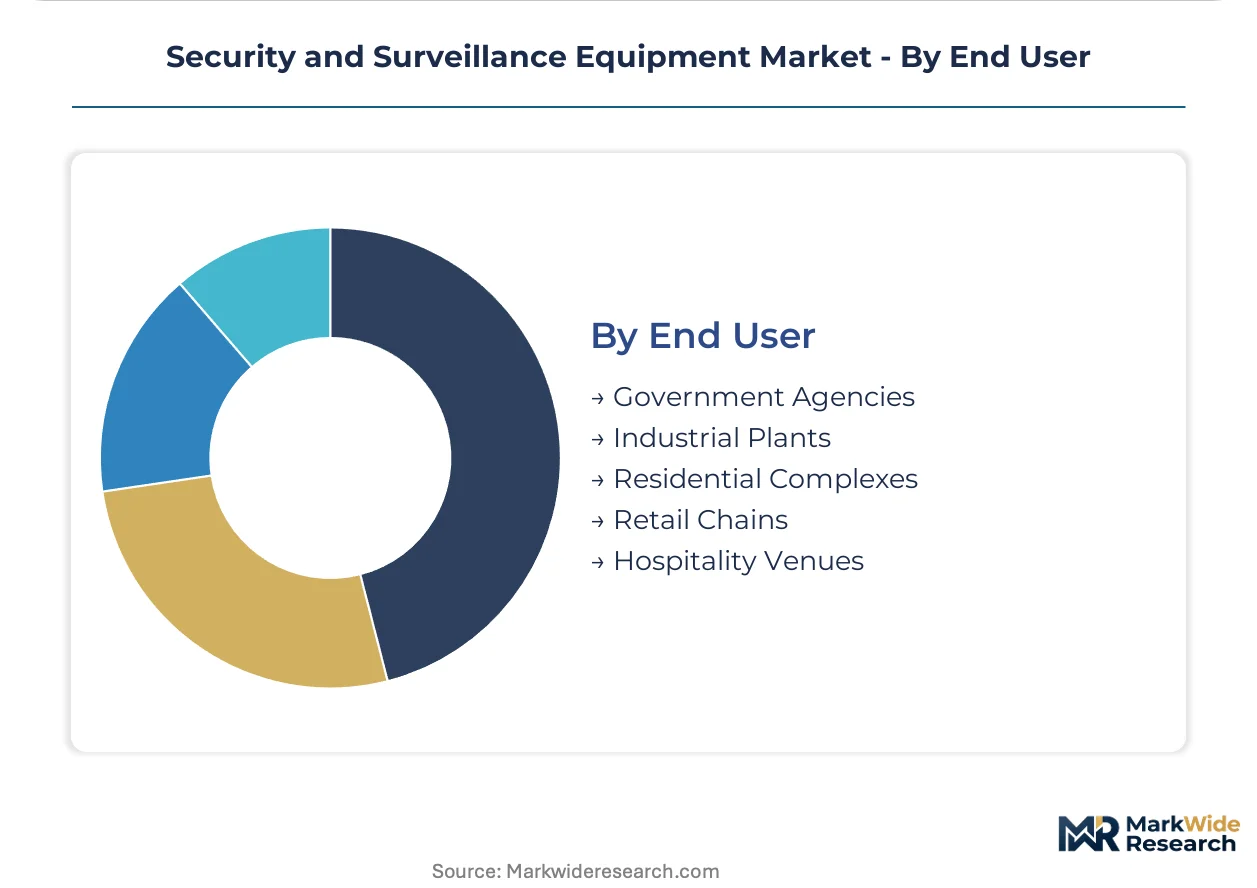
End User:
The end user segmentation differentiates solutions based on organizational scale, operational context, and budgetary considerations for security investments.
- Government Agencies:Public sector entities, including federal and local authorities, procure systems for public safety, border control, and facility protection. The US National Defense Authorization Act restricts procurement of specific foreign-made equipment for federal use.
- Industrial Plants:Manufacturing facilities and processing plants utilize surveillance for operational monitoring, safety compliance, and asset security. High-resolution cameras and video analytics support process optimization in these environments.
- Residential Complexes:Multi-dwelling units, gated communities, and individual homes install systems for occupant safety and property protection.
- Retail Chains:Stores deploy surveillance for loss prevention, customer flow analysis, and employee safety across multiple locations.
- Hospitality Venues:Hotels, resorts, and entertainment complexes use security equipment for guest safety, property management, and access control.
Volume is primarily driven by Industrial Plants, with Residential Complexes expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While India's urban infrastructure projects drive demand for integrated surveillance systems, the United States market navigates procurement restrictions. European nations prioritize data protection mandates for security equipment, shaping product design and deployment. Meanwhile, China's extensive manufacturing capabilities influence global supply chains.
India
India's smart city initiatives create recurring demand for integrated traffic management and public safety solutions. The government's focus on urban infrastructure projects, including large-scale surveillance deployments, underpins market expansion. Major urban centers like Mumbai and Delhi are spearheading the adoption of advanced IP-based systems for public security.
United States
The United States market sees demand from commercial facilities upgrading to modern IP camera systems. The US National Defense Authorization Act (NDAA) restricts federal procurement of specific foreign-made equipment. Technology hubs in California and Texas drive innovation in video analytics and cloud-based security platforms.
Germany
Germany's critical infrastructure sectors require sophisticated video analytics and access control integration. Compliance with the EU's GDPR is mandatory for surveillance systems handling personal data. Industrial regions like North Rhine-Westphalia are adopting advanced monitoring solutions for operational safety and asset protection.
China
China's market benefits from large-scale manufacturing capabilities and extensive urban surveillance projects. National GB standards dictate technical specifications for security and surveillance equipment. Manufacturing hubs in Shenzhen and Guangzhou are central to the production and innovation of advanced camera and sensor technologies.
Security and Surveillance Equipment Market Key Industry Players
Chinese producers anchor one tier of the security and surveillance equipment market, while specialized European and North American firms hold distinct positions. The market structure exhibits fragmentation, with diverse integrators and cloud-native providers emerging alongside established hardware manufacturers. Key strategic archetypes include large-scale component suppliers, open-platform solution providers, and integrated hardware-software platform vendors. Competitive moves focus on portfolio diversification and strategic partnerships to address evolving customer needs.
Within the large-scale manufacturing archetype, Dahua Technology, a China-based entity, exemplifies high-volume production capabilities for surveillance hardware. Axis Communications, a European-based firm, represents the open-platform IP solutions segment, catering to diverse integrators. Meanwhile, Verkada, a US-based company, occupies a position as a cloud-native integrated hardware and software platform provider, targeting enterprise clients seeking simplified management. These companies anchor different segments of the market, reflecting varied approaches to product development and market access.
| Leading Market Players |
|---|
| Dahua Technology |
| Pelco |
| Hanwha Vision |
| Avigilon |
| Panasonic i-PRO |
| Axis Communications |
| Bosch Security |
| Verkada |
| Hikvision |
| Others |
Cost & Logistics Intelligence
The rapid adoption of cloud-based platforms and edge AI processing is simultaneously reshaping cost economics and concentrating supply in software-centric ecosystems. This technological evolution influences both the production architecture and the pricing strategies across the security and surveillance equipment market.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity hardware components. Project-based pricing dominates large infrastructure deployments, while VSaaS subscription models emerge for small and medium-sized enterprises. Price differentiation stems from resolution capabilities and cybersecurity certifications. Pricing softness reflects intense competition among high-volume manufacturers, making small and medium-sized enterprises particularly price-sensitive.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns manage the flow of security equipment globally. Supply concentration centers on China for high-volume hardware and on Taiwan for critical semiconductor chips. The market draws from specialized optical lenses and robust storage components. Restrictive trade policies, like the US National Defense Authorization Act, pose a significant structural risk. Downstream distribution runs through a network of system integrators and, increasingly, direct-to-customer cloud service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Security and Surveillance Equipment Market is now a late-cycle quality story, as demand shifts toward integrated, AI-powered solutions with stringent data protection specifications.
For Market Incumbents:Cement leadership by deepening integration of AI analytics into existing hardware platforms. Focus R&D on explainable AI features to meet evolving regulations like the EU AI Act. This mitigates the threat from cloud-native providers offering simplified management. Investment in robust cybersecurity certifications across product lines is a crucial lever for maintaining trust and market share.
For New Entrants and Emerging Players:AI-powered video analytics offers a technology-first wedge into underserved vertical markets. Target specialized applications in retail analytics or industrial process monitoring, which are currently underpenetrated. A subscription-based VSaaS model provides a compelling go-to-market angle for small and medium-sized enterprises seeking simplified, cost-effective security solutions.
For Investors and Strategic Acquirers:Valuations sit cheapest among hardware-centric manufacturers facing intense commoditization pressure. The long-term viability favors firms with strong recurring revenue from cloud-native platforms or proprietary AI intellectual property. Acquisition targets should prioritize specialized software firms offering advanced video analytics or robust data governance solutions. The signal to watch is the accelerated adoption of cloud-based access control systems in enterprise environments.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Cloud-native access control platform | This expands recurring revenue streams and unifies security management for enterprise clients. |
| Platform Integration: AI-powered video analytics | This enhances proactive threat detection and operational intelligence for critical infrastructure. |
| Strategic Partnership: Cybersecurity certification | This builds trust and ensures compliance with evolving regulatory mandates like GDPR. |
| Acquisition of Specialist Firm: Edge AI technology | This embeds real-time processing capabilities directly into cameras, reducing network load. |
| Geographic Expansion: Smart city initiatives in India | This captures large-scale, recurring demand from government-led urban infrastructure projects. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, secondary market reports, and regulatory documents — were reconciled to build a comprehensive view. The study engaged security integrators, IT procurement managers, facility security directors, and smart city planners. Secondary validation drew from public company financial filings, industry association analyses, and technology standard publications (e.g., China's GB standards). This approach ensured robust bottom-up and top-down triangulation.
Data-stream reconciliation informed the analytical framework used to project market trajectories. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends, market drivers, and projected technology adoption rates across the analysis window. Urbanization rates in emerging markets and evolving cybersecurity spending trends served as key industry-specific forecast inputs.
The model holds under current geopolitical stability and technological development trajectories; deviation in trade policies or rapid AI regulatory shifts would shift forecast outcomes. Forecasts reflect assumptions documented in the full report. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Global Traveler Security Services Market
Security and Surveillance
Europe People Screening Market
Security and Surveillance
North America Security Screening Market
Security and Surveillance
Riot Control System Market
Security and Surveillance
Smart Security in Healthcare Market
Security and Surveillance
Security Inspection Market
Security and Surveillance
Global Corporate Travel Security Market
Security and Surveillance
Lawful Interception Market
Security and Surveillance
Middle East and Africa Cargo Inspection Market
Security and Surveillance
Intelligent Fencing Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Urban Security Screening Market
Security and Surveillance
Global Adaptive Security Market
Security and Surveillance
North America People Screening Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Europe Security Assurance Market