
 Global Police and Law Enforcement Equipment Market | 2026-2036
Global Police and Law Enforcement Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Police and Law Enforcement Equipment Market Outlook
Polymer composites are hardening protective equipment economics as aramid and ultra-high-molecular-weight polyethylene displace older ceramic inserts in body armor plates. Axon Enterprise leverages integrated software-hardware ecosystems to dominate the digital evidence management space. Motorola Solutions anchors critical communication infrastructure through Project 25 and LTE-based public safety networks. Safariland differentiates via modular holster platforms and duty gear customization for specialized tactical units.
Police and law enforcement equipment encompasses protective garments, less-lethal and lethal weapons, biometric identification systems, and encrypted radio networks engineered to NIJ ballistic resistance standards and FCC emission protocols for interoperable emergency response. Forensic analysis technology within the technology segment is capturing margin pools as DNA sequencing speed and digital evidence authentication become procurement priorities for criminal investigation applications. Communication equipment maintains mature revenue stability while robotics and unmanned ground systems represent the fastest-expanding technology category for bomb disposal and reconnaissance missions.
The U.S. Department of Justice, the European Union's CE marking framework under MDR, and India's BIS certification requirements collectively dictate product compliance trajectories across protective equipment and electronic surveillance categories. The EU AI Act introduces additional algorithmic transparency mandates for facial recognition and predictive policing platforms that will reshape vendor development roadmaps. Stakeholders must monitor divergence between U.S. state-level facial recognition moratoriums and federal procurement standards to anticipate demand fragmentation in surveillance systems.
Market Dynamics
Polymer composite armor plates and AI-enabled surveillance systems are restructuring procurement priorities across municipal and federal agencies, forcing vendors to reconfigure R&D roadmaps around NIJ ballistic standards and algorithmic transparency mandates.
Growth Catalysts
- EU AI Act Compliance:Algorithmic transparency requirements for facial recognition and predictive policing platforms are generating replacement demand for legacy surveillance infrastructure across German and French municipal police forces.
- Body-Worn Camera Mandates:U.S. state-level legislation requiring officer-worn recording devices is expanding hardware procurement and associated cloud storage subscriptions for evidence management.
- Aramid Fiber Advances:Next-generation para-aramid weaves are reducing plate weight by thirty percent versus traditional ceramic inserts, accelerating adoption among tactical response units.
Market Restraints
- Raw Material Concentration:Ultra-high-molecular-weight polyethylene fiber production concentrates in U.S. and Dutch chemical complexes, exposing armor manufacturers to single-source vulnerability.
- CE Marking Timeline:MDR recertification requirements for protective equipment are extending product approval cycles by eighteen to twenty-four months for European market entry.
- Budget Cyclicality:Municipal police department capital expenditure depends on annual appropriations processes that compress during fiscal tightening periods.
Strategic Opportunities
- Indian Internal Security Expansion:Central Armed Police Forces modernization programs under Ministry of Home Affairs directives are opening procurement channels for non-lethal systems and encrypted communications.
- Drone Integration:Unmanned ground vehicles for bomb disposal and hostage reconnaissance represent underpenetrated application space with limited incumbent specialization.
- FCC Narrowbanding Mandate:Legacy radio system obsolescence deadlines are forcing wholesale infrastructure replacement across U.S. county sheriff departments.
Industry Challenges
- Forensic Technician Shortage:DNA analysis and digital evidence authentication require specialized laboratory personnel that police departments struggle to recruit and retain.
- Interoperability Fragmentation:Project 25 standards compliance varies across manufacturer implementations, complicating multi-agency emergency response coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Police and Law Enforcement Equipment Market |
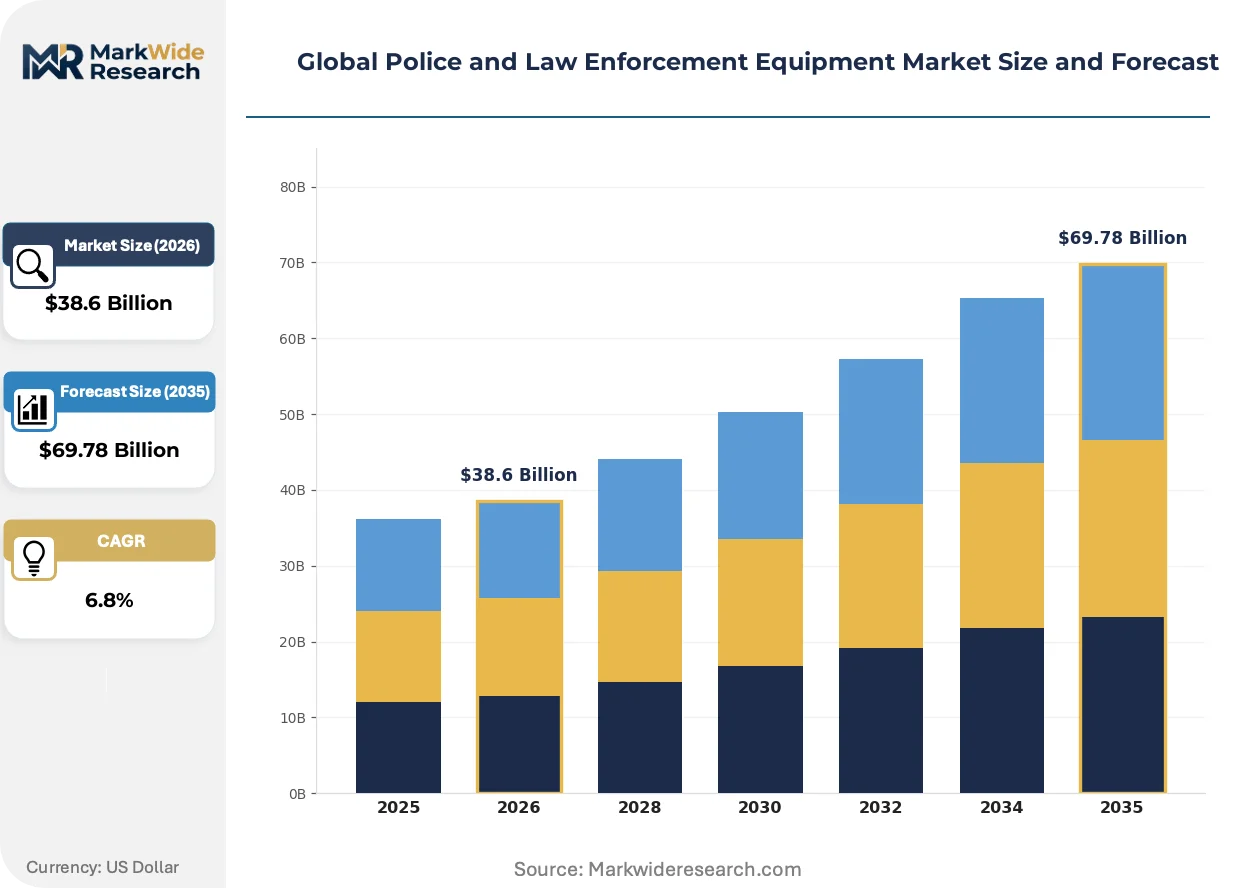
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Armor, Firearms, Surveillance Systems, Communication Equipment Technology: Digital Communication, Forensic Analysis, Data Management, Robotics End User: Municipal Police, Federal Agencies, Private Security, National Guard Application: Crowd Control, Criminal Investigation, Public Safety, Traffic Enforcement |
| Companies Covered | Axon Enterprise Inc., Motorola Solutions Inc., Safariland LLC, 3M, Combined Systems Inc., Digital Ally Inc., Avon Polymer Products Ltd., Streichers Inc., General Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Police and Law Enforcement Equipment Market Strategic Shifts
Real-time biometric identification and edge-computing surveillance nodes are compressing incident response timelines while complicating data governance frameworks for evidence chain-of-custody requirements.
Edge AI processors embedded within body-worn cameras are integrating on-device facial recognition and threat classification without cloud latency. State highway patrol agencies in Texas and Florida are piloting these units for traffic stop safety protocols. This architecture is integrating localized decision-making that reduces bandwidth costs and accelerates officer situational awareness.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of water-repellent treatments for duty uniforms and tactical gear. German textile suppliers are accelerating fluorine-free alternatives to maintain CE marking eligibility. Protective garment manufacturers serving European markets are absorbing reformulation costs and extending supplier qualification timelines.
Subscription-based evidence management platforms are displacing perpetual-license software models among mid-sized police departments. Cloud storage tiering and automated redaction tools now anchor vendor competitive positioning. This transition is most visible in U.S. municipal contracts where operating expenditure budgets exceed capital allocation flexibility.
Global Police and Law Enforcement Equipment Market Segmentation
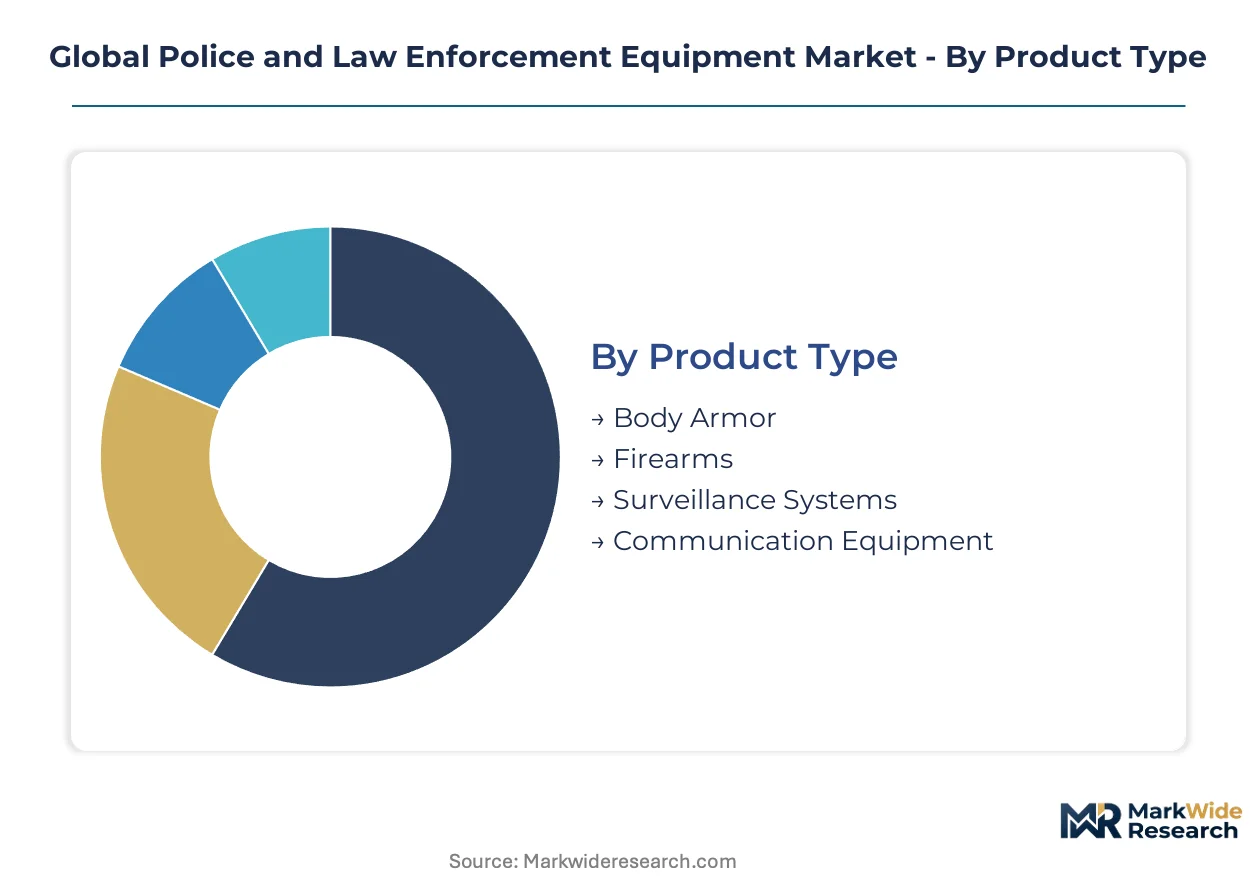
Equipment procurement in law enforcement diverges sharply across agency tiers and operational mandates. Technical specifications, certification requirements, and budget cycles create distinct demand profiles that vendors must navigate separately.
Product Type:
Ballistic protection specifications and surveillance platform architectures define procurement evaluation criteria across municipal and federal buyers.
- Body Armor:Polymer composite plates utilizing ultra-high-molecular-weight polyethylene and para-aramid weaves achieve NIJ Level III and IV ratings at reduced weight versus legacy ceramic inserts. Demand concentrates among U.S. tactical response units where mobility requirements conflict with protection mandates, driving replacement cycles as fiber advances mature.
- Surveillance Systems:AI-enabled facial recognition nodes and edge-computing cameras integrate real-time biometric matching with localized threat classification. German and French municipal police forces are replacing legacy infrastructure to satisfy EU AI Act algorithmic transparency requirements, generating compliance-driven procurement waves.
- Firearms:Lethal weapons procurement follows military specification standards with modular platform architectures dominating federal agency selection.
- Communication Equipment:Project 25 and LTE-based public safety networks anchor critical infrastructure with FCC narrowbanding mandates forcing county-level replacement cycles.
Mature deployment sits with Communication Equipment. Newer deployment is concentrated in Surveillance Systems.
Technology:
Software-hardware integration intensity separates margin profiles across technology categories, with cloud-native architectures commanding subscription economics.
- Digital Communication:Encrypted radio networks and interoperable broadband systems serve as backbone infrastructure for multi-agency emergency response. India's Central Armed Police Forces modernization programs under Ministry of Home Affairs directives are expanding procurement channels for next-generation encrypted communications.
- Data Management:Cloud-based evidence storage platforms with automated redaction and chain-of-custody authentication are displacing perpetual-license software among U.S. mid-sized police departments where operating expenditure flexibility exceeds capital allocation.
- Forensic Analysis:DNA sequencing acceleration and digital evidence authentication tools capture expanding laboratory budgets.
- Robotics:Unmanned ground vehicles for bomb disposal and hostage reconnaissance represent underpenetrated application space with limited incumbent specialization and steepest expansion trajectory.
Established integration sits with Digital Communication. Capability investment is accelerating fastest in Robotics.
End User:
Budget authority and procurement cycle predictability determine vendor go-to-market resource allocation across agency categories.
- Municipal Police:Annual appropriations processes govern capital expenditure with body-worn camera mandates in Texas and Florida driving hardware and cloud subscription procurement. State-level facial recognition moratoriums create demand fragmentation that complicates vendor standardization efforts.
- Federal Agencies:Multi-year procurement schedules and classified specification requirements favor established contractors with security clearance infrastructure. FBI and Homeland Security equipment standards propagate through grant programs to state and local counterparts.
- National Guard:Dual civil-military mission profiles require equipment compatibility with both domestic law enforcement and combat theater specifications.
- Private Security:Commercial guard services and corporate protection units operate outside regulatory procurement frameworks with cost-driven selection criteria.
Procurement volume concentrates with Municipal Police. Specification complexity peaks with Federal Agencies.
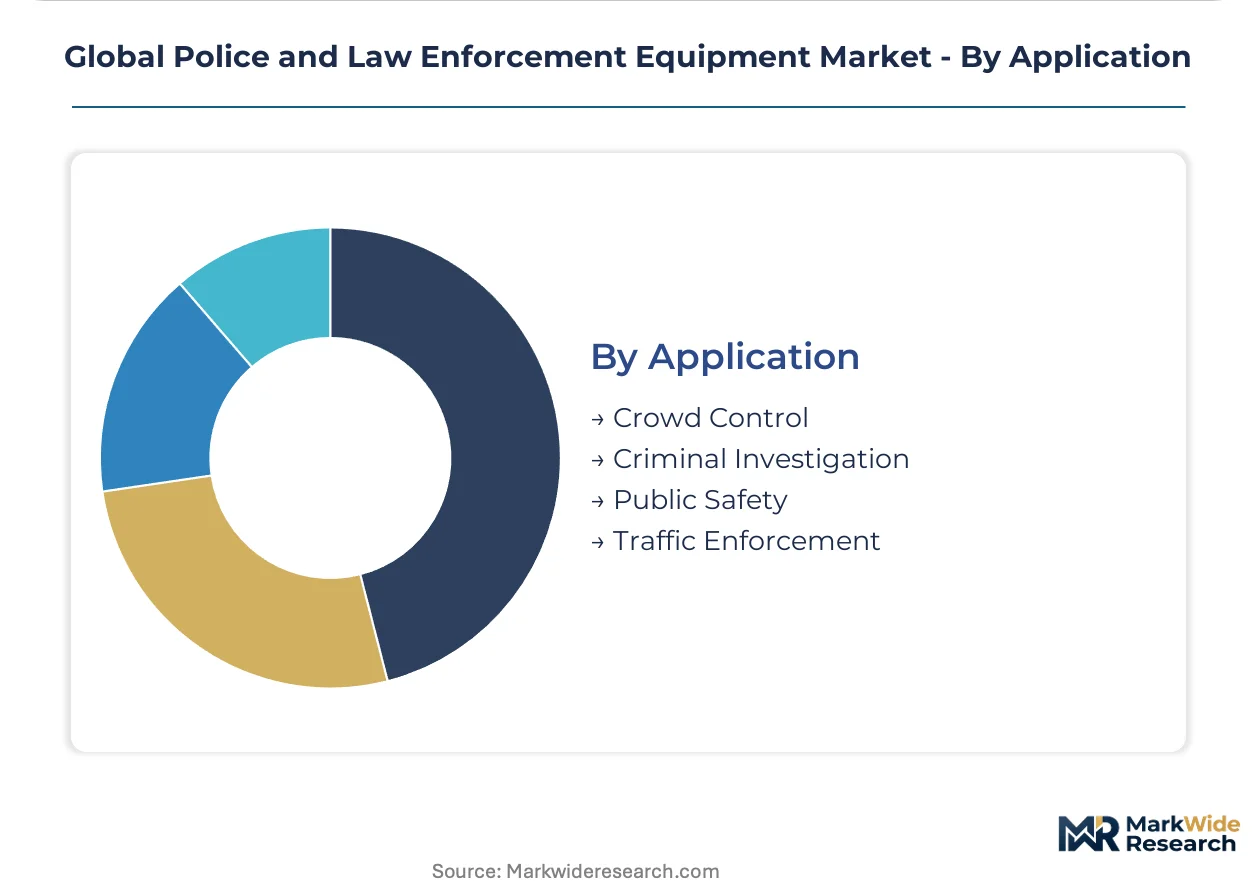
Application:
Operational tempo and evidentiary requirements shape equipment durability and data governance specifications.
- Criminal Investigation:Forensic evidence collection and laboratory analysis demand chain-of-custody documentation and specialized technician training that police departments struggle to staff and retain.
- Public Safety:Patrol and emergency response operations require ruggedized equipment with interoperable communication standards across jurisdictional boundaries.
- Crowd Control:Less-lethal systems and protective formations deploy against civil disturbance scenarios with liability exposure driving non-lethal technology investment.
- Traffic Enforcement:Highway patrol agencies pilot edge-AI body-worn cameras for traffic stop safety protocols, integrating on-device threat classification without cloud latency.
Equipment standardization is most advanced in Public Safety. Technology refresh cycles are shortest in Traffic Enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Tamil Nadu are concentrating polymer composite manufacturing for ballistic protection, drawing fiber suppliers and armor fabricators into integrated production corridors.
United States
State-level body-worn camera mandates in Texas and Florida are accelerating hardware procurement cycles. FCC narrowbanding deadlines for legacy radio systems are forcing county sheriff departments into infrastructure replacement programs. The Dallas-Fort Worth metroplex hosts clustered integration facilities for Project 25 communication networks serving municipal agencies.
Germany
EU AI Act compliance requirements are generating replacement demand for facial recognition infrastructure across municipal police forces. MDR recertification timelines are extending protective equipment approval cycles by eighteen to twenty-four months. Stuttgart's industrial corridor anchors polymer composite R&D for next-generation para-aramid weaves reducing plate weight.
India
Central Armed Police Forces modernization programs under Ministry of Home Affairs directives are opening procurement channels for non-lethal systems and encrypted communications. BIS certification requirements dictate product compliance trajectories for protective equipment categories. The Delhi-NCR cluster concentrates domestic assembly operations for tactical gear serving internal security applications.
France
Algorithmic transparency mandates for predictive policing platforms are reshaping vendor development roadmaps for surveillance systems. CE marking frameworks under MDR govern European market entry for protective garments and electronic equipment. The Lyon-Grenoble corridor hosts specialized facilities for forensic analysis technology serving criminal investigation laboratories.
United Kingdom
GDPR-aligned data governance frameworks are complicating evidence chain-of-custody requirements for cloud-based storage platforms. National Police Chiefs' Council procurement standards propagate equipment specifications through regional constabularies. Greater Manchester's technology corridor concentrates digital evidence management software development for mid-sized municipal departments.
Global Police and Law Enforcement Equipment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated software-hardware ecosystems commanding premium positioning in digital evidence management while component fabricators compete on fiber specification and ballistic certification. The vendor base organizes into three tiers: full-stack platform providers, modular subsystem specialists, and commodity protective equipment suppliers. Dominant competitive moves include strategic partnerships for interoperability certification and geographic expansion into Indian internal security procurement channels.
Within the platform-provider tier, Axon Enterprise and Motorola Solutions exemplify integrated ecosystem architectures that bind hardware procurement to recurring software subscriptions. Safariland occupies a position among modular equipment specialists serving tactical response units with customizable duty gear configurations. These three companies represent contrasting archetypes—cloud-native platform dominance, critical communication infrastructure anchoring, and specialized tactical customization—that collectively illustrate the market's segmentation between subscription economics and durable goods procurement.
| Leading Market Players |
|---|
| Axon Enterprise Inc. |
| Motorola Solutions Inc. |
| Safariland LLC |
| 3M |
| Combined Systems Inc. |
| Digital Ally Inc. |
| Avon Polymer Products Ltd. |
| Streichers Inc. |
| General Dynamics |
| Others |
Value Chain & Pricing Dynamics
NIJ certification tiers create a bifurcated market where Level IV polymer composite plates command substantial premiums over Level IIIA soft armor, with that performance gap manifesting in both unit economics and supply chain sourcing patterns. Subscription-based evidence management platforms from Axon Enterprise and Motorola Solutions capture recurring revenue streams that commodity protective equipment vendors cannot replicate, while raw material concentration in U.S. and Dutch chemical complexes constrains pricing flexibility for armor manufacturers.
Pricing Analysis
High-volume municipal procurement of body-worn cameras generates thin hardware margins that vendors offset through cloud storage subscriptions and software tiers. Price differentiation hinges on NIJ ballistic certification grade and after-sales service bundling, with Level IV plates carrying substantial premiums over Level IIIA equivalents. Cost compression in soft armor segments is intensifying because REACH-compliant fluorine-free textile treatments extend supplier qualification timelines. Federal agencies exhibit the lowest price sensitivity due to multi-year procurement schedules, while private security contractors drive commoditization in duty gear categories.
Supply Chain Analysis
Freight costs for ultra-high-molecular-weight polyethylene fiber shipments from U.S. and Dutch production hubs to Asian armor fabricators add meaningful landed cost premiums for Indian Central Armed Police Forces procurement. Raw material sourcing draws from para-aramid weaves, ceramic substrate precursors, and edge-AI processor chipsets. Single-source vulnerability concentrates in fiber production, where DSM and Honeywell anchor global capacity. Distribution runs through defense contractors with security clearance infrastructure for federal channels, and direct municipal sales forces for body-worn camera deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market structure rewards vertical integration into polymer composite fiber production and cloud-native software stacks, with upstream control over UHMWPE supply and downstream ownership of evidence management subscriptions emerging as the decisive competitive moats.
For Market Incumbents: To counter algorithmic transparency mandates from the EU AI Act, Axon Enterprise and Motorola Solutions should deepen in-house production of edge-AI processors for body-worn cameras while acquiring forensic authentication startups to lock in laboratory workflow integration. Certification investment in BIS compliance for Indian Central Armed Police Forces procurement channels provides defensive positioning against emerging domestic competitors. For New Entrants and Emerging Players: Direct-to-municipal SaaS sales models offer the lowest customer acquisition cost pathway into evidence management, where mid-sized police departments in Texas and Florida exhibit acute procurement flexibility constraints. Unmanned ground vehicles for bomb disposal represent the most penetrable application space, with limited incumbent specialization and steepest expansion trajectory. Targeting state-level facial recognition moratoriums as compliance consulting entry points builds relationships ahead of federal standardization. For Investors and Strategic Acquirers: Re-rating potential sits with modular equipment specialists given consolidation pressure from full-stack platform providers. Long-term viability over a five-to-ten year window favors vendors with captive fiber supply and recurring software revenue above sixty percent of total mix. The signal to watch is BIS certification timeline compression for Indian market entry, which would validate geographic diversification thesis for protective equipment categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Captive UHMWPE supply from DSM and Honeywell complexes insulates margin pressure from raw material concentration. |
| Platform Integration | Axon Enterprise's evidence.com ecosystem binds hardware procurement to recurring cloud subscriptions with high switching costs. |
| CE Marking Pathway Acceleration | MDR recertification timeline reduction opens European protective equipment market entry eighteen months faster than competitors. |
| Geographic Expansion | Delhi-NCR assembly operations for tactical gear capture Indian Central Armed Police Forces modernization procurement channels. |
| Strategic Partnership | Project 25 interoperability certification with Motorola Solutions anchors county sheriff department infrastructure replacement programs. |
Study Parameters
Document review covered SEC 10-K filings from Axon Enterprise and Motorola Solutions, EU AI Act implementation guidance, and BIS certification protocols, complemented by interviews with municipal police procurement officers, federal grant administrators, ballistic testing laboratory directors, and polymer composite R&D leads. Secondary validation drew from NIJ compliance databases, FCC narrowbanding mandate documentation, and Indian Ministry of Home Affairs modernization directives. Bottom-up equipment shipment data triangulated against top-down internal security budget appropriations.
Segment-level projections across product type, technology, end user, and application dimensions were generated through driver-based modeling over the projection horizon. CAGRs were derived from regression analysis against defense and internal security expenditure trends, with specific inputs including NIJ standard revision timelines and REACH restriction implementation schedules for fluorine-free textile treatments.
Inputs from municipal police departments and federal procurement offices were available through the study window; gaps in classified specification requirements for tactical response units introduce uncertainty bands around robotics and unmanned ground system adoption trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Security Product Integration Services Market
Security and Surveillance
Manned Guarding Services Market
Security and Surveillance
Asia-Pacific Security Screening Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
X-Ray Security Screening System Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Russian Intelligent Eavesdropping Detection System Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
India CCTV Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market
Security and Surveillance
Urban Security Screening Market
Security and Surveillance
Explosive Detection Technology Market