
 Asia-Pacific Security Services Market | 2026-2036
Asia-Pacific Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Security Services Market Insights
The Asia-Pacific security services market is restructuring around a widening capability gap between premium integrated platforms and commoditized guard-replacement monitoring. Palo Alto Networks leverages its cloud-native architecture to dominate cybersecurity service layers for large enterprises. Wipro Limited anchors its regional position through managed security operations centers that blend Indian engineering scale with local-language incident response across ASEAN markets.
Asia-Pacific security services encompass the design, installation, monitoring, and maintenance of systems that protect physical assets, personnel, data, and networks against unauthorized access, intrusion, theft, or disruption, typically integrating sensor arrays, biometric authentication modules, and encrypted communication protocols with centralized command platforms. The primary purpose spans crime deterrence, regulatory compliance, business continuity assurance, and operational risk reduction across facilities and digital infrastructure. Managed services and cloud security deployments are capturing disproportionate margin expansion as recurring-revenue models displace one-time hardware sales, while biometrics integration within access control systems is maturing fastest in South Korean and Japanese commercial real estate portfolios where fingerprint and facial recognition have become standard lobby fixtures.
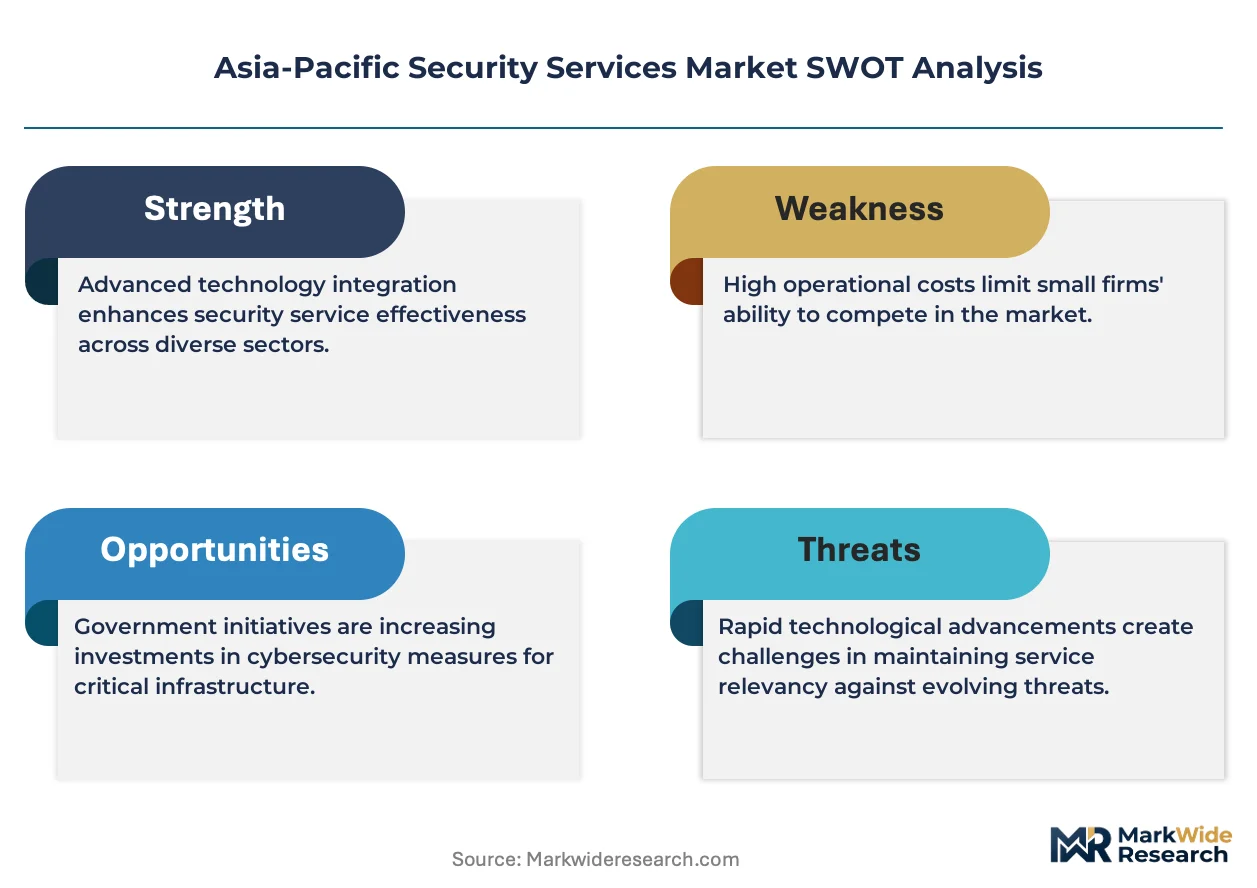
Japan's METI cybersecurity framework, Australia's Security of Critical Infrastructure Act, and India's CERT-In directives collectively shape product certification requirements and cross-border data handling rules that vendors must satisfy before securing government and regulated industry contracts. Compliance costs are filtering smaller regional integrators out of contention for national-level tenders, concentrating procurement among providers with dedicated regulatory affairs teams across multiple jurisdictions. Stakeholders must weigh whether to build in-house compliance capabilities or partner with established local license holders as certification fragmentation deepens across the region.
Market Dynamics
Physical-cyber convergence is compressing procurement cycles across Asia-Pacific security services, as facility operators abandon siloed guard contracts for unified threat management platforms that fuse perimeter sensors with network monitoring dashboards.
Growth Catalysts
- Australia's Security of Critical Infrastructure Act:Mandatory security programs for ports and energy facilities are forcing asset owners into multi-year managed service agreements with integrated physical-digital providers.
- Data center construction boom:Hyperscale cloud operators in Singapore and Sydney are specifying biometric access control and 24/7 remote monitoring as standard procurement terms for new builds.
- India's PLI scheme for electronics:Manufacturing incentives are drawing foreign security technology providers into domestic joint ventures, expanding local production of surveillance cameras and access control modules.
Market Restraints
- Semiconductor supply concentration:Image sensor and edge AI chip fabrication concentrates in Taiwan and South Korea, exposing integrators to single-source disruption risks.
- Cross-border data localization mandates:Australia's TGA, India's CERT-In, and Japan's METI impose conflicting data residency requirements that fragment cloud security architecture costs.
- Skilled technician scarcity:Biometric system calibration and encrypted protocol configuration require certified engineers that remain concentrated in Seoul, Tokyo, and Bangalore labor pools.
Strategic Opportunities
- Indonesia's underpenetrated commercial real estate:Jakarta and Surabaya office stock lacks integrated access control, creating first-mover advantage for biometric lobby systems.
- AI-video analytics convergence:Behavioral recognition algorithms layered onto existing camera networks enable predictive threat detection without full hardware replacement.
- Vietnam's manufacturing zone expansion:Industrial park developers in Bac Ninh and Hai Phong are mandating perimeter intrusion detection for foreign tenant leases.
Industry Challenges
- Multi-jurisdiction certification timelines:Vendors seeking Australian government contracts must simultaneously satisfy TGA security guidelines and state-level procurement rules, extending qualification periods.
- Legacy analog system integration:Banking and logistics facilities across Thailand and Malaysia operate hybrid environments where coaxial camera feeds must interface with IP-based command platforms.
- Cyber-physical breach liability ambiguity:Insurers in Singapore and Hong Kong lack standardized actuarial models for converged security incidents, complicating client risk transfer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Security Services Market |
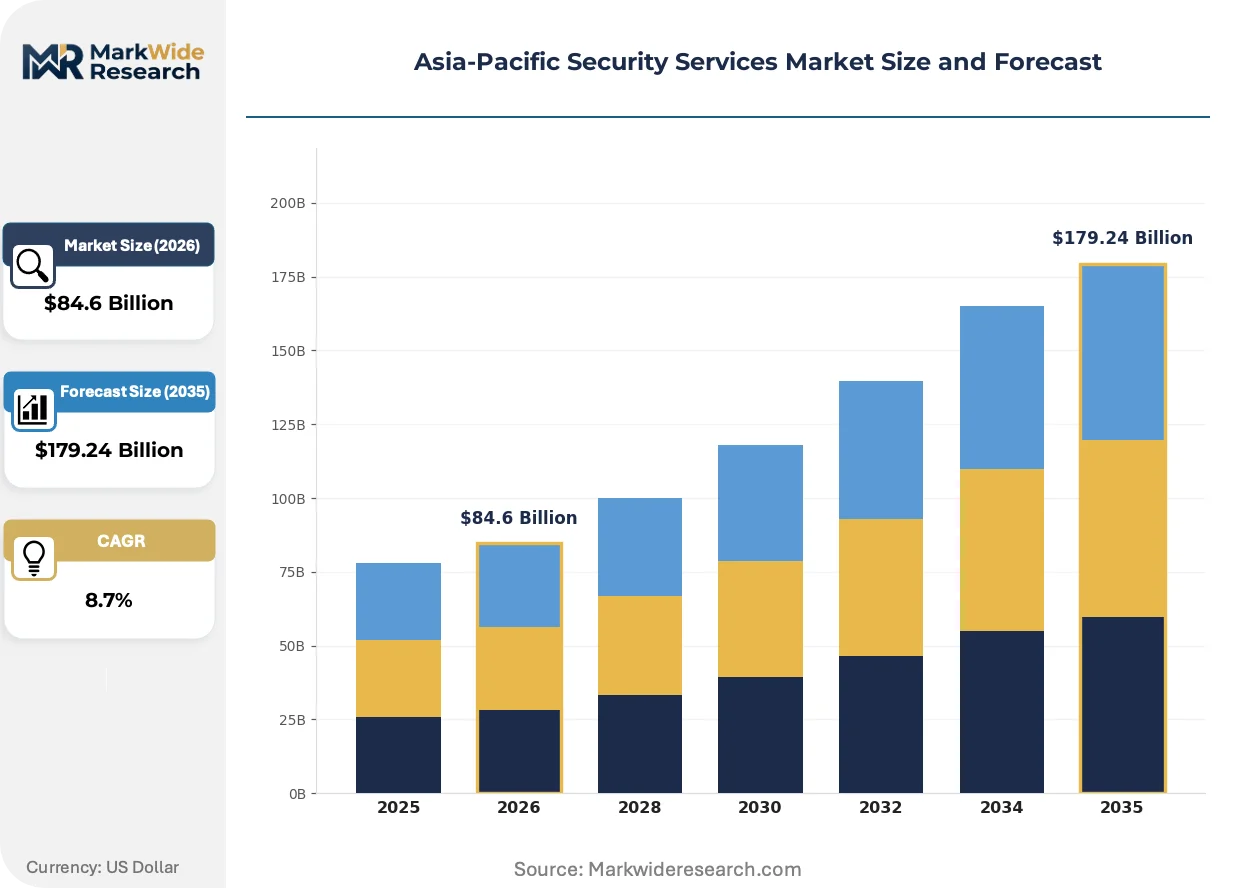
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $179.24 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Access Control, Alarm Monitoring, Video Surveillance, Cybersecurity End User: Government, Commercial, Residential, Industrial Technology: Biometrics, IoT Security, RFID, Cloud Security Deployment Model: On-premises, Managed Services, Hybrid, Remote Monitoring |
| Companies Covered | Broadcom Inc., IBM Corporation, Palo Alto Networks, Microsoft Corporation, Cisco Systems Inc., NEC Corporation, Fortinet Inc., Wipro Limited, Kaspersky Lab, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Security Services Market Trends and Innovations
Edge computing architectures are redistributing processing load from centralized data centers to perimeter devices, enabling real-time threat response without bandwidth dependency on cloud backhauls.
Computer vision algorithms embedded in thermal and optical cameras are integrating on-device analytics for crowd density monitoring and abandoned object detection. Singapore Changi Airport and Sydney Metro have deployed these systems for automated anomaly alerting. The shift is compressing response latency from minutes to seconds while reducing transmission costs for high-resolution video streams.
Japan's METI cybersecurity framework now mandates third-party penetration testing for critical infrastructure operators, forcing vendors to maintain certified red-team capabilities. Industrial consequence includes mandatory security audit budgets in utility procurement specifications. Power generation and water treatment facilities in Osaka and Nagoya are restructuring vendor selection criteria around demonstrated compliance documentation.
Subscription-based managed detection and response is displacing capital-intensive on-premise security operations center builds among mid-market enterprises. Australian healthcare networks and Philippine BPO operators are adopting per-endpoint pricing models that convert fixed security infrastructure costs into operational expenditures. This procurement pattern is most visible in Melbourne and Manila where CFOs prioritize cash flow flexibility over asset ownership.
Asia-Pacific Security Services Market Segmentation
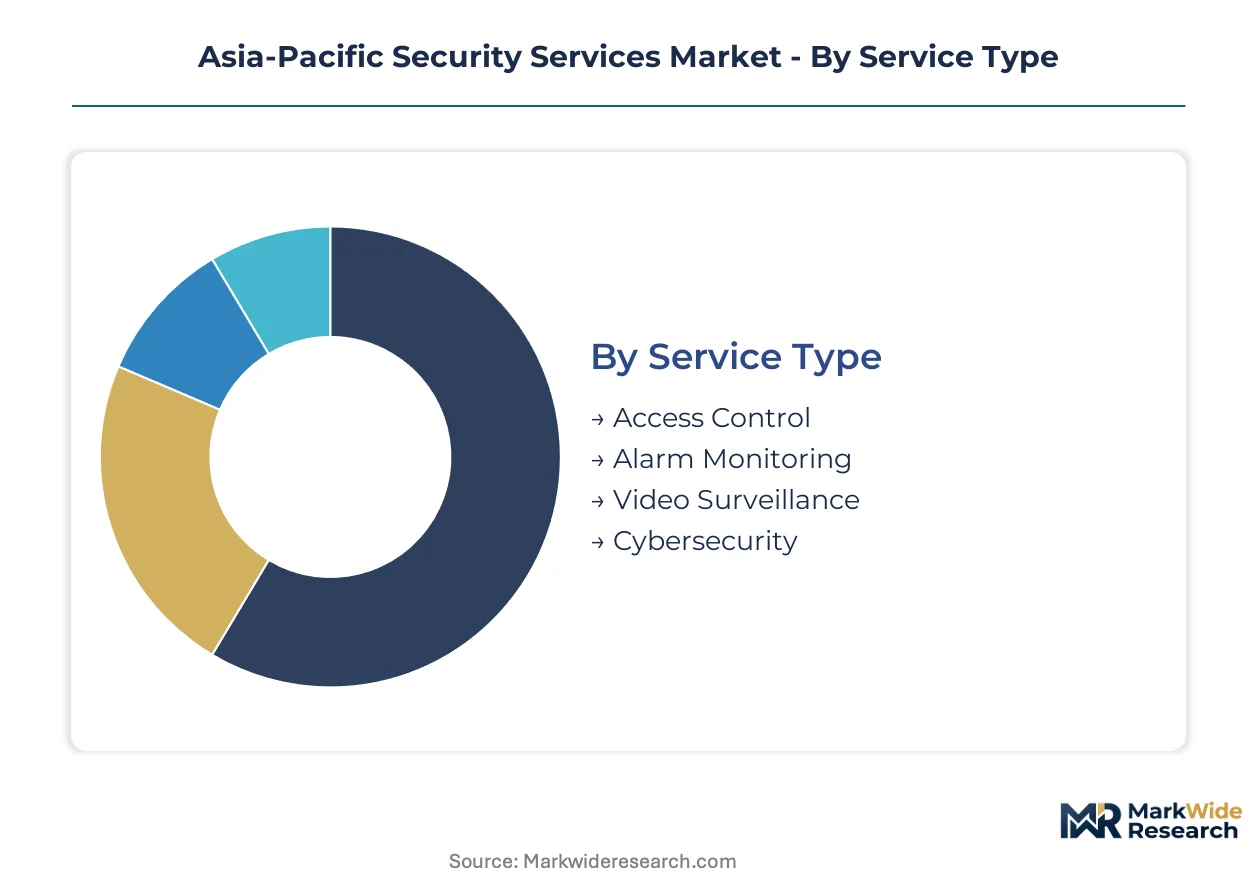
Security services procurement across Asia-Pacific fragments across four intersecting dimensions that determine pricing architecture and vendor selection criteria. Service type and deployment model together shape capital expenditure profiles, while end-user verticals and technology choices dictate compliance burdens and integration complexity. Understanding these segment boundaries clarifies why integrated platforms command premium positioning against point-solution competitors.
Service Type:
Customization intensity varies sharply across this category, with biometric-integrated systems requiring site-specific engineering while alarm monitoring standardizes into repeatable service tiers.
- Access Control:Biometric readers, smart card systems, and mobile credential platforms form the core hardware layer. Demand concentrates in Singapore and Sydney data centers where hyperscale operators mandate multi-factor authentication for cage entry, driven by Australia's Security of Critical Infrastructure Act compliance deadlines.
- Alarm Monitoring:Central station services process intrusion, fire, and environmental alerts through 24/7 operator desks. Australian ports and energy facilities are consolidating fragmented guard contracts into multi-year managed monitoring agreements under federal mandatory security program requirements.
- Video Surveillance:Camera networks with edge analytics for facial recognition and behavioral detection.
- Cybersecurity:Network monitoring, endpoint protection, and threat intelligence services.
Most installed capacity flows through Video Surveillance. Expansion is steepest in Cybersecurity.
End User:
Procurement sophistication scales with regulatory exposure, separating government and critical infrastructure buyers from price-sensitive residential segments.
- Government:Federal, state, and municipal facilities requiring cleared personnel and certified systems. India's defense and railway sectors are expanding perimeter hardening contracts under domestic procurement preferences, though semiconductor supply constraints delay sensor deployment timelines.
- Commercial:Banking, healthcare, and corporate office portfolios. South Korean commercial real estate in Seoul and Busan has standardized fingerprint and facial recognition lobby systems, driven by tenant expectations and insurance premium reductions.
- Residential:Smart home security and apartment building access systems.
- Industrial:Manufacturing plants, warehouses, and logistics hubs.
Government verticals absorb the highest per-site expenditure. Commercial accounts are gaining share fastest.
Technology:
Technology maturity determines integration cost, with biometrics and cloud security requiring specialized engineering while RFID commoditizes into plug-and-play modules.
- Biometrics:Fingerprint, facial recognition, iris scan, and vein pattern authentication. Japanese commercial real estate in Tokyo and Osaka has achieved near-universal biometric lobby deployment, with METI cybersecurity framework mandates accelerating replacement of legacy card systems.
- IoT Security:Sensor network protection and device authentication protocols. Vietnam's manufacturing zone expansion in Bac Ninh and Hai Phong is driving demand for industrial IoT perimeter monitoring as foreign tenant lease terms mandate connected intrusion detection.
- RFID:Radio-frequency identification for asset tracking and access credentials.
- Cloud Security:Data protection, identity management, and secure access service edge.
Biometrics carries the highest installed base. Cloud Security is climbing the fastest.
Deployment Model:
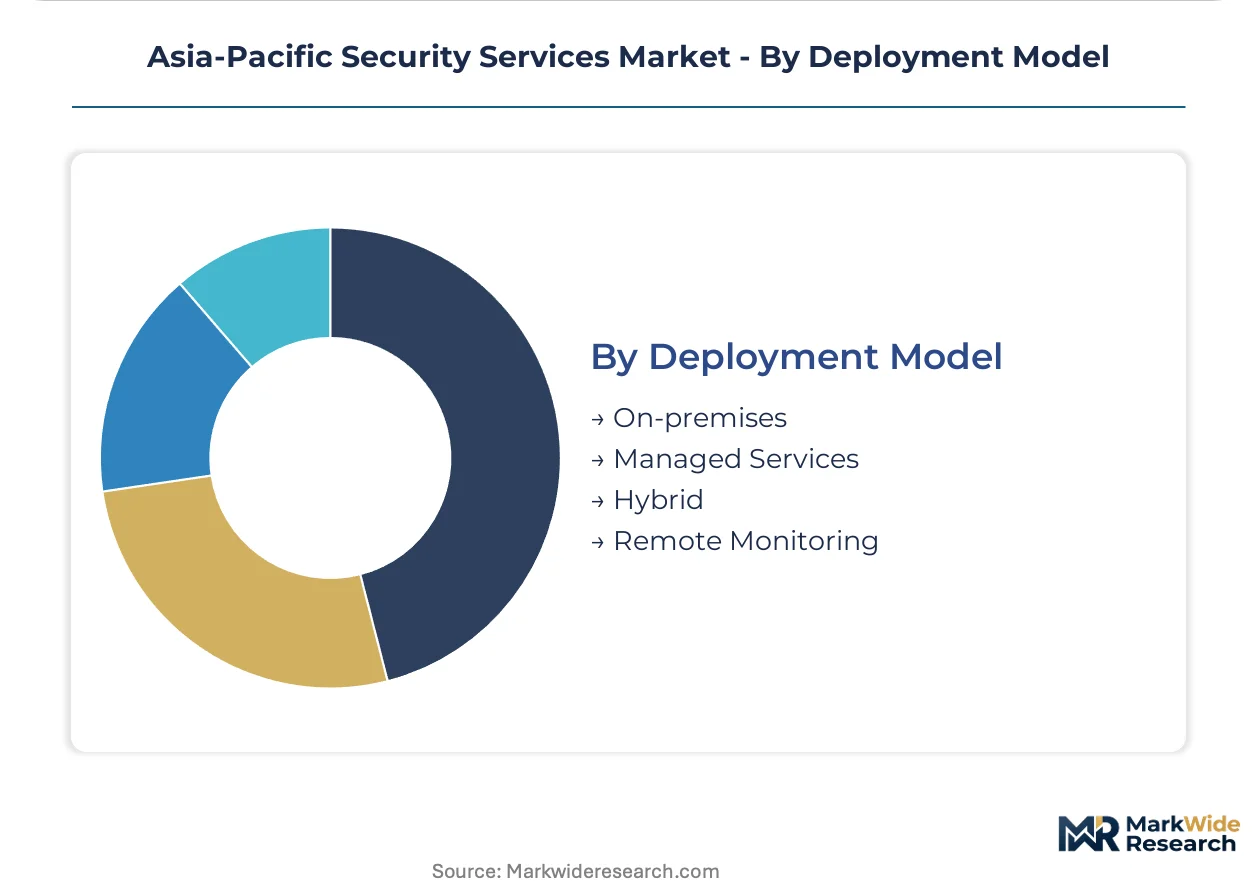
Capital availability and internal IT capacity divide buyers between asset-heavy on-premises builds and operational-expenditure-focused managed alternatives.
- On-premises:Dedicated hardware and software operated within client facilities. Australian healthcare networks in Melbourne retain on-site security operations centers for patient data sovereignty compliance, constrained by TGA data localization requirements that prohibit cloud transmission of certain record categories.
- Managed Services:Outsourced monitoring, maintenance, and incident response. Philippine BPO operators in Manila are converting fixed security infrastructure costs to per-endpoint subscription pricing, prioritizing cash flow flexibility over asset ownership.
- Hybrid:Mixed on-site and cloud-resident security infrastructure.
- Remote Monitoring:Off-site operator desks and virtual guarding services.
Managed Services dominates new contract value. Hybrid architectures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's critical infrastructure protection spending outpaces Indonesia's commercial real estate security penetration by a wide margin, reflecting divergent regulatory maturity across the region. Japan and South Korea anchor high-end biometric adoption, while India and Vietnam drive volume expansion through manufacturing incentives and industrial zone development.
Australia
Federal funding for port hardening and energy facility protection dominates procurement, with mandatory security programs under the Security of Critical Infrastructure Act forcing multi-year managed service agreements. The TGA imposes data localization requirements that constrain cloud security architecture for healthcare networks. Melbourne retains on-site security operations centers for patient data sovereignty compliance.
Japan
METI cybersecurity framework mandates now require third-party penetration testing for critical infrastructure operators, restructuring vendor selection criteria around demonstrated compliance documentation. Commercial real estate in Tokyo and Osaka has achieved near-universal biometric lobby deployment. Power generation and water treatment facilities in Nagoya are accelerating replacement of legacy card systems.
India
PLI scheme incentives for electronics manufacturing are drawing foreign security technology providers into domestic joint ventures, expanding local production of surveillance cameras and access control modules. Defense and railway sectors are expanding perimeter hardening contracts under domestic procurement preferences. Semiconductor supply constraints delay sensor deployment timelines in Delhi-Mumbai industrial corridors.
Singapore
Hyperscale cloud operators specify biometric access control and 24/7 remote monitoring as standard procurement terms for new data center builds. Changi Airport has deployed computer vision systems with on-device analytics for automated anomaly alerting. Financial services procurement concentrates on multi-factor authentication for cage entry in digital infrastructure facilities.
Vietnam
Manufacturing zone expansion in Bac Ninh and Hai Phong is driving demand for industrial IoT perimeter monitoring as foreign tenant lease terms mandate connected intrusion detection. Industrial park developers are specifying perimeter intrusion detection for foreign tenant leases. Security procurement remains price-sensitive compared to regional peers, favoring standardized over customized solutions.
Asia-Pacific Security Services Market Competitive Landscape
Top-tier vendors anchor integrated physical-cyber platforms, while mid-tier regional integrators compete on price-sensitive guard-replacement monitoring. The vendor base stratifies across three capability bands: cloud-native cybersecurity specialists, managed security operations providers with engineering scale, and hardware-focused surveillance equipment manufacturers. Consolidation pressures are filtering smaller regional integrators out of national-level tenders. Dominant competitive moves include strategic partnerships for regulatory compliance coverage and portfolio diversification into converged threat management platforms.
Within the cybersecurity specialist tier, Palo Alto Networks and Fortinet occupy positions defined by cloud-native architecture dominance for large enterprise accounts. Wipro Limited exemplifies the managed services archetype, leveraging Indian engineering scale with local-language incident response capabilities across ASEAN markets. NEC Corporation anchors the integrated hardware-software segment, representing Japanese vendors with established critical infrastructure compliance documentation. These three companies collectively illustrate the capability gaps that separate premium integrated platforms from commoditized monitoring alternatives.
| Leading Market Players |
|---|
| Broadcom Inc. |
| IBM Corporation |
| Palo Alto Networks |
| Microsoft Corporation |
| Cisco Systems Inc. |
| NEC Corporation |
| Fortinet Inc. |
| Wipro Limited |
| Kaspersky Lab |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up security service specialists across Australia and Singapore are consolidating fragmented guard-replacement monitoring contracts into unified managed service platforms, compressing procurement costs while extracting subscription-based pricing premiums from critical infrastructure operators. This ownership pattern concentrates pricing discipline among integrated providers with dedicated regulatory affairs teams, filtering price-sensitive regional integrators from national-level tenders.
Pricing Analysis
The bundled-vs-unbundled service split separates premium integrated physical-cyber platforms from commoditized point solutions. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade and after-sales service intensity. Pricing pressure stems from semiconductor supply constraints in Taiwan and South Korea that delay sensor deployment and compress margins on hardware-dependent contracts. Government and critical infrastructure buyers exhibit lowest price sensitivity due to mandatory compliance deadlines, while Indonesian commercial real estate developers drive hardest bargain on standardized access control modules.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Singapore and Sydney data center operators, while systems integrators serve mid-market commercial accounts across ASEAN markets. Component fabrication concentrates in Taiwan, South Korea, and China for image sensors, edge AI chips, and biometric modules. Raw material dependencies include rare earth elements for magnet assemblies, gallium arsenide for optical components, and high-purity silicon for sensor substrates. Single-source vulnerability in Taiwan semiconductor foundries exposes integrators to disruption risks. Distribution runs through authorized dealer networks in Japan and Australia, direct enterprise sales in India, and project-based contracting in Vietnam's industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia-Pacific security services rests on cloud-native managed detection and response displacing capital-intensive on-premise builds, converting fixed infrastructure costs into recurring operational expenditures for mid-market buyers.
For Market Incumbents: Acquire certified red-team capabilities and compliance documentation libraries to satisfy Japan's METI third-party penetration testing mandates and Australia's Security of Critical Infrastructure Act qualification requirements. Consolidate fragmented guard contracts into multi-year managed service agreements before emerging cloud-native cybersecurity specialists capture critical infrastructure accounts. Backward integration into edge AI chip sourcing through South Korean and Taiwanese partnerships mitigates single-source semiconductor exposure. For New Entrants and Emerging Players: The mid-tier price-point gap between Palo Alto Networks premium cybersecurity platforms and commoditized alarm monitoring services creates entry space for specialized biometric-integrated access control providers. Target Indonesia's underpenetrated Jakarta and Surabaya office stock with standardized fingerprint and facial recognition lobby systems before incumbent integrators establish local presence. Vietnam's Bac Ninh and Hai Phong manufacturing zones offer white-space for industrial IoT perimeter monitoring mandated in foreign tenant lease terms. Go-to-market through industrial park developers rather than direct tenant sales accelerates volume accumulation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional integrators with established local license holdings across multiple ASEAN jurisdictions but lacking cloud-native platform capabilities. Long-term viability favors providers with recurring-revenue managed service models over hardware-dependent project businesses. Acquisition target archetype: Australian or Japanese compliance-heavy specialists with critical infrastructure customer relationships and underdeveloped cybersecurity service layers. Signal to watch is CERT-In and METI certification fragmentation deepening procurement concentration among multi-jurisdiction license holders.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Certification | METI, TGA, and CERT-In multi-jurisdiction documentation enables national-level tender participation in Japan, Australia, and India. |
| Cloud-Native Platform Migration | Subscription-based managed detection and response converts fixed security infrastructure costs to operational expenditures for Philippine BPO and Australian healthcare networks. |
| Biometric System Integration | Fingerprint and facial recognition lobby deployment captures South Korean and Japanese commercial real estate standardization trends. |
| Joint Venture Localization | India's PLI scheme partnerships expand domestic production of surveillance cameras and access control modules for defense and railway sectors. |
| Edge Computing Architecture | On-device analytics at Singapore Changi Airport and Sydney Metro compress response latency from minutes to seconds while reducing bandwidth costs. |
Research Methodology
Direct dialogue with security operations center directors, critical infrastructure protection officers, regulatory compliance leads, and systems integration engineers across Australia, Japan, India, Singapore, and Vietnam grounded qualitative findings. Secondary validation drew from METI cybersecurity framework documentation, Australia's Security of Critical Infrastructure Act regulatory filings, India's PLI scheme electronics manufacturing incentive records, and hyperscaler data center procurement disclosures. Bottom-up service provider revenue aggregation and top-down regional security expenditure estimates were triangulated to anchor market sizing.
Segment-level outputs across service type, deployment model, end-user vertical, and technology choice were generated through structured modeling across the projection horizon. CAGRs were derived from regression analysis against macroeconomic indicators, regulatory implementation timelines, and capital expenditure patterns in data center construction and critical infrastructure hardening. Forecast inputs incorporated biometric adoption curves in commercial real estate, cloud security penetration rates among mid-market enterprises, and semiconductor supply availability constraints affecting sensor deployment timelines.
The model assumes a particular technology adoption path; alternative pathways for edge AI and behavioral recognition algorithms would alter the outlook if on-device processing costs fall faster than projected. Forecasts reflect base-case assumptions regarding regulatory enforcement intensity, cross-border data localization mandate harmonization, and sovereign funding continuity for critical infrastructure protection. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
APAC Security Testing Market
Security and Surveillance
Shock Sensor Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
Sirens Market
Security and Surveillance
Global Police and Law Enforcement Equipment Market
Security and Surveillance
Intrusion Alarm System Market
Security and Surveillance
Smart Security Market
Security and Surveillance
Prescriptive Security Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
Explosive Detection Technology Market
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
Europe Rockfall Radar Market
Security and Surveillance
India CCTV Market
Security and Surveillance
Private Security Market
Security and Surveillance
Narcotics Scanner Market
Security and Surveillance
Global Wireless Monitoring and Surveillance Market