
 Smoke and Carbon Monoxide Alarm Market | 2026-2036
Smoke and Carbon Monoxide Alarm Market Size, Share, and Industry Trends Forecast 2026-2036
Smoke and Carbon Monoxide Alarm Market Analytics
The capital-intensity gap between semiconductor-capable smart-alarm producers and legacy hardware assemblers is collapsing as IoT module costs fall below the threshold where scale economies matter. First Alert leverages its retail channel dominance to sustain volume leadership in big-box home improvement chains. Kidde anchors its position through backward integration into ionization chamber manufacturing, while X-Sense competes aggressively on direct-to-consumer pricing through e-commerce platforms.
Smoke and carbon monoxide alarms are electromechanical safety devices combining optical or ionization smoke sensors with electrochemical CO cells, designed to detect combustion particulates and toxic gas accumulation before lethal exposure occurs. Photoelectric alarms now lead the product type category due to superior smoldering-fire detection and reduced false-alarm rates versus ionization designs, though dual-sensor units command premium positioning where code mandates maximum sensitivity. Smart alarms represent the fastest-expanding technology segment as Wi-Fi and Z-Wave connectivity enable remote monitoring and insurance-premium discounts, while traditional battery-powered units retain volume dominance in price-sensitive residential replacement cycles.
The National Fire Protection Association's NFPA 72 standards, the European Union's Construction Products Regulation with CE marking requirements, and China's GB 20517 national standard collectively shape product design, testing protocols, and market access across the three largest demand centers. These frameworks mandate interconnection capability, end-of-life signaling, and specific response-time thresholds that disqualify non-compliant imports and accelerate replacement cycles. Stakeholders must monitor evolving smart-home interoperability mandates and insurance-industry incentive structures that increasingly tie premium reductions to connected alarm verification.
Market Dynamics
The residential retrofit wave is compressing replacement cycles as UL 217 Edition 8 and EN 54-7 certification deadlines force wholesale sensor redesigns, collapsing the performance gap between premium smart systems and legacy hardware.
Growth Catalysts
- Interconnection mandates:NFPA 72 requirements in the United States now compel wireless mesh capability in new construction, accelerating hardwired-to-smart conversions.
- Insurance premium incentives:Verified alarm response programs through major underwriters reward connected CO detection with rate reductions, pulling homeowners toward upgrade cycles.
- Photoelectric sensor dominance:Superior smoldering-fire sensitivity versus ionization designs is displacing legacy inventory across German and Chinese residential channels.
Market Restraints
- Electrochemical cell supply concentration:CO sensor membrane production clusters in East Asian specialty chemical suppliers, exposing assemblers to input volatility.
- Ionization chamber disposal friction:Americium-241 licensing requirements under EPA regulations impose end-of-life handling costs that deter budget-segment participation.
- Dual-sensor cost premium:Combining photoelectric and ionization elements in single housings raises bill-of-materials thresholds above mass-market price ceilings.
Strategic Opportunities
- Matter protocol convergence:Thread and Wi-Fi unification under CSA standards is fragmenting proprietary smart-home silos, opening interoperability plays for mid-tier hardware vendors.
- Rental housing compliance gaps:Underpenetrated multifamily inspection regimes in secondary US metropolitan areas present bulk-installation contracting channels.
- Voice-assistant integration:Alexa and Google Home alarm-status queries are creating new service-layer revenue streams beyond hardware margins.
Industry Challenges
- UL 217 smoke sensitivity testing:Revised polyurethane foam and smoldering-wood fire protocols extend certification timelines by 8-14 months for redesigned optical chambers.
- Legacy Z-Wave ecosystem fragmentation:500-series to 800-series controller transitions strand installed-base compatibility commitments, complicating product roadmaps.
- Electrochemical CO drift calibration:Field sensor degradation curves vary by ambient humidity and temperature, undermining predictive maintenance algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoke and Carbon Monoxide Alarm Market |
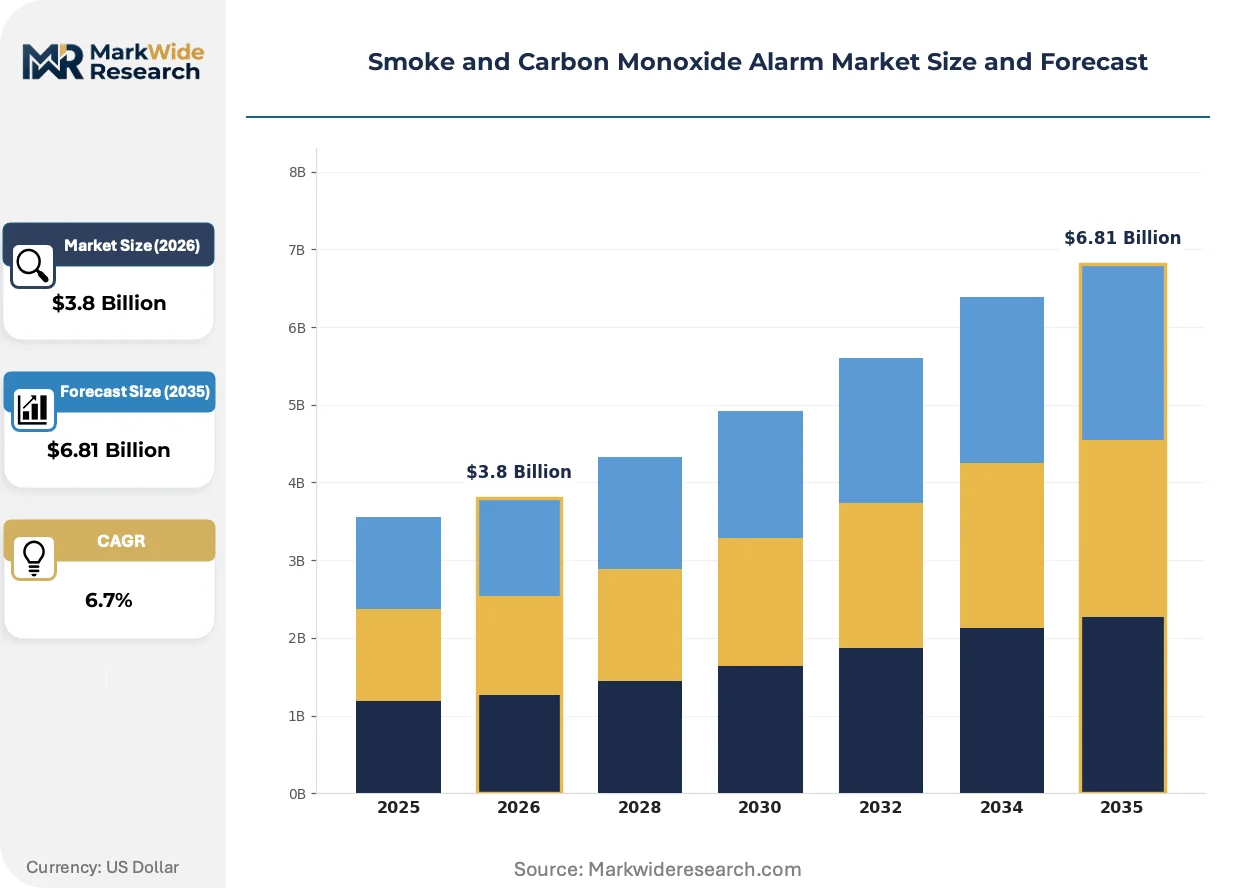
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photoelectric Alarms, Ionization Alarms, Dual-Sensor Alarms, Touchless Alarms Technology: Smart Alarms, Traditional Alarms, Wireless Alarms, Hardwired Alarms End User: Residential, Commercial, Industrial, Government Facilities Installation Type: Standalone, Integrated, Surface-Mounted, Ceiling-Mounted |
| Companies Covered | Nest, Universal Instruments, First Alert, OneLink, Abode, Kidde, Siterwell, SimpliSafe, X-Sense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoke and Carbon Monoxide Alarm Market Evolving Landscape
Connectivity integration and regulatory test-protocol evolution are compressing product lifecycles while fragmenting competitive advantage between sensor physics and software-layer service delivery.
Multi-criteria detection algorithms is fragmenting the traditional smoke-versus-CO device category. Advanced sensor fusion combines optical scatter patterns with electrochemical gas readings in single firmware stacks. Commercial landlords and property managers are adopting these units fastest, seeking consolidated maintenance contracts. The technology is fragmenting vendor specialization boundaries, forcing optical specialists to master gas-cell calibration and vice versa.
REACH substance restrictions on halogenated flame retardants in polymer housings are reshaping material selection across European supply chains. Manufacturers must reformulate ABS and polycarbonate blends to maintain UL 94 V-0 ratings without restricted brominated compounds. German and French distributors are prioritizing compliant inventory, squeezing non-adapted imports from secondary Asian suppliers.
Direct-to-consumer subscription monitoring is displacing traditional dealer-installed alarm networks. Homeowners now self-install Wi-Fi-enabled units and pay monthly fees for professional dispatch services, bypassing regional security contractors. This pattern concentrates in United States suburban markets where insurance discounts offset subscription costs, compressing traditional channel margins.
Smoke and Carbon Monoxide Alarm Market Segmentation
Segmentation in the smoke and carbon monoxide alarm market reveals how sensor physics, connectivity protocols, and installation constraints fragment procurement decisions across residential and commercial channels. Understanding these divides exposes where premium pricing power concentrates versus where commoditization pressures dominate.
Product Type:
Margin pools concentrate in dual-sensor and touchless configurations where certification complexity and patent positioning deter low-cost competition.
- Photoelectric Alarms:Optical scatter detection using infrared LED and photodiode chambers identifies smoldering combustion particles. UL 217 Edition 8 polyurethane foam testing protocols favor these units in United States residential retrofits where nuisance-alarm reduction drives replacement decisions.
- Ionization Alarms:Americium-241 ionization chambers detect fast-flaming fires through air conductivity changes. EPA licensing requirements for radioactive source disposal impose end-of-life handling costs that compress margins in budget-segment distribution through big-box retail channels.
- Dual-Sensor Alarms:Combined photoelectric and ionization elements in single housings address both smoldering and flaming fire types. German and Chinese building code enforcement is accelerating specification of these units in multifamily housing inspections.
- Touchless Alarms:Gesture-controlled hush functions and remote test capabilities reduce physical interaction requirements. Accessibility mandates in public facilities and aging-in-place residential retrofits are expanding addressable demand for these units.
The dominant share belongs to photoelectric alarms, while dual-sensor configurations are closing the gap fastest.
Technology:
Volume leadership remains with battery-powered traditional units, yet value capture is migrating toward connectivity-enabled segments where recurring revenue models supplement hardware margins.
- Smart Alarms:Wi-Fi and Z-Wave connectivity enable remote status monitoring, mobile notifications, and insurance-verified alarm response. United States suburban homeowners facing premium discount incentives are adopting these units fastest, though Matter protocol standardization is fragmenting proprietary ecosystem lock-in.
- Traditional Alarms:Standalone battery or AC-powered units without network connectivity dominate replacement cycles in price-sensitive channels. Retail shelf space concentration in home improvement chains sustains volume leadership despite technology obsolescence pressures.
- Wireless Alarms:RF-interconnected mesh networks satisfy NFPA 72 interconnection mandates without hardwired infrastructure. Rental housing compliance gaps in secondary United States metropolitan areas present bulk-installation contracting opportunities.
- Hardwired Alarms:AC-powered units with battery backup anchor new construction specifications where electrical code mandates permanent installation. Electrician labor integration and inspection scheduling create channel friction that slows upgrade cycles.
Traditional alarms retain the largest installed base, though smart alarms are expanding most quickly.
End User:
Procurement sophistication varies sharply across customer types, with commercial and government segments demanding consolidated maintenance contracts that favor multi-criteria detection platforms.
- Residential:Single-family and multifamily dwellings represent the volume foundation, driven by retrofit replacement cycles and insurance incentive structures. Homeowner self-installation of Wi-Fi-enabled units is displacing traditional dealer networks in United States suburban markets.
- Commercial:Office buildings, retail spaces, and hospitality properties require centralized monitoring integration and inspection documentation. Property managers are consolidating vendor relationships around maintenance-inclusive service contracts.
- Industrial:Manufacturing facilities and warehouses demand explosion-proof housings and extreme-temperature operating ranges. Process safety integration with building management systems distinguishes specification requirements.
- Government Facilities:Schools, hospitals, and military installations mandate compliance with federal procurement standards and disability access requirements. Extended warranty terms and domestic content preferences filter supplier eligibility.
Residential channels command the highest unit volumes, while commercial end users are driving specification upgrades fastest.
Installation Type:
Physical mounting constraints and system architecture choices determine whether alarms function as discrete safety devices or integrated building infrastructure components.
- Standalone:Self-contained units operating without interconnection to other alarms or central systems. Battery-powered configurations dominate landlord-installed minimum-compliance scenarios in underpenetrated rental housing markets.
- Integrated:Hardwired or wireless connection to security panels, building management systems, or central monitoring stations. Commercial landlords seeking consolidated maintenance contracts are specifying these configurations.
- Surface-Mounted:Wall or ceiling attachment without recessed electrical boxes, common in retrofit applications where running new conduit is cost-prohibitive. Aesthetic integration challenges limit premium residential adoption.
- Ceiling-Mounted:Recessed or surface installation at optimal smoke detection height per NFPA 72 placement guidelines. New construction specifications universally require this configuration, anchoring hardwired product demand.
Ceiling-mounted installations hold the dominant specification share, while integrated configurations are gaining traction fastest in commercial retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany and the United States where certification complexity and insurance-linked upgrade cycles sustain margin premiums, while cost-sensitive volume flows through Chinese manufacturing clusters serving domestic retrofit demand and export assembly.
United States
NFPA 72 interconnection mandates and verified alarm response programs through major underwriters are accelerating hardwired-to-smart conversions in suburban markets. The EPA enforces Americium-241 licensing requirements that impose end-of-life handling costs on ionization chamber disposal. Chicago and Dallas-Fort Worth metro areas exhibit concentrated demand for rental housing compliance bulk installations.
Germany
REACH substance restrictions on halogenated flame retardants are forcing housing reformulation in ABS and polycarbonate blends for CE-marked products. EN 54-7 certification deadlines are displacing legacy ionization inventory through accelerated replacement cycles. The Rhine-Ruhr industrial corridor anchors specialty chemical supply for electrochemical CO sensor membranes.
China
GB 20517 national standard enforcement is tightening building code compliance in tier-one city residential construction. The Ministry of Ecology and Environment oversees dual carbon goals that shape polymer housing material selection. Shenzhen and Dongguan manufacturing clusters dominate IoT module assembly for smart alarm export production.
United Kingdom
Construction Products Regulation with CE marking requirements and evolving smart-home interoperability mandates are filtering non-compliant imports from secondary Asian suppliers. London and Southeast England concentrate property management demand for consolidated maintenance contracts around multi-criteria detection platforms.
Japan
METI standards for connected device cybersecurity and JIS certification protocols are extending product development timelines for Wi-Fi-enabled units. The Kanto region around Tokyo anchors demand for aging-in-place residential retrofits with touchless alarm configurations.
Smoke and Carbon Monoxide Alarm Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with semiconductor-capable smart-alarm producers competing against legacy hardware assemblers on divergent capability vectors. The market structure consolidates around three tiers: retail-channel dominators leveraging big-box shelf space, direct-to-consumer e-commerce specialists compressing price points, and integrated safety platform vendors bundling hardware with subscription monitoring. Dominant competitive moves include backward integration into sensor component manufacturing and strategic partnerships around Matter protocol interoperability.
Within the retail-channel tier, First Alert and Kidde occupy positions anchored by volume relationships with home improvement chains and captive supply of ionization chamber components. X-Sense exemplifies the direct-to-consumer archetype, competing aggressively on e-commerce pricing through platform-native distribution models.
| Leading Market Players |
|---|
| Nest |
| Universal Instruments |
| First Alert |
| OneLink |
| Abode |
| Kidde |
| Siterwell |
| SimpliSafe |
| X-Sense |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for electrochemical CO sensor membranes lock in both supply access and price visibility for alarm assemblers, insulating them from East Asian specialty chemical volatility while compressing margin buffers for non-integrated competitors.
Pricing Analysis
The customization-premium spread between standard battery-powered units and configured-to-order smart systems with Z-Wave or Matter protocol support runs wide. Three-tier pricing structure across premium, standard, and economy levels reflects UL 217 Edition 8 certification grade and insurance-verified connectivity status. Cost compression in economy-tier standalone units is intensifying because direct-to-consumer e-commerce specialists compress price points below big-box retail thresholds. Residential retrofit homeowners exhibit highest price sensitivity, while commercial property managers purchasing maintenance-inclusive service contracts show lowest.
Supply Chain Analysis
Inbound logistics costs through the Shenzhen-Dongguan corridor to Los Angeles and Rotterdam gateways shape landed cost structures for IoT module assembly. Electrochemical cell membrane production clusters in China, Japan, and Germany, drawing from palladium catalyst and fluoropolymer membrane inputs. Single-source vulnerability concentrates in Americium-241 ionization chamber supply under EPA licensing requirements. Distribution runs through home improvement chain retail, direct-to-consumer e-commerce platforms, and bulk-installation contracting channels serving rental housing compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smoke and carbon monoxide alarm markets sit in early-cycle expansion as UL 217 Edition 8 and EN 54-7 certification deadlines force wholesale sensor redesigns and accelerate replacement cycles.
For Market Incumbents: Secure backward integration into photoelectric optical chamber manufacturing to defend against semiconductor-capable smart-alarm producers collapsing the performance gap. Anchor retail shelf space dominance through exclusive big-box partnerships while investing in Matter protocol certification to neutralize proprietary ecosystem threats from Nest and SimpliSafe. For New Entrants and Emerging Players: Professional monitoring service-layer gaps in multifamily rental housing compliance present the most penetrable white-space target. Secondary United States metropolitan areas with underpenetrated inspection regimes offer bulk-installation contracting opportunities. Voice-assistant integration partnerships with Alexa and Google Home provide a differentiated go-to-market angle bypassing traditional dealer networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Wi-Fi-enabled smart alarm vendors with subscription monitoring services. Five-to-ten year viability favors mid-tier hardware vendors with Matter protocol interoperability and consolidated maintenance contract relationships with commercial landlords. Watch insurance-industry incentive structures tying premium reductions to connected alarm verification as the inflection indicator for mass-market adoption acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Thread and Wi-Fi unification under CSA standards fragments proprietary smart-home silos. |
| Backward Integration into Sensor Manufacturing | In-house optical chamber production insulates margins from electrochemical cell supply volatility. |
| Subscription Monitoring Service Launch | Professional dispatch services bypass regional security contractors and capture recurring revenue. |
| Rental Housing Bulk Installation Contracting | Chicago and Dallas-Fort Worth metro areas concentrate underpenetrated compliance demand. |
| Voice-Assistant Platform Partnership | Alexa and Google Home alarm-status queries create service-layer revenue beyond hardware. |
Research Methodology
Desk research of UL certification databases, NFPA 72 standard documentation, and building code enforcement records preceded structured interviews with product development directors at alarm manufacturers, procurement managers at home improvement chains, and property management executives overseeing multifamily compliance. Primary fieldwork with IoT module suppliers and electrochemical cell membrane producers validated secondary data from EPA licensing filings and REACH substance restriction notices. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Variance decomposition across sensor technology, connectivity protocol, and end-user segments shaped the analytical framework over the projection horizon. Modeled dimensions included photoelectric versus ionization versus dual-sensor configurations, smart versus traditional versus wireless versus hardwired technology tiers, and residential versus commercial versus industrial versus government facility end users. CAGRs derived from replacement cycle compression rates and certification deadline impacts, with insurance premium incentive structures and smart-home interoperability mandates as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EPA Americium-241 licensing, REACH halogenated flame retardant restrictions, and NFPA 72 interconnection mandates; material policy shifts would require re-modeling. Electrochemical cell supply disruptions, Matter protocol adoption velocity, and rental housing inspection regime expansion represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Fire Protection Systems for Industrial Cooking Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Flame Barrier Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
Europe Passive Fire Protection Market
Fire Safety & Protection
Global Fire Control System Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Fire Resistant Glass Market