
 North America Surveillance Analog Camera Market | 2026-2036
North America Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
North America Surveillance Analog Camera Market Insights
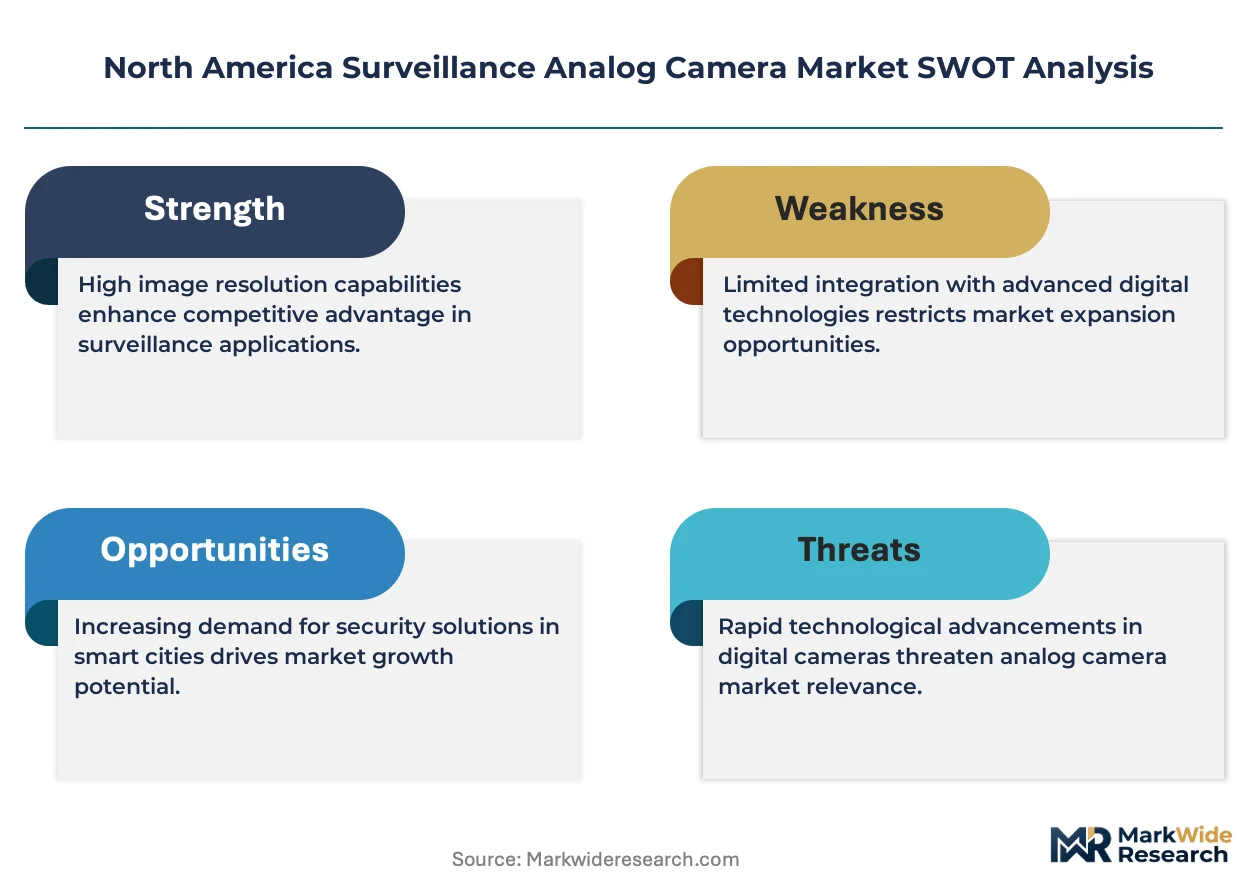
A capital-intensity divergence between in-house sensor fabrication and outsourced assembly is bifurcating competitive positioning across the North America Surveillance Analog Camera Market. Bosch Security Systems leverages captive manufacturing in Mexico to sustain margin control on HD-TVI chipset production. Panasonic Corporation anchors its position through R&D intensity in low-light analog sensor architectures. Hanwha Vision America competes on channel density, controlling distributor relationships across the southeastern United States.
North America Surveillance Analog Camera denotes closed-circuit video capture devices transmitting uncompressed analog signals over coaxial cable, typically operating at 720p to 1080p resolution through HD-CVI, HD-TVI, or AHD protocols for real-time security monitoring without network latency. The technology serves critical infrastructure where IP conversion costs exceed replacement budgets, particularly in prisons, parking structures, and remote utility substations. Dome cameras dominate government installations due to vandal-resistant housing requirements, while bullet configurations lead retail sector adoption for perimeter deterrence visibility. HD-TVI technology captures the fastest upgrade trajectory as end users seek 1080p clarity without rewiring existing RG-59 infrastructure.
FCC Part 15 emissions compliance and UL 2900 cybersecurity readiness standards constrain market access for uncertified imports while NHTSA guidelines influence transportation sector procurement specifications for analog backup systems in transit depots. The Department of Homeland Security SAFETY Act certification creates additional qualification layers for cameras deployed at critical infrastructure sites. Stakeholders must monitor FCC rulemaking on analog spectrum efficiency as potential repurposing of sub-1GHz bands could force accelerated migration timelines for wireless analog installations.
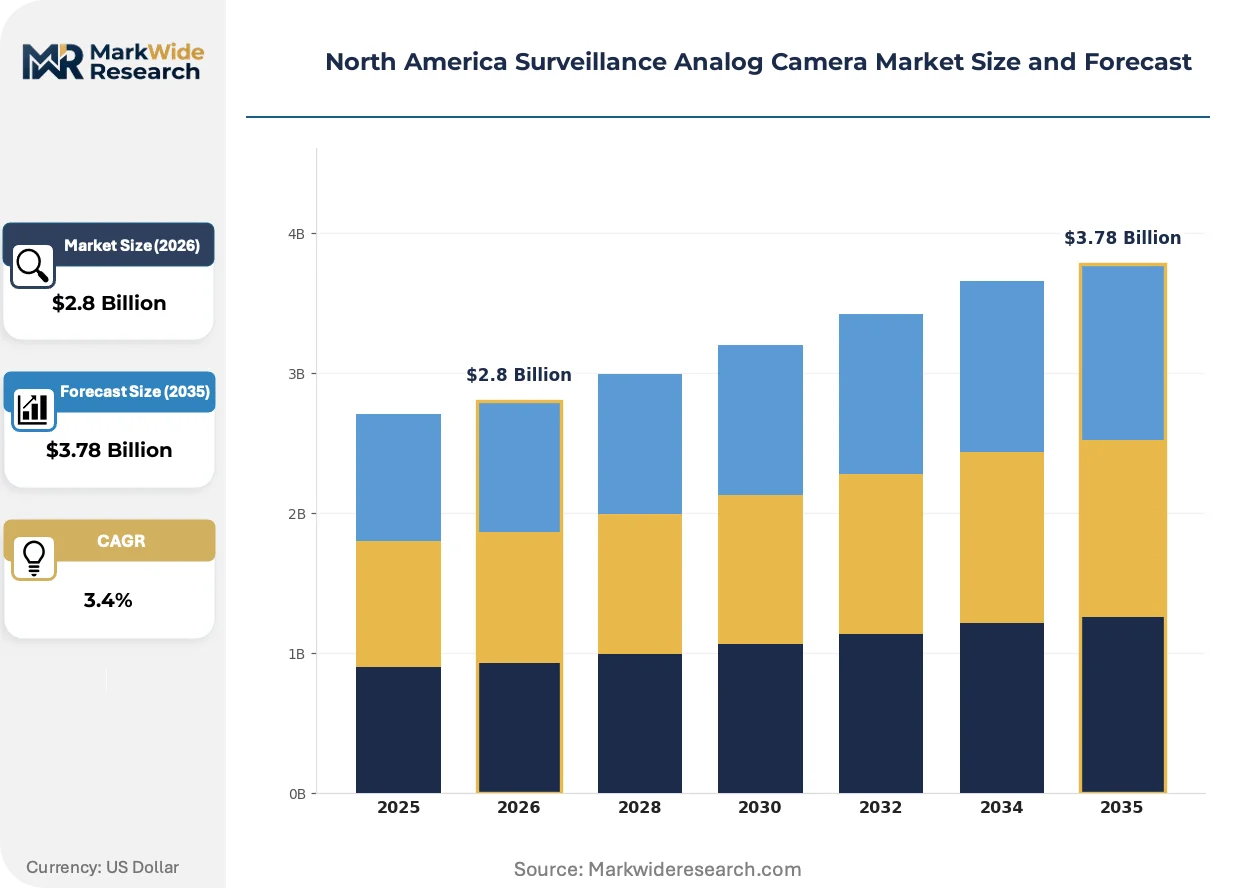
Market Dynamics
HD-TVI protocol migration is compressing upgrade cycles across correctional facilities and border infrastructure, forcing procurement departments to reconcile 1080p clarity demands with RG-59 coaxial preservation mandates.
Growth Catalysts
- FCC Part 15 Equipment Authorization:Federal compliance requirements for analog-over-coax emissions are filtering out uncertified imports, creating procurement preference for UL-listed manufacturers serving U.S. critical infrastructure.
- Texas-Mexico Border Corridor Deployments:Customs and Border Protection bulk orders for weather-resistant bullet cameras are sustaining volume demand through hardened environmental specifications.
- Legacy Infrastructure Lock-In:Federal prison construction budgets allocate dedicated surveillance line items that prioritize coaxial compatibility over IP conversion, extending analog replacement timelines.
Market Restraints
- Copper Cable Input Volatility:RG-59 coaxial pricing fluctuates with commodity copper markets, squeezing margin predictability for infrastructure-heavy installations.
- IP Camera Substitution Pressure:Power-over-Ethernet convergence is eroding analog's cost advantage in greenfield retail and commercial construction.
- Spectrum Repurposing Risk:FCC rulemaking on sub-1GHz band efficiency threatens wireless analog installations with forced migration timelines.
Strategic Opportunities
- Canadian Correctional Retrofit Pipeline:Provincial prison systems lag U.S. HD-TVI adoption by three to five years, creating white space for protocol upgrade services.
- DHS SAFETY Act Certification:Critical infrastructure qualification layers create vendor stickiness at ports, power substations, and transportation depots.
- HD-CVI/HD-TVI Hybrid Chipsets:Dual-protocol silicon is decomposing single-standard lock-in, enabling integrators to bid across incompatible legacy bases.
Industry Challenges
- Coaxial Splicing Skill Scarcity:Field technician pools trained on BNC termination and impedance matching are aging out faster than certification programs replenish.
- UL 2900 Cybersecurity Readiness:Analog camera firmware audit timelines extend procurement cycles by eight to fourteen weeks for hardened facility deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Surveillance Analog Camera Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: Dome, Bullet, C-Mount, PTZ End User: Government, Retail Sector, Transportation, Hospitality Technology: Infrared, HD-CVI, HD-TVI, AHD Installation Method: Wired, Wireless, PoE, Hybrid |
| Companies Covered | Bosch Security Systems, Panasonic Corporation, Hanwha Vision America, Zhejiang Uniview Technologies, IDIS, Johnson Controls, Motorola Solutions, Digital Watchdog, Pelco, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Surveillance Analog Camera Market Trends and Innovations
Protocol convergence and certification layering are fragmenting vendor specialization, compressing the boundary between analog maintenance and hybrid surveillance architecture deployment.
HD-TVI signal processing is decomposing the resolution ceiling that trapped analog in 720p territory. State correctional departments in Arizona and Georgia are standardizing on 1080p HD-TVI dome configurations for vandal-resistant housing requirements. The technology is decomposing price premiums previously commanded by early IP migration, forcing integrators to rebid maintenance contracts around coaxial preservation economics.
FCC equipment authorization requirements are tightening electromagnetic compatibility verification for analog-over-coax imports. Uncertified Asian manufacturers face exclusion from federal procurement channels, redirecting supply toward Mexico-based captive production. U.S. border infrastructure projects now specify FCC Part 15 compliance as a pass-fail gate, compressing vendor qualification pools.
Facility maintenance departments are unbundling after-sales service from hardware procurement, demanding separate pricing for firmware update subscriptions and field technician dispatch. State prison systems in Texas and California are piloting three-year service separations from capital equipment budgets. This unbundling concentrates negotiating leverage with integrators holding regional technician density.
North America Surveillance Analog Camera Market Segmentation
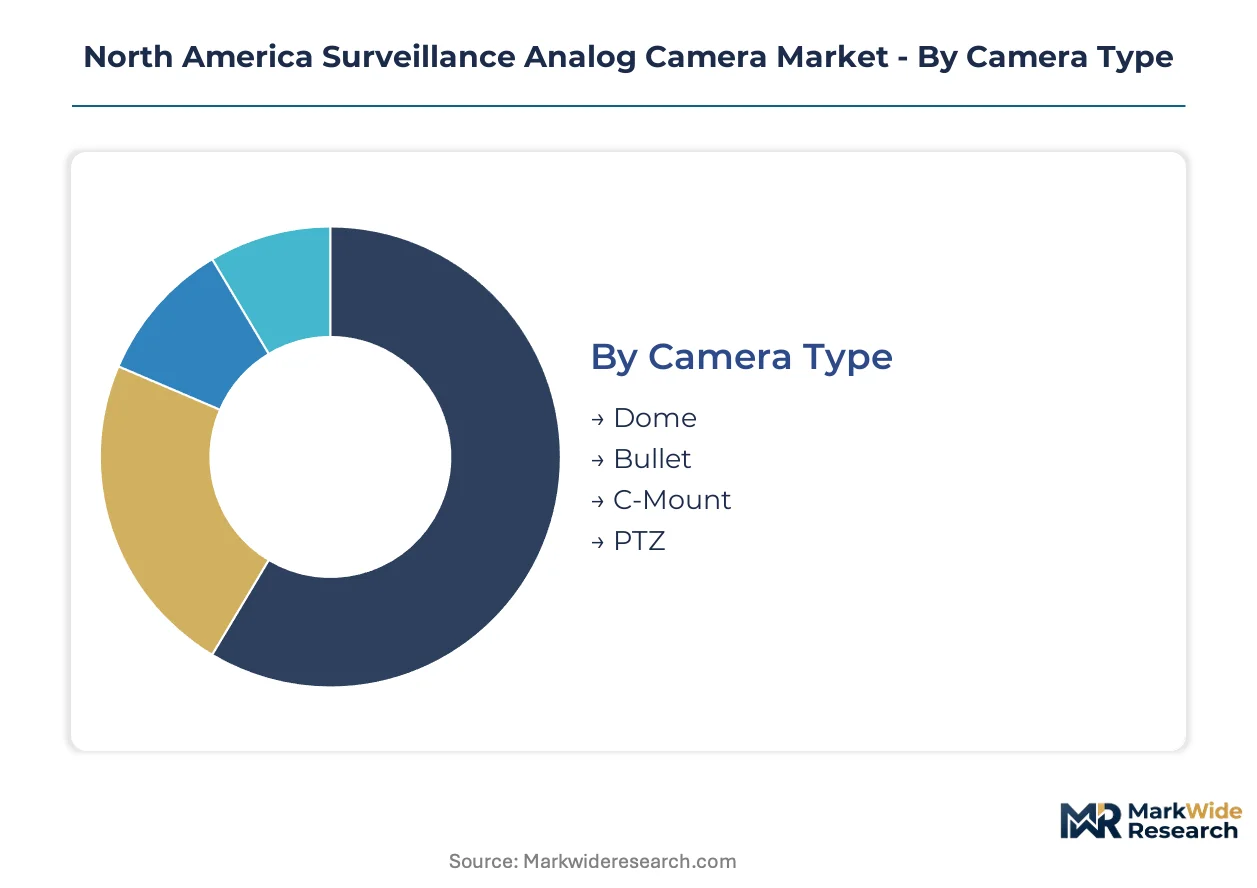
Segmentation in the North America Surveillance Analog Camera Market reveals where coaxial infrastructure preservation creates defensive moats against IP substitution and where protocol migration opens upgrade revenue. Procurement patterns diver sharply across camera housing requirements, federal certification thresholds, and legacy wiring constraints.
Camera Type:
IP substitution pressure concentrates on exposed perimeter installations where Power-over-Ethernet trenching costs have collapsed, while enclosed infrastructure preserves analog economics for vandal-resistant form factors.
- Dome:Vandal-resistant housing with polycarbonate or metal enclosures protects the lens assembly from physical impact and environmental intrusion. State correctional departments in Arizona and Georgia specify dome configurations for cell block monitoring where inmate tampering risks mandate hardened enclosures. Federal prison construction budgets prioritize dome deployments for indoor surveillance corridors.
- Bullet:Cylindrical weather-sealed housing with integrated sunshield and mounting bracket optimizes for outdoor perimeter visibility. Customs and Border Protection installations across the Texas-Mexico border corridor drive bulk procurement of bullet cameras with IP66 environmental ratings for desert and coastal exposure.
- C-Mount:Detachable lens interface enables varifocal customization for specialized focal length requirements in industrial inspection and laboratory settings.
- PTZ:Motorized pan-tilt-zoom mechanisms with joystick-controlled positioning serve traffic monitoring and large-area coverage where operator-directed surveillance replaces fixed-view density.
Bullet cameras retain volume leadership through border infrastructure scale; dome configurations hold the steepest expansion curve as correctional retrofit programs accelerate.
End User:
Cost tier stratification separates federally funded critical infrastructure from commercial deployments where total cost of ownership calculations favor IP migration.
- Government:Federal procurement channels mandate FCC Part 15 equipment authorization and UL cybersecurity certification as pass-fail gates. Department of Homeland Security SAFETY Act certification creates vendor stickiness at ports, power substations, and transportation depots where analog backup systems preserve operational continuity during network failures.
- Retail Sector:Perimeter deterrence visibility drives bullet camera preference for parking lot coverage, though greenfield construction increasingly defaults to Power-over-Ethernet convergence. Franchise operators with existing RG-59 infrastructure delay conversion through HD-TVI upgrade economics.
- Transportation:NHTSA guidelines influence transit depot procurement specifications for analog backup systems where network latency disrupts real-time safety monitoring.
- Hospitality:Casino floor and corridor surveillance prioritizes discrete dome aesthetics over perimeter visibility, with tribal gaming commissions specifying hardened environmental ratings for desert and mountain resort locations.
Government end use retains volume leadership; retail sector applications face the steepest IP substitution compression.
Technology:
Supply concentration in HD-TVI silicon fabrication is decomposing single-protocol lock-in while AHD and HD-CVI defend installed base preservation economics.
- HD-TVI:Transport Video Interface protocol transmits uncompressed 1080p video over standard RG-59 coaxial cable without latency or compression artifacts. State correctional departments standardize on HD-TVI for 1080p clarity demands reconciled with coaxial preservation mandates, decomposing price premiums previously commanded by early IP migration.
- HD-CVI:Composite Video Interface technology offers comparable resolution with longer transmission distances over lower-grade cable, defending market position in sprawling campus and industrial yard deployments.
- AHD:Analog High Definition protocol maintains backward compatibility with earliest-generation analog recorders, preserving upgrade pathways for budget-constrained municipal and educational installations.
- Infrared:LED array illumination extends low-light capture capability without visible spectrum emission, serving perimeter detection where white-light exposure compromises operational security.
HD-TVI retains volume leadership through correctional and border infrastructure standardization; HD-CVI gains share fastest in Canadian provincial systems lagging U.S. adoption curves.
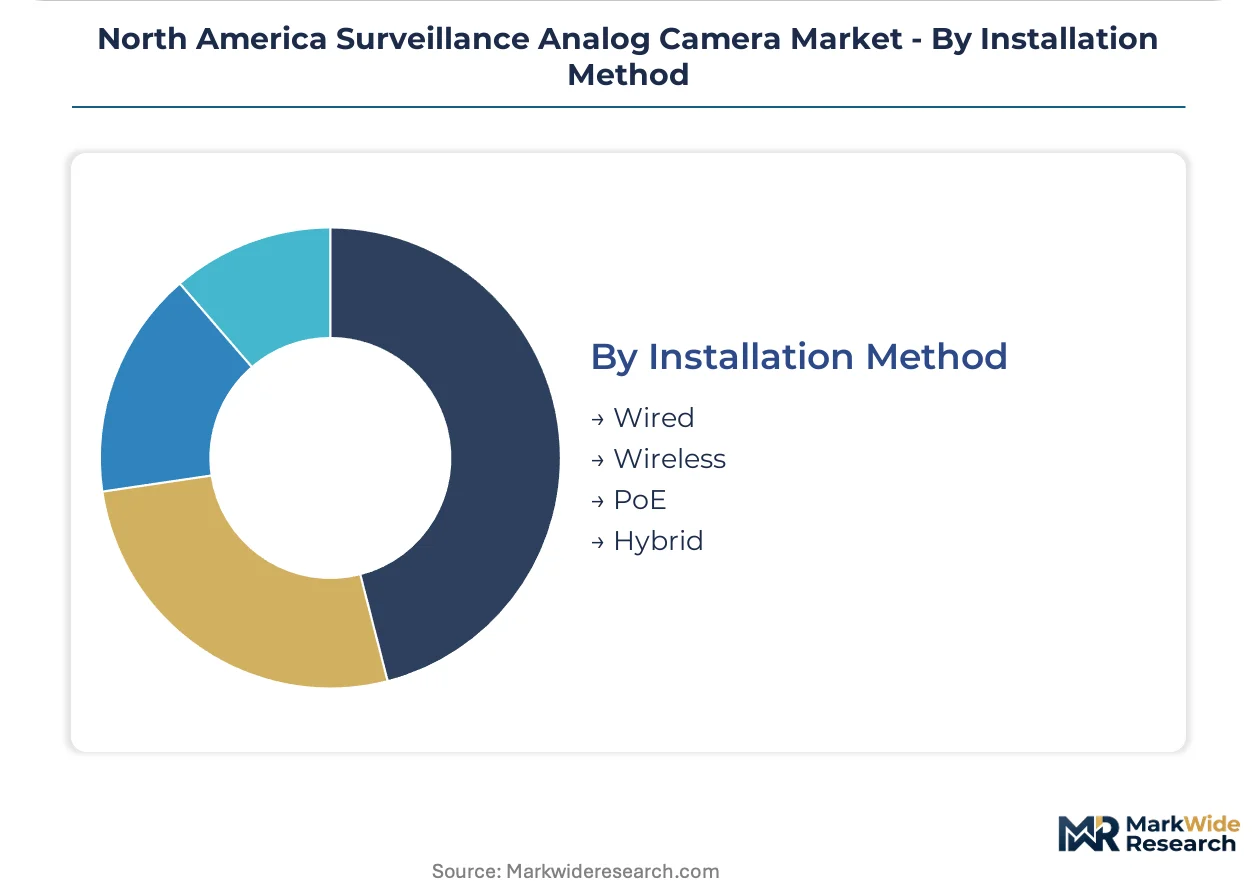
Installation Method:
Customer type stratification separates legacy infrastructure lock-in from greenfield deployment flexibility, with hybrid architectures bridging the transition.
- Wired:Dedicated coaxial cable runs deliver interference-free signal transmission with deterministic latency for real-time security monitoring. Federal prison construction budgets allocate dedicated surveillance line items prioritizing coaxial compatibility over IP conversion.
- Hybrid:Dual-path architecture preserves analog camera investment while enabling incremental IP recorder integration through encoder bridging. State prison systems in Texas and California pilot three-year service separations from capital equipment budgets, concentrating negotiating leverage with integrators holding regional technician density.
- Wireless:Sub-1GHz analog transmission avoids trenching costs in remote utility substations and temporary construction monitoring, though FCC spectrum repurposing risk threatens forced migration timelines.
- PoE:Power-over-Ethernet convergence erodes analog's cost advantage in greenfield retail and commercial construction where structured cabling installation proceeds regardless of camera technology selection.
Wired installation retains volume leadership through legacy infrastructure lock-in; hybrid configurations climb the fastest as integrators unbundle after-sales service from hardware procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows from Asian manufacturing clusters dominate supply, while intra-regional trade concentrates on specialized components and certification-heavy finished goods serving critical infrastructure.
United States
Federal prison construction budgets and Customs and Border Protection deployments drive procurement volume. FCC Part 15 equipment authorization filters uncertified imports from federal channels. The Texas-Mexico border corridor sustains bulk orders for weather-resistant bullet cameras with hardened environmental specifications.
Canada
Provincial correctional systems lag U.S. HD-TVI adoption by three to five years, creating retrofit service opportunities. Health Canada equipment safety standards align with UL certification requirements for cross-border procurement. Ontario and Quebec prison infrastructure programs prioritize coaxial compatibility over full IP conversion.
Mexico
Captive manufacturing facilities serve North American demand with tariff-advantaged production. Domestic security infrastructure modernization accelerates analog deployment in municipal surveillance. The Bajío Region and northern border states concentrate assembly operations for HD-TVI chipset fabrication.
North America Surveillance Analog Camera Market Competitive Landscape
Concentration sits with diversified security conglomerates and specialized video surveillance manufacturers. The vendor base splits between captive production operators and R&D-intensive sensor architects. Two strategic archetypes dominate: Mexico-based fabricators leveraging tariff-advantaged assembly, and technology licensors controlling protocol standards. Competitive moves center on dual-protocol silicon development and DHS SAFETY Act certification pursuit for critical infrastructure vendor stickiness.
Among Asia-Pacific technology licensors, Zhejiang Uniview Technologies and IDIS occupy positions emphasizing multi-protocol compatibility. Bosch Security Systems exemplifies the captive manufacturing archetype through Mexico-based production control. These three represent distinct competitive vectors: protocol flexibility, regional production economics, and federal certification depth.
| Leading Market Players |
|---|
| Bosch Security Systems |
| Panasonic Corporation |
| Hanwha Vision America |
| Zhejiang Uniview Technologies |
| IDIS |
| Johnson Controls |
| Motorola Solutions |
| Digital Watchdog |
| Pelco |
| Others |
Pricing and Supply Chain Analysis
FCC Part 15 equipment authorization gates both vendor qualification and price differentiation simultaneously, compressing procurement pools to UL-certified manufacturers while creating certification-premium tiers across federal and commercial channels. Buyers with SAFETY Act mandates absorb higher per-unit costs for hardened firmware audit compliance, while municipal operators trade specification depth for volume discounts on standard dome configurations.
Pricing Analysis
Configured-to-order pricing for DHS-certified bullet cameras with custom focal lengths and environmental hardening commands substantial premiums over standard HD-TVI dome configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by UL 2900 cybersecurity readiness and FCC authorization tier, with federal prison procurement showing lowest price sensitivity and retail franchise operators driving hardest bargain on coaxial-upgrade bundles. Cost compression in standard-definition replacement tiers is intensifying because HD-TVI silicon commoditization erodes legacy 720p margins faster than integrators can reprice maintenance contracts.
Supply Chain Analysis
Port congestion along the Los Angeles-Long Beach corridor and container availability constraints on the Shenzhen-Los Angeles trade lane are extending inbound lead times for Asian-manufactured sensor modules and DSP chipsets. Supply concentrates in China for CMOS sensor fabrication, South Korea for image signal processor design, and Mexico for final assembly and FCC pre-certification testing. Copper conductor pricing volatility and tariff exposure on Chinese coaxial cable imports create margin unpredictability, while distribution runs through regional security integrators holding captive relationships with state procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HD-TVI protocol migration is compressing analog's remaining upgrade window, with FCC spectrum rulemaking threatening wireless analog installations and forcing accelerated hardening investment decisions.
For Market Incumbents: Secure DHS SAFETY Act certification depth across bullet and dome form factors before spectrum repurposing deadlines eliminate wireless analog revenue streams. Deepen captive manufacturing control in Mexico to offset tariff exposure on Chinese coaxial inputs, while locking three-year service separations into state prison RFPs to defend technician-density leverage against IP-conversion bids. For New Entrants and Emerging Players: Anchor in Canadian provincial correctional retrofit pipelines where HD-TVI adoption lags U.S. curves by three to five years, creating white space for protocol-upgrade service bundling. Target municipal surveillance in Mexico's Bajío Region through tariff-advantaged local assembly partnerships, positioning on dual-protocol HD-CVI/HD-TVI silicon to bid across incompatible legacy bases without single-standard lock-in. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across HD-TVI chipset fabrication as outsourced assembly displaces captive sensor production, compressing returns for R&D-heavy sensor architects relative to Mexico-based volume assemblers. Acquisition targets should display regional technician density in Texas-California corridors or SAFETY Act certification backlogs at critical infrastructure sites; watch FCC sub-1GHz rulemaking timelines as forced-migration inflection signal for wireless analog exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Protocol Silicon Development | HD-CVI/HD-TVI hybrid chipsets decompose single-standard lock-in across incompatible legacy bases. |
| DHS SAFETY Act Certification Pursuit | Federal qualification layers create vendor stickiness at ports, substations, and transportation depots. |
| Captive Mexico Manufacturing Expansion | Tariff-advantaged assembly offsets copper cable input volatility and FCC pre-certification timelines. |
| Three-Year Service Unbundling | Texas and California prison pilots concentrate negotiating leverage with regional technician-dense integrators. |
| Canadian Provincial Retrofit Targeting | Ontario and Quebec lag U.S. HD-TVI adoption, opening white space for protocol-upgrade services. |
Research Methodology
Cross-validation between integrator field interviews and federal procurement database analysis anchors the qualitative findings on correctional and border infrastructure demand patterns. Primary discussions with state prison procurement officers, CBP facilities engineers, regional security integrators, and UL certification auditors combined with secondary validation through FCC equipment authorization filings, DHS SAFETY Act certification records, and customs import data for coaxial cable and camera assemblies. Bottom-up demand sizing from facility-level deployment records triangulates against top-down market value reconstruction.
Sensitivity analysis on copper commodity pricing and FCC rulemaking timelines frames projection uncertainty across the analysis window. Segmentation dimensions modeled include camera housing type, end-user sector, protocol technology, and installation method, with federal certification tier and regional technician density as industry-specific forecast inputs. CAGRs derive from protocol migration curves fitted to correctional facility upgrade cycles and border infrastructure appropriation trajectories.
Decision-makers should treat outputs as directional under stable copper pricing and unchanged FCC spectrum allocation assumptions; material deviation would warrant model refresh. Forecasts reflect these base conditions alongside Canadian provincial budget execution and Mexican domestic security modernization pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Storage Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Central Monitoring Station Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Smart Outdoor Cameras Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
China Surveillance IP Camera Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Hosted Video Surveillance Market
Video Surveillance Systems
Surveillance Camera Systems Market
Video Surveillance Systems
Europe Video Surveillance Storage Market