
 Seaport Security Management Market | 2026-2036
Seaport Security Management Market Size, Share, and Industry Trends Forecast 2026-2036
Seaport Security Management Market Analytics
Integrated threat-detection specifications is redrawing procurement criteria across major harbor complexes. Honeywell International leverages its building-automation heritage to bundle climate, fire, and perimeter systems into unified command platforms. Siemens anchors European retrofit demand through its Siveillance portfolio, which dominates software-defined video management at Rotterdam and Hamburg. Saab AB specializes in naval-grade radar-to-camera fusion, a capability that positions it for military-civilian dual-use contracts at strategic chokepoints.
Seaport security management encompasses the layered protection of maritime cargo facilities through electronic access barriers, sensor networks, and centralized command infrastructure designed to intercept unauthorized intrusion, contraband movement, and terrorism. Systems typically integrate thermal imaging with minimum 640x480 resolution, edge-based video analytics, and sub-500-millisecond alarm relay to satisfy ISPS Code response-time mandates. Surveillance solutions currently command the largest installed base, though biometric authentication is registering the steepest adoption curve as facial-recognition turnstiles replace magnetic-badge systems at Asian mega-ports. IoT sensors are emerging as the margin-rich segment, since salt-corrosion-rated environmental monitors and under-wharf pressure detectors require specialized marine certification that limits vendor pool depth.
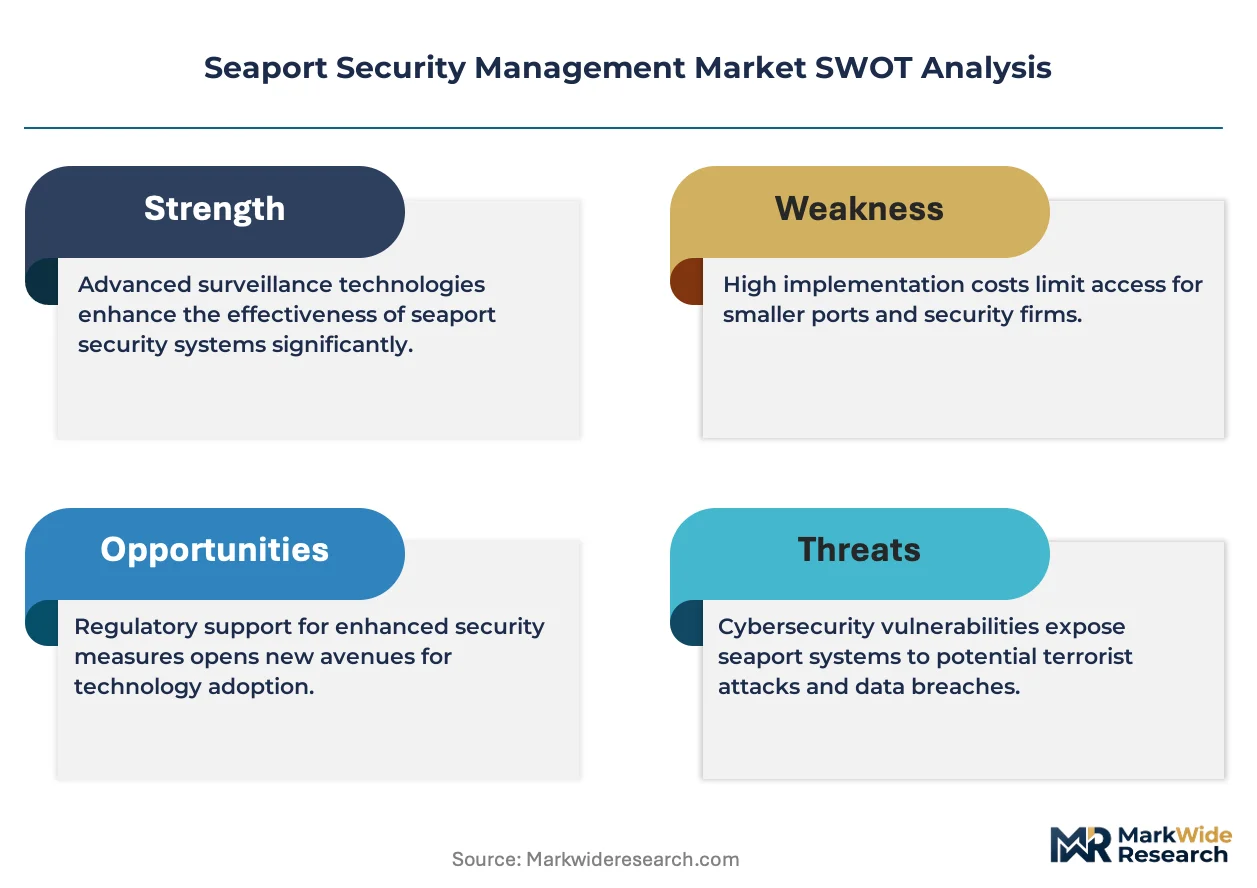
The International Maritime Organization's ISPS Code, the U.S. Coast Guard's Maritime Transportation Security Act regulations, and the EU's Critical Entities Resilience Directive collectively mandate layered access control and periodic vulnerability assessments at commercial harbors. Compliance deadlines force recurring technology refresh cycles, converting one-time equipment sales into sustained service relationships. Stakeholders must weigh the trade-off between proprietary system lock-in and interoperability demands as port authorities consolidate regional command centers.
Market Dynamics
The convergence of biometric authentication corridors with legacy perimeter infrastructure is compressing procurement cycles at Asian mega-ports, forcing vendors to rearchitect product roadmaps around salt-corrosion-rated edge computing rather than centralized server stacks.
Growth Catalysts
- ISPS Code amendments:The International Maritime Organization's revised compliance deadlines mandate sub-500-millisecond alarm relay systems, triggering wholesale sensor network upgrades at container terminals in Singapore and Rotterdam.
- Facial-recognition turnstiles:Multi-factor identification corridors at Tuas Port demonstrate operational feasibility, creating reference architectures that port authorities in Vietnam and Indonesia now specify in tenders.
- EU Critical Entities Resilience Directive:This framework forces European harbor complexes to consolidate regional command centers, bundling climate, fire, and perimeter systems into unified procurement packages.
Market Restraints
- Marine-grade certification scarcity:Salt-corrosion-rated environmental monitors require specialized IEC 60945 compliance testing that only three accredited laboratories in Northern Europe currently perform.
- Proprietary system lock-in:Honeywell's building-automation heritage creates integration friction with Siemens Siveillance deployments, fragmenting command-center consolidation efforts at multi-vendor sites.
- Under-wharf sensor replacement cycles:Pressure detectors submerged in tidal zones face 18-24 month mean-time-between-failures, doubling lifecycle costs versus above-deck alternatives.
Strategic Opportunities
- Software-defined video management:Rotterdam and Hamburg retrofit demand creates a template for AI-enabled analytics layers that smaller Baltic ports can adopt without full infrastructure replacement.
- Radar-to-camera fusion:Military-civilian dual-use specifications at strategic chokepoints like the Strait of Malacca open adjacent revenue streams for naval-grade sensor vendors.
- IoT sensor certification services:The shallow vendor pool for marine-certified environmental monitors creates margin-rich consulting and testing revenue for standards bodies with IEC accreditation.
Industry Challenges
- Interoperability testing complexity:Port authorities consolidating regional command centers must reconcile proprietary protocols from incumbent building-automation vendors with open-architecture surveillance platforms.
- Edge computing deployment expertise:Thermal imaging systems with 640x480 resolution minimum specifications require on-site calibration capabilities that legacy security integrators rarely possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seaport Security Management Market |
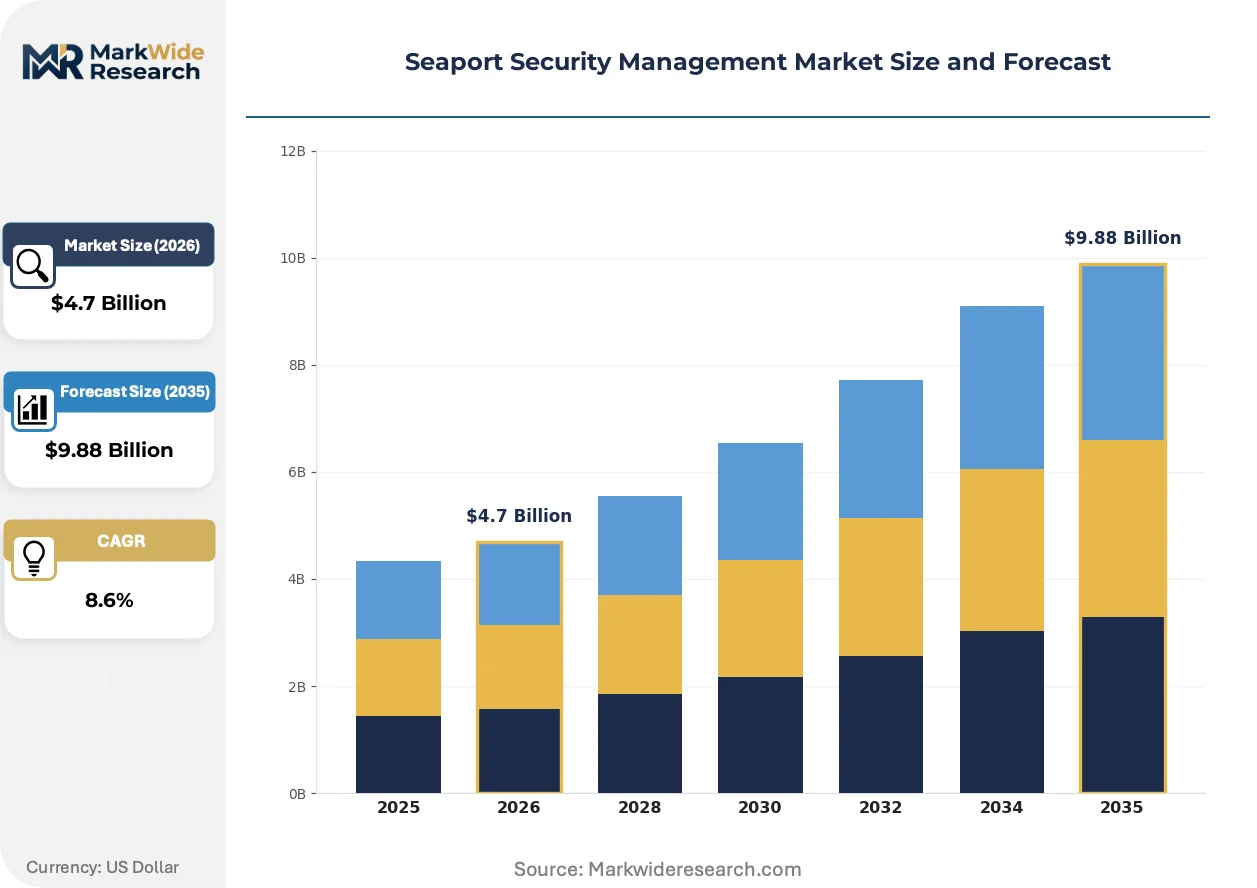
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Control Systems, Surveillance Solutions, Intrusion Detection Systems, Monitoring Equipment End User: Port Authorities, Shipping Companies, Security Agencies, Customs Technology: Biometric Authentication, Video Analytics, RFID Tracking, IoT Sensors Service Type: Consulting, Implementation, Maintenance, Training |
| Companies Covered | Johnson Controls, Honeywell International, Siemens, Saab AB, Bosch Security Systems, FLIR Systems, L3Harris Technologies, Raytheon, Thales, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seaport Security Management Market Evolving Landscape
Sensor fusion architectures are redrawing competitive boundaries between naval-defense contractors and commercial security vendors, compressing the traditional separation between military-grade and harbor-protection procurement channels.
Edge-based video analytics is decomposing centralized server architectures at container terminals. Singapore's PSA International deploys sub-500-millisecond processing nodes directly at gate access points, eliminating latency from cloud-reliant systems. This topology is decomposing the traditional value chain, shifting margin capture from server manufacturers to corrosion-hardened edge device specialists.
The EU's Critical Entities Resilience Directive mandates periodic vulnerability assessments with documented remediation timelines. Harbor operators in Hamburg and Rotterdam now embed compliance auditing into multi-year service contracts rather than treating assessments as discrete procurement events. Software-defined video management platforms absorb the largest share of this compliance-driven spending.
Consolidated regional command centers are displacing siloed terminal operations across Southeast Asian port clusters. PSA International's Tuas Port integrates climate, fire, and perimeter monitoring through unified dashboards, a model that Indonesian port authorities in Batam and Belawan now specify in tender documents. This behavioral shift compresses vendor selection criteria around platform breadth rather than point-solution performance.
Seaport Security Management Market Segmentation
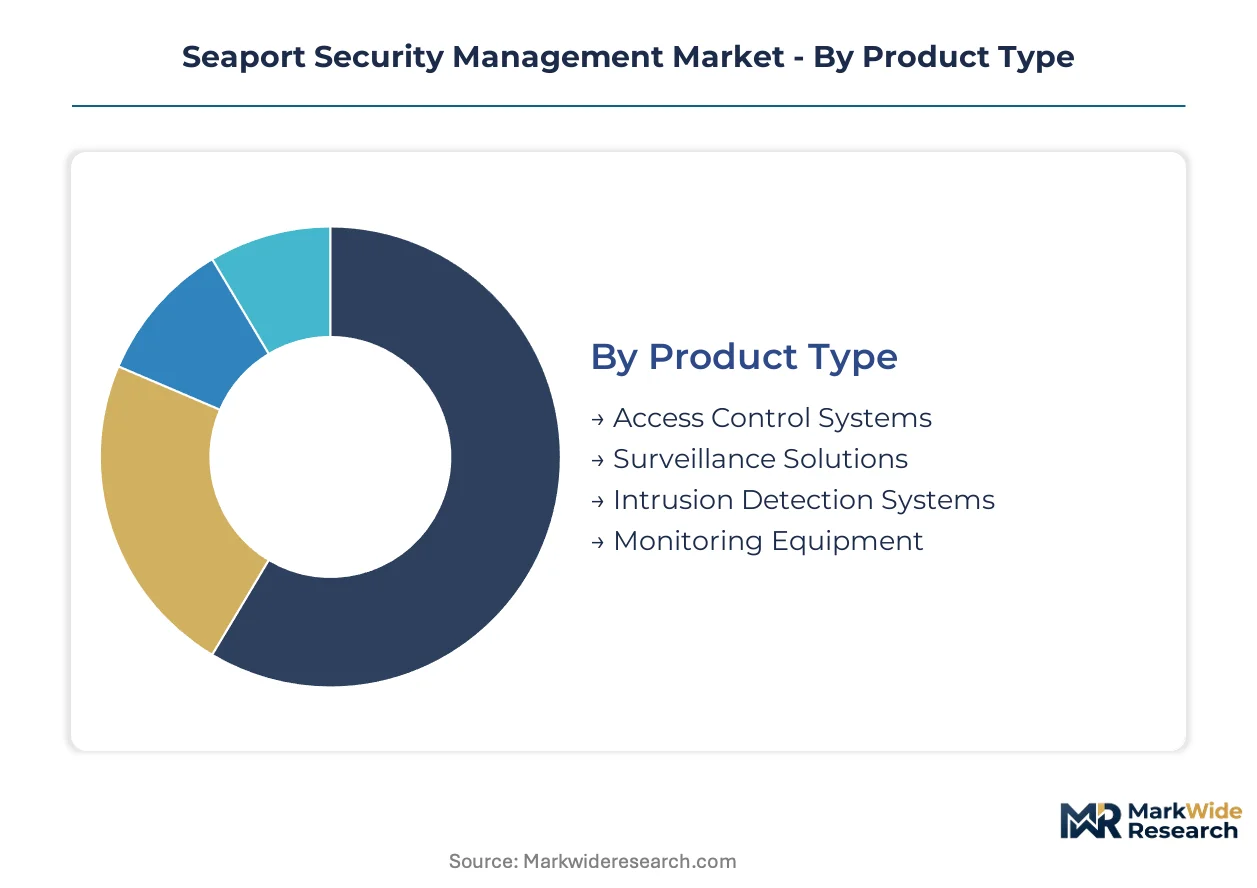
Seaport security procurement divides sharply between infrastructure-heavy capital expenditure and recurring service contracts. Understanding these fault lines clarifies where vendor margins concentrate versus where price competition erodes profitability.
Product Type:
Surveillance and access systems dominate domestic procurement at mature hubs, while intrusion detection and monitoring equipment flow disproportionately to greenfield port developments across Southeast Asia.
- Surveillance Solutions:Thermal imaging arrays with minimum 640x480 resolution anchor perimeter defense at Rotterdam and Singapore. Demand concentrates on edge-based analytics nodes that eliminate cloud latency for ISPS Code compliance.
- Access Control Systems:Multi-factor biometric corridors at Tuas Port demonstrate operational feasibility, creating reference architectures that Vietnamese and Indonesian authorities now specify in tender documents.
- Intrusion Detection Systems:Radar-to-camera fusion technologies serve military-civilian dual-use specifications at strategic chokepoints like the Strait of Malacca.
- Monitoring Equipment:Salt-corrosion-rated environmental monitors require specialized IEC 60945 compliance testing available only at three Northern European laboratories.
Surveillance solutions command the established base. The steepest expansion runs through access control systems.
End User:
Cost tier differentiation separates integrated platform buyers from point-solution adopters, with port authorities and security agencies driving unified procurement while shipping companies and customs optimize for discrete compliance minimums.
- Port Authorities:Consolidated regional command centers at Hamburg and Rotterdam bundle climate, fire, and perimeter monitoring through unified dashboards, compressing vendor selection around platform breadth.
- Security Agencies:Naval-grade radar specifications at strategic chokepoints open adjacent revenue streams for defense contractors with marine certification capabilities.
- Shipping Companies:Container line operators prioritize vessel-to-shore interface protection with documented remediation timelines for EU Critical Entities Resilience Directive compliance.
- Customs:Border enforcement agencies specify contraband detection modules with sub-500-millisecond alarm relay systems mandated by revised ISPS Code deadlines.
Port authorities absorb the largest procurement volumes. Security agencies generate the highest-margin specialized contracts.
Technology:
Application maturity varies sharply across this dimension, with video analytics and RFID tracking representing proven deployments while biometric authentication and IoT sensors demand specialized marine certification expertise.
- Biometric Authentication:Facial-recognition turnstiles replace magnetic-badge systems at Asian mega-ports, with PSA International's Tuas Port deployment serving as the reference architecture for regional tenders.
- IoT Sensors:Under-wharf pressure detectors submerged in tidal zones face 18-24 month mean-time-between-failures, doubling lifecycle costs versus above-deck alternatives and limiting vendor pool depth.
- Video Analytics:Software-defined platforms enable AI-enabled analytics layers that smaller Baltic ports adopt without full infrastructure replacement.
- RFID Tracking:Container movement verification systems integrate with legacy terminal operating systems at established hubs.
Video analytics retains the largest installed footprint. Biometric authentication climbs the fastest as facial-recognition corridors displace legacy badge systems.
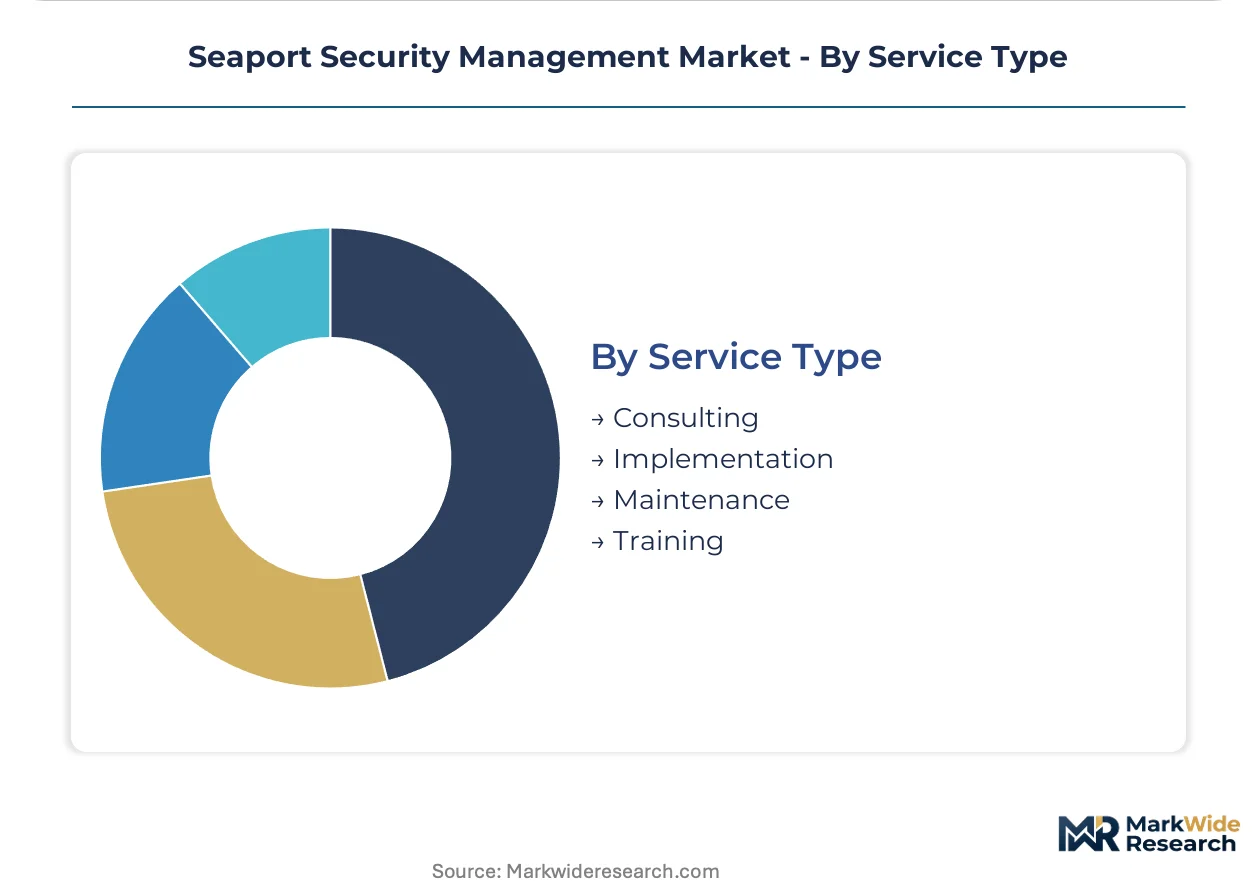
Service Type:
Customer type segmentation reveals diverging contract structures, with implementation and maintenance anchoring multi-year relationships while consulting and training remain discrete procurement events.
- Implementation:System integration services reconcile proprietary protocols from incumbent building-automation vendors with open-architecture surveillance platforms at multi-vendor sites.
- Maintenance:Recurring service contracts now embed compliance auditing for EU Critical Entities Resilience Directive vulnerability assessments, converting one-time equipment sales into sustained revenue streams.
- Consulting:IEC 60945 certification advisory commands premium pricing given the shallow vendor pool for marine-rated environmental monitors.
- Training:Edge computing deployment expertise for thermal imaging calibration represents a capability gap that legacy security integrators rarely possess.
Maintenance services capture the recurring revenue base. Implementation contracts deliver the steepest expansion as port authorities consolidate regional command centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports container security architectures to Southeast Asian port authorities, while Rotterdam and Hamburg supply integrated command platforms to Baltic and North Sea neighbors. This trade in reference designs shapes procurement patterns across three continents.
Singapore
PSA International's Tuas Port deployment compresses procurement cycles for biometric authentication corridors. The Maritime and Port Authority of Singapore enforces ISPS Code amendments with sub-500-millisecond alarm relay mandates. The Tuas mega-port cluster anchors regional demand for multi-factor identification systems that Vietnamese and Indonesian authorities now replicate.
Netherlands
Rotterdam's software-defined video management platforms absorb the largest share of EU Critical Entities Resilience Directive compliance spending. The Dutch Human Environment and Transport Inspectorate mandates periodic vulnerability assessments with documented remediation timelines. The Rotterdam harbor complex bundles climate, fire, and perimeter monitoring through unified dashboards that smaller Baltic ports adopt without full infrastructure replacement.
Germany
Hamburg's consolidated regional command center creates templates for harbor operators embedding compliance auditing into multi-year service contracts. The Federal Maritime and Hydrographic Agency enforces layered access control standards aligned with EU harbor protection frameworks. The Hamburg port cluster drives retrofit demand for AI-enabled analytics layers.
United States
The U.S. Coast Guard's Maritime Transportation Security Act regulations force recurring technology refresh cycles at container terminals along the Gulf and Atlantic coasts. The Department of Homeland Security mandates vessel-to-shore interface protection with documented security protocols. The Port of Long Beach and Port of Los Angeles anchor West Coast demand for integrated surveillance platforms.
Indonesia
Batam and Belawan port authorities specify tender documents modeled on Singapore's Tuas Port reference architecture. The Directorate General of Sea Transportation implements ISPS Code compliance deadlines that trigger wholesale sensor network upgrades. These port clusters concentrate demand for facial-recognition turnstiles replacing magnetic-badge systems.
Seaport Security Management Market Competitive Landscape
Listed leaders compete with private specialists across building-automation heritage and naval-grade defense contracting. The vendor base concentrates around three tiers: diversified conglomerates bundling climate and perimeter systems, defense contractors with marine certification capabilities, and corrosion-hardened edge device specialists. Strategic moves center on platform breadth expansion and military-civilian dual-use specification capture.
Within the diversified systems tier, Honeywell International and Siemens exemplify contrasting integration philosophies. Honeywell leverages building-automation heritage to bundle unified command platforms, while Siemens anchors European retrofit demand through software-defined video management portfolios. Saab AB occupies a position within the naval-defense contractor archetype, specializing in radar-to-camera fusion capabilities that serve strategic chokepoint specifications.
| Leading Market Players |
|---|
| Johnson Controls |
| Honeywell International |
| Siemens |
| Saab AB |
| Bosch Security Systems |
| FLIR Systems |
| L3Harris Technologies |
| Raytheon |
| Thales |
| Others |
Value Network & Pricing Analysis
Multi-year service contracts with embedded compliance auditing lock in both supply access and price visibility for port authorities consolidating regional command centers, converting discrete equipment procurement into sustained vendor relationships with predictable cost structures.
Pricing Analysis
Current-generation biometric authentication corridors command substantial premiums over legacy magnetic-badge systems and prior-generation RFID tracking, while next-generation radar-to-camera fusion specifications remain quotation-stage. Pricing stratifies across military-grade certification, commercial marine rating, and uncertified economy tiers. Cost compression in edge-computing hardware is intensifying because semiconductor foundries are expanding corrosion-hardened chip fabrication capacity. Customs and border enforcement agencies exhibit highest price sensitivity due to budget-constrained procurement cycles, while naval defense contractors absorb premium positioning with lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of salt-corrosion-rated sensors dominates procurement behavior as port authorities buffer against 18-24 month replacement cycles for submerged under-wharf equipment. Component manufacturing concentrates in Germany, the Netherlands, and Singapore, with specialized IEC 60945 certification testing available only at three Northern European laboratories. Production draws from naval-grade radar subsystems, thermal imaging arrays, and marine-hardened edge processors. Single-source vulnerability runs through the shallow vendor pool for marine-certified environmental monitors. Distribution feeds from systems integrators with port-authority relationships rather than direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The seaport security management market represents a high-growth disruption as ISPS Code amendments with sub-500-millisecond alarm relay mandates force wholesale infrastructure replacement across container terminals worldwide.
For Market Incumbents: Secure marine-grade certification expansion at the three accredited Northern European laboratories to lock out emerging competitors from the margin-rich IoT sensor segment. Deepen backward integration into corrosion-hardened edge processor fabrication as semiconductor supply constraints threaten delivery timelines for thermal imaging deployments.
For New Entrants and Emerging Players: Differentiate on software-defined video management analytics layers that Baltic and Southeast Asian secondary ports can adopt without full infrastructure replacement, bypassing entrenched building-automation incumbents. Target Indonesian port clusters in Batam and Belawan where Singapore's Tuas reference architecture has created specification templates but local vendor relationships remain unsettled.
For Investors and Strategic Acquirers: Capital is best deployed toward corrosion-hardened edge device specialists with existing IEC 60945 certification relationships and proven salt-environment deployment records, positioned for 5-10 year recurring service contract capture. The signal to watch is biometric authentication corridor tender volumes from Vietnamese and Indonesian port authorities as adoption inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Marine Certification Expansion | IEC 60945 accreditation at Northern European laboratories limits vendor pool depth and protects premium positioning. |
| Software-Defined Platform Integration | Unified dashboards bundling climate, fire, and perimeter systems displace siloed terminal operations at Rotterdam and Hamburg. |
| Radar-to-Camera Fusion Development | Military-civilian dual-use specifications at the Strait of Malacca open adjacent revenue streams for naval-grade sensor vendors. |
| Edge Computing Deployment Partnership | On-site calibration capabilities for thermal imaging systems address capability gaps that legacy security integrators rarely possess. |
| Regional Command Center Consolidation | Multi-year service contracts embedding EU Critical Entities Resilience Directive compliance auditing convert equipment sales into sustained revenue. |
Research Methodology
The analysis maps surveillance solutions, access control systems, intrusion detection equipment, and monitoring devices, each validated through port authority procurement directors, security agency specification officers, customs technology leads, and systems integration engineers. Primary interviews with terminal operating system vendors and marine certification laboratory technical directors combined with secondary validation from IMO ISPS Code amendment documentation, EU Critical Entities Resilience Directive regulatory filings, and U.S. Coast Guard Maritime Transportation Security Act enforcement records. Bottom-up equipment shipment tracking and top-down port infrastructure investment analysis provided cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology generation, end-user tier, service contract structure, and regional regulatory cluster as segmentation dimensions. CAGRs derived from installed base replacement cycles and greenfield port development pipelines incorporated sensor network upgrade mandates, biometric authentication adoption curves, and compliance-driven recurring service contract conversion rates.
Forecasts assume regulatory continuity in IMO ISPS Code enforcement, EU harbor protection frameworks, and U.S. Maritime Transportation Security Act implementation; material policy shifts would require re-modeling. Revision becomes warranted when marine-grade certification laboratory capacity constraints or semiconductor foundry allocation decisions cross thresholds that disrupt equipment delivery timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
India CCTV Market
Security and Surveillance
Alarm Monitoring Software Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
X-Ray Security Screening System Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Middle East and Africa Baggage and Parcel Screening Market
Security and Surveillance
Asia-Pacific Security Services Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
TSCM Equipment Market
Security and Surveillance
5G-Enhanced Surveillance Market
Security and Surveillance
Commercial Security Market
Security and Surveillance
Security Services Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Smart Security Market