
 Global Rodent Control Market | 2026-2036
Global Rodent Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rodent Control Market Foresight
Consolidation among multinational food retailers and cold-chain logistics operators is recalibrating procurement thresholds for rodent control services. BASF SE leverages its agrochemical R&D pipeline to develop restricted-use rodenticides with enhanced target specificity. Rentokil Initial Plc anchors its growth through long-term integrated pest management contracts with institutional property managers across North America and Europe. Ecolab Inc. differentiates by embedding sanitation and rodent control into unified facility service bundles for food processing clients.
Rodent control encompasses the management, exclusion, and elimination of rodent populations through mechanical, chemical, electronic, and biological interventions, typically involving anticoagulant formulations with active concentrations below 0.005% for restricted-use applications or snap mechanisms with 4-6 kg trigger sensitivity for humane dispatch. Rodenticides retain the largest value share due to recurring bait rotation requirements, though ultrasonic devices are gaining traction in food-sensitive environments where chemical residues face scrutiny. Mechanical traps command premium pricing in residential and commercial establishments where pet safety and non-toxic mandates dominate purchasing criteria. Biological delivery methods remain nascent but attract agricultural facilities seeking resistance-management protocols.
The EPA regulates rodenticide classifications under FIFRA, restricting second-generation anticoagulants to certified applicators and mandling child-resistant packaging standards that elevate manufacturing compliance costs. REACH and the EU Biocidal Products Regulation govern active substance approvals in Europe, creating multi-year registration timelines that limit new entrant market access. Stakeholders must monitor regulatory divergence between jurisdictions, as the shift toward non-anticoagulant chemistries and digital monitoring systems demands parallel investment portfolios rather than single-technology bets.
Market Dynamics
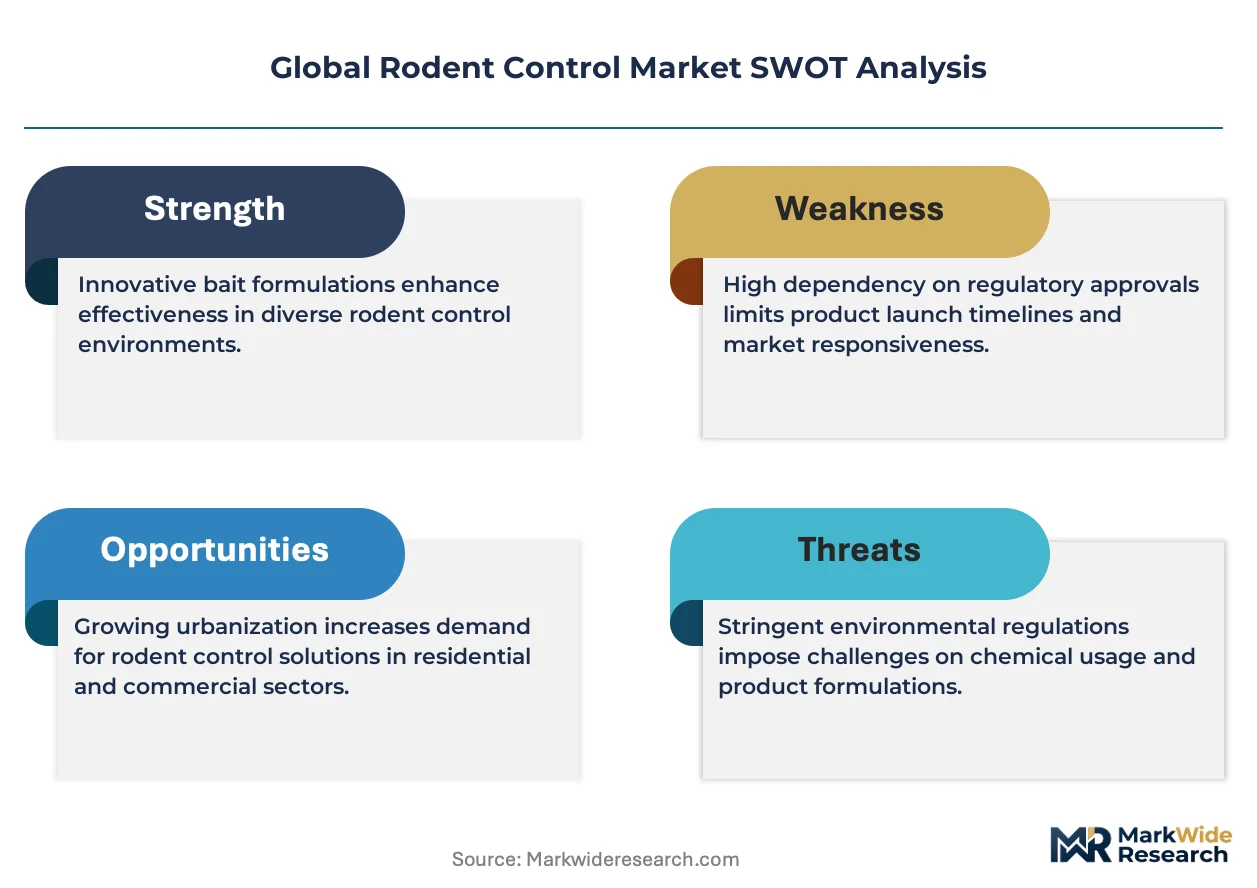
Second-generation anticoagulant restrictions under EPA and REACH are compressing chemical rodenticide availability while accelerating investment in non-toxic alternatives and digital monitoring infrastructure across food processing and logistics facilities.
Growth Catalysts
- FSMA residue mandates:Food Safety Modernization Act requirements tighten traceability standards, forcing processing plants toward integrated pest management programs with documented exclusion protocols.
- Warehouse construction velocity:Cold-chain expansion in the United States, Germany, and China generates recurring service contract demand from institutional property managers seeking preventive rodent exclusion.
- Ultrasonic device maturation:Frequency-modulation advances enable effective rodent deterrence in grain storage facilities without chemical residue complications.
Market Restraints
- Active ingredient supply concentration:Bromadiolone and difenacoum production clusters in China create vulnerability to export license disruptions and price volatility.
- REACH registration timelines:Multi-year biocidal product authorization processes under EU BPR limit new entrant market access and freeze formulation innovation cycles.
- Anticoagulant resistance spread:Target rodent populations in urban centers develop VKORC1 mutations, degrading efficacy of first-line chemical interventions.
Strategic Opportunities
- Indian food retail formalization:Organized grocery expansion under FSSAI hygiene codes creates first-mover advantage for IPM service providers in Tier-2 cities.
- IoT trap convergence:Sensor-enabled mechanical traps combining real-time alerts with humane dispatch address premium residential demand for pet-safe monitoring.
- Biological delivery systems:Contraceptive bait formulations attract agricultural facilities seeking resistance-management protocols compliant with organic certification.
Industry Challenges
- Certified applicator scarcity:EPA restricted-use pesticide licensing requirements outpace vocational training pipeline expansion, constraining service capacity in high-growth metro corridors.
- Legacy bait rotation compliance:Resistance-prevention protocols demand quarterly formulation switches, complicating inventory management and technician retraining schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rodent Control Market |
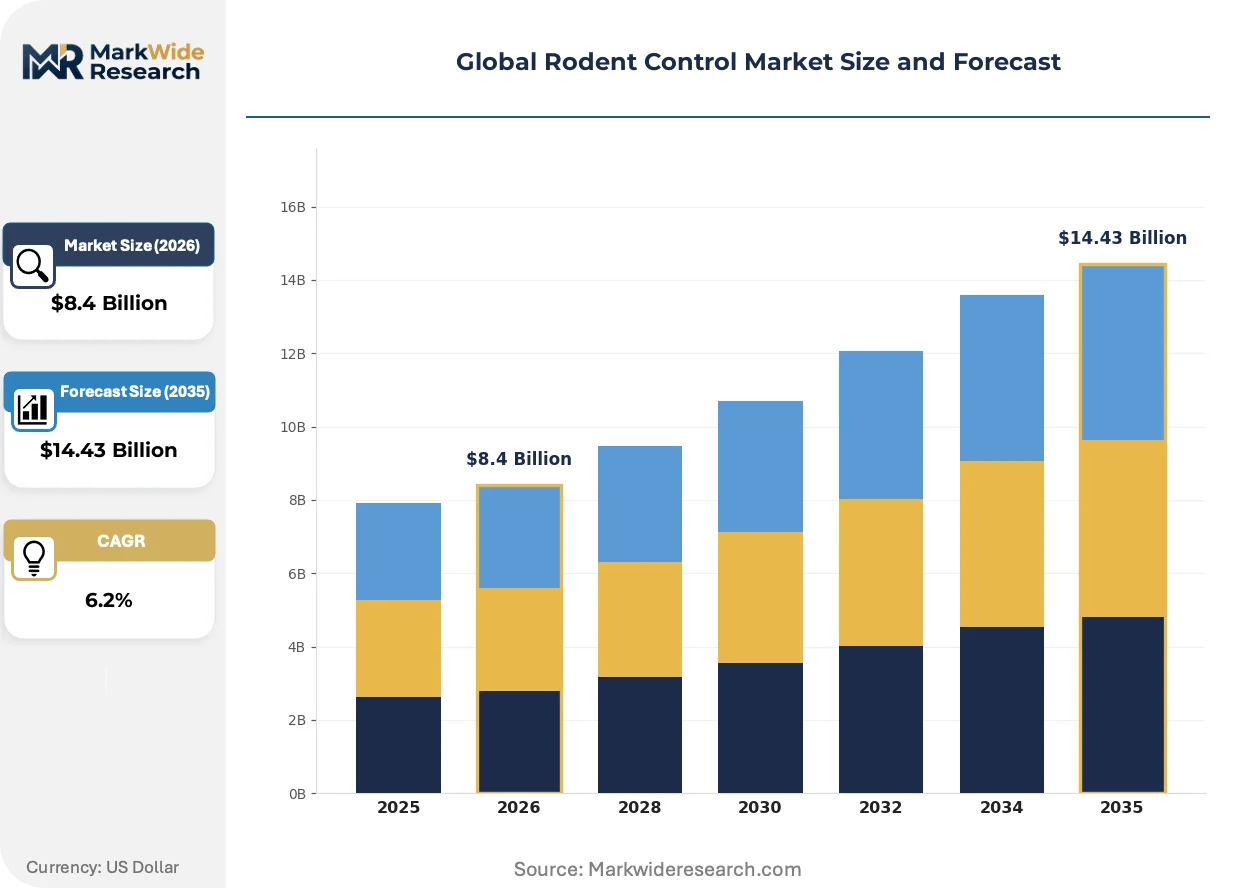
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rodenticides, Traps, Baits, Ultrasonic Devices, Glue Boards Application: Residential, Food Processing Units, Warehouses, Commercial Establishments, Transportation Delivery Method: Mechanical, Chemical, Electronic, Biological End User: Property Managers, Pest Control Operators, Agricultural Facilities, Food Service Providers |
| Companies Covered | Rentokil Initial Plc, BASF SE, Bayer AG, Anticimex International AB, Ecolab Inc., Syngenta Crop Protection AG, Bell Laboratories Inc., Liphatech Inc., Rollins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rodent Control Market Shifts & Advancements
Digital sensing infrastructure and biological intervention methods are displacing conventional chemical-centric approaches, while regulatory divergence between jurisdictions forces parallel technology investment rather than single-platform standardization.
Connected trap networks is electrifying facility management workflows by transmitting real-time capture data to centralized dashboards, enabling predictive intervention scheduling. Food processing auditors in the United States and Germany now specify sensor density minimums in vendor qualification scorecards, compressing response latency from days to hours while reducing routine inspection labor.
REACH authorization reviews under the EU Biocidal Products Regulation are systematically excluding second-generation anticoagulants from consumer-accessible formulations, restricting brodifacoum and flocoumafen to certified professionals. Manufacturers redirect R&D toward cholecalciferol and non-chemical alternatives, with formulation pipelines now split across three distinct active substance categories to hedge regulatory outcomes.
Facility managers increasingly unbundle rodent control from bundled janitorial contracts, issuing standalone IPM tenders with outcome-based performance metrics. Large food retailers in the United States and China now specify zero-tolerance thresholds with penalty clauses, displacing traditional time-and-materials billing with guaranteed-result pricing structures that shift operational risk to service providers.
Global Rodent Control Market Segmentation
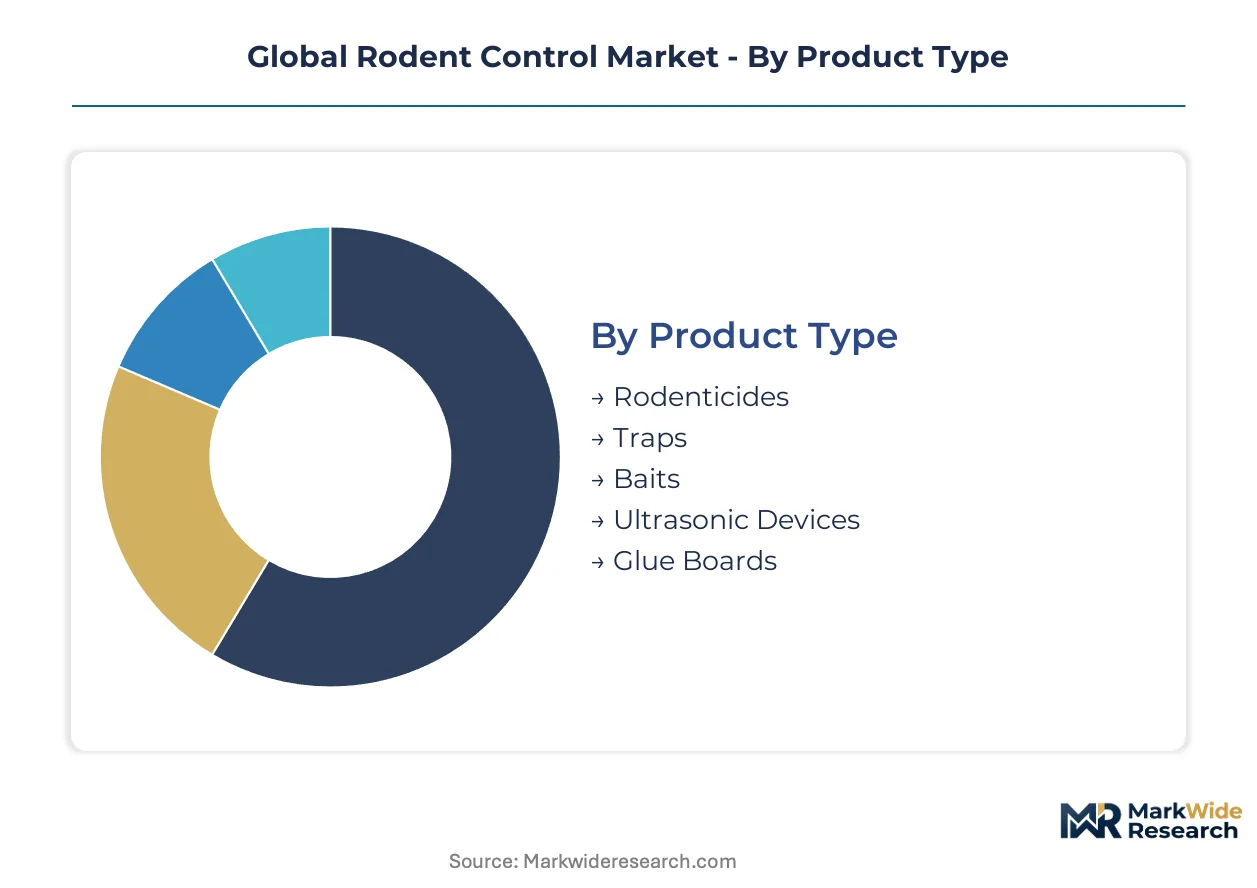
Rodent control procurement varies sharply by facility type and regulatory exposure, with food safety mandates dictating technology selection and service contract structures. Segment boundaries blur where integrated pest management bundles combine chemical, mechanical, and electronic interventions under unified performance guarantees.
Product Type:
Capital intensity peaks in ultrasonic device manufacturing, where frequency-modulation R&D and sensor integration demand sustained engineering investment before commercialization.
- Rodenticides:Anticoagulant formulations with active concentrations below 0.005% dominate restricted-use applications; recurring bait rotation requirements in United States food processing plants sustain recurring revenue streams despite EPA registration burdens.
- Traps:Snap mechanisms with 4-6 kg trigger sensitivity enable humane dispatch; German and Chinese warehouse operators specify pet-safe mechanical alternatives where chemical residues face scrutiny under FSMA and REACH protocols.
- Baits:Palatability-enhanced formulations require quarterly resistance-prevention rotation schedules.
- Ultrasonic Devices:Frequency-modulation advances enable grain storage deployment without residue complications.
- Glue Boards:Adhesive-based capture systems serve residential markets with strict non-toxic mandates.
Rodenticides absorb the bulk of installed capacity; ultrasonic devices are expanding most quickly.
Application:
Volume concentration follows cold-chain construction velocity, with logistics facilities generating recurring preventive maintenance contracts at higher margins than reactive residential calls.
- Food Processing Units:FSMA traceability mandates force documented exclusion protocols; United States and German auditors now specify sensor density minimums in vendor qualification scorecards, compressing response latency from days to hours.
- Warehouses:Cold-chain expansion in the United States, Germany, and China generates institutional property manager demand for preventive rodent exclusion; facility managers increasingly unbundle rodent control from janitorial contracts, issuing standalone IPM tenders with outcome-based performance metrics.
- Residential:Pet safety concerns drive premium pricing for non-toxic mechanical alternatives.
- Commercial Establishments:Zero-tolerance thresholds with penalty clauses displace time-and-materials billing.
- Transportation:Container and vessel inspections under biosecurity protocols create episodic demand spikes.
Warehouses command the largest contract values; food processing units impose the strictest compliance thresholds.
Delivery Method:
Margin profiles diverge where digital infrastructure enables predictive scheduling versus labor-intensive manual inspection rounds.
- Mechanical:Snap traps and glue boards with real-time sensor integration command premium pricing; connected trap networks transmitting capture data to centralized dashboards enable predictive intervention scheduling in United States and German facilities.
- Chemical:Second-generation anticoagulant restrictions under EPA and REACH compress availability while elevating certified applicator requirements; manufacturers split R&D across cholecalciferol and non-chemical alternatives to hedge regulatory outcomes.
- Electronic:Ultrasonic deterrence systems avoid residue complications in grain storage.
- Biological:Contraceptive bait formulations attract agricultural facilities seeking resistance-management protocols compliant with organic certification.
Chemical delivery retains the widest installed base; biological methods are climbing the fastest as resistance spreads.
End User:
Procurement sophistication scales with regulatory exposure, from commodity spot purchases by residential property managers to multi-year integrated pest management contracts with documented audit trails.
- Pest Control Operators:EPA restricted-use pesticide licensing requirements constrain service capacity; vocational training pipeline expansion lags demand growth in high-growth United States metro corridors, compressing available technician supply.
- Property Managers:Institutional clients across North America and Europe anchor long-term integrated pest management contracts with guaranteed-result pricing structures that shift operational risk to service providers.
- Agricultural Facilities:Resistance-management protocols and organic certification compliance drive biological method experimentation.
- Food Service Providers:FSSAI hygiene codes in India create first-mover opportunities for IPM providers in Tier-2 cities.
Pest control operators intermediate the largest transaction volumes; agricultural facilities are gaining share fastest in biological delivery adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for rodent control services concentrates in urban corridors with dense food processing infrastructure and expanding cold-chain logistics. Regulatory divergence between jurisdictions shapes technology deployment patterns. Procurement sophistication varies sharply by local enforcement intensity.
United States
FSMA traceability mandates drive integrated pest management adoption across meatpacking and grain processing facilities. EPA restrictions on second-generation anticoagulants elevate certified applicator requirements and compliance costs. Chicago and Kansas City warehouse clusters generate recurring preventive maintenance contracts as cold-chain construction accelerates.
Germany
REACH authorization reviews under EU BPR systematically exclude brodifacoum and flocoumafen from consumer formulations. Industrial property managers in the Ruhr Valley and Bavaria unbundle rodent control from janitorial contracts, issuing standalone IPM tenders with outcome-based performance metrics. Sensor density minimums now appear in vendor qualification scorecards.
China
Warehouse construction velocity in Yangtze River Delta and Pearl River Delta generates institutional demand for preventive exclusion protocols. Export license volatility for bromadiolone and difenacoum active ingredients creates supply vulnerability. Shanghai and Shenzhen facility managers specify zero-tolerance thresholds with penalty clauses in service agreements.
India
FSSAI hygiene codes governing organized grocery expansion create first-mover opportunities in Tier-2 cities. Maharashtra and Gujarat food retail formalization drives IPM service procurement. Mumbai and Ahmedabad processing plants adopt documented exclusion protocols under tightening residue monitoring.
United Kingdom
Urban rodent populations in London and Birmingham develop VKORC1 mutations, degrading first-line anticoagulant efficacy. HSE enforcement of biocidal product regulations limits new entrant market access. Greater Manchester logistics hubs specify pet-safe mechanical alternatives where chemical residues face scrutiny.
Global Rodent Control Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital monitoring and biological delivery niches. The vendor base splits between multinational agrochemical conglomerates with restricted-use rodenticide portfolios and specialized pest control operators with integrated service capabilities. Three archetypes dominate: R&D-intensive formulators hedging regulatory outcomes, scale-driven service contractors with long-term IPM agreements, and technology specialists embedding sensors into mechanical systems. Competitive moves concentrate on M&A for geographic footprint expansion and strategic partnerships for IoT trap convergence.
Within the multinational formulator tier, BASF SE and Bayer AG exemplify R&D-intensive players splitting active substance pipelines across cholecalciferol and non-chemical alternatives. Among specialized service operators, Rentokil Initial Plc and Ecolab Inc. anchor positions through institutional property manager relationships. Bell Laboratories Inc. represents the mid-scale specialist archetype navigating EPA registration burdens.
| Leading Market Players |
|---|
| Rentokil Initial Plc |
| BASF SE |
| Bayer AG |
| Anticimex International AB |
| Ecolab Inc. |
| Syngenta Crop Protection AG |
| Bell Laboratories Inc. |
| Liphatech Inc. |
| Rollins Inc. |
| Others |
Supply & Pricing Matrix
Institutional property managers in the United States, Germany, and China concentrate procurement volume, locking in long-term integrated pest management contracts with outcome-based pricing that shifts operational risk toward service providers.
Pricing Analysis
Volume concentrates in commodity rodenticide formulations while margins accrue to sensor-enabled mechanical systems and biological delivery methods. Three-tier pricing structure across premium, standard, and economy levels separates connected trap networks with real-time dashboards from basic snap mechanisms and generic anticoagulant baits. Pricing pressure stems from EPA and REACH registration burdens elevating compliance costs for second-generation anticoagulants. Residential buyers exhibit highest price sensitivity, while food processing facilities under FSMA mandates absorb premium pricing for documented exclusion protocols.
Supply Chain Analysis
Certified applicator scarcity in United States metro corridors and REACH-authorized manufacturing zones constrains formulation production capacity and service deployment velocity. Active ingredient production clusters in China for bromadiolone and difenacoum, with secondary formulation capabilities in Germany and the United States. Supply chain risk centers on export license volatility for Chinese-sourced anticoagulants. Distribution runs through pest control operators and direct institutional contracts, bypassing traditional retail channels for restricted-use categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around service providers with integrated digital capabilities, as EPA licensing requirements and sensor infrastructure investments force smaller operators toward acquisition or exit.
For Market Incumbents: Extend certified applicator training pipelines in high-growth United States metro corridors to capture warehouse construction demand before capacity constraints bite. Deepen backward integration into sensor hardware manufacturing to secure supply of IoT-enabled trap components against semiconductor allocation volatility. Lock in multi-year IPM contracts with zero-tolerance penalty clauses to entrench switching costs.
For New Entrants and Emerging Players: Capture biological delivery white space in Indian agricultural facilities seeking FSSAI-compliant resistance management protocols. Penetrate Tier-2 Indian cities ahead of organized grocery formalization, where incumbent service networks remain thin. Lead with contraceptive bait formulations differentiated from anticoagulant commoditization.
For Investors and Strategic Acquirers: The window for entry favors mid-scale specialists with EPA-registered restricted-use portfolios and established technician workforces. Acquisition targets with cholecalciferol pipelines and sensor integration capabilities offer hedge positioning against anticoagulant regulatory exclusion. Watch VKORC1 mutation spread rates in urban rodent populations as signal for biological method inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Trap Convergence | Sensor-enabled mechanical traps with real-time alerts command premium pricing in FSMA-audit environments. |
| Biological Delivery Development | Contraceptive bait formulations attract organic-certified agricultural facilities facing anticoagulant resistance. |
| Certified Applicator Expansion | EPA licensing pipeline investment secures service capacity in Chicago and Kansas City warehouse corridors. |
| Backward Integration into Sensors | In-house production of capture-detection hardware insulates against semiconductor supply volatility. |
| Standalone IPM Contract Unbundling | Outcome-based pricing with penalty clauses shifts operational risk from facility managers to service providers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with pest control operator executives, facility management procurement leads, EPA regulatory affairs specialists, and agricultural extension officers. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level estimates. Secondary sources included EPA FIFRA registration databases, ECHA biocidal product authorization records, FDA FSMA compliance guidance, and cold-chain construction permits from United States, German, and Chinese municipal authorities.
Data-stream reconciliation across product type, application, delivery method, and end-user dimensions informed analytical framework construction across the analysis window. CAGRs derived from segment-level volume projections and value-per-unit assumptions, with explicit modeling of regulatory phase-out timelines for second-generation anticoagulants and sensor adoption curves in food processing audit environments. Forecast inputs incorporated warehouse construction velocity indices and certified applicator pipeline expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization timelines, VKORC1 mutation spread patterns, and Chinese active ingredient export policy shifts. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution elasticities. A small set of named triggers—EPA anticoagulant reclassification, EU BPR substance exclusion announcements, and major food retailer zero-tolerance mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
China Premium Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market