
 Middle East and Africa Cargo Inspection Market | 2026-2036
Middle East and Africa Cargo Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cargo Inspection Market Foresight
Saudi Arabia's port expansion at King Abdullah Economic City is reshaping cargo inspection capacity across the Red Sea corridor. SGS Group leverages its accredited laboratory network to dominate third-party verification in Jeddah and Dammam. Bureau Veritas SA anchors its regional position through marine and commodity inspection protocols tailored to hydrocarbon exports. Intertek Group plc competes on petroleum testing specialization, while Cotecna Inspection SA sustains government contract relationships across Francophone Africa.
Middle East and Africa cargo inspection encompasses the systematic examination of goods, vessels, and transport infrastructure using non-destructive testing protocols including gamma ray transmission and optical scanning systems to detect contraband, verify trade documentation, and enforce customs compliance. The primary purpose centers on securing supply chain integrity while facilitating legitimate commerce across maritime, air, and land border crossings. Container inspection services command the largest service type share due to volume throughput at regional transshipment hubs. X-ray technology leads the technology dimension given its operational maturity, though optical scanning is gaining traction for perishable and high-value cargo screening.
SFDA and Saudi Customs Authority frameworks mandate phased inspection upgrades for food and pharmaceutical imports, while UAE Federal Customs Authority regulations enforce WCO SAFE standards across Dubai and Abu Dhabi ports. These requirements directly shape procurement specifications for inspection equipment and service provider accreditation. Stakeholders must monitor evolving dual-use export controls and harmonization between Gulf Cooperation Authority customs unions and national sovereignty over border enforcement.
Market Dynamics
Port modernization across the United Arab Emirates is compressing inspection cycles while raising throughput requirements, forcing customs authorities to reconcile speed mandates with security protocols.
Growth Catalysts
- SFDA and Saudi Customs Authority frameworks:Phased inspection upgrades for food and pharmaceutical imports are mandating new equipment procurement across Jeddah and Dammam corridors.
- Container inspection services:Volume throughput at regional transshipment hubs is pulling investment toward automated scanning infrastructure.
- South Africa's logistics corridor:Concentrated demand from mineral and automotive export flows is sustaining inspection service contracting.
Market Restraints
- Gamma ray equipment supply concentration:Dependence on specialized radiography component manufacturers in Europe and North America creates procurement bottlenecks.
- WCO SAFE standard implementation costs:UAE Federal Customs Authority enforcement is imposing capital requirements that strain smaller port operators.
- Optical scanning technical limitations:Perishable cargo screening remains constrained by false-positive rates in high-humidity environments.
Strategic Opportunities
- Francophone Africa government contracts:Underpenetrated customs modernization programs in Senegal and Côte d'Ivoire present white space for accredited service providers.
- Dual-use export control harmonization:Gulf Cooperation Authority customs union alignment is creating unified procurement specifications across member states.
- X-ray and optical convergence:Hybrid scanning systems combining transmission imaging with spectral analysis are opening new service tiers for high-value cargo.
Industry Challenges
- Certified radiographic technician scarcity:SFDA and MOHAP accreditation requirements are outpacing regional training pipeline capacity.
- Legacy analog system integration:Customs authorities in older ports face friction retrofitting digital inspection protocols onto 1990s-era infrastructure.
- Dual-use technology licensing complexity:Gamma ray transmission equipment falls under export control classifications that delay deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cargo Inspection Market |
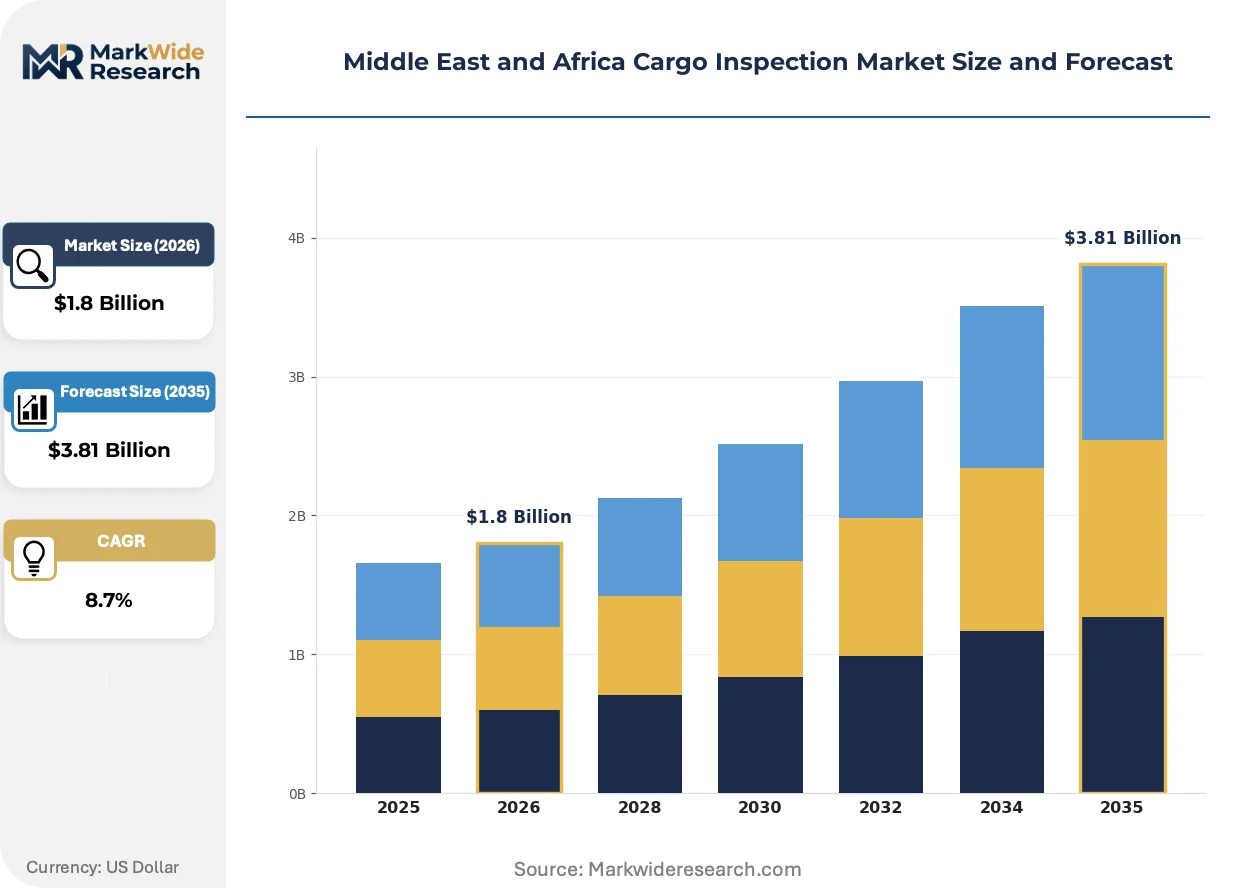
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Container Inspection, Freight Inspection, Equipment Inspection, Personnel Inspection Technology: X-Ray, Gamma Ray, Metal Detection, Optical Scanning End User: Government Agencies, Shipping Companies, Logistics Providers, Customs Authorities Application: Import Compliance, Export Compliance, Security Screening, Quality Control |
| Companies Covered | Cotecna Inspection SA, Peterson and Control Union BV, SGS Group, Alfred H Knight International Limited, AIM Control Inspection Group of Companies, Bureau Veritas SA, ALS Limited, Commodity Inspection Services, Intertek Group plc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cargo Inspection Market Shifts & Advancements
Non-destructive testing protocols are compressing inspection dwell times while raising detection thresholds, reshaping how customs authorities balance security mandates against trade facilitation imperatives.
Automated optical scanning systems equipped with machine learning classification algorithms are rendering obsolete manual document verification stations at high-volume ports. Dubai Customs and Abu Dhabi terminals are deploying these systems for perishable and pharmaceutical cargo lanes. The technology is rendering obsolete shift-based inspector staffing models while compressing average container release times.
UAE Federal Customs Authority regulations enforcing WCO SAFE standards are mandating advance cargo information systems and risk-based targeting protocols across Dubai and Abu Dhabi ports. Industrial consequence includes mandatory accreditation upgrades for third-party inspection service providers. Container inspection services face the steepest compliance timelines, with providers accelerating ISO 17020 certification renewals.
Buyer concentration among national customs authorities is consolidating contract awards toward accredited laboratory networks with multi-port presence. Traditional single-location inspection firms are losing share to integrated service providers offering hydrocarbon testing alongside cargo screening. Saudi Arabia's port expansion at King Abdullah Economic City exhibits this pattern most visibly, with bundled service contracts displacing standalone commodity inspection awards.
Middle East and Africa Cargo Inspection Market Segmentation
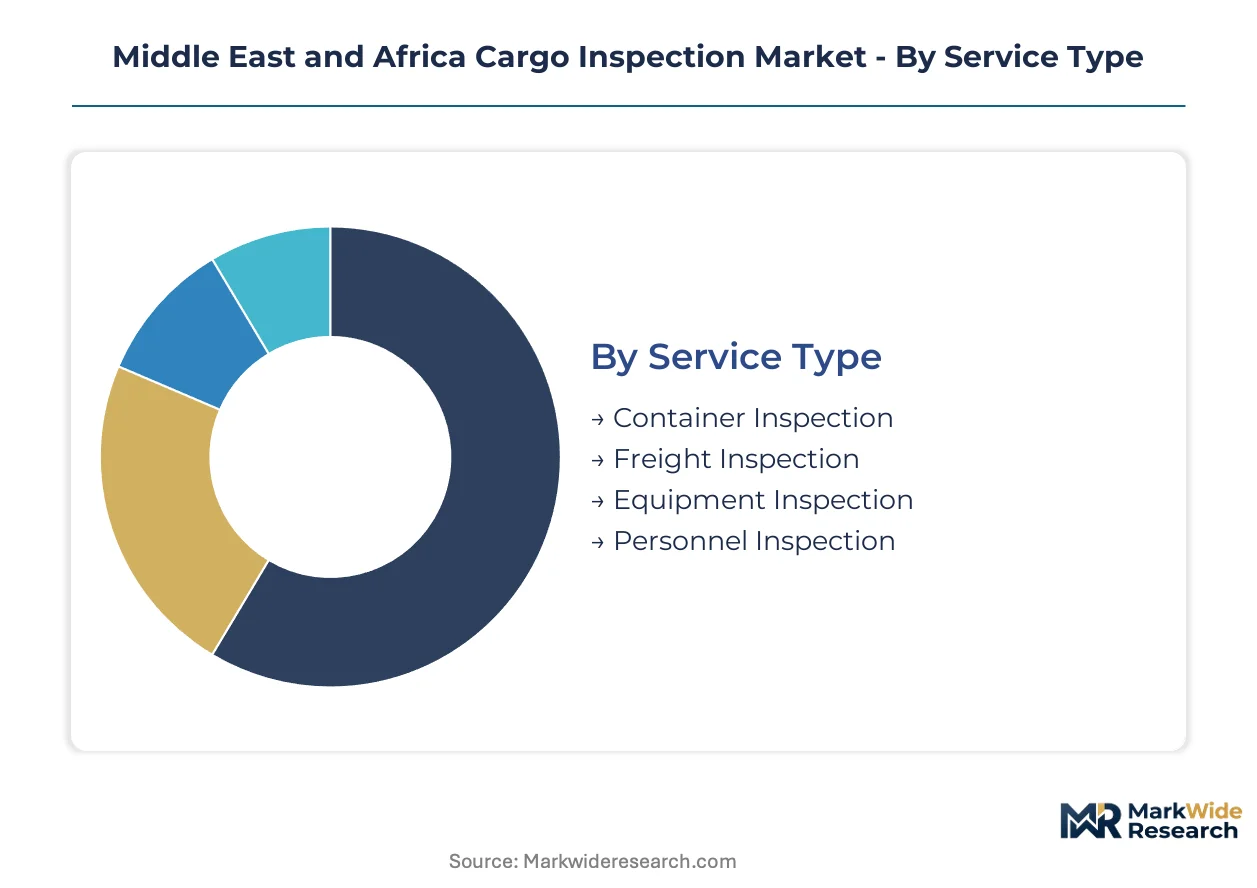
Cargo inspection procurement patterns diverge sharply across service modalities and enforcement contexts. Technology selection and end-user mandates reshape how inspection capacity deploys across maritime corridors and land border crossings.
Service Type:
Inspection protocols span from high-volume container screening to specialized personnel verification, each commanding distinct equipment specifications and accreditation requirements.
- Container Inspection:Automated scanning systems examine sealed shipping units using non-destructive transmission imaging to detect contraband, verify manifest declarations, and enforce customs compliance without physical breach. Volume throughput at Jeddah and Dubai transshipment hubs is compressing dwell times while raising throughput requirements, forcing customs authorities to reconcile speed mandates with security protocols.
- Freight Inspection:Break-bulk and loose cargo screening applies handheld and portal detection systems to palletized goods, bulk commodities, and irregular shipments outside standard container dimensions. South Africa's logistics corridor sustains concentrated contracting for mineral and automotive export flows where freight inspection protocols verify commodity grades and origin documentation.
- Equipment Inspection:Crane, chassis, and handling machinery certification ensures port infrastructure safety compliance and operational integrity across loading and unloading cycles.
- Personnel Inspection:Access control and worker screening protocols secure restricted zones within port perimeters and customs facilities through biometric and credential verification systems.
The dominant share belongs to Container Inspection, while Freight Inspection is closing the gap fastest.
Technology:
Detection modalities range from mature radiographic systems to emerging spectral analysis, with procurement decisions trading off penetration depth against operational speed and material discrimination.
- X-Ray:Transmission imaging systems generate high-resolution cargo content visualization through differential absorption mapping, enabling automated threat recognition algorithms. Operational maturity and established maintenance networks across UAE and Saudi ports sustain X-ray technology's procurement preference despite higher capital requirements than alternative modalities.
- Gamma Ray:Cobalt-60 or cesium-137 source radiography penetrates dense cargo loads including steel-walled containers and shielded compartments impervious to lower-energy systems. Dependence on specialized radiography component manufacturers in Europe and North America creates procurement bottlenecks that delay deployment timelines across African customs modernization programs.
- Metal Detection:Ferromagnetic and non-ferrous material identification systems screen for weapons, ammunition, and metallic contraband through electromagnetic field disturbance analysis.
- Optical Scanning:Machine vision and spectral imaging systems classify cargo contents through surface reflectance patterns, document authentication, and container seal integrity verification.
X-Ray systems command the installed base majority, though Optical Scanning is expanding most quickly in perishable and pharmaceutical lanes.
End User:
Procurement authority concentrates among sovereign enforcement bodies, with private sector demand emerging around compliance verification and risk mitigation services.
- Government Agencies:National security, defense, and cross-border enforcement directorates mandate inspection protocols for dual-use goods, sanctioned entity screening, and strategic material controls. SFDA and Saudi Customs Authority frameworks mandate phased inspection upgrades that directly shape equipment procurement specifications and service provider accreditation.
- Customs Authorities:Revenue collection and trade facilitation agencies operate primary inspection infrastructure at ports of entry, balancing duty assessment accuracy against cargo release velocity. UAE Federal Customs Authority regulations enforcing WCO SAFE standards impose capital requirements that strain smaller port operators while consolidating contract awards toward accredited laboratory networks.
- Shipping Companies:Container lines and vessel operators deploy pre-loading verification to minimize destination port delays and customs penalties.
- Logistics Providers:Third-party freight forwarders and supply chain integrators subscribe to inspection services for client compliance assurance and insurance underwriting.
Customs Authorities retain the largest contract volume, with Government Agencies climbing the fastest on security-driven procurement.
Application:
Inspection deployment aligns with distinct regulatory objectives spanning revenue protection, threat interdiction, and quality assurance.
- Import Compliance:Duty assessment, tariff classification verification, and trade agreement eligibility confirmation protect domestic revenue bases while enforcing preferential trade regime integrity. SFDA frameworks for food and pharmaceutical imports mandate laboratory testing integration that extends inspection cycles beyond pure document verification.
- Security Screening:Contraband detection, weapons interdiction, and counter-terrorism protocols prioritize threat identification over commercial facilitation. NMPA-equivalent standards for cross-border security are tightening inspection protocols across Middle East corridors.
- Export Compliance:Sanctions enforcement, dual-use technology controls, and destination verification prevent diversion of controlled goods to prohibited end-users.
- Quality Control:Pre-shipment inspection and certificate of conformity issuance verify product specifications match contractual and regulatory requirements.
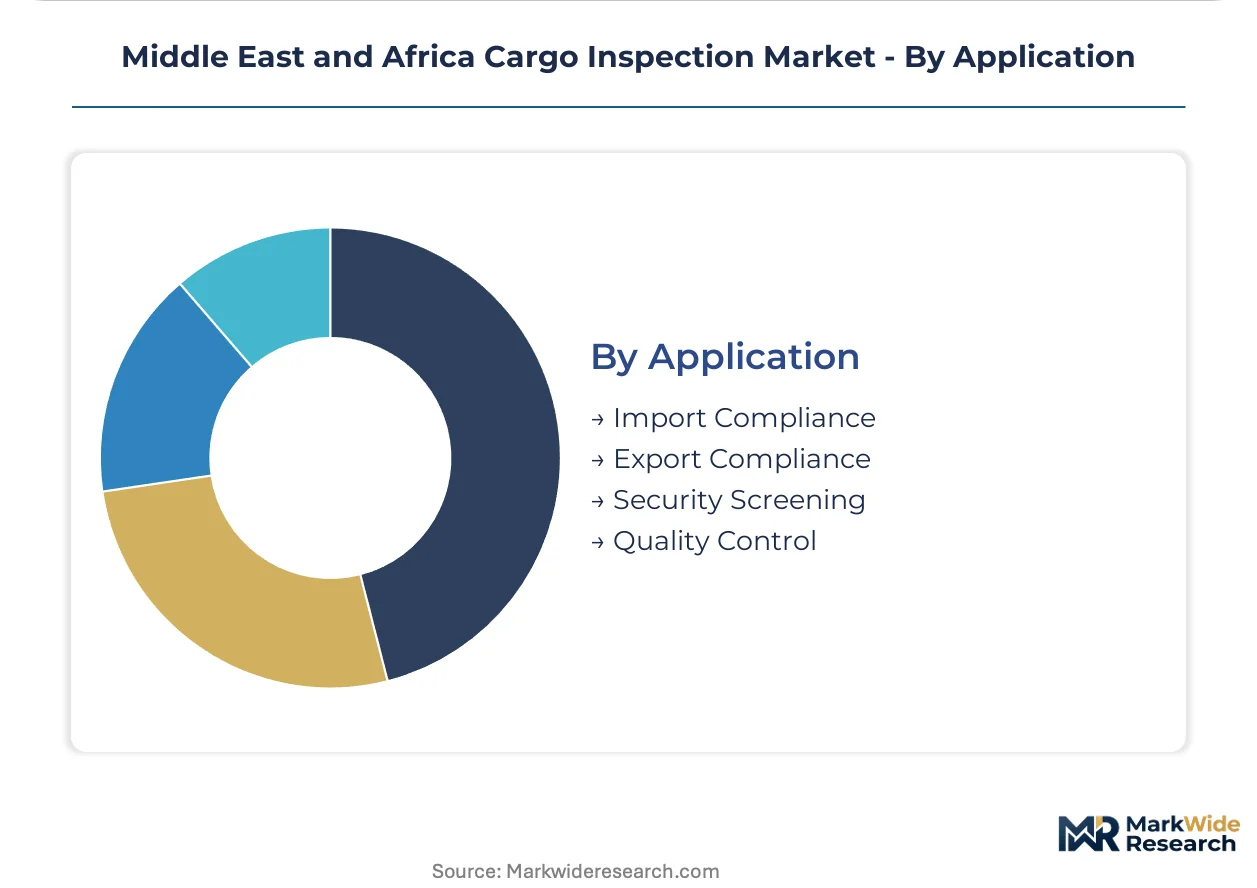
Import Compliance generates the highest service volume, while Security Screening is gaining share fastest on threat environment intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cargo inspection deployment varies sharply across the Middle East and Africa, with Gulf states prioritizing automated transshipment throughput while African corridors emphasize mineral export verification and cross-border security protocols.
United Arab Emirates
Dubai and Abu Dhabi ports drive demand for optical scanning integration alongside X-ray infrastructure to handle perishable pharmaceutical lanes. UAE Federal Customs Authority regulations enforcing WCO SAFE standards mandate advance cargo information systems across Jebel Ali and Khalifa terminals. Abu Dhabi terminals are deploying machine learning classification algorithms that compress container release times while maintaining security thresholds.
Saudi Arabia
King Abdullah Economic City port expansion is pulling investment toward bundled hydrocarbon testing and cargo screening services across the Red Sea corridor. SFDA frameworks mandate phased inspection upgrades for food and pharmaceutical imports that directly shape equipment procurement specifications. Jeddah and Dammam corridors are consolidating contract awards toward accredited laboratory networks with multi-port presence.
South Africa
The logistics corridor sustains concentrated demand for mineral and automotive export flows where freight inspection protocols verify commodity grades and origin documentation. National customs modernization programs are tightening inspection protocols for strategic material controls and sanctioned entity screening. Durban and Cape Town terminals anchor inspection capacity for break-bulk cargo screening outside standard container dimensions.
Nigeria
Lagos port complexes are retrofitting digital inspection protocols onto legacy analog infrastructure from the 1990s era, creating friction in deployment timelines. The country's national customs authority is implementing risk-based targeting protocols that strain smaller port operators with capital requirements. Apapa and Tin Can Island terminals are focal points for container inspection service contracting as throughput volumes expand.
Egypt
Suez Canal transit cargo is driving demand for rapid screening systems that minimize vessel dwell times without compromising contraband detection thresholds. National security directorates are mandating inspection protocol upgrades for dual-use goods and strategic material controls. Alexandria and Damietta ports are concentrating government agency procurement for cross-border enforcement infrastructure.
Middle East and Africa Cargo Inspection Market Competitive Landscape
Capability concentration sits with accredited laboratory networks possessing multi-port presence; scale advantage sits with integrated service providers offering bundled hydrocarbon testing alongside cargo screening. The vendor base organizes around three strategic archetypes: global inspection conglomerates with marine and commodity specialization, regional players anchored in Francophone or Anglophone African government relationships, and niche technicians focused on petroleum testing or perishable cargo lanes. Dominant competitive moves include ISO 17020 certification renewals to maintain customs authority contract eligibility and strategic partnerships with European radiography component manufacturers to secure gamma ray equipment supply.
Among Switzerland-based inspection specialists, Cotecna Inspection SA and SGS Group occupy positions within the government contract tier across Francophone Africa and Gulf Cooperation Authority member states. Bureau Veritas SA, structured as a French S.A., exemplifies the marine and commodity inspection archetype through its regional protocol tailoring. These three entities represent the accredited laboratory network concentration that is displacing single-location inspection firms at major transshipment hubs.
| Leading Market Players |
|---|
| Cotecna Inspection SA |
| Peterson and Control Union BV |
| SGS Group |
| Alfred H Knight International Limited |
| AIM Control Inspection Group of Companies |
| Bureau Veritas SA |
| ALS Limited |
| Commodity Inspection Services |
| Intertek Group plc |
| Others |
Supply & Pricing Matrix
Undercapacity in gamma ray transmission equipment across African customs modernization programs is compressing supplier margins while elevating pricing power for European and North American radiography component manufacturers serving Jeddah and Dammam corridors.
Pricing Analysis
Long-term offtake contracts dominate procurement between accredited laboratory networks and UAE Federal Customs Authority, though spot purchasing persists for emergency equipment replacement in legacy analog ports. Three-tier pricing structure across ISO 17020 premium certification, standard accreditation, and uncertified economy service levels reflects capability differentiation. Cost compression in economy tiers is intensifying because smaller port operators strain under WCO SAFE implementation capital requirements. Government agencies exhibit lowest price sensitivity given security mandates, while logistics providers face acute margin pressure from bundled service commoditization.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for European radiography component manufacturers supplying cobalt-60 and cesium-137 sources to Middle East customs authorities. Manufacturing concentration in Germany, France, and the United States creates procurement bottlenecks for gamma ray transmission systems. Component supply draws from specialized radiography source producers, optical scanning sensor fabricators, and machine learning classification algorithm developers. Single-source vulnerability in isotope supply chains poses structural risk given dual-use technology licensing complexity. Distribution runs through accredited laboratory networks with multi-port presence rather than single-location inspection firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating toward national customs authorities with multi-port accreditation requirements, fragmenting contract awards away from standalone commodity inspection providers across Gulf Cooperation Authority member states.
For Market Incumbents: Entrench market position through ISO 17020 certification renewals ahead of SFDA-mandated inspection upgrade deadlines and strategic partnerships with European radiography component manufacturers to secure gamma ray equipment allocation. Capacity addition in King Abdullah Economic City corridor addresses bundled hydrocarbon testing demand displacement threat. Certification investment represents the critical defensive lever against integrated service provider competition.
For New Entrants and Emerging Players: Francophone Africa government contracts in Senegal and Côte d'Ivoire present the most penetrable white space given underpenetrated customs modernization programs and Cotecna Inspection SA relationship concentration. Optical scanning specialization for perishable pharmaceutical lanes offers second entry vector against X-ray incumbent dominance. Go-to-market angle should emphasize machine learning classification algorithm deployment for document verification automation.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because customs authority contract tenure extends across equipment replacement cycles and accreditation dependency creates switching costs. Acquisition target archetype: accredited laboratory networks with existing SFDA or MOHAP relationships and multi-port presence. Signal to watch is Gulf Cooperation Authority customs union alignment progress creating unified procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17020 Certification Renewal | Maintains customs authority contract eligibility under UAE Federal Customs Authority WCO SAFE enforcement. |
| Machine Learning Classification Deployment | Compresses container release times at Dubai and Abu Dhabi pharmaceutical cargo lanes. |
| European Radiography Partnership | Secures cobalt-60 and cesium-137 supply allocation against procurement bottlenecks. |
| Francophone Africa Geographic Expansion | Captures white space in Senegal and Côte d'Ivoire customs modernization programs. |
| Hybrid X-Ray Optical Convergence | Opens premium service tiers for high-value cargo screening with spectral analysis integration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs authority procurement records, WCO SAFE implementation documentation, and radiography equipment trade data. Primary interviews engaged customs technology procurement officers, accredited laboratory network executives, port infrastructure planners, and SFDA regulatory compliance leads. Secondary validation drew from UAE Federal Customs Authority enforcement circulars, Saudi Customs Authority framework publications, and Gulf Cooperation Authority harmonization protocols. Bottom-up equipment installation tracking and top-down contract value aggregation provided triangulation across the analysis window.
Forecast inputs include service type segmentation by container, freight, equipment, and personnel inspection modalities; technology dimension spanning X-ray, gamma ray, metal detection, and optical scanning systems; and end-user categories across government agencies, customs authorities, shipping companies, and logistics providers. CAGRs derive from regression against port throughput expansion, regulatory mandate phase-in schedules, and equipment replacement cycles. Industry-specific inputs encompass radiography technician training pipeline capacity and dual-use technology licensing approval timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated hydrocarbon testing providers or optical scanning specialists would shift outcomes. Macroeconomic deviation in mineral export flows, regulatory acceleration in Gulf Cooperation Authority harmonization, or technological breakthrough in spectral analysis detection thresholds would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Intrusion Alarm System Market
Security and Surveillance
North America Wireless Monitoring and Surveillance Market
Security and Surveillance
Residential Security Market
Security and Surveillance
Smart Home Security Market
Security and Surveillance
Security Holograms Market
Security and Surveillance
India Electronic Security Market
Security and Surveillance
Stadium Security Market
Security and Surveillance
Europe Security Assurance Market
Security and Surveillance
Global Container Security Market
Security and Surveillance
Middle East and Africa Baggage and Parcel Screening Market
Security and Surveillance
Global Law Enforcement Software Market
Security and Surveillance
Lawful Interception Market
Security and Surveillance
Ballistic Protection Scanners Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Asia-Pacific Urban Security Screening Market