
 Underwater Security (Systems and Services) Market | 2026-2036
Underwater Security (Systems and Services) Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Security (Systems and Services) Market Analytics
Acoustic sensor fusion with artificial intelligence is fragmenting traditional sonar-dominated architectures into layered detection ecosystems. Thales Group leverages its seabed warfare integration heritage to anchor European naval programs with multi-static sonar arrays. Saab competes through autonomous underwater vehicle swarming capabilities that extend Nordic coastal defense perimeters. L3Harris Technologies, Inc. dominates undersea communication links, sustaining interoperability across NATO underwater networks.
Underwater security encompasses systems and services designed to detect, track, classify, and neutralize subsea threats across port facilities, maritime boundaries, and critical infrastructure zones, typically operating at depths from littoral shallows to full ocean pressure ratings exceeding 6000 meters. The primary commercial purpose centers on protecting subsea cables, offshore energy installations, and naval assets from intrusion, sabotage, or unauthorized surveillance. Surveillance systems command the largest value pool given their capital intensity and integration complexity, while monitoring solutions represent the fastest-expanding segment as persistent seabed sensing shifts from episodic patrol to continuous automated coverage. Sonar technology retains structural dominance in detection fidelity, though AUVs are displacing crewed platforms for mine countermeasures and infrastructure inspection where human risk proves unacceptable.
The US Navy's Unmanned Campaign Framework and NATO's Maritime Strategy for 2030 collectively shape procurement standards for interoperability and autonomous system certification. The US Coast Guard's port security regulations and the International Maritime Organization's ISPS Code mandate layered underwater detection at critical infrastructure facilities, directly stimulating intrusion detection and integration service demand. Stakeholders must weigh sovereign technology development against alliance interoperability requirements as allied navies diverge on classified versus commercial acoustic processing standards.
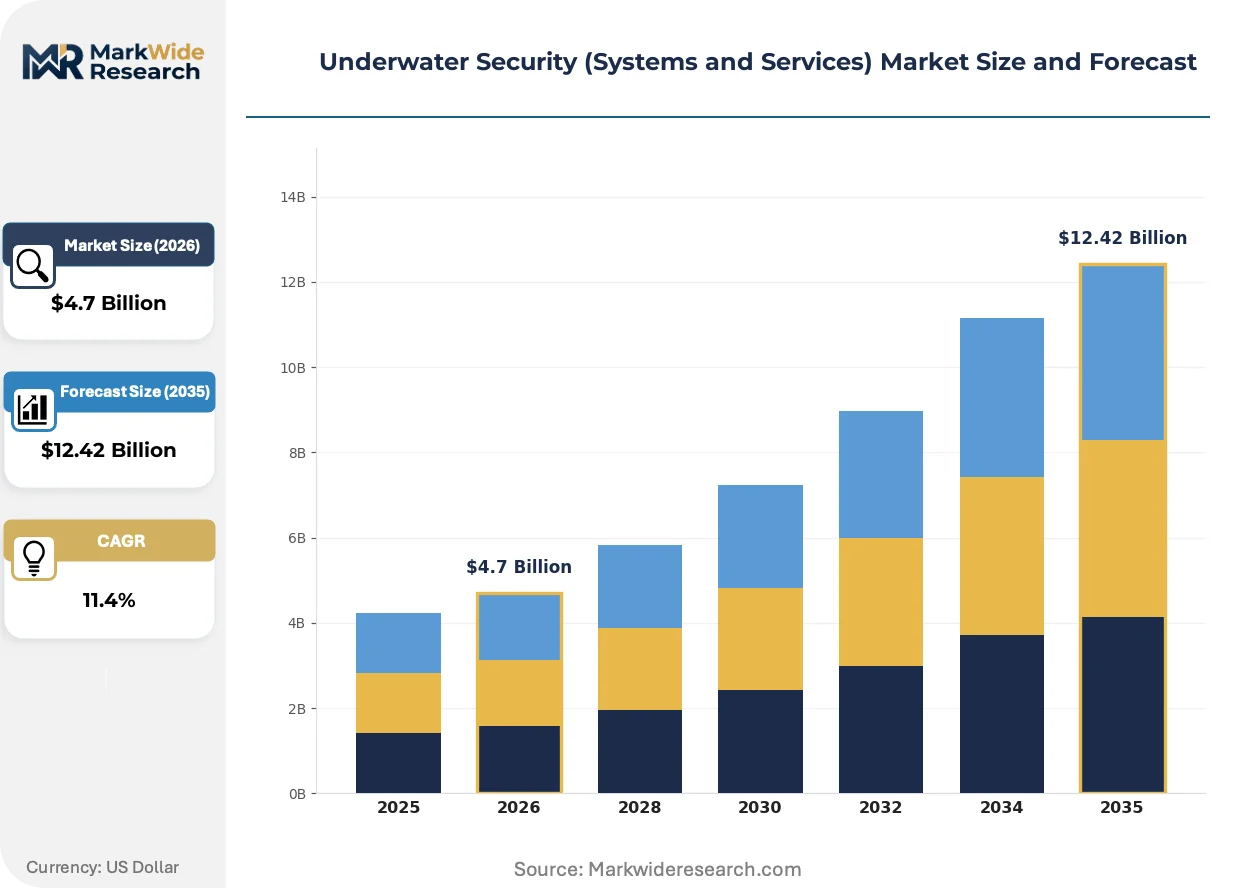
Market Dynamics
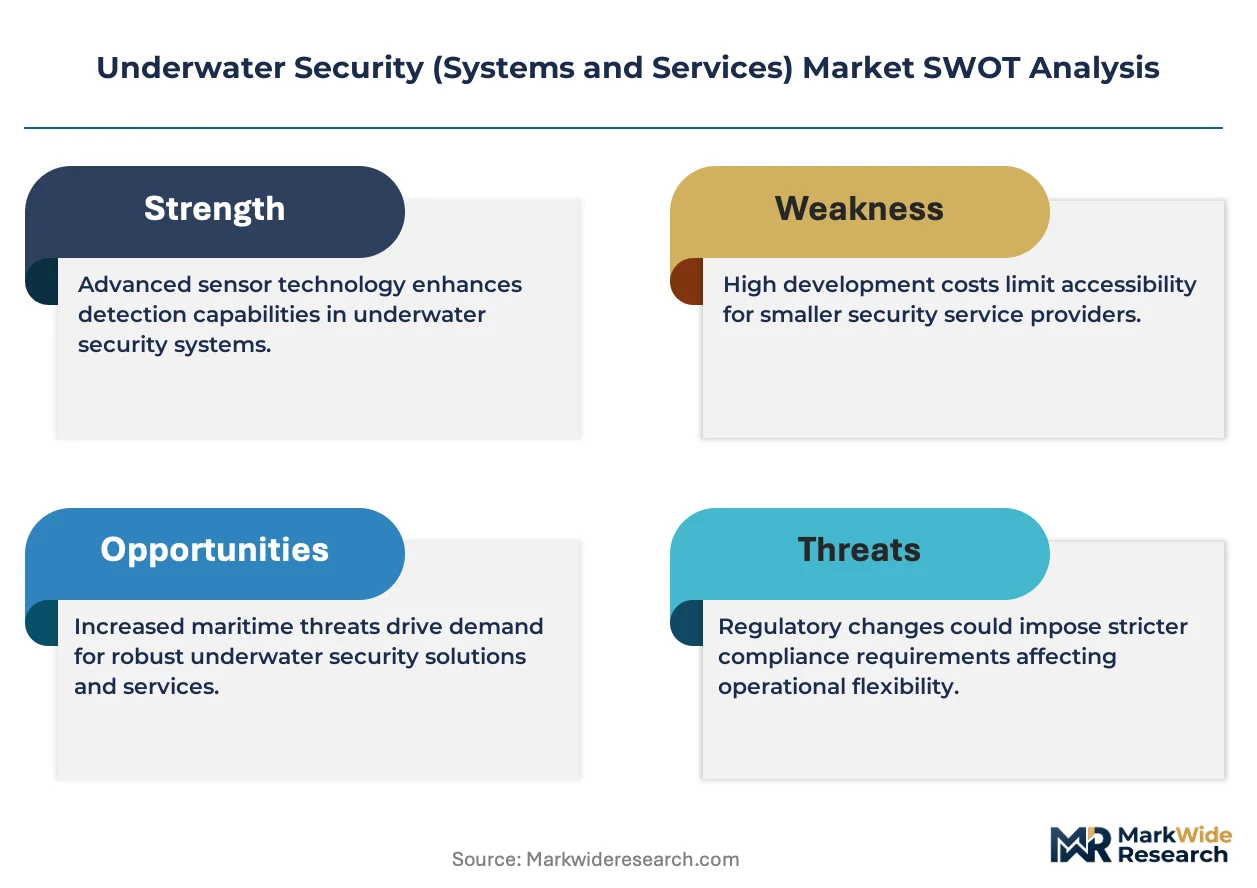
Acoustic sensor fusion with artificial intelligence is fragmenting traditional sonar-dominated architectures into layered detection ecosystems, compressing procurement cycles and redefining interoperability standards across NATO naval programs.
Growth Catalysts
- US Navy's distributed maritime operations doctrine:This operational framework mandates networked undersea sensing across dispersed platforms, accelerating procurement of integrated sonar and autonomous vehicle systems for contested littoral zones.
- Critical subsea cable protection mandates:Territorial seabed disputes in the Indo-Pacific have elevated subsea infrastructure to national security priority status, stimulating persistent monitoring solutions at cable landing stations and transit corridors.
- Artificial intelligence-enabled acoustic processing:Machine learning classification of contact signatures reduces false alarm rates and operator burden, enabling scaled deployment of unmanned surveillance nodes without proportional manpower expansion.
Market Restraints
- Titanium alloy and rare earth magnet supply concentration:Deep-rated pressure hull materials and high-performance sensor components face sourcing constraints from limited qualified suppliers, exposing programs to price volatility and delivery risk.
- Classified acoustic processing standard fragmentation:Divergence between allied national security classification regimes for sonar algorithms creates integration friction in multinational NATO procurement frameworks.
- Human-rated platform substitution ceiling:Crewed submarines and surface vessels retain operational authority for kinetic engagement decisions, capping autonomous system mission scope in contested environments.
Strategic Opportunities
- Arctic seabed domain awareness gaps:Diminishing ice coverage has exposed previously inaccessible submarine transit routes and resource claims, creating demand for persistent under-ice sensing infrastructure.
- Offshore wind farm security integration:Floating and fixed-bottom turbine arrays require co-located intrusion detection, offering dual-use technology deployment at civilian energy installations.
- Commercial synthetic aperture sonar convergence:Fusion of military-grade signal processing with seabed survey economics is opening new service revenue streams in infrastructure integrity monitoring.
Industry Challenges
- Subsea systems engineering talent scarcity:Deep ocean pressure engineering and acoustic physics specialization pools are concentrated within defense primes and national laboratories, constraining supplier base expansion.
- Autonomous system certification timeline compression: NATO interoperability standards and national safety-of-navigation approvals require concurrent validation, extending development-to-deployment intervals for novel platforms.
- Legacy analog sonar integration complexity:Brownfield naval platforms with decades-old sensor architectures demand costly middleware development to interface with modern digital networks and AI processing backends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Security (Systems and Services) Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Systems, Intrusion Detection, Monitoring Solutions, Communication Equipment Technology: Sonar, ROVs, AUVs, RFID End User: Government Agencies, Commercial Fisheries, Oil & Gas, Maritime Security Service Type: Consulting, Maintenance, Training, Integration |
| Companies Covered | Thales Group, Saab, L3Harris Technologies, Inc., Kongsberg Mesotech Ltd., Sonardyne, Huntington Ingalls Industries, Inc., Ultra Group, DSIT Solutions Ltd., ASELSAN A.Ş., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Security (Systems and Services) Market Evolving Landscape
Underwater security architecture is pivoting from platform-centric to network-centric paradigms, compressing the value chain toward software-defined sensing and service-based capability delivery.
Multi-static sonar arrays coordinated through low-latency undersea communication links are rendering obsolete monolithic hull-mounted systems that rely on single-platform source-receiver geometry. Naval procurement offices across NATO member states are mandating modular, open-architecture interfaces that permit rapid algorithm updates without dry-dock hardware modification. The structural consequence is a shift from capital-intensive platform replacement toward iterative software refresh cycles.
China's MEE enforcement of port facility security regulations is mandating layered underwater detection at critical infrastructure nodes, directly stimulating intrusion detection system deployment at commercial maritime facilities. The regulations require integration with national security monitoring networks, blurring the boundary between civilian port operations and defense surveillance architecture. Asian terminal operators are responding by contracting specialized undersea security integrators rather than conventional port engineering firms.
Service unbundling is separating hardware ownership from operational capability in naval procurement frameworks. European defense ministries are piloting seabed-sensing-as-a-service models where contractors retain asset ownership and deliver detection-certainty metrics rather than equipment specifications. The Royal Navy's persistent operational deployment experimentation program exemplifies this shift, transferring mission risk to industrial partners in exchange for guaranteed availability contracts.
Underwater Security (Systems and Services) Market Segmentation
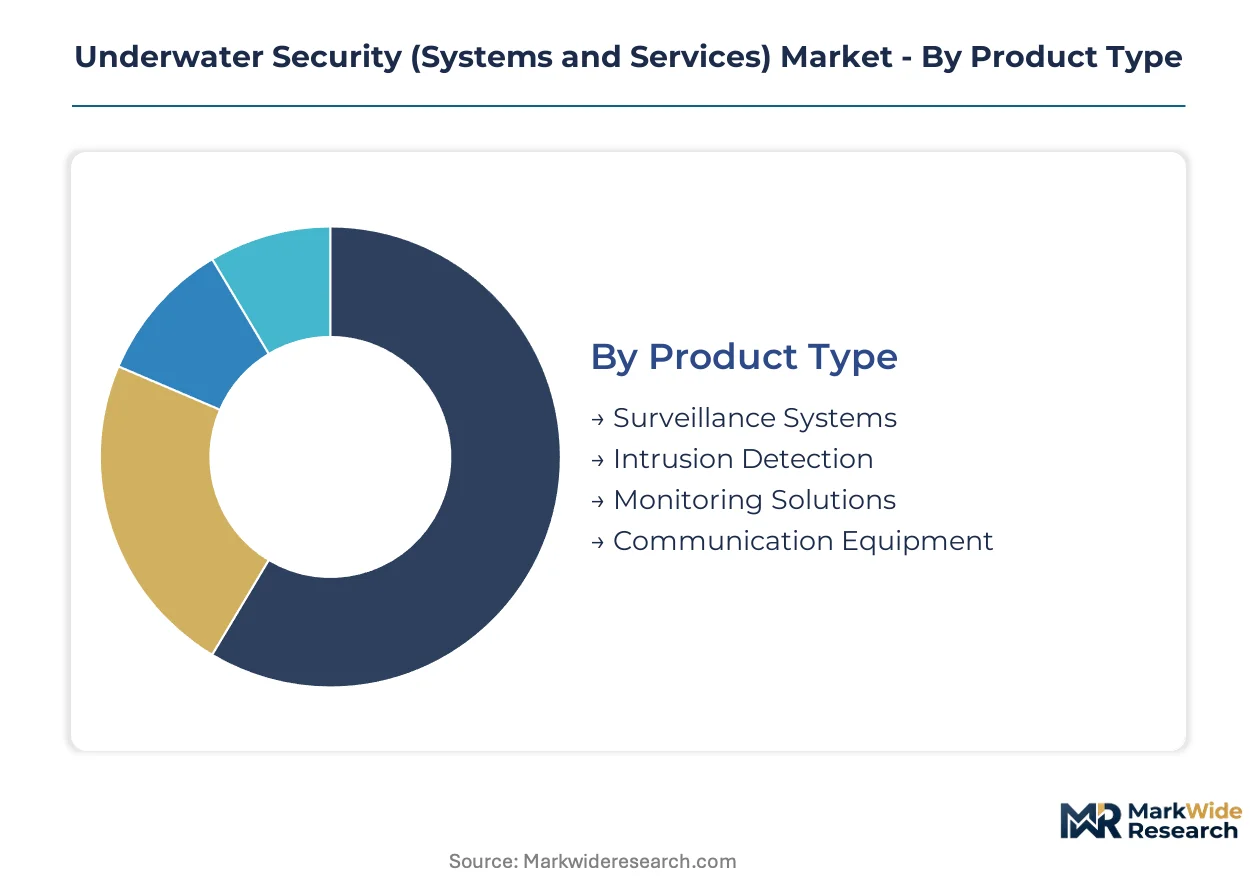
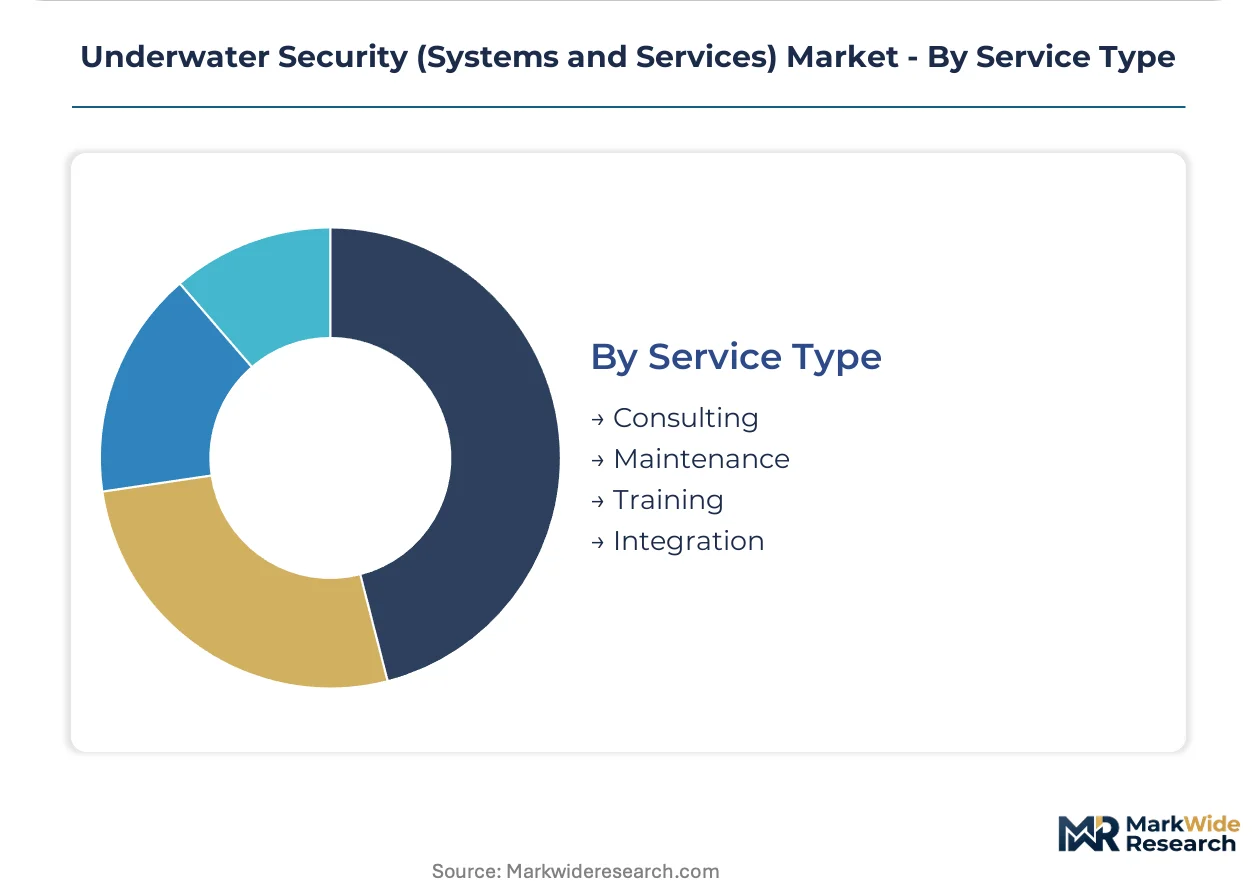
Underwater security procurement fragments across four distinct category axes, each reflecting divergent buyer priorities from capital-intensive platform acquisition to recurring service contracts. Technology selection and end-user mission profiles drive significant variation in pricing structures and supplier engagement models across these segments.
Product Type:
Mature hardware platforms dominate procurement budgets while emerging software-defined alternatives reshape capability delivery timelines.
- Surveillance Systems:Integrated sonar arrays and seabed sensor networks constitute the capital core of naval modernization programs. NATO distributed maritime operations doctrine accelerates demand for networked, multi-static configurations across littoral defense perimeters.
- Monitoring Solutions:Persistent automated sensing platforms with AI-enabled acoustic classification represent the fastest-advancing capability category. Critical subsea cable protection mandates in the Indo-Pacific drive deployment at landing stations and transit corridors where continuous coverage replaces episodic patrol.
- Intrusion Detection:Perimeter security arrays for port facilities and offshore installations. China's MEE port security regulations mandate layered underwater detection at commercial maritime nodes.
- Communication Equipment:Undersea data links and acoustic modems enabling interoperability across distributed platforms. NATO underwater networks require standardized transmission protocols.
Surveillance Systems retain volume leadership; Monitoring Solutions hold the steepest expansion curve.
Technology:
Cost tier stratification separates proven acoustic methods from emerging autonomous platforms requiring extended certification cycles.
- Sonar:Hull-mounted, towed, and seabed-deployed acoustic sensors remain the detection fidelity standard. Signal processing algorithm classification regimes fragment interoperability across allied naval programs.
- AUVs:Autonomous underwater vehicles displace crewed platforms for mine countermeasures and infrastructure inspection. The US Navy's Unmanned Campaign Framework shapes procurement standards for autonomous system certification.
- ROVs:Tethered remotely operated vehicles deliver precision intervention for subsea cable repair and energy installation maintenance. Commercial offshore wind development expands civilian demand.
- RFID:Radio-frequency identification tags support asset tracking and diver identification in confined port environments. Integration with broader security networks remains limited.
Sonar commands the installed base; AUVs are climbing the fastest as operational authority constraints ease.
End User:
Customer type determines procurement authority structures, with sovereign defense buyers operating under classified technology restrictions absent from commercial segments.
- Government Agencies:Naval forces and coast guards drive integrated system-of-systems procurement. The US Coast Guard's port security regulations and NATO Maritime Strategy for 2030 shape capability requirements.
- Maritime Security:Private port operators and terminal managers contract specialized undersea security integrators. Asian terminal operators increasingly bypass conventional port engineering firms.
- Oil & Gas:Offshore platform operators require co-located intrusion detection for subsea infrastructure protection. Floating production systems demand deep-rated pressure hull specifications.
- Commercial Fisheries:Limited adoption concentrates in vessel traffic monitoring and protected marine area enforcement. Budget constraints favor lower-cost surface sensor alternatives.
Government Agencies anchor procurement volume; Maritime Security shows the fastest contract velocity as regulatory mandates proliferate.
Service Type:
Margin structures favor recurring revenue streams over one-time integration fees, with European defense ministries piloting availability-based contracting models.
- Integration:System-of-systems engineering for multi-vendor sensor fusion and command-and-control interface development. Brownfield naval platforms demand costly middleware for legacy analog sonar connectivity.
- Maintenance:Pressure hull integrity verification, sensor calibration, and undersea communication link testing. Deep ocean engineering talent scarcity concentrates service provision within defense primes.
- Consulting:Threat assessment, vulnerability analysis, and procurement specification development for port facility security compliance.
- Training:Operator certification for acoustic signature classification and autonomous system mission planning. NATO interoperability standards require concurrent national validation.
Integration captures the largest contract values; Maintenance delivers the most predictable recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and port authorities concentrate demand across five national markets where seabed infrastructure protection has escalated to sovereign priority status. Each geography presents distinct regulatory drivers and industrial cluster specializations.
United States
The US Navy's distributed maritime operations doctrine and Coast Guard port security regulations drive integrated sonar and autonomous system procurement. Virginia-class submarine construction at Newport News Shipbuilding and unmanned vehicle development in San Diego anchor defense industrial base concentration. The National Defense Authorization Act mandates persistent undersea domain awareness investments through 2030.
China
Critical subsea cable protection mandates and MEE enforcement of port facility security regulations stimulate layered detection system deployment. Shanghai's maritime engineering cluster and Qingdao's naval shipyard complex concentrate indigenous sonar manufacturing capacity. State-owned enterprises dominate procurement under national security technology localization directives.
United Kingdom
Royal Navy persistent operational deployment experimentation and NATO Maritime Strategy alignment shape availability-based contracting models. Plymouth's underwater warfare center and Glasgow's shipbuilding corridor sustain acoustic sensor integration expertise. The Integrated Review Refresh prioritizes seabed infrastructure protection as core defense output.
Japan
Senkaku Islands seabed dispute monitoring and METI offshore wind security integration requirements expand dual-use technology demand. Kobe's maritime equipment manufacturing base and Yokosuka's naval facility cluster support indigenous AUV development programs. Revised National Defense Strategy documents explicitly address subsea cable protection.
Australia
AUKUS submarine pathway commitments and critical infrastructure protection legislation accelerate undersea surveillance capability acquisition. Perth's naval base expansion and Adelaide's shipbuilding precinct concentrate sovereign sustainment investments. The Defence Strategic Review identifies seabed domain awareness as priority capability gap.
Underwater Security (Systems and Services) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated defense-tier segment and a fragmenting commercial-services tier. Prime contractors anchor national procurement frameworks through classified technology access and sovereign security clearances. Mid-tier specialists capture niche autonomy and acoustic processing segments. Dominant competitive moves include strategic partnerships for algorithm development and geographic expansion through local facility establishment.
Within the European defense prime tier, Thales Group and Saab represent integrated system-of-systems providers with seabed warfare heritage. L3Harris Technologies, Inc. occupies a position linking undersea communication standardization with NATO interoperability requirements. These three entities exemplify the channel-control archetype where national security classification regimes create structural barriers to challenger entry.
| Leading Market Players |
|---|
| Thales Group |
| Saab |
| L3Harris Technologies, Inc. |
| Kongsberg Mesotech Ltd. |
| Sonardyne |
| Huntington Ingalls Industries, Inc. |
| Ultra Group |
| DSIT Solutions Ltd. |
| ASELSAN A.Ş. |
| Others |
Value Network & Pricing Analysis
Titanium alloy and rare earth magnet supply concentration in Japan and China anchors margin capture at the deep-rated pressure hull tier, forcing buyers into long-term offtake arrangements or sovereign stockpile commitments to secure sensor-grade material access.
Pricing Analysis
Cost-plus contracts with titanium sponge indexation dominate deep-rated system procurement, insulating prime contractors from alloy price volatility while transferring commodity risk to government buyers. Three-tier pricing structure across expeditionary-grade, littoral-standard, and survey-economy levels reflects certification grade and pressure rating differentiation. Pricing pressure stems from AUV platform commoditization as commercial offshore entrants replicate military-spec autonomy stacks. Government agencies exhibit lowest price sensitivity given classified processing requirements; commercial port operators face acute budget constraints under MEE compliance mandates.
Supply Chain Analysis
High-purity titanium sponge feeds from Japan, Russia, and Kazakhstan sustain Western pressure hull fabrication, with sensor-grade rare earth processing concentrated in Chinese refining complexes. Acoustic transducer ceramics and fiber-optic gyroscopes draw from limited qualified supplier pools. Single-source vulnerability runs through seabed-qualified titanium forging capacity. Distribution runs through national security-cleared prime contractors who integrate multi-vendor subsystems under sovereign procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial synthetic aperture sonar convergence represents a substitution threat that incumbents must neutralize through capability unbundling before survey-grade processing erodes military premium tiers.
For Market Incumbents: Pre-empt commercial sonar convergence by acquiring seabed survey specialists with dual-use algorithm libraries, then embedding their signal processing into NATO-certified hardware stacks. Lock in titanium alloy supply through backward integration into sponge conversion or exclusive offtake from Japanese producers. The priority defensive lever rests on classified acoustic processing certification moats that commercial entrants cannot replicate.
For New Entrants and Emerging Players: Arctic seabed domain awareness gaps in Norway, Canada, and Greenland offer the most penetrable white-space for persistent under-ice sensing infrastructure where incumbent presence remains thin. Target commercial offshore wind security integration in the North Sea and Baltic markets where regulatory mandates outpace prime contractor response capacity. Lead with seabed-sensing-as-a-service contracting models that transfer capital burden from European defense ministries to industrial balance sheets.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier autonomy specialists with NATO interoperability certification and under-ice AUV operational records, positioned for AUKUS and Arctic procurement waves. Long-term viability hinges on software-defined sensing architectures that compress hardware refresh cycles into algorithm update revenue streams. Monitor AUKUS submarine pathway milestone commitments as the inflection signal for sovereign undersea surveillance spending acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Seabed-Sensing-as-a-Service Deployment | Availability-based contracting transfers mission risk from Royal Navy to industrial partners under persistent operational deployment frameworks. |
| Multi-Static Sonar Array Integration | Networked source-receiver geometries render obsolete monolithic hull-mounted systems across NATO distributed maritime operations. |
| Arctic Under-Ice AUV Certification | Diminishing ice coverage exposes submarine transit routes requiring sovereign sensing infrastructure in Norway and Canada. |
| Commercial Synthetic Aperture Sonar Acquisition | Military-grade signal processing fusion with seabed survey economics opens infrastructure integrity monitoring revenue streams. |
| Titanium Alloy Supply Securement | Pressure hull material sourcing constraints from limited qualified suppliers expose programs to price volatility and delivery risk. |
Research Methodology
Operator-level perspectives from submarine program officers, port facility security directors, AUV mission planners, seabed warfare integrators, and titanium alloy procurement managers anchored the qualitative base. Primary interview findings triangulated against secondary sources including US Navy Unmanned Campaign Framework documentation, NATO Maritime Strategy implementation guidance, MEE port security compliance filings, and national defense authorization act appropriations schedules. Bottom-up segment sizing across surveillance systems, monitoring solutions, intrusion detection, and communication equipment validated against top-down defense budget allocation analysis.
Scenario-bracketing around AUKUS delivery timelines, Arctic ice coverage projections, and Indo-Pacific cable protection mandate enforcement intensity shaped the analytical framework across the modeling period. Segmentation dimensions modeled include product type, technology tier, end-user procurement authority, and service delivery mode. CAGRs derived from defense budget trajectory analysis, platform replacement cycle assessment, and autonomous system penetration curve modeling. Industry-specific forecast inputs incorporated Virginia-class construction rates and METI offshore wind security integration timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-owned enterprises or commercial sonar convergence specialists would shift outcomes beyond projected ranges. Quarterly review of AUKUS milestone commitments, NATO autonomous system certification progress, and titanium alloy spot price movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Smart Security Market
Security and Surveillance
Radar Security Market
Security and Surveillance
Global Security As a Service Market
Security and Surveillance
Global Wireless Doorbells Market
Security and Surveillance
India Perimeter Intrusion Detection and Prevention Market
Security and Surveillance
Global Manned Security Service Market
Security and Surveillance
Night Vision Scopes Market
Security and Surveillance
Global Security and Vulnerability Management Market
Security and Surveillance
Europe Security Services Market
Security and Surveillance
Global Threat Intelligence Management Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Signal Jamming Systems Market
Security and Surveillance
Europe Cargo and Vehicle Screening Market
Security and Surveillance
Forensic Technologies Market
Security and Surveillance
Surveillance Radars Market
Security and Surveillance
Explosive Detection Kit Market