
 Smart Grid Market | 2026-2036
Smart Grid Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Grid Market Analysis
Market Context
Utility procurement channels is fragmenting as state regulators decouple hardware purchasing from software integration contracts. GE Vernova leverages its turbine-to-grid portfolio to anchor large-scale utility modernization programs across the southeastern United States. Siemens AG competes through digital twin platforms that unify substation automation with cloud-based analytics. Schneider Electric SE controls the mid-market segment for commercial building energy management systems in France and Germany.
Technical Definition and Segments
A smart grid constitutes a digitally enabled electrical network integrating advanced sensors, two-way communication protocols, and automated control systems to monitor power flows from generation through consumption in real time. The architecture relies on IEC 61850 substation automation standards and IP-based communication networks to achieve sub-second fault detection and self-healing capabilities. Advanced Metering Infrastructure leads installed base value due to decade-long utility amortization schedules, while Demand Response captures expanding margin pools as wholesale electricity markets adopt real-time pricing mechanisms. Software components within the component dimension exhibit the fastest growth trajectory as utilities shift capital expenditure toward grid analytics platforms and predictive maintenance algorithms.
Regulatory Framework
FERC Order 2222 mandates regional transmission organizations to accommodate aggregated distributed energy resources, directly expanding addressable market scope for demand response technology providers. The EU Green Deal and associated CSRD disclosure requirements compel European utilities to deploy smart sensors achieving granular carbon accounting across transmission and distribution networks. Stakeholders must monitor evolving cybersecurity mandates from national regulators as grid digitization expands attack surfaces beyond traditional operational technology boundaries.
Market Dynamics
Utilities face mounting pressure to modernize aging transmission infrastructure while integrating intermittent renewable generation, forcing capital reallocation from hardware-heavy substation upgrades toward software-defined grid orchestration platforms that manage bidirectional power flows.
Growth Catalysts
- FERC Order 2222:This US mandate requires regional transmission organizations to accept aggregated distributed energy resources, directly expanding revenue pools for demand response aggregators and virtual power plant operators.
- Commercial building electrification:Property developers across France and Germany are deploying building energy management systems to meet CSRD disclosure requirements, pulling through substation automation and metering infrastructure.
- AMI refresh cycles:First-generation smart meters installed during 2010-2015 stimulus programs are reaching end-of-life, triggering replacement demand that bundles advanced analytics capabilities.
Market Restraints
- Copper and rare earth price volatility:Transformer cores and power electronics depend on concentrated Chilean copper and Chinese-processed rare earths, exposing project budgets to commodity swings.
- Legacy SCADA integration debt:Proprietary protocols from 1990s-era control systems create technical friction that slows cloud-based analytics deployment and extends implementation timelines.
- Utility procurement fragmentation:State regulators decoupling hardware from software contracts force vendors to navigate multiple procurement channels, elevating sales complexity and elongating deal cycles.
Strategic Opportunities
- Texas ERCOT market design:Real-time pricing volatility creates arbitrage opportunities for battery-plus-solar aggregators using automated demand response platforms.
- Grid-edge AI convergence:Machine learning inference at distribution transformers combined with digital twin simulation enables predictive maintenance that reduces outage duration.
- Performance-based ratemaking:Regulators in California and New York are shifting utility compensation toward reliability and carbon metrics, incentivizing software investments over traditional capex.
Industry Challenges
- Cybersecurity workforce scarcity:Grid operators struggle to recruit personnel with combined OT/IT security expertise capable of defending IEC 61850 networks against ransomware.
- Interoperability certification delays:Multi-vendor system integration requires extensive testing against evolving IEEE 2030.5 standards, compressing deployment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Grid Market |
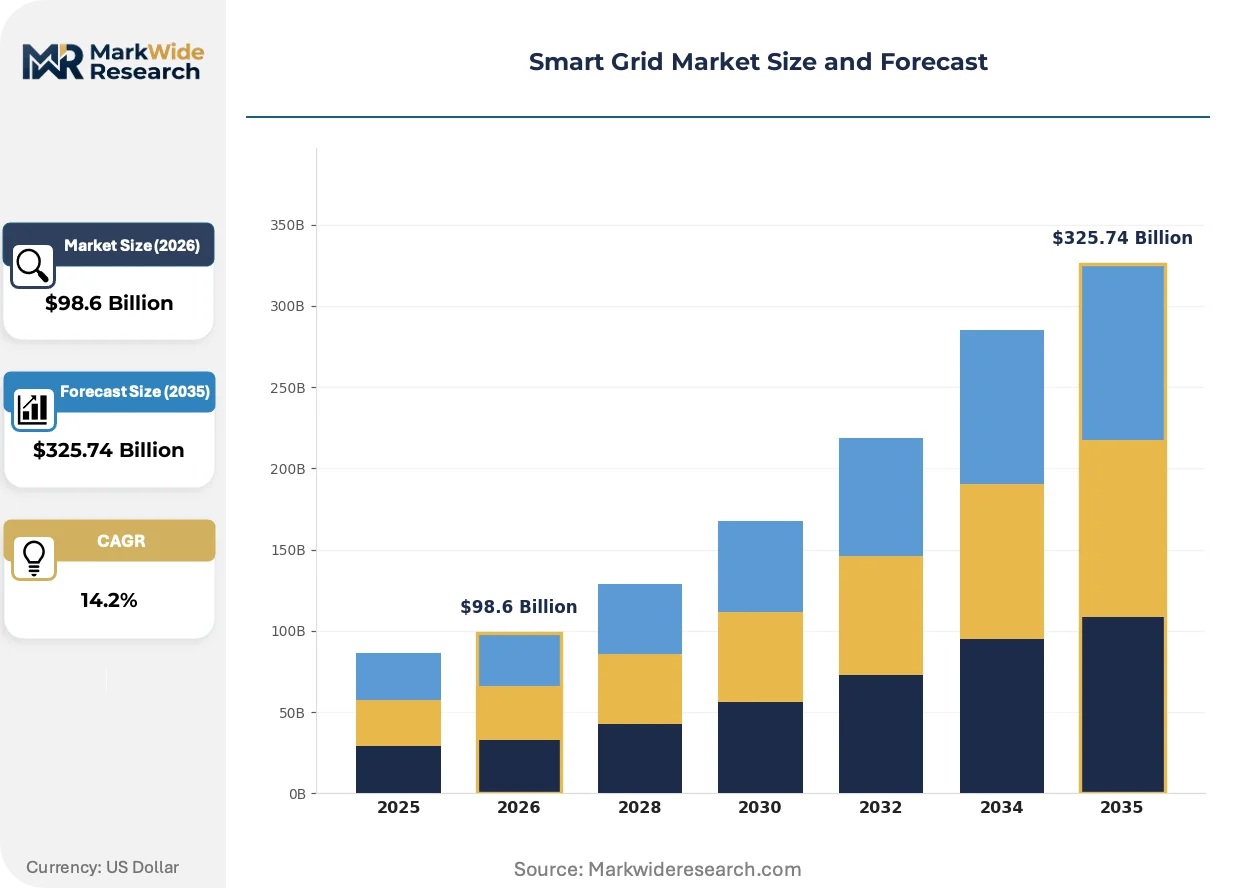
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $325.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Demand Response, Smart Sensors, Communication Networks End User: Utilities, Commercial Buildings, Residential Customers, Industrial Sector Component: Software, Hardware, Services, Integration Tools Application: Energy Management, Grid Optimization, Renewable Integration, Demand Forecasting |
| Companies Covered | GE Vernova, Prysmian Group SPA, Siemens AG, Eaton Corporation plc, Nexans SA, Hitachi Energy Ltd, Mitsubishi Electric Corporation, Fuji Electric Co Ltd, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Grid Market Emerging Trajectories
Digital infrastructure investment is pivoting from meter deployment toward predictive intelligence layers that anticipate equipment failure and optimize power flows in sub-second intervals.
Edge computing architectures are hybridizing substation automation with cloud analytics, enabling utilities to process fault detection locally while aggregating operational data for fleet-wide optimization. Mid-sized municipal utilities in the southeastern United States are piloting these distributed intelligence nodes to reduce latency for protection schemes. The technology is hybridizing traditional relay-based protection with software-defined networking, compressing vendor margins on proprietary hardware.
CSRD disclosure mandates from the European Commission are compelling transmission operators to deploy granular carbon accounting sensors across high-voltage networks. Industrial consequence includes mandatory Scope 3 emissions tracking that elevates smart sensor specifications in procurement tenders. French and German utilities are responding by bundling environmental monitoring with standard AMI deployments to satisfy dual compliance requirements.
Buying patterns among North American utilities are fragmenting as state regulators mandate competitive bidding for software components previously sole-sourced with hardware. Engineering-procurement-construction firms are displacing traditional direct utility sales channels for grid analytics platforms. This channel rotation is most visible in California, where community choice aggregators procure distributed energy resource management systems through specialized integrators rather than incumbent vendors.
Smart Grid Market Segmentation
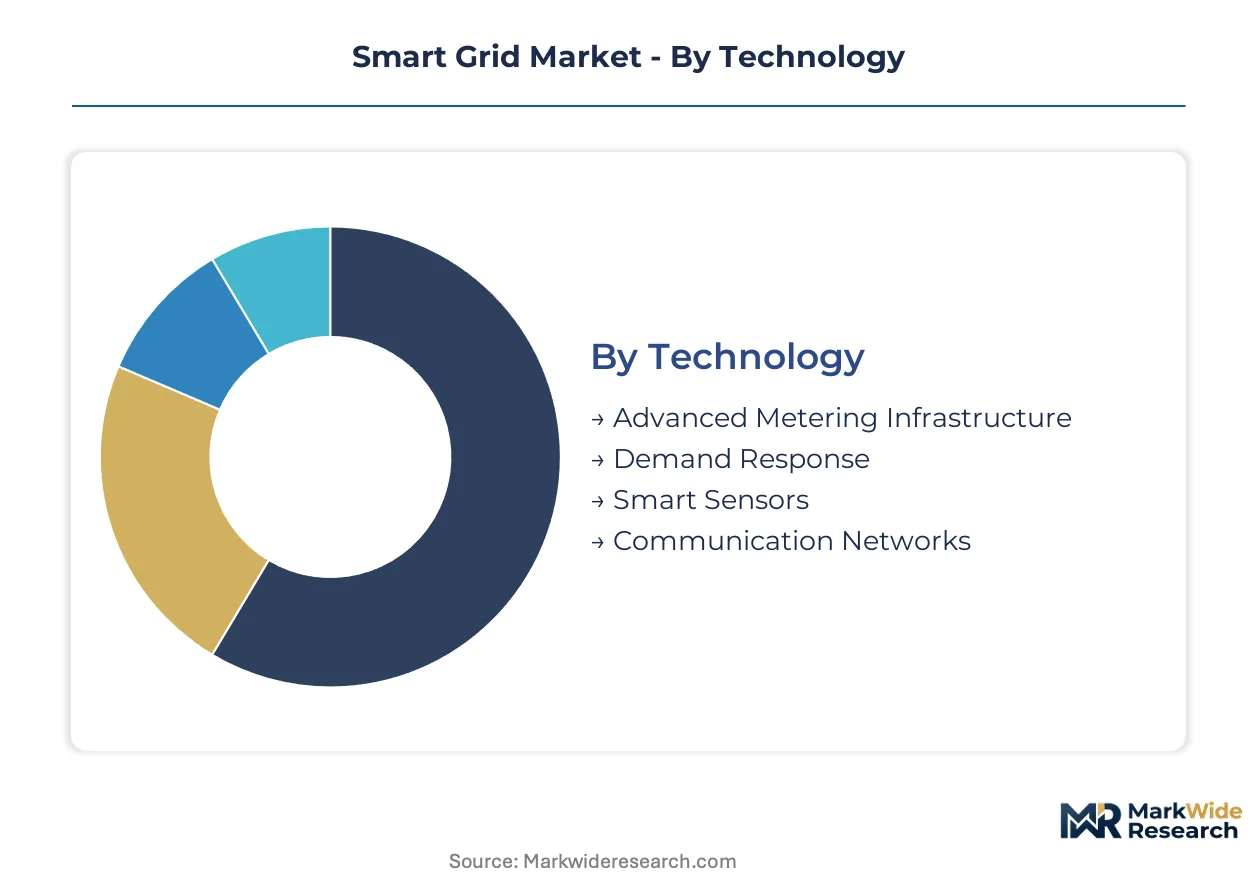
Smart grid procurement patterns diver sharply across technology maturity curves and regulatory exposure levels. Understanding these segment boundaries clarifies where capital allocation concentrates versus where margin compression threatens vendor economics.
Technology:
The use-case spectrum spans legacy meter infrastructure through predictive grid intelligence, with each layer carrying distinct amortization timelines and interoperability requirements.
- Advanced Metering Infrastructure:First-generation deployments from stimulus-era programs are entering replacement cycles. Utilities in California, Texas, and New York are bundling AMI refreshes with edge analytics capabilities to satisfy performance-based ratemaking metrics.
- Demand Response:FERC Order 2222 mandates regional transmission organizations to accept aggregated distributed energy resources. Texas ERCOT's real-time pricing volatility creates arbitrage opportunities for virtual power plant operators using automated load curtailment platforms.
- Smart Sensors:IEC 61850-compliant devices enable sub-second fault detection across distribution networks. European transmission operators deploy these for granular carbon accounting under CSRD disclosure mandates.
- Communication Networks:IP-based protocols replace proprietary SCADA links, though legacy integration debt slows cloud analytics deployment for municipal utilities.
The dominant share belongs to Advanced Metering Infrastructure, while Demand Response is closing the gap fastest.
End User:
Customer archetypes range from regulated monopolies with century-long asset horizons to price-sensitive commercial developers facing disclosure deadlines.
- Utilities:Vertically integrated operators face capital reallocation pressure from hardware-heavy substation upgrades toward software-defined orchestration platforms. Southeastern US municipal utilities pilot edge computing nodes to compress protection scheme latency.
- Commercial Buildings:Property developers across France and Germany deploy building energy management systems to meet CSRD requirements, pulling through substation automation and metering infrastructure.
- Residential Customers:Community choice aggregators in California procure distributed energy resource management systems through specialized integrators rather than incumbent vendors, fragmenting traditional sales channels.
- Industrial Sector:Energy-intensive manufacturers leverage real-time pricing signals from wholesale markets to optimize production scheduling around grid congestion events.
Utilities retain the largest installed base, though Commercial Buildings are expanding most quickly under regulatory compulsion.
Component:
Margin pools concentrate in intangible layers as hardware commoditization accelerates across transformer and switchgear categories.
- Software:Grid analytics platforms and predictive maintenance algorithms capture expanding capital expenditure share. Cloud-based digital twin simulation enables fleet-wide optimization from distributed operational data.
- Hardware:Copper and rare earth price volatility exposes transformer core and power electronics budgets to commodity swings from Chilean and Chinese supply concentration.
- Services:Engineering-procurement-construction firms displace direct vendor sales for grid analytics deployment, elongating deal cycles but reducing utility procurement risk.
- Integration Tools:Multi-vendor system testing against evolving IEEE 2030.5 standards compresses deployment windows and elevates certification costs.
Software commands the steepest expansion trajectory, while Hardware faces sustained margin pressure from input cost volatility.
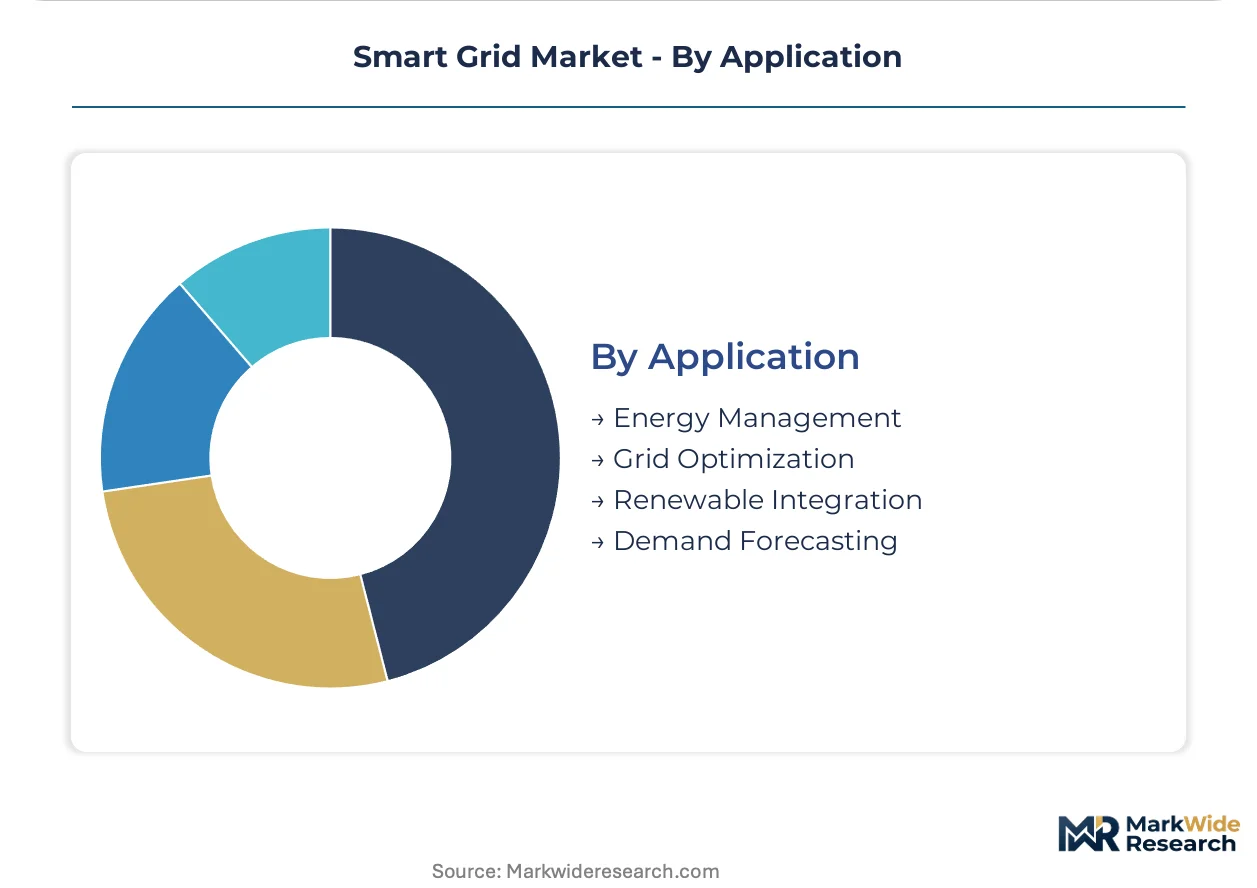
Application:
Functional priorities shift from reactive fault management toward anticipatory optimization as renewable penetration destabilizes traditional dispatch patterns.
- Energy Management:Bidirectional power flow orchestration becomes critical as distributed solar and battery storage proliferate behind the meter.
- Grid Optimization:Machine learning inference at distribution transformers combined with digital twin simulation reduces outage duration through predictive maintenance scheduling.
- Renewable Integration:Intermittent generation forecasting errors force utilities to maintain spinning reserves, elevating demand for automated frequency regulation services.
- Demand Forecasting:Real-time pricing mechanisms in restructured markets require sub-hourly load prediction accuracy to minimize imbalance penalties.
Grid Optimization leads current investment intensity, while Renewable Integration is gaining share fastest as clean energy mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific DC Intertie transmission corridor anchors United States grid modernization investment, channeling hydropower from Columbia River dams to California load centers while enabling bidirectional power flows from distributed solar aggregations.
United States
FERC Order 2222 mandates regional transmission organizations to accept aggregated distributed energy resources, expanding revenue pools for demand response aggregators in Texas and California. The Inflation Reduction Act channels production tax credits toward grid-scale battery storage paired with renewable generation. ERCOT's real-time pricing volatility in Houston-Austin corridor creates arbitrage opportunities for virtual power plant operators using automated load curtailment platforms.
Germany
Transmission system operators deploy IEC 61850-compliant smart sensors to achieve granular carbon accounting under CSRD disclosure mandates. The EU Green Deal compels utilities to modernize aging distribution networks while integrating intermittent offshore wind from North Sea interconnects. Industrial clusters in North Rhine-Westphalia pilot edge computing nodes at substations to compress protection scheme latency for manufacturing load centers.
China
State Grid Corporation accelerates ultra-high voltage direct current transmission deployment to move renewable generation from western provinces to eastern coastal demand centers. National Energy Administration mandates smart meter penetration targets that trigger AMI refresh cycles across provincial utilities. Yangtze River Delta manufacturing hubs in Shanghai-Suzhou corridor deploy building energy management systems to meet dual carbon goals for industrial emissions tracking.
India
The national smart grid mission channels central funding toward advanced metering infrastructure in urban distribution circles facing aggregate technical and commercial loss reduction targets. Central Electricity Authority regulations mandate renewable purchase obligations that force discoms to deploy forecasting and scheduling systems for solar-wind hybrid parks. Maharashtra State Electricity Distribution Company pilots digital twin platforms for Mumbai-Thane industrial belt load forecasting accuracy.
Japan
Tokyo Electric Power Company deploys battery energy storage systems at substations to manage frequency regulation from variable renewable penetration on Honshu island grid. METI's green transformation initiative subsidizes grid-edge AI convergence for predictive maintenance at distribution transformers. Kansai region utilities in Osaka-Kobe corridor integrate demand response platforms with commercial building energy management systems for peak shaving during summer cooling loads.
Smart Grid Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform providers capable of spanning generation assets through distribution automation, with mid-market specialists occupying niches in building energy management and regional substation integration. Three archetypes dominate: turbine-to-grid conglomerates anchoring large-scale utility modernization programs, digital twin platform vendors unifying substation automation with cloud analytics, and mid-market energy management specialists controlling commercial building segments. Competitive dynamics center on portfolio diversification into software-defined grid orchestration and strategic partnerships with engineering-procurement-construction firms displacing direct utility sales channels.
Among European-headquartered industrial conglomerates, Siemens AG and Schneider Electric SE exemplify divergent positioning strategies within the competitive set. Siemens AG occupies the digital twin platform tier, while Schneider Electric SE anchors the mid-market building energy management specialization. GE Vernova represents the turbine-to-grid integrated portfolio archetype, leveraging generation asset relationships to secure downstream grid modernization contracts. These three entities collectively illustrate how vendor origin and historical capability footprints shape contemporary competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| GE Vernova |
| Prysmian Group SPA |
| Siemens AG |
| Eaton Corporation plc |
| Nexans SA |
| Hitachi Energy Ltd |
| Mitsubishi Electric Corporation |
| Fuji Electric Co Ltd |
| Schneider Electric SE |
| Others |
Supply Flow & Price Mechanics
The Pacific DC Intertie transmission corridor freight economics compress margins for transformer manufacturers while amplifying price differentiation between integrated platform providers and component specialists. Copper cathode shipments from Chilean mines through Long Beach port terminals feed into California substation projects, where logistics cost volatility separates premium-tier vendors bundling installation services from economy-tier commodity suppliers.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on software integration depth and IEC 61850 certification grade. Premium tiers capture margins through predictive analytics bundling, while economy tiers face price erosion from Chinese-manufactured hardware imports. Municipal utilities exhibit highest price sensitivity due to constrained capital budgets, whereas investor-owned utilities in Texas and California prioritize reliability metrics over unit cost.
Supply Chain Analysis
Supplier-financing facilities from Chinese state-backed institutions enable extended payment terms for transformer core manufacturers sourcing Chilean copper and Chinese-processed rare earths. Distribution runs through engineering-procurement-construction firms displacing direct vendor relationships, with single-source vulnerability concentrated in semiconductor components for power electronics. Tariff exposure on Chinese electrical steel amplifies cost uncertainty for North American grid infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
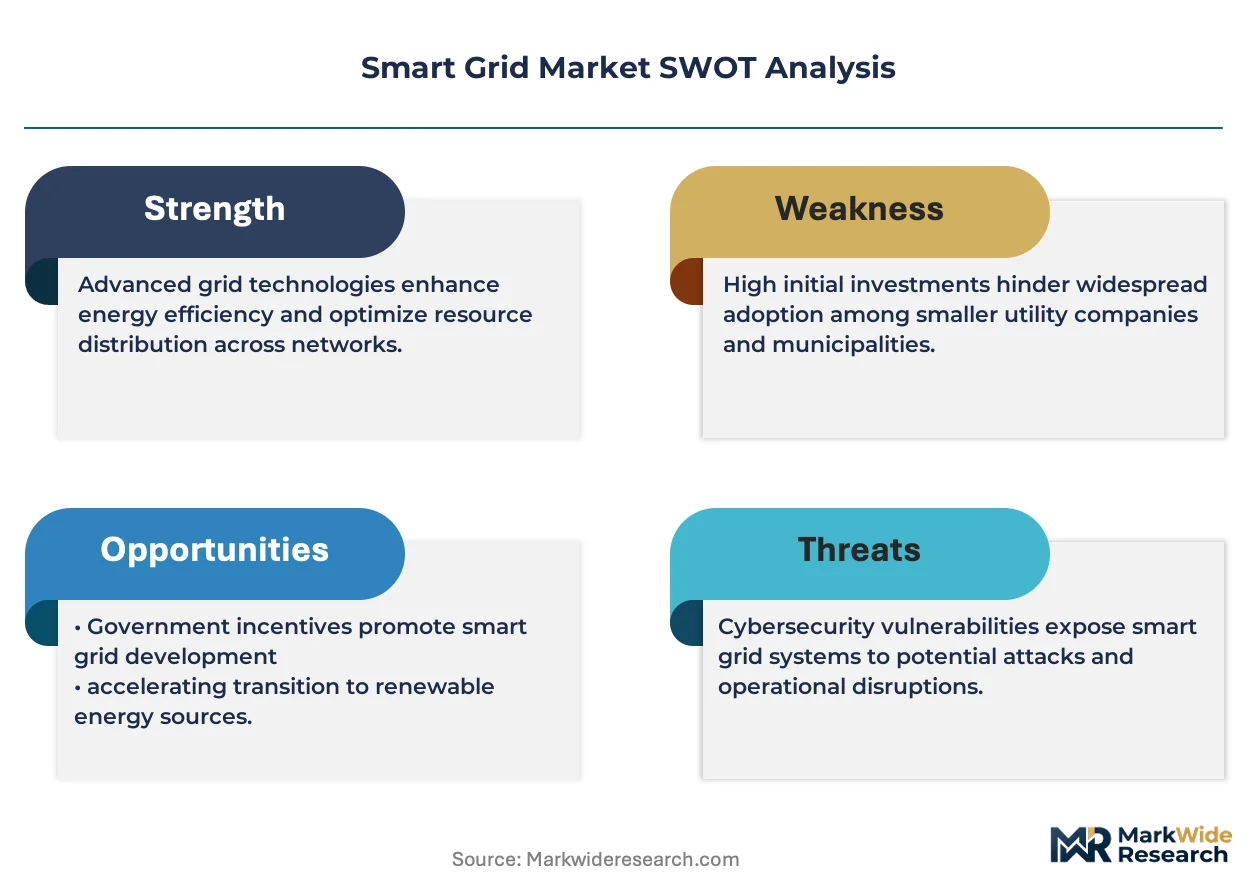
Smart grid incumbents face substitution pressure from software-native entrants offering grid-edge AI platforms without legacy SCADA integration debt. Defense requires building moats around data assets and regulatory relationships that pure-play analytics vendors cannot replicate.
For Market Incumbents: Build switching-cost moats through deep integration with utility operational technology environments and FERC compliance workflows. Incumbents should anchor large-scale modernization programs by bundling generation asset expertise with distribution automation, while investing in cybersecurity certification to defend against cloud-native competitors lacking OT security credentials. For New Entrants and Emerging Players: Build out specialized demand response aggregation capabilities targeting Texas ERCOT's real-time pricing volatility. White-space exists in virtual power plant orchestration for commercial building portfolios in France and Germany, where CSRD disclosure mandates create urgent procurement windows without incumbent saturation. For Investors and Strategic Acquirers: Grid-edge AI specialists with proven predictive maintenance algorithms represent the most compelling acquisition archetype. Long-term viability hinges on software recurring revenue models displacing project-based hardware sales. Monitor FERC Order 2222 implementation pace across regional transmission organizations as inflection indicator for demand response market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Grid Orchestration Platform | Unifies substation automation with cloud analytics for bidirectional power flow management. |
| Cybersecurity Certification Investment | Addresses IEC 61850 network defense requirements as attack surfaces expand beyond traditional OT boundaries. |
| Virtual Power Plant Aggregation Capability | Captures FERC Order 2222-enabled revenue pools for distributed energy resource orchestration. |
| Engineering-Procurement-Construction Partnership | Displaces fragmented direct utility sales channels elongating deal cycles in California and New York. |
| Predictive Maintenance Algorithm Development | Reduces outage duration through machine learning inference at distribution transformers. |
Methodological Framework
The analysis maps Advanced Metering Infrastructure, Demand Response, Smart Sensors, and Communication Networks segments, each validated through utility planning officers, IPP project developers, EPC contractors, and grid operators. Primary interview data triangulates against EIA statistics, FERC filings, IEA grid integration reports, and project development databases. Bottom-up unit economics for AMI deployment and top-down utility capex surveys converge on segment sizing.
Assumption sets held regulatory timelines fixed while varying commodity price scenarios and renewable penetration rates across the projection horizon. Segmentation models incorporate technology maturity curves, end-user archetypes, component margin pools, and application functional priorities. CAGRs derive from installed base replacement cycles, policy mandate enforcement schedules, and software subscription revenue recognition patterns.
Practitioners should monitor copper and rare earth price volatility, FERC Order 2222 regional implementation variance, and cybersecurity mandate evolution for early signals requiring forecast adjustment. Macroeconomic contraction, regulatory delay, or breakthrough battery storage cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
Demand Response Market
Smart Grid
Microgrid Market
Smart Grid
Europe Microgrid Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Smart Microgrid Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Power Grid Market
Smart Grid
Smart Demand Response Market
Smart Grid
Microgrid Controller Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Smart Water Grid Market
Smart Grid
United Kingdom Smart Grid Market