
 Smart Grid Home Area Network (HAN) Market | 2026-2036
Smart Grid Home Area Network (HAN) Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Grid Home Area Network (HAN) Market Analytics
The utility-direct channel is narrowing as energy retailers and broadband providers bundle HAN hardware with rate plans and connectivity services. Cisco Systems leverages its enterprise networking heritage to anchor utility-scale mesh deployments, while Honeywell International sustains a dominant position in thermostat-integrated energy management through its residential building automation portfolio. Schneider Electric competes aggressively on cloud-based deployment architectures that reduce on-premise infrastructure burdens for smaller utilities.
A Smart Grid Home Area Network comprises the localized communication infrastructure linking smart meters, distributed energy resources, and controllable loads within residential premises, typically operating over Zigbee, Wi-Fi, or Z-Wave protocols at sub-gigahertz and 2.4 GHz frequencies to enable real-time demand response and grid-edge visibility. The primary commercial purpose centers on enabling utilities to modulate household consumption during peak events while giving consumers tariff visibility. Smart meters constitute the mature revenue base where replacement cycles dominate, whereas energy management systems capture expanding margin pools as software subscription models displace hardware-only sales. Communication devices represent the fastest-growing product category as multi-protocol gateways consolidate formerly siloed device networks.
The U.S. Federal Energy Regulatory Commission's Order 2222 and the EU F-Gas Regulation collectively reshape product standards by mandating interoperability and restricting refrigerants in heat pumps that HAN systems must control. Japan's METI has tightened technical compatibility requirements for home energy management systems under its ZEH and ZEB building codes, creating certification barriers for non-compliant imports. Stakeholders must monitor whether emerging national cybersecurity frameworks for critical infrastructure will impose firmware audit requirements that fragment vendor qualification processes across jurisdictions.
Market Dynamics
Utilities deploying demand-response programs are forcing a channel restructuring as energy retailers and broadband providers displace direct utility procurement with bundled service models. This shift compresses hardware margins while expanding recurring software revenue pools across the value chain.
Growth Catalysts
- EU Green Deal efficiency mandates:Building renovation targets and grid modernization timelines in Germany are accelerating meter replacement cycles and gateway deployments.
- Demand-response program expansion:Utilities in the United States leverage FERC Order 2222 to aggregate distributed energy resources through HAN-enabled load modulation.
- Multi-protocol gateway consolidation:Zigbee, Wi-Fi, and Z-Wave integration into single hardware units reduces consumer equipment clutter and installer complexity.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate sub-gigahertz radio chip fabrication, creating vulnerability for gateway manufacturers.
- EU F-Gas refrigerant restrictions:Heat pump control requirements under tightening environmental rules add compliance layers to HAN thermostat integrations.
- Copper and rare earth price volatility:Magnet materials for smart meter components face input cost instability from concentrated mining geographies.
Strategic Opportunities
- Japan ZEH/ZEB building codes:METI technical compatibility requirements for home energy management systems create certified import channels for compliant vendors.
- Cloud-based deployment architectures:Schneider Electric's model of reducing on-premise infrastructure burdens opens smaller utility segments previously closed to HAN vendors.
- Broadband provider channel entry:Cable and fiber operators bundling HAN hardware with connectivity subscriptions capture customer relationships utilities once owned exclusively.
Industry Challenges
- Firmware audit fragmentation:Emerging national cybersecurity frameworks for critical infrastructure threaten to multiply vendor qualification processes across jurisdictions without harmonization.
- Interoperability certification complexity:Japan's tightened technical requirements and EU interoperability mandates create overlapping testing burdens that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Grid Home Area Network (HAN) Market |
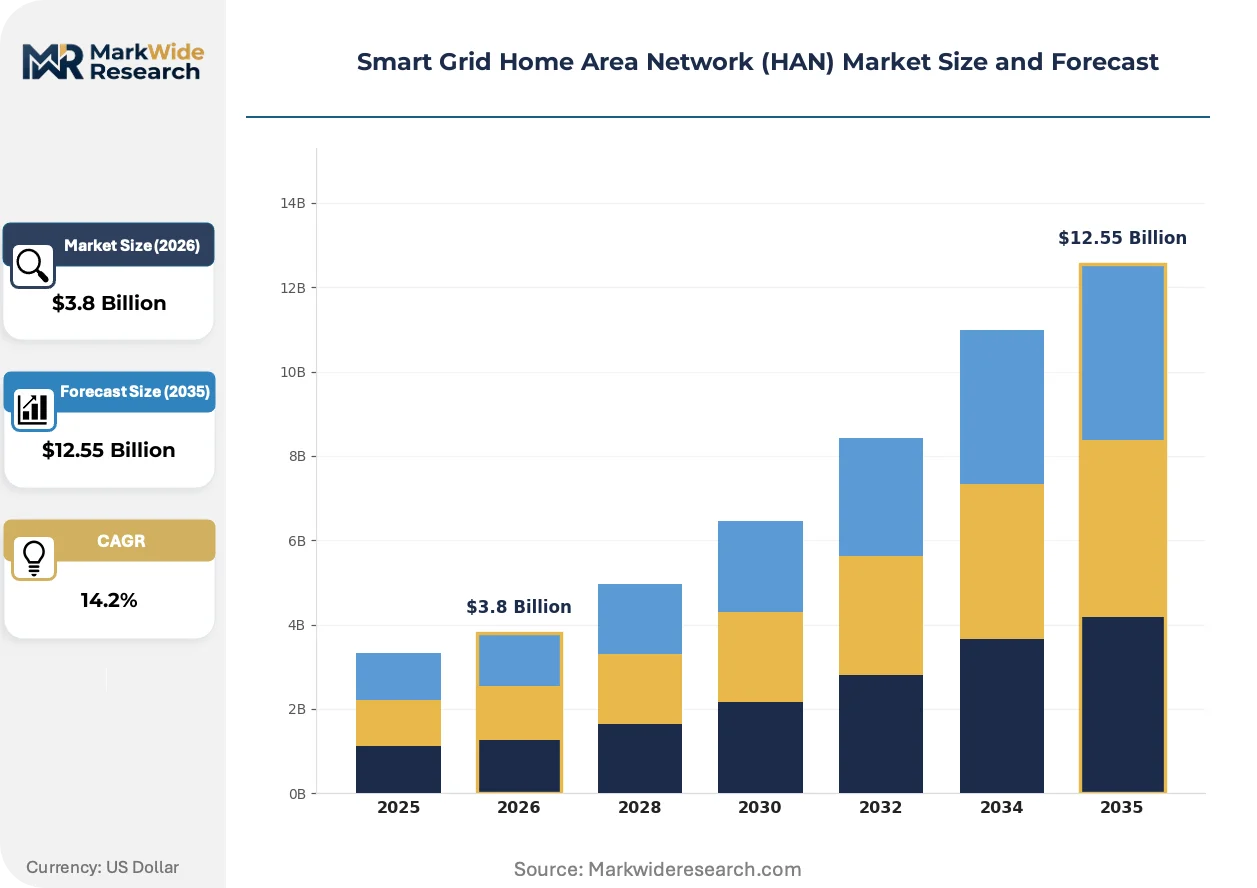
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, In-home Displays, Energy Management Systems, Communication Devices Technology: Zigbee, Wi-Fi, Z-Wave, Bluetooth End User: Residential Homes, Multi-family Units, Assisted Living Facilities, Energy Providers Deployment: On-premise, Cloud-based, Hybrid, Managed Services |
| Companies Covered | Cisco Systems, Honeywell International, GE Energy, Siemens, Schneider Electric, Landis+Gyr, Itron, Control4, Silver Spring Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Grid Home Area Network (HAN) Market Evolving Landscape
Protocol convergence and policy mandates are compressing the competitive window for single-function hardware vendors while elevating software-defined platform providers. The market is bifurcating between commodity connectivity and premium energy management services.
Thread and Matter protocols are rendering obsolete proprietary Zigbee and Z-Wave silos that previously locked consumers into single-ecosystem device purchases. European utilities and North American retailers are accelerating adoption of these open standards to reduce support costs and expand consumer choice. This transition is rendering obsolete the historical hardware margin model built on gateway vendor lock-in.
The U.S. Inflation Reduction Act's home energy rebates are restructuring procurement incentives by tying HAN hardware eligibility to whole-home electrification retrofits. Contractors and aggregators now capture the customer interface that utilities previously controlled through direct meter programs. Residential solar-plus-storage installers represent the fastest-growing channel for gateway deployments as they bundle monitoring with generation assets.
Subscription-based energy management software is unbundling from hardware sales as utilities and third-party providers monetize tariff optimization and demand-response participation. German energy retailers lead this shift by packaging HAN-enabled load control with dynamic time-of-use rate plans. This behavioral pivot is most visible in markets with retail competition, where customer churn risk drives ongoing service innovation.
Smart Grid Home Area Network (HAN) Market Segmentation
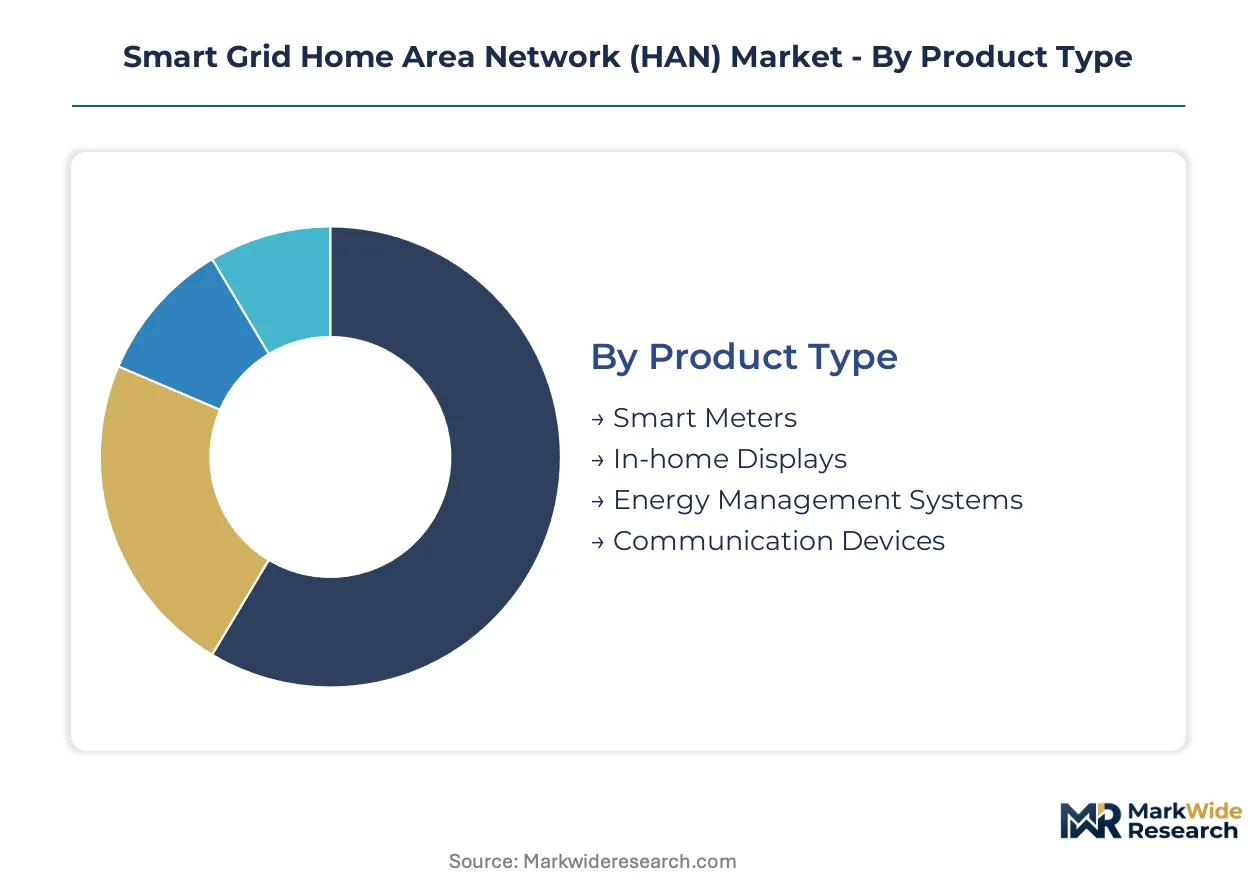
Smart Grid Home Area Network market segmentation reveals divergent margin structures across hardware maturity curves and deployment architectures. Vendors calibrate portfolio investments by mapping product lifecycles against utility procurement channels and residential electrification retrofit cycles.
Product Type:
Cost tier differentiation separates mature meter replacement cycles from emerging software-enabled revenue pools in gateway and display categories.
- Smart Meters:These devices measure real-time electricity consumption and communicate usage data to utilities via embedded cellular or mesh radio modules. German utilities and U.S. cooperatives dominate procurement volumes as regulatory mandates force accelerated replacement timelines. Hardware margins compress as volume manufacturing scales and procurement consolidates under national rollout programs.
- Communication Devices:Multi-protocol gateways consolidate Zigbee, Wi-Fi, and Z-Wave networks into unified home energy management interfaces. Demand concentrates among broadband providers bundling connectivity with HAN hardware and solar-plus-storage installers seeking monitoring integration. These units command premium pricing against single-function alternatives.
- Energy Management Systems:Software platforms enabling tariff optimization and automated load control through cloud-based analytics engines.
- In-home Displays:Wall-mounted or countertop units providing real-time consumption feedback and demand-response event notifications to residential consumers.
Smart meters hold installed capacity. Communication devices are rotating up the share rankings.
Technology:
Protocol maturity determines interoperability certification burdens and silicon sourcing strategies for gateway manufacturers.
- Zigbee:Sub-gigahertz and 2.4 GHz mesh networking standard purpose-built for low-power home automation and utility demand-response signaling. German meter deployments and Japanese ZEH building codes specify Zigbee compatibility, creating concentrated certification investment for vendors targeting these procurement channels. Taiwan-based radio chip fabrication concentrates supply risk.
- Wi-Fi:Ubiquitous 2.4 GHz and 5 GHz connectivity standard leveraging existing residential broadband infrastructure. North American retailers and broadband providers favor Wi-Fi-enabled HAN hardware to minimize consumer setup friction and support costs. Higher power consumption limits battery-operated sensor applications.
- Z-Wave:Proprietary sub-gigahertz mesh protocol historically dominant in security and lighting integration ecosystems.
- Bluetooth:Short-range 2.4 GHz standard enabling smartphone-based device commissioning and localized energy data access.
Zigbee commands legacy utility deployments. Wi-Fi is climbing fastest in retail channels.
End User:
Customer type segmentation maps procurement authority and installation complexity across residential and institutional settings.
- Residential Homes:Single-family dwellings where homeowners control device selection and energy management participation. U.S. Inflation Reduction Act rebates and German building efficiency codes accelerate gateway adoption among households pursuing electrification retrofits. Contractor and aggregator channels displace direct utility relationships.
- Energy Providers:Utilities and energy retailers deploying HAN infrastructure for demand-response program administration and grid-edge visibility. These entities specify interoperability standards and firmware security requirements that shape vendor qualification processes across jurisdictions.
- Multi-family Units:Apartment and condominium buildings with shared metering infrastructure and landlord-mediated device deployment.
- Assisted Living Facilities:Institutional residential settings requiring simplified interfaces and remote monitoring capabilities for vulnerable populations.
Residential homes anchor volume demand. Energy providers are rotating up the share rankings as channel restructuring accelerates.
Deployment:
Architecture selection determines infrastructure capital requirements and ongoing operational control for utilities of varying scale.
- Cloud-based:Fully hosted software platforms eliminating on-premise server infrastructure and reducing IT staffing burdens for smaller utilities. Schneider Electric's deployment model opens municipal and cooperative utility segments previously excluded by capital constraints. Subscription pricing aligns vendor revenue with ongoing service delivery.
- On-premise:Locally hosted systems maintaining direct data sovereignty and minimizing external network dependency for security-sensitive operators.
- Hybrid:Architectures combining edge processing for latency-critical functions with cloud analytics for longitudinal optimization.
- Managed Services:Outsourced operational models where third parties assume firmware maintenance, security patching, and demand-response event orchestration.
On-premise retains share among large utilities. Cloud-based deployment is expanding most quickly in smaller utility segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities command premium pricing for gateway deployments under EU Green Deal mandates, while U.S. procurement channels fragment toward contractor-led retrofit bundling. This asymmetry concentrates vendor qualification investments in European certification corridors while compressing margins in North American retail channels.
United States
FERC Order 2222 aggregation rules and Inflation Reduction Act home energy rebates accelerate demand-response program enrollment. Contractors and solar-plus-storage installers now capture customer relationships previously held by direct utility procurement. California's Title 24 building efficiency codes and Texas's ERCOT demand-response markets anchor concentrated deployment corridors.
Germany
Grid modernization timelines under the EU Green Deal force accelerated smart meter replacement cycles and gateway deployments. The Federal Network Agency's interoperability mandates and building efficiency codes create concentrated vendor qualification requirements. North Rhine-Westphalia's industrial utility clusters and Bavaria's municipal cooperative networks drive procurement volume concentration.
Japan
METI's ZEH and ZEB building codes tighten technical compatibility requirements for home energy management systems, erecting certification barriers for non-compliant imports. Kanto region utilities around Tokyo and Kansai's Osaka-centered industrial corridor concentrate deployment demand. The country's semiconductor fabrication ecosystem supports domestic radio chip sourcing for gateway manufacturers.
China
Dual carbon goals and State Grid Corporation's AMI expansion targets drive smart meter procurement at scale. MIIT technical standards for home energy management systems shape domestic vendor qualification processes. Yangtze River Delta manufacturing clusters and Pearl River Delta electronics assembly hubs concentrate gateway production capacity.
United Kingdom
Ofgem's smart meter rollout mandates and retail market competition accelerate energy retailer channel restructuring. Dynamic time-of-use tariffs drive subscription-based energy management software adoption. London's fintech-utility hybrid platforms and Scotland's renewable-heavy grid zones create differentiated deployment corridors.
Smart Grid Home Area Network (HAN) Market Competitive Landscape
Enterprise networking heritage and residential building automation specialists split the market along deployment-architecture lines. The vendor base organizes into three strategic archetypes: utility-scale infrastructure providers, thermostat-integrated energy management platforms, and cloud-native deployment specialists. Consolidation pressure intensifies as protocol convergence renders single-function hardware margins unsustainable. Competitive moves center on multi-protocol gateway consolidation and subscription-based software unbundling from hardware sales.
Among enterprise networking heritage providers, Cisco Systems exemplifies the utility-scale mesh deployment archetype, while Honeywell International occupies a position within thermostat-integrated residential automation. Schneider Electric represents the cloud-native architecture approach reducing on-premise infrastructure burdens for smaller utilities. These three anchors illustrate the strategic bifurcation between commodity connectivity hardware and premium software-defined energy management services.
| Leading Market Players |
|---|
| Cisco Systems |
| Honeywell International |
| GE Energy |
| Siemens |
| Schneider Electric |
| Landis+Gyr |
| Itron |
| Control4 |
| Silver Spring Networks |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta electronics clusters anchor gateway manufacturing capacity and transmit pricing power downstream through semiconductor sourcing leverage. Multi-protocol hardware margins compress when radio chip availability tightens, while software subscription tiers expand independently of component cost cycles.
Pricing Analysis
Configured-to-order gateway deployments command substantial premiums over standard SKUs due to utility-specific interoperability certification requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies by protocol complexity and firmware customization depth. Pricing pressure stems from broadband provider bundling strategies that commoditize baseline connectivity hardware. Residential solar installers exhibit lowest price sensitivity given bundled monitoring value, while municipal utilities face acute budget constraints.
Supply Chain Analysis
Extended payment terms from Taiwan and South Korea radio chip suppliers have become standard as gateway manufacturers absorb working capital strain to secure allocation. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, while final assembly draws from China, Mexico, and Vietnam. Rare earth magnet materials and copper winding stock face commodity price volatility from concentrated mining geographies. Distribution runs through utility procurement departments, energy retailer logistics networks, and broadband provider fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positioning. Certification requirements and interoperability mandates erect barriers that compound with each deployment cycle.
For Market Incumbents: Build switching-cost moats by deepening firmware integration with utility demand-response platforms. Acquire Zigbee certification specialists to consolidate European qualification pipelines. Counter Thread protocol substitution threats through multi-protocol gateway roadmaps that preserve installed base value. For New Entrants and Emerging Players: Pursue cloud-native deployment architectures targeting municipal cooperatives excluded by on-premise capital requirements. Japan's ZEH building code certification gaps represent the most penetrable entry corridor. Partner with solar-plus-storage installers for gateway bundling that bypasses utility procurement gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a subscription-recovery play because software unbundling from hardware transforms capital expenditure cycles into recurring revenue streams. Target acquisition candidates with established utility firmware integration and cleared cybersecurity audit pathways. Monitor FERC and EU cybersecurity framework harmonization progress as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Gateway Consolidation | Thread and Matter adoption by European utilities collapses legacy Zigbee lock-in economics. |
| Cloud Deployment Architecture Expansion | Schneider Electric's hosted model opens municipal cooperative segments previously capital-constrained. |
| Certification Pipeline Investment | Japan METI and EU interoperability mandates create qualification bottlenecks favoring prepared vendors. |
| Channel Partnership with Broadband Providers | Cable and fiber operators capture customer relationships utilities once controlled exclusively. |
| Subscription Software Unbundling | German energy retailers monetize tariff optimization through dynamic time-of-use rate packaging. |
Research Methodology
A spread of perspectives from utility demand-response program managers, gateway hardware procurement leads, energy retailer platform engineers, and solar installer operations heads converged on the working assumptions. Primary fieldwork combined structured interviews with firmware security auditors and cloud deployment architects. Secondary validation drew from FERC Order 2222 implementation filings, EU Green Deal building efficiency databases, and Japan METI ZEH certification registries. Bottom-up unit deployment estimates triangulated against top-down utility capital expenditure disclosures.
Demand-supply balance modeling anchored the analytical framework across the projection horizon. Segmentation dimensions included protocol technology tier, deployment architecture type, and end-user procurement authority. CAGRs derived from utility smart meter replacement cycle timing and residential electrification retrofit penetration curves. Model inputs incorporated broadband provider bundling adoption rates and semiconductor fab capacity utilization trends.
Sensitivities concentrate around cybersecurity framework harmonization timelines and rare earth supply disruption scenarios. Forecasts reflect documented assumptions regarding regulatory mandate enforcement consistency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
India Smart Grid Network Market
Smart Grid
Microgrid Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Demand Response Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Latin America Smart Grid Security Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Smart Grid Network Market
Smart Grid
Smart Grid Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Smart Grid Technology Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Microgrid Controller Market
Smart Grid
Europe Microgrid Market
Smart Grid
Smart Grid Data Management Market