
 Middle-East Smart Grid Network Market | 2026-2036
Middle-East Smart Grid Network Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Smart Grid Network Market Foresight
Modular deployment of AMI, SCADA, and demand response as discrete purchasable units is recalibrating how utilities structure procurement cycles and vendor relationships. Siemens Energy leverages its integrated hardware-software portfolio to anchor large transmission modernization contracts across the Gulf. Huawei Technologies Co. Ltd. competes aggressively on communications-layer infrastructure, particularly 5G-enabled grid backhaul. Schneider Electric differentiates through cloud-based distribution management platforms that reduce on-premises capital intensity for mid-sized utilities.
A smart grid network integrates digital sensing, two-way communications, and automated control systems into legacy electrical infrastructure to optimize generation dispatch, reduce technical losses, and enable distributed resource participation. Advanced Metering Infrastructure leads current investment flows as utilities replace electromechanical meters with IP-connected endpoints capable of interval data logging and remote disconnect. Demand Response represents the fastest-expanding technology segment as regulators in Saudi Arabia and the UAE introduce time-of-use tariffs that reward load flexibility. Cloud-Based deployment models are capturing margin pools from smaller utilities seeking to avoid data center capital expenditure while maintaining cybersecurity compliance.
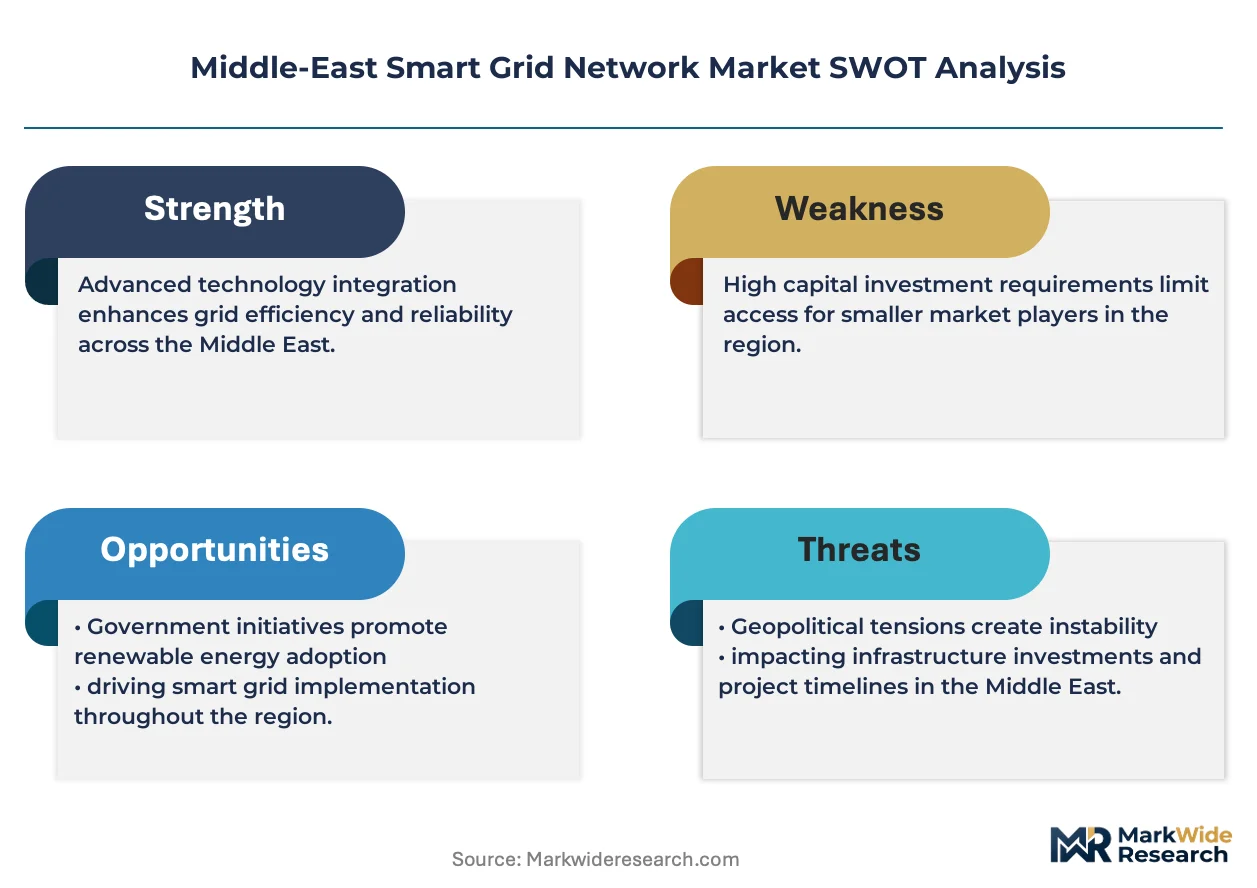
Saudi Electricity Company and DEWA operate under mandates from their respective national regulators to achieve specific renewable integration targets that require smart grid enablement. The UAE's central electricity regulatory framework and Saudi Arabia's grid codes together shape equipment certification requirements, data localization rules, and cybersecurity standards that determine vendor market access. Stakeholders must monitor how evolving carbon accounting rules and green financing eligibility criteria reshape procurement priorities across state-backed utilities.
Market Dynamics
Modular procurement of AMI, SCADA, and demand response systems is fragmenting vendor relationships across Gulf utilities as regulators mandate renewable integration timelines. This structural shift forces equipment suppliers to compete for discrete contracts rather than bundled infrastructure awards.
Growth Catalysts
- SFDA Grid Code Mandates:Saudi Arabia's electricity regulator requires smart meter penetration targets that accelerate AMI replacement cycles. Utilities must comply with interval data logging standards by fixed regulatory deadlines.
- NEOM Integrated Architecture:The giga-project's energy system design specifies two-way communications infrastructure from inception. This creates demand for greenfield smart grid deployments without legacy retrofit constraints.
- Time-of-Use Tariff Frameworks:Dubai's regulatory authority introduces dynamic pricing structures that reward load flexibility. Commercial and industrial consumers install automated demand response systems to capture rate arbitrage.
Market Restraints
- Semiconductor Supply Concentration:AMI endpoint production depends on concentrated Asian foundry capacity for power management chips. Lead times for meter-grade components extend procurement cycles.
- Data Localization Requirements:Saudi and Emirati regulations mandate domestic data storage for grid operational information. Foreign vendors must establish local cloud infrastructure, raising fixed cost barriers.
- Cybersecurity Certification Complexity:National regulators impose device-level security standards that lack mutual recognition across Gulf Cooperation Council jurisdictions. Vendors face redundant testing protocols.
Strategic Opportunities
- Oman Utility Modernization:The sultanate's rural electrification expansion lags regional peers in smart grid penetration. Greenfield distribution networks present first-mover advantages for integrated AMI-DMS providers.
- 5G-Enabled Grid Backhaul:Convergence of cellular network slicing and substation automation creates new communications-layer revenue pools. Telecom operators partner with grid technology vendors for joint infrastructure deployment.
- Green Financing Eligibility:Evolving carbon accounting rules for state-backed utilities prioritize smart grid investments in sustainability-linked loan frameworks. Equipment suppliers structure offerings to meet eligibility criteria.
Industry Challenges
- SCADA-DMS Integration Complexity:Utilities operating legacy electromechanical protection systems face multi-year migration timelines. Parallel operation of analog and digital control architectures strains operational staff.
- Cybersecurity Talent Scarcity:Gulf utilities compete with financial services and defense sectors for industrial control system security specialists. Certification requirements for critical infrastructure access limit labor pool flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Smart Grid Network Market |
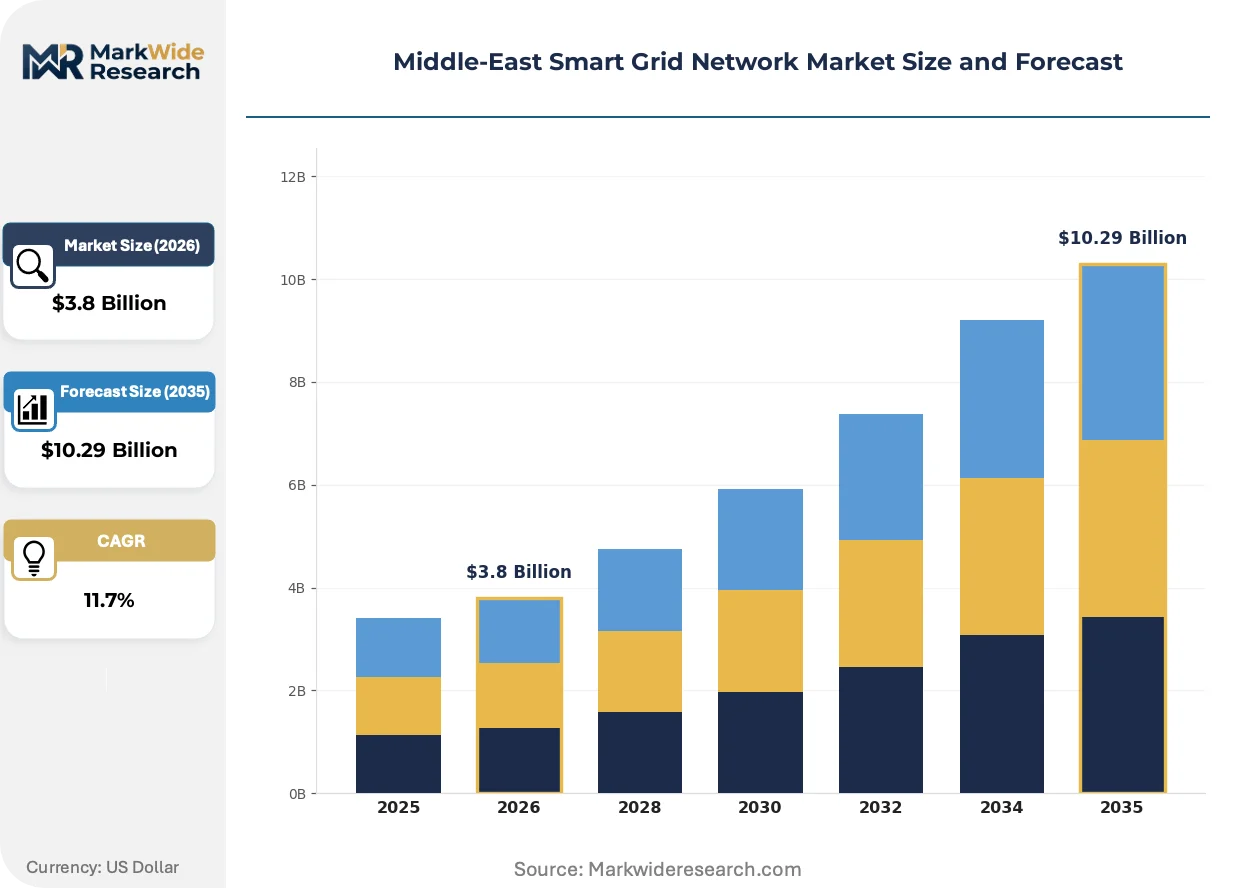
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Demand Response, Distribution Management Systems, SCADA End User: Utilities, Industrial Sector, Commercial Sector, Residential Customers Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service Application: Energy Management, Load Forecasting, Outage Management, Renewable Integration |
| Companies Covered | Siemens Energy, Huawei Technologies Co. Ltd., Saudi Electricity Company, Hitachi Energy Ltd., General Electric Company, Emirates Water and Electricity Company, Schneider Electric, Landis+Gyr, DEWA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Smart Grid Network Market Shifts & Advancements
Digital sensing convergence with cellular communications is compressing the traditional separation between distribution automation and consumer-facing demand management. Vendors reconfigure product architectures to capture margin pools at this intersection.
Artificial intelligence-based predictive maintenance is automating fault detection and isolation across medium-voltage distribution networks. Saudi Electricity Company deploys machine learning models on substation sensor streams to preempt transformer failures. This capability is automating the dispatch of field crews before customer outages occur, reducing technical losses and operational expenditure.
MOHAP and SFDA coordinate Gulf-wide cybersecurity certification frameworks for grid-connected medical and critical infrastructure loads. The UAE's health regulator and Saudi Arabia's electricity regulator jointly specify device security standards that create compliance harmonization pressure. Medical facility microgrids in Dubai and Riyadh face dual certification requirements that extend vendor qualification timelines.
Subscription-based software licensing displaces perpetual ownership models for distribution management systems. Mid-sized utilities in Kuwait and Bahrain prefer operational expenditure treatment for grid analytics platforms. This shift concentrates vendor revenue into recurring streams while reducing utility capital commitment for data center infrastructure.
Middle-East Smart Grid Network Market Segmentation
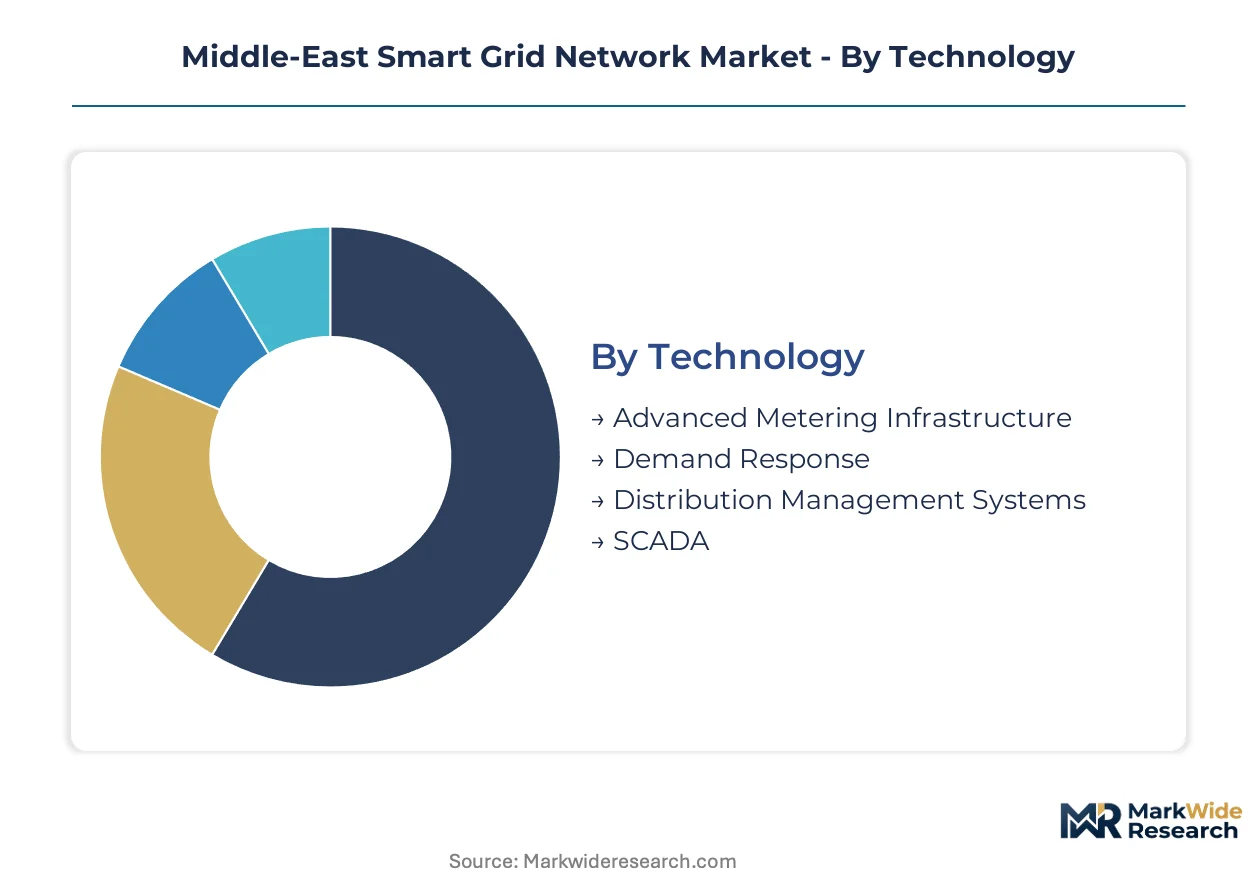
Segmentation reveals how procurement patterns diverge across technology maturity, customer scale, and deployment economics in Middle Eastern smart grid infrastructure. Each axis exposes distinct vendor margin pools and integration complexity thresholds that shape competitive positioning.
Technology:
Technology segmentation traces the evolution from meter-level data capture toward system-wide predictive control architectures.
- Advanced Metering Infrastructure:IP-connected endpoints with interval data logging and remote disconnect capabilities form the foundational layer. Saudi Electricity Company and DEWA drive concentrated demand as SFDA and the UAE's regulatory authority mandate replacement deadlines for electromechanical meters.
- Demand Response:Automated load curtailment systems enable commercial and industrial consumers to capture time-of-use tariff arbitrage. Dubai's regulatory authority and Saudi Arabia's grid codes are accelerating deployment as dynamic pricing frameworks expand across the Gulf.
- Distribution Management Systems:Cloud-based platforms for real-time network visibility and switching optimization. Mid-sized utilities in Kuwait and Bahrain favor subscription licensing to avoid data center capital intensity.
- SCADA:Supervisory control systems for transmission and substation automation. Legacy electromechanical protection integration creates multi-year migration timelines for established utilities.
Mature deployment sits with Advanced Metering Infrastructure. Newer deployment is concentrated in Demand Response.
End User:
End user segmentation maps how regulatory mandates and tariff structures differentially activate investment across customer classes.
- Utilities:State-backed transmission and distribution operators under renewable integration mandates from national regulators. Saudi Electricity Company and DEWA anchor procurement volumes for AMI and SCADA modernization.
- Industrial Sector:Petrochemical, aluminum smelting, and desalination facilities with high load flexibility and exposure to time-of-use pricing. Automated demand response installation rates climb fastest in this segment.
- Commercial Sector:Shopping malls, data centers, and hospital complexes in Dubai and Riyadh. Dual cybersecurity certification from MOHAP and SFDA extends vendor qualification timelines for medical facility microgrids.
- Residential Customers:Smart meter endpoints with in-home energy displays lag industrial and commercial adoption. Regulatory mandates rather than price signals currently drive deployment.
Procurement scale concentrates with Utilities. Margin expansion is concentrated in Industrial Sector.
Deployment Model:
Deployment model segmentation captures the shift from capital-intensive ownership toward operational expenditure treatment.
- On-Premises:Dedicated data center infrastructure for grid operational technology. Saudi and Emirati data localization requirements mandate domestic storage, raising fixed cost barriers for foreign vendors.
- Cloud-Based:Vendor-hosted platforms with utility subscriber access. Mid-sized utilities across Kuwait and Bahrain prefer this model to reduce cybersecurity compliance burden and eliminate hardware refresh cycles.
- Hybrid:Sensitive operational data remains on-premises while analytics workloads shift to cloud. This architecture addresses regulatory fragmentation across Gulf Cooperation Council jurisdictions.
- Managed Service:Outsourced grid operations and maintenance with performance guarantees. Emerging option for rural electrification expansion in Oman where technical talent scarcity strains utility staffing.
Established deployment sits with On-Premises. Fastest expansion is concentrated in Cloud-Based.
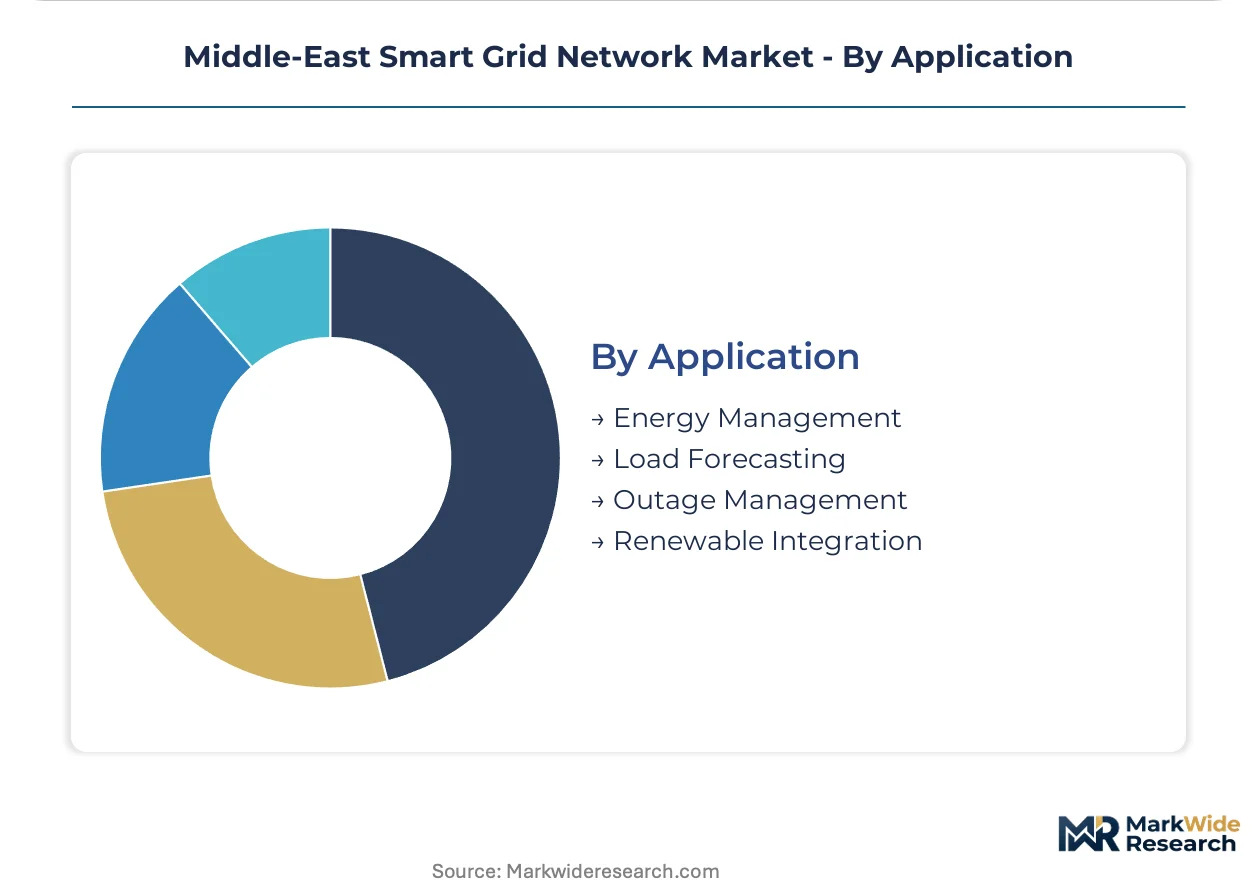
Application:
Application segmentation tracks functional priorities from operational efficiency toward renewable accommodation.
- Energy Management:Real-time consumption monitoring and automated efficiency optimization. Foundation capability deployed across all customer classes.
- Load Forecasting:Machine learning models predicting demand patterns from weather and economic indicators. Saudi Electricity Company deploys these on substation sensor streams to preempt transformer failures.
- Outage Management:Automated fault detection, isolation, and restoration. AI-based predictive maintenance is compressing response times across medium-voltage distribution networks.
- Renewable Integration:Grid stabilization and dispatch optimization for solar and wind capacity. NEOM's greenfield energy architecture specifies two-way communications infrastructure from inception without legacy retrofit constraints.
Operational deployment sits with Energy Management. Steepest expansion trajectory is concentrated in Renewable Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NEOM's special economic zone status accelerates smart grid deployment timelines by exempting greenfield projects from legacy retrofit constraints. This tax-advantaged corridor concentrates vendor engineering resources and creates reference architectures for national utility adoption across the Gulf Cooperation Council.
Saudi Arabia
Saudi Electricity Company's transmission expansion and NEOM's integrated energy architecture drive concentrated demand for AMI and SCADA systems. SFDA grid code mandates require smart meter penetration targets with fixed deadlines for interval data logging compliance. Riyadh and the Eastern Province anchor procurement volumes as state-backed utilities execute renewable integration timelines.
United Arab Emirates
DEWA operates under mandates from the UAE's central electricity regulatory framework to achieve specific renewable integration targets requiring smart grid enablement. Dubai's regulatory authority introduces time-of-use tariffs that reward load flexibility and accelerate automated demand response installation. Commercial and industrial clusters in Dubai and Abu Dhabi face dual cybersecurity certification requirements from MOHAP and SFDA that extend vendor qualification timelines.
Oman
The sultanate's rural electrification expansion lags regional peers in smart grid penetration and presents first-mover advantages for integrated AMI-DMS providers. National regulators mandate grid modernization to accommodate solar capacity additions in distributed generation zones. Greenfield distribution networks in rural governorates create procurement opportunities without legacy electromechanical protection constraints.
Kuwait
Mid-sized utilities prefer cloud-based deployment models with subscription licensing to reduce data center capital intensity and cybersecurity compliance burden. The Ministry of Electricity and Water procurement frameworks favor operational expenditure treatment for grid analytics platforms. Urban distribution networks in Kuwait City concentrate demand for vendor-hosted platforms with domestic data localization infrastructure.
Qatar
Utility modernization programs align with national renewable energy targets that require two-way communications infrastructure for grid stabilization. Kahramaa's regulatory mandates specify equipment certification requirements and data localization rules that determine vendor market access. Industrial zones surrounding Doha concentrate demand response deployment as petrochemical facilities seek rate arbitrage under emerging dynamic pricing frameworks.
Middle-East Smart Grid Network Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across discrete technology layers rather than bundled infrastructure awards. Siemens Energy leverages integrated hardware-software portfolios to anchor large transmission modernization contracts, while Huawei Technologies Co. Ltd. competes aggressively on communications-layer infrastructure. Three strategic archetypes dominate: integrated technology conglomerates, communications infrastructure specialists, and cloud-native software providers. M&A activity concentrates on communications-layer capabilities, while strategic partnerships between telecom operators and grid technology vendors accelerate 5G-enabled substation automation deployment.
Within the integrated technology tier, Siemens Energy and Hitachi Energy Ltd. exemplify vendors with transmission-scale project execution capabilities. Schneider Electric occupies a position among cloud-native providers reducing on-premises capital intensity for mid-sized utilities. Huawei Technologies Co. Ltd. represents the communications infrastructure archetype, particularly for 5G-enabled grid backhaul applications. These three companies illustrate how vendor positioning fragments across AMI, SCADA, demand response, and distribution management system layers as modular procurement recalibrates utility-vendor relationships.
| Leading Market Players |
|---|
| Siemens Energy |
| Huawei Technologies Co. Ltd. |
| Saudi Electricity Company |
| Hitachi Energy Ltd. |
| General Electric Company |
| Emirates Water and Electricity Company |
| Schneider Electric |
| Landis+Gyr |
| DEWA |
| Others |
Supply & Pricing Matrix
SFDA renewable integration mandates gate qualified supply access and premium-tier pricing for grid technology vendors serving Saudi Electricity Company and NEOM. These sustainability-linked procurement frameworks concentrate pricing power among certified suppliers while excluding uncertified competitors from state-backed utility contracts.
Pricing Analysis
Margin tightening in AMI endpoints reflects concentrated Asian foundry capacity for power management semiconductors. Three-tier pricing structure across certified-premium, standard-compliant, and economy-unverified levels differentiates vendors by cybersecurity certification tier and data localization compliance. Pricing pressure accelerates as mid-sized utilities in Kuwait and Bahrain shift subscription licensing for cloud-based distribution management systems. Industrial sector buyers exhibit lowest price sensitivity due to time-of-use tariff arbitrage capture, while residential smart meter deployment remains mandate-driven with minimal voluntary uptake.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced meter-grade semiconductor fabrication. AMI endpoint production draws from concentrated Asian foundry capacity, power management integrated circuits, and cellular communications modules. Tariff exposure on electronics imports from concentrated manufacturing zones threatens procurement cycle stability. Distribution runs through authorized systems integrators and direct utility procurement frameworks across Gulf Cooperation Council jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle-East smart grid network market sits in a technology-transition phase where cloud-native distribution management platforms displace legacy on-premises SCADA architectures. IP-connected AMI endpoints and AI-based predictive maintenance systems are supplanting electromechanical protection and manual fault response workflows.
For Market Incumbents: Anticipate margin compression from modular procurement fragmentation by anchoring large transmission contracts through integrated hardware-software portfolios. Defend against communications-layer specialists by deepening 5G-enabled grid backhaul partnerships with telecom operators. Prioritize cybersecurity certification investment to maintain SFDA and MOHAP compliance access.
For New Entrants and Emerging Players: Cloud-based subscription licensing for mid-sized utilities offers the most penetrable entry vector. Target Oman's rural electrification expansion where greenfield distribution networks lack legacy retrofit constraints. Pursue joint infrastructure deployment with cellular operators for substation automation backhaul.
For Investors and Strategic Acquirers: Accelerating M&A activity in communications-layer capabilities is the leading indicator that vendor consolidation is compressing the competitive set. Long-term viability favors integrated technology conglomerates with transmission-scale execution capability. Monitor green financing eligibility criteria evolution as the inflection signal for procurement priority shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| 5G-Enabled Grid Backhaul Partnership | Telecom operators and grid vendors jointly deploy cellular network slicing for substation automation across Dubai and Riyadh. |
| Cloud-Based DMS Platform Launch | Subscription licensing reduces capital intensity for Kuwaiti and Bahraini utilities seeking cybersecurity compliance. |
| Cybersecurity Certification Investment | Dual MOHAP-SFDA compliance opens medical facility microgrid contracts in Dubai and Riyadh. |
| AMI-DMS Integration Capability Buildout | First-mover advantages emerge in Oman's rural electrification expansion without legacy constraints. |
| Green Financing Eligibility Structuring | Equipment suppliers align offerings with evolving carbon accounting rules for state-backed utility loans. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with utility planning officers, grid operators, EPC contractors, and IPP project developers combined with SFDA mandates, DEWA procurement disclosures, and Gulf Cooperation Council customs data. Bottom-up endpoint deployment estimates triangulated against top-down infrastructure investment forecasts.
Segment-level granularity modeled technology type, deployment model, end-user scale, and application function across the projection horizon. CAGRs derived from regression analysis of historical procurement cycles against regulatory mandate timelines. Forecast inputs incorporated renewable integration targets, smart meter penetration deadlines, and data localization requirement evolution.
The model holds under stable regulatory enforcement and semiconductor supply continuity; deviation in tariff regimes or foundry capacity allocation would shift deployment timelines. Forecasts reflect documented assumptions about mandate adherence and vendor qualification pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Grid Communications Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Demand Response Market
Smart Grid
China Smart Grid Network Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
Europe Microgrid Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
South and Central America Smart Grid Market