
 Smart Microgrid Market | 2026-2036
Smart Microgrid Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Microgrid Market Analytics
Utility providers is reorganizing procurement priorities away from large centralized assets toward modular, island-capable microgrids. Siemens leverages its digital grid software stack to anchor European utility modernization programs. Tesla competes through vertically integrated battery-inverter architectures that slash commissioning timelines for commercial buyers. Schneider Electric dominates the control systems layer with hardware-agnostic platforms spanning multiple generation sources.
A smart microgrid constitutes a localized energy system integrating distributed generation, storage, and load management through bi-directional communication protocols, typically operating between 480V and 34.5kV depending on scale and interconnection requirements. Its primary commercial purpose is to maintain power quality and continuity independently from or in parallel with the central grid. Grid Storage captures the deepest margin pools as lithium-ion and emerging solid-state chemistries absorb peak shaving and frequency regulation workloads. Distributed Energy Resources within the technology dimension leads deployment velocity, pairing rooftop solar with battery assets behind single meters. The application split favors Industrial sites seeking tariff arbitrage and resilience against utility rate volatility.
The US Inflation Reduction Act and FERC Order 2222 reshape market access by enabling aggregated distributed resources to bid into wholesale markets, compelling control system upgrades. IEEE 1547-2018 interconnection standards in North America and the EU's Clean Energy Package collectively mandate grid-supportive functionality rather than simple backup operation. Stakeholders must decide whether to build software competency in-house or partner as microgrids evolve from hardware projects to ongoing energy-as-a-service relationships.
Market Dynamics
Utility procurement departments are abandoning centralized generation contracts in favor of modular, island-capable microgrids that can island during grid disturbances. This structural pivot compresses project timelines from years to months and redefines vendor relationships around operational performance rather than equipment delivery.
Growth Catalysts
- US Inflation Reduction Act standalone storage incentives:Federal tax credits now apply to battery assets independent of solar pairing, unlocking behind-the-meter deployments at industrial campuses and municipal facilities.
- California Public Safety Power Shutoff mandates:Wildfire-driven de-energization protocols compel municipal utility districts to procure resilient distributed systems for critical infrastructure.
- FERC Order 2222 aggregation frameworks:Wholesale market access for pooled distributed resources creates revenue streams that justify control system investments previously uneconomic at small scale.
Market Restraints
- Lithium carbonate price volatility:Battery storage constitutes the dominant cost component, and raw material swings compress developer margins and financing viability.
- North American inverter supply concentration:Domestic manufacturing capacity for power electronics remains insufficient, creating procurement bottlenecks for projects exceeding 10MW.
- IEEE 1547-2018 interconnection complexity:Grid-supportive functionality requirements extend engineering timelines and inflate soft costs for smaller developers lacking utility relationships.
Strategic Opportunities
- India rural electrification gaps:Distributed microgrids bypass transmission infrastructure deficits in Bihar and Uttar Pradesh, serving agricultural processing loads without grid extension.
- EU Clean Energy Package citizen energy frameworks:Regulatory recognition of energy communities enables novel ownership structures aggregating residential and commercial assets.
- AI-driven predictive control convergence:Machine learning layer integration with traditional SCADA architectures enables automated islanding decisions and demand response optimization.
Industry Challenges
- Power systems engineering talent scarcity:Control system architecture and protection coordination expertise concentrates at aging utilities and a handful of specialized consultancies.
- Multi-vendor integration complexity:Hardware-agnostic software platforms must reconcile proprietary communication protocols across battery, inverter, and generation assets from disparate suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Microgrid Market |
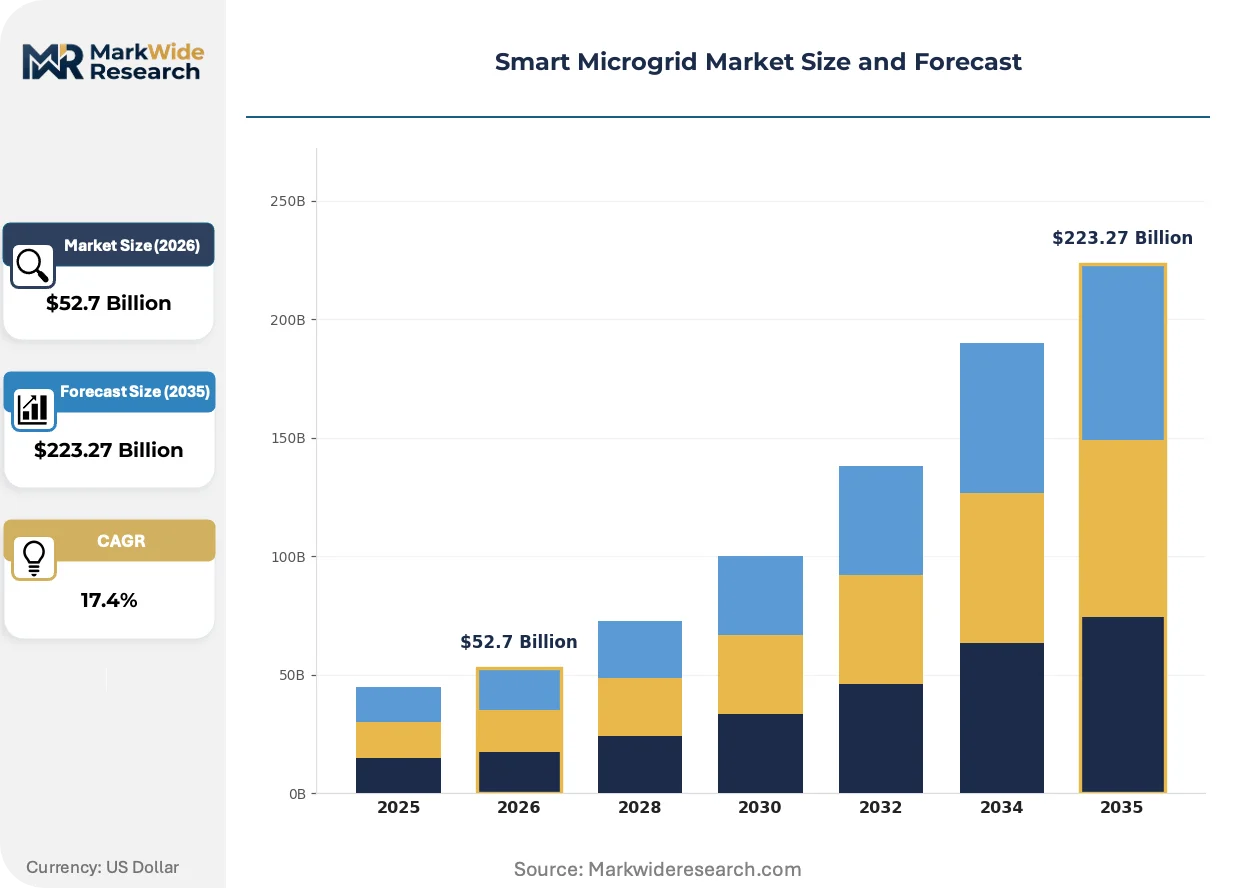
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $223.27 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grid Storage, Control Systems, Communication Systems, Generators Application: Residential, Commercial, Industrial, Utilities Technology: Renewable Integration, Demand Response, Energy Management, Distributed Energy Resources End User: Government, Utility Providers, Enterprises, Educational Institutions |
| Companies Covered | Schneider Electric, Siemens, General Electric, ABB, Eaton, Hitachi Energy, Honeywell International, Tesla, Enel X, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Microgrid Market Evolving Landscape
Solid-state battery chemistries and silicon carbide power electronics are compressing system footprints and thermal management requirements. These material shifts enable containerized deployments in space-constrained urban environments and accelerate commissioning timelines for commercial buyers.
Solid-state lithium-metal architectures are supplanting conventional liquid electrolyte designs in premium microgrid storage applications. Data center operators and semiconductor fabs are piloting these systems for their reduced fire risk and higher energy density. The technology is compressing footprint requirements by 40 percent and eliminating complex thermal management subsystems that dominate conventional battery room engineering.
The EU F-Gas Regulation phase-down is accelerating adoption of natural refrigerant-based cooling for power conversion equipment. This mandates redesign of inverter and transformer thermal systems ahead of 2030 bans on hydrofluorocarbon coolants. German and Dutch industrial microgrid deployments are now specifying CO2-based cooling loops to preempt compliance retrofit costs.
Energy-as-a-service contracting is displacing traditional equipment purchase models among commercial and institutional buyers. Facility managers at universities and hospital systems are transferring operational risk to vendors through performance-guaranteed service agreements. California and New York lead this transition, where property owners prioritize resilience outcomes over capital asset ownership.
Smart Microgrid Market Segmentation
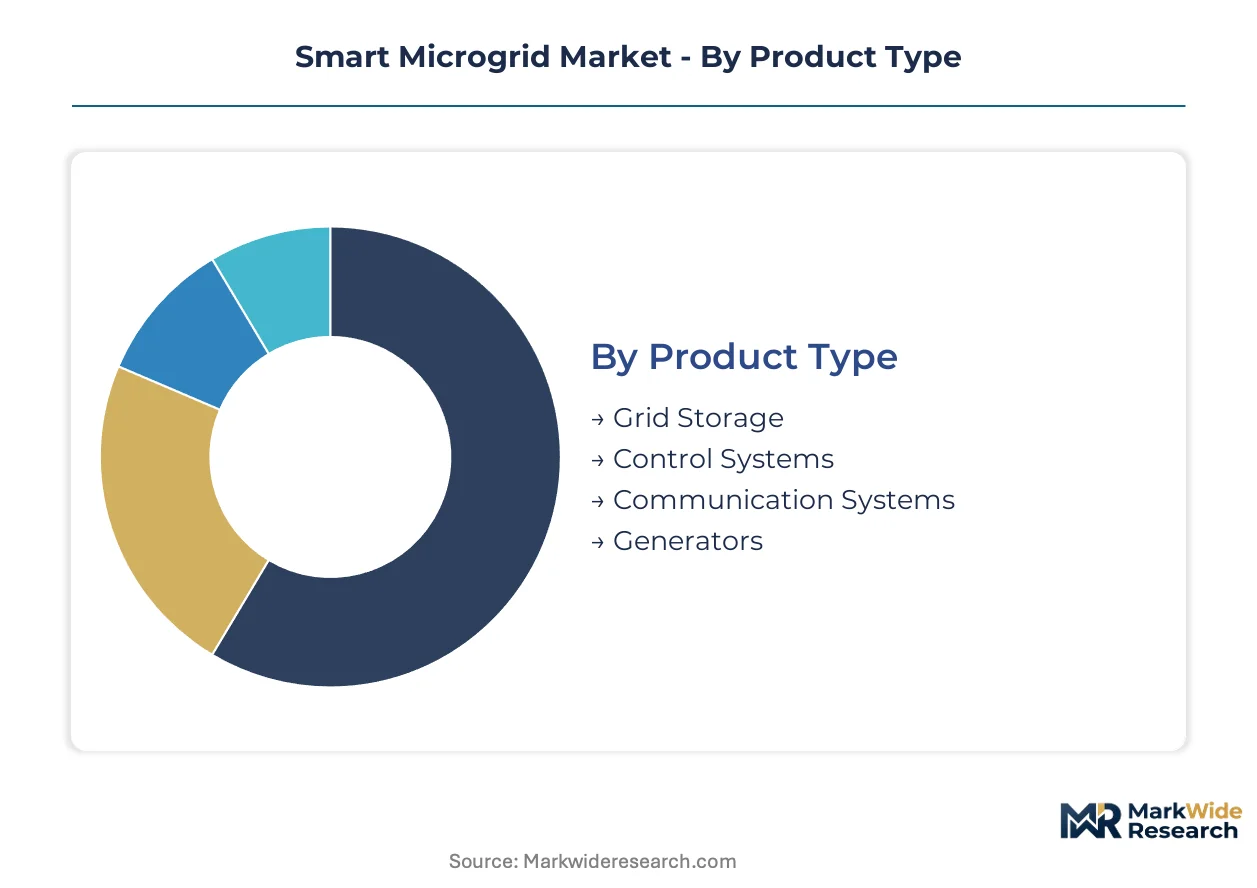
Smart microgrid architectures fragment across hardware, software, and service layers. Procurement patterns diverge sharply between utility-scale deployments and behind-the-meter commercial installations. Understanding these fault lines exposes where vendor margins concentrate and where commoditization pressures intensify.
Product Type:
Grid Storage faces acute substitution pressure from alternative resilience investments including backup generators and fuel cells, forcing lithium-ion suppliers to differentiate through software integration and warranty terms.
- Grid Storage:Battery systems utilizing lithium-ion and emerging solid-state chemistries absorb peak shaving, frequency regulation, and islanding workloads. Demand concentrates at California municipal utility districts where Public Safety Power Shutoff mandates compel behind-the-meter resilience investments at critical facilities.
- Control Systems:Hardware-agnostic software platforms coordinate protection, dispatch, and market participation across multi-vendor assets. Industrial campuses in Texas and New York prioritize these systems to capture FERC Order 2222 aggregation revenues from pooled distributed resources.
- Communication Systems:Bi-directional protocols enabling real-time telemetry between field devices and central management platforms.
- Generators:Natural gas and diesel prime movers providing spinning reserve and black-start capability for islanded operation.
Grid Storage anchors the volume base while Control Systems gains share at the steepest rate.
Application:
Cost tier stratification separates premium resilience buyers from price-sensitive adopters, with tariff arbitrage opportunities determining willingness to pay for advanced functionality.
- Industrial:Manufacturing and processing facilities operating mission-critical loads requiring sub-cycle transfer switching and voltage regulation. Semiconductor fabs and data centers in Arizona and Oregon drive procurement of solid-state battery architectures for reduced fire risk and footprint compression.
- Commercial:Retail, hospitality, and office properties seeking demand charge management and backup power for revenue protection. Multi-site operators in Florida and Georgia prioritize standardized containerized deployments that accelerate commissioning across distributed portfolios.
- Utilities:Investor-owned and municipal grid operators procuring front-of-meter assets for distribution deferral and ancillary services.
- Residential:Single-family and multi-family dwellings with rooftop solar pairing and outage protection as primary value propositions.
Industrial applications command the highest per-site spending while Commercial deployments expand most quickly across regional portfolios.
Technology:
Technology maturity curves separate proven integration approaches from emerging control methodologies still seeking scale validation.
- Distributed Energy Resources:Behind-the-meter solar-plus-storage assets operating under single meter aggregation with bi-directional grid interconnection. Pairing concentrates in Hawaii and Puerto Rico where high retail rates and grid instability accelerate payback periods for commercial adopters.
- Demand Response:Automated load curtailment and modulation protocols enabling participation in wholesale capacity and energy markets. Industrial facilities in PJM and ERCOT territories leverage these capabilities to capture capacity performance payments during peak events.
- Renewable Integration:Power electronics and control logic managing variable output from solar PV and wind turbines.
- Energy Management:Optimization algorithms balancing generation, storage, and load against tariff structures and market signals.
Distributed Energy Resources dominates installed capacity while Demand Response climbs the fastest as market access rules mature.
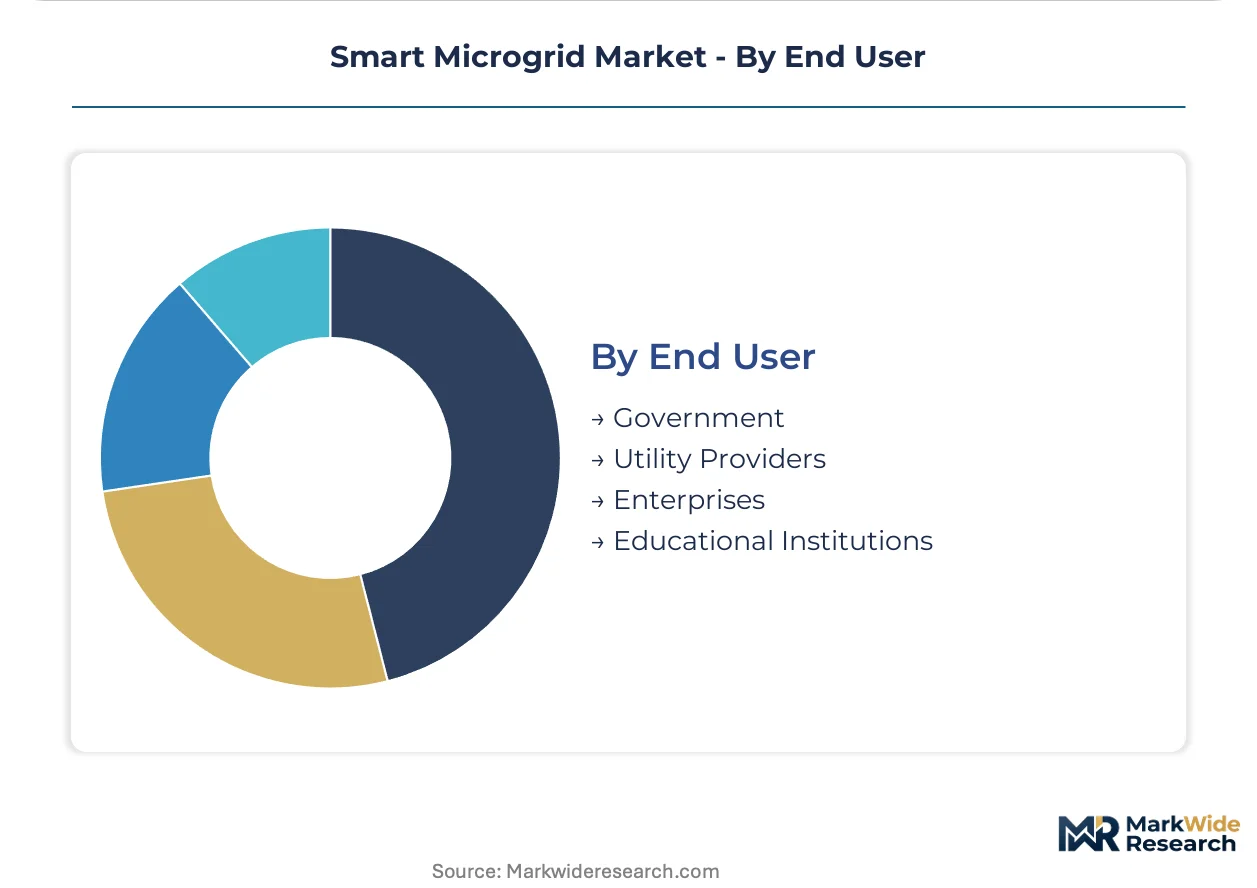
End User:
Customer procurement sophistication ranges from technical specification-driven enterprises to outcome-oriented institutions seeking performance guarantees.
- Utility Providers:Grid operators modernizing distribution infrastructure through modular, island-capable microgrids that compress project timelines from years to months. Procurement concentrates at California municipal utility districts responding to wildfire-driven de-energization protocols.
- Enterprises:Corporations with explicit resilience targets and sustainability commitments driving direct procurement of behind-the-meter assets. Technology and pharmaceutical firms in Massachusetts and North Carolina prioritize energy-as-a-service contracts that transfer operational risk to vendors.
- Government:Federal, state, and local agencies securing critical infrastructure against extended outages.
- Educational Institutions:Universities and research campuses with combined heat and power assets seeking to optimize dispatch and participate in wholesale markets.
Utility Providers anchor the revenue base while Enterprises show the steepest expansion trajectory through performance-guaranteed service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial campuses and municipal utilities drive procurement concentration. California's wildfire protocols, Germany's distribution modernization, and India's rural electrification gaps anchor distinct demand archetypes across geographies.
United States
FERC Order 2222 aggregation frameworks and IRA standalone storage incentives compel control system upgrades at Texas industrial facilities and New York commercial campuses. California municipal utility districts respond to Public Safety Power Shutoff mandates with behind-the-meter resilience investments at critical infrastructure sites.
Germany
Distribution grid operators modernize infrastructure through modular island-capable architectures that compress project timelines. The EU F-Gas Regulation phase-down accelerates adoption of natural refrigerant-based cooling for power conversion equipment ahead of 2030 hydrofluorocarbon bans. Industrial deployments in the Ruhr region and Bavaria specify CO2-based cooling loops to preempt compliance retrofit costs.
India
Agricultural processing loads in Bihar and Uttar Pradesh bypass transmission infrastructure deficits through distributed microgrids without grid extension. The CEA mandates grid-supportive functionality standards for distributed energy resources. Rural electrification gaps concentrate deployment velocity in eastern and northern states where centralized grid extension remains uneconomic.
Japan
Semiconductor fabs and data center operators pilot solid-state battery architectures for reduced fire risk and footprint compression. METI promotes energy-as-a-service frameworks that transfer operational risk from facility managers to vendors. Industrial microgrid procurement concentrates in the Kanto and Kansai regions where manufacturing density justifies behind-the-meter resilience investments.
China
Dual carbon goals accelerate renewable integration mandates for industrial parks and export manufacturing zones. MIIT standards govern bi-directional communication protocols between distributed generation assets and grid management platforms. Deployment clusters concentrate in the Yangtze River Delta and Pearl River Delta where manufacturing load density supports tariff arbitrage economics.
Smart Microgrid Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with power systems heritage. Siemens leverages digital grid software stacks to anchor European utility modernization programs. Schneider Electric dominates control systems with hardware-agnostic platforms spanning multiple generation sources. Tesla competes through vertically integrated battery-inverter architectures that slash commissioning timelines. Consolidation pressures intensify as microgrids evolve from hardware projects to ongoing energy-as-a-service relationships. Strategic moves concentrate on software competency build-versus-partner decisions and operational performance guarantees rather than equipment delivery metrics.
Within the diversified industrial tier, Schneider Electric, Siemens, and Tesla occupy distinct positioning vectors. Schneider Electric exemplifies the control systems specialist archetype with broad protocol compatibility across vendor ecosystems. Siemens anchors European utility relationships through integrated digital grid offerings. Tesla represents the vertically integrated challenger model with captive battery and power electronics supply. These three entities collectively illustrate how vendor strategies diverge between hardware-agnostic platform plays and captive component integration approaches.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| General Electric |
| ABB |
| Eaton |
| Hitachi Energy |
| Honeywell International |
| Tesla |
| Enel X |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with lithium carbonate indexation lock in battery supply access and price visibility for California municipal utilities and Texas industrial campuses navigating IRA incentive timelines. These contracts transfer raw material volatility risk to suppliers while securing commissioning slots at constrained inverter manufacturing facilities.
Pricing Analysis
Cost-plus contracts with quarterly lithium carbonate indexation dominate grid storage procurement, tying final system costs to Shanghai Metals Market spot movements. Price differentiation separates UL-certified industrial-tier systems with 20-year warranties from commercial-grade alternatives with shorter coverage periods. Pricing pressure stems from silicon carbide power electronics commoditization as Chinese suppliers expand capacity. Commercial multi-site operators in Florida and Georgia show highest price sensitivity, while Arizona semiconductor fabs prioritize fire-risk specifications over unit economics.
Supply Chain Analysis
Strategic stockpiling of power electronics and battery cells has displaced just-in-time preferences as lead times for 10MW+ inverters stretch beyond 18 months. Manufacturing concentrates in China for lithium-ion cells, South Korea for cathode materials, and Germany for industrial control systems. The supply chain rests on refined lithium from Chile and Australia, cobalt from the DRC, and high-purity silicon from polysilicon plants in Xinjiang and Inner Mongolia. Single-source vulnerability in IGBT semiconductor production creates procurement bottlenecks. Distribution runs through EPC contractors with utility relationships rather than direct manufacturer-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, as IEEE 1547-2018 certification requirements and utility interconnection queues create switching costs that cement incumbent positions.
For Market Incumbents: Secure control system software competency through acquisition of specialized protection coordination consultancies, as power systems engineering talent scarcity threatens project execution timelines. Deepen backward integration into silicon carbide wafer production to reduce exposure to inverter supply concentration. California Public Safety Power Shutoff mandates and FERC Order 2222 aggregation frameworks favor vendors with existing utility relationships.
For New Entrants and Emerging Players: Lead with AI-driven predictive control modules that integrate with legacy SCADA architectures, targeting industrial campuses in ERCOT and PJM territories seeking automated islanding capabilities. India rural electrification gaps in Bihar and Uttar Pradesh offer the most penetrable geography, bypassing transmission infrastructure deficits without competing for utility procurement slots. Energy-as-a-service contracting models reduce customer capital barriers and accelerate initial deployments.
For Investors and Strategic Acquirers: The market sits at a standardization phase that favors control system specialists with hardware-agnostic platforms over vertically integrated hardware vendors. Long-term viability over the next decade hinges on software recurring revenue streams rather than equipment margins. Acquisition targets should demonstrate operational performance guarantees across multiple vendor ecosystems. The signal to watch is FERC implementation timelines for Order 2222 aggregation rules, which would accelerate control system upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Control System Software Acquisition | Protection coordination expertise concentrates at aging utilities and specialized consultancies, creating scarcity value. |
| Solid-State Battery Pilot Deployment | Data center operators in Japan and Arizona validate reduced fire risk and 40 percent footprint compression. |
| Natural Refrigerant Cooling Transition | German and Dutch industrial sites specify CO2-based loops to preempt EU F-Gas Regulation 2030 compliance costs. |
| Energy-as-a-Service Contracting | California and New York facility managers transfer operational risk to vendors through performance-guaranteed agreements. |
| AI Predictive Control Integration | Machine learning layers automate islanding decisions and demand response optimization for ERCOT industrial campuses. |
Research Methodology
A spread of perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators converged on the working assumptions for deployment velocity and technology substitution patterns. Primary fieldwork combined structured interviews with secondary validation through EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity and project pipeline analysis triangulated against top-down regulatory incentive modeling to constrain forecast variance.
Segmentation dimensions modeled include generation capacity tier, project scale, regulatory framework, and regional grid type across the analysis window. CAGRs derived from installed base evolution and replacement cycle analysis, cross-checked against utility procurement budget disclosures and inverter manufacturing capacity expansion announcements. Technology cost curves for lithium-ion and solid-state chemistries informed storage system price elasticity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained IRA incentive continuity and IEEE 1547-2018 interconnection standard adoption would require recalibration. Forecasts reflect assumptions regarding raw material price normalization and power electronics supply expansion. Revision becomes warranted when lithium carbonate volatility or inverter manufacturing bottlenecks cross thresholds that compress developer financing viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Grid Data Management Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Energy Switch Market
Smart Grid
Demand Response Market
Smart Grid
North America Microgrid Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Global Microgrid As a Service Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
South Africa Smart Grid Network Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
Smart Grid Network Market
Smart Grid
China Smart Grid Network Market
Smart Grid
North America Smart Grid Market