
 Microgrid Controller Market | 2026-2036
Microgrid Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Microgrid Controller Market Outlook
Modular controller bundling is shifting procurement patterns across the microgrid sector. Schneider Electric leverages its EcoStruxure platform to anchor integrated hardware-software offerings for commercial and industrial deployments. Siemens competes through its Spectrum Power suite, which specializes in real-time grid optimization for utility-scale installations. General Electric differentiates via its Power Digital portfolio, extending predictive analytics capabilities into controller firmware for distributed generation assets.
A microgrid controller is a hardware-software system that manages power flow, frequency regulation, and load dispatch across distributed energy resources with response times typically under 100 milliseconds. Its primary purpose is maintaining grid stability during islanded operation or seamless transitions between grid-connected and standalone modes. Centralized controllers dominate current utility procurement due to proven reliability in large-scale deployments, though edge computing architectures are gaining traction in remote industrial applications where latency requirements preclude cloud dependency. Software controllers represent the fastest-expanding segment as utilities prioritize API-driven interoperability with existing SCADA infrastructure.
FERC Order 2222 in the United States compels regional grid operators to accommodate aggregated distributed resources, directly expanding the addressable market for controller systems that manage multi-asset portfolios. IEEE 1547-2018 standards for interconnection and interoperability shape product development requirements, forcing manufacturers to certify voltage ride-through and communication protocols. NERC CIP cybersecurity mandates add compliance layers that favor established vendors with dedicated certification teams. Stakeholders must monitor how state-level resilience mandates evolve alongside federal grid modernization funding disbursement timelines.
Market Dynamics
Modular software architectures are compressing controller deployment timelines from months to weeks, forcing incumbent hardware vendors to restructure product roadmaps around API-first interoperability.
Growth Catalysts
- FERC Order 2222:The United States mandate for distributed energy resource aggregation compels regional grid operators to procure multi-asset control platforms, expanding addressable demand across utility-scale deployments.
- Wildfire resilience mandates:California utilities face state-mandated de-energization protocols that require island-capable microgrids for critical facility backup, concentrating procurement in high-fire-threat districts.
- Edge computing architectures:Latency-sensitive industrial applications in remote mining and oilfield operations are adopting localized control nodes that operate independently of cloud connectivity.
Market Restraints
- Semiconductor supply concentration:Controller manufacturing depends on specialized power electronics chips sourced primarily from East Asian foundries, exposing lead times to geopolitical disruption.
- Cybersecurity certification costs:NERC CIP compliance requires dedicated engineering teams and third-party auditing, creating capital barriers for smaller controller vendors entering utility procurement.
- Legacy SCADA lock-in:Existing utility infrastructure operates on proprietary communication protocols that resist seamless integration with open-architecture controllers.
Strategic Opportunities
- Texas winter storm hardening:Post-2021 grid failure legislation funds microgrid installations at hospitals, water treatment plants, and emergency centers across ERCOT territory.
- AI-driven predictive control:Machine learning algorithms converging with traditional PID control logic enable anticipatory load dispatch that reduces battery cycling costs.
- Behind-the-meter commercial growth:Retail electricity volatility is pushing data centers, cold storage facilities, and manufacturing plants toward self-managed microgrids with controller-managed asset optimization.
Industry Challenges
- Control systems engineering talent scarcity:Utilities and vendors compete for specialists fluent in both power electronics and real-time software development, compressing project staffing timelines.
- Multi-protocol integration complexity:Deployments must reconcile IEEE 1547-2018, Modbus, DNP3, and emerging IEC 61850 standards within single controller installations, extending commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microgrid Controller Market |
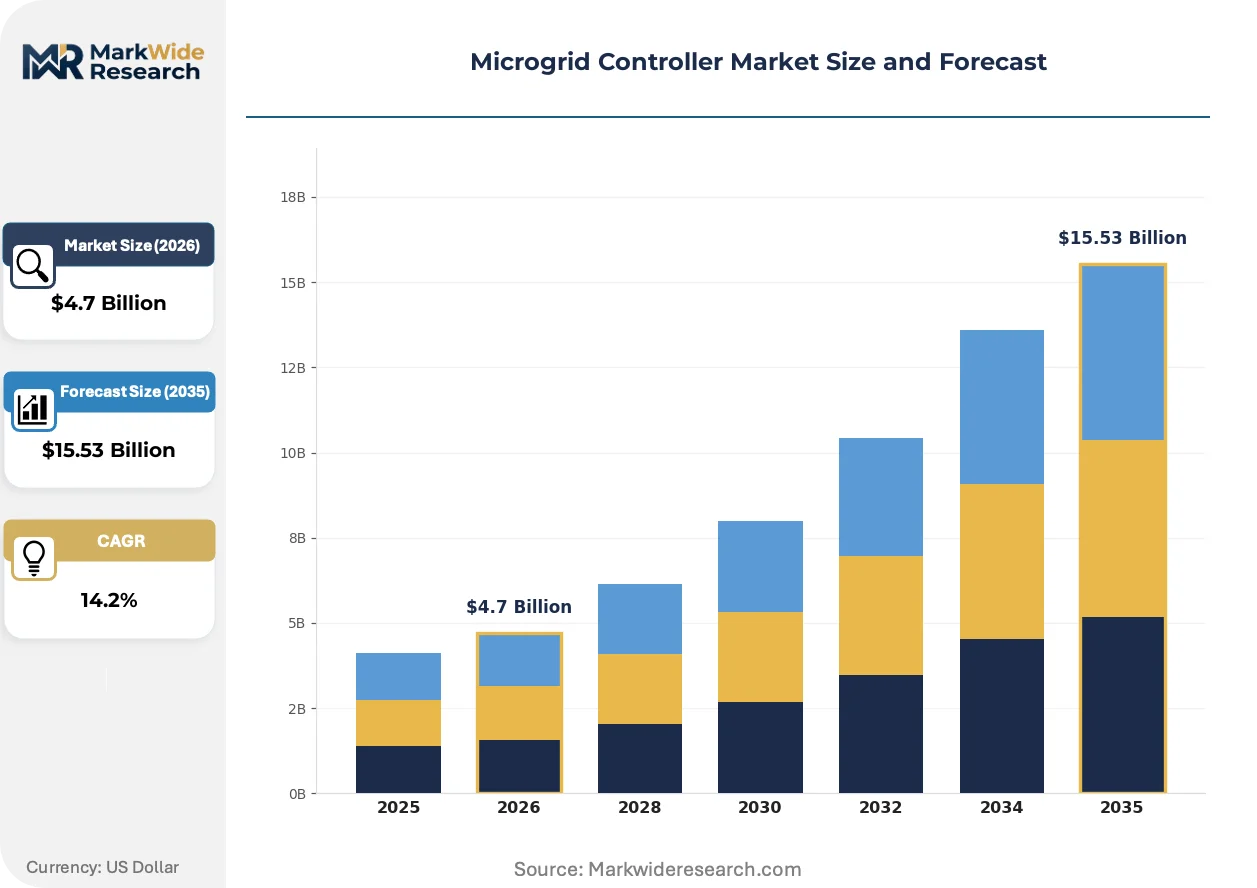
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centralized Controller, Decentralized Controller, Hybrid Controller, Software Controller Technology: Real-Time Monitoring, Adaptive Control, Distributed Generation, Energy Management System End User: Utility Providers, Commercial Facilities, Industrial Plants, Residential Complexes Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Schneider Electric, General Electric, ABB, Siemens, Eaton, Schweitzer Engineering Laboratories, Honeywell International, S&C Electric Company, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microgrid Controller Market Strategic Shifts
Controller functionality is migrating from dedicated hardware appliances toward containerized software deployments, enabling faster iteration cycles and reducing physical infrastructure footprints.
Containerized controller software is modularizing deployment architectures across the sector. Virtualized control instances running on standard industrial servers replace proprietary hardware appliances in pilot utility programs. This shift compresses capital expenditure timelines and enables over-the-air firmware updates that previously required field technician visits.
California's SB 100 mandates for 100% clean electricity by 2045 are accelerating controller procurement with renewable-optimized dispatch algorithms. Utilities must integrate high-penetration solar and battery assets while maintaining grid stability, forcing controller vendors to certify advanced inverter-based resource management. The state's investor-owned utilities now require native CAISO market interface capabilities in all new controller specifications.
Performance-based service contracts are displacing traditional equipment purchase agreements in utility procurement. Vendors assume operational risk for controller uptime and dispatch accuracy, with payments tied to measured reliability metrics. This model concentrates in Texas municipal utilities seeking to transfer technology obsolescence risk while preserving capital for generation assets.
Microgrid Controller Market Segmentation
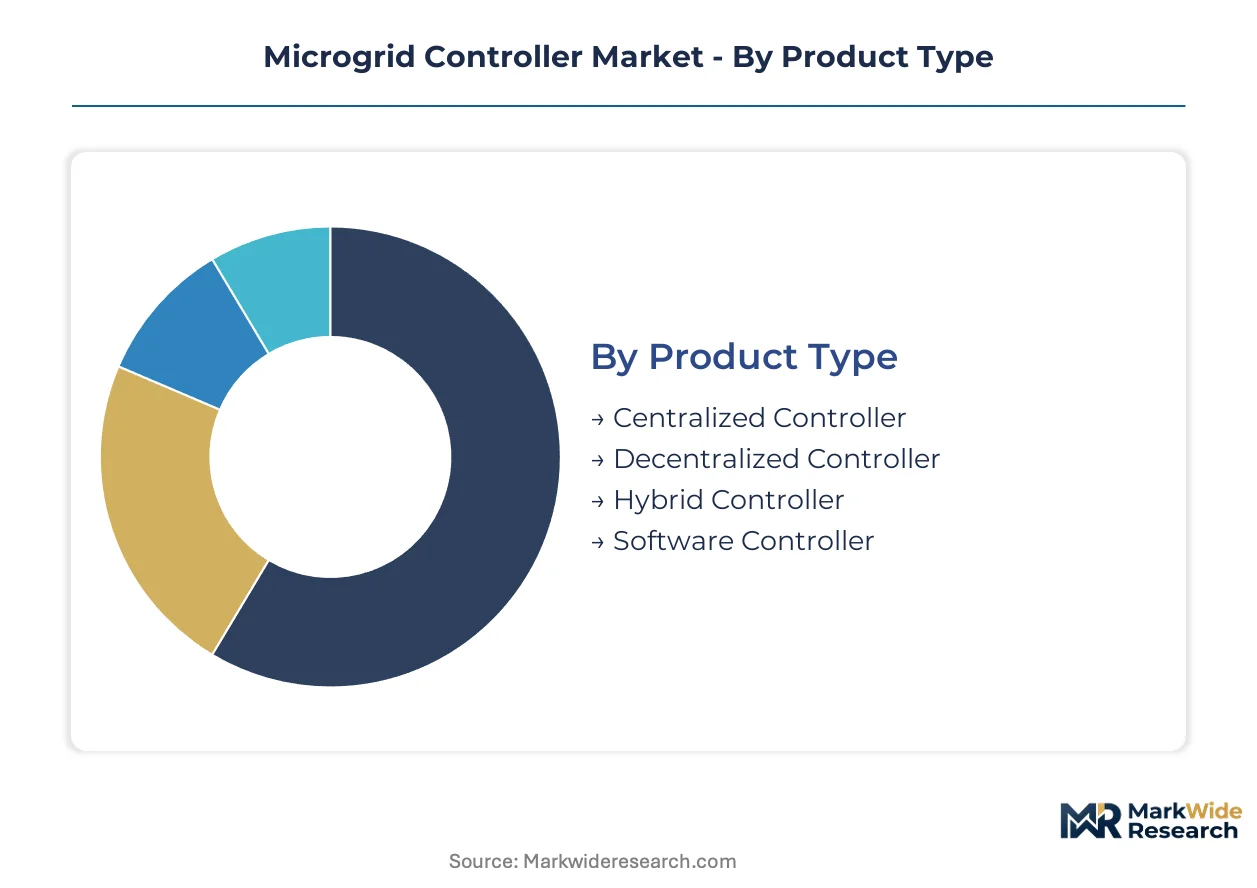
Microgrid controller procurement varies sharply by operational scale and integration complexity. Buyers prioritize different performance specifications across utility, commercial, and industrial deployments. Understanding segment boundaries clarifies where hardware-software bundling commands premium pricing versus where modular software achieves cost compression.
Product Type:
Centralized hardware dominates utility-scale procurement volumes, while software controllers capture premium pricing in retrofit installations.
- Centralized Controller:Single hardware node manages all distributed energy resources through direct I/O interfaces with sub-100 millisecond response times. Procurement concentrates with California investor-owned utilities facing FERC Order 2222 aggregation mandates and wildfire de-energization protocols.
- Software Controller:Containerized applications deploy on standard industrial servers, enabling API-driven interoperability with legacy SCADA infrastructure. Texas municipal utilities and data center operators favor this architecture for faster commissioning and over-the-air update capability.
- Decentralized Controller:Multiple autonomous nodes coordinate through peer-to-peer communication protocols without single points of failure.
- Hybrid Controller:Combines centralized oversight with distributed edge nodes for latency-sensitive load dispatch.
Mature deployment sits with Centralized Controller systems at utility scale. Newer deployment is concentrated in Software Controller architectures for commercial and industrial retrofits.
Technology:
Real-time monitoring commands the largest installed base, though adaptive control algorithms gain share in renewable-heavy microgrids.
- Real-Time Monitoring:Continuous telemetry acquisition from distributed assets enables immediate fault detection and islanding decisions. California utilities deploy this technology extensively for high-fire-threat district resilience compliance.
- Adaptive Control:Machine learning models adjust dispatch parameters based on load forecasting and renewable generation variability. ERCOT-area hospitals and water treatment plants adopting this technology reduce battery cycling costs through anticipatory optimization.
- Distributed Generation:Coordinates multiple small-scale generation assets without central dispatch authority.
- Energy Management System:Holistic platform integrating economic dispatch with market participation and demand response.
Established deployments favor Real-Time Monitoring for proven reliability. Adaptive Control is climbing the fastest as renewable penetration rises in island-capable microgrids.
End User:
Utility providers drive volume procurement, while industrial plants pay premiums for specialized integration services.
- Utility Providers:Regional transmission organizations and distribution utilities procure multi-asset platforms for FERC-mandated distributed resource aggregation. Procurement clusters in California and Texas where state resilience mandates overlap with federal grid modernization funding.
- Industrial Plants:Remote mining operations and oilfield facilities require edge-capable controllers with standalone operation certification. These buyers prioritize latency-independent control nodes operating without cloud connectivity.
- Commercial Facilities:Data centers, cold storage warehouses, and manufacturing plants seek behind-the-meter optimization.
- Residential Complexes:Multi-unit developments and master-planned communities deploy smaller-scale controllers for shared solar and battery assets.
Volume concentration remains with Utility Providers. Commercial Facilities represent the steepest expansion trajectory as retail electricity volatility drives self-managed microgrid adoption.
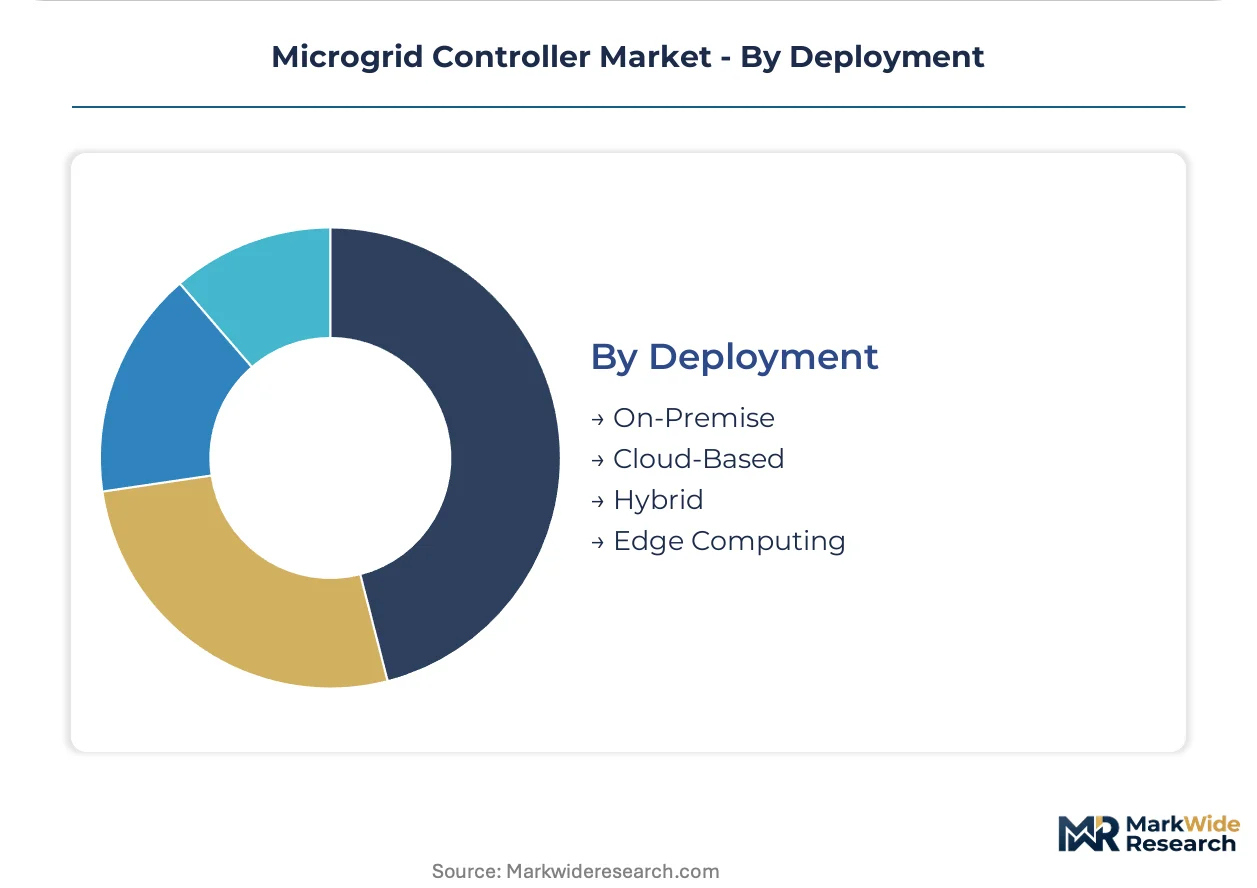
Deployment:
On-premise installations retain dominance in critical infrastructure, though cloud-based architectures penetrate commercial segments.
- On-Premise:Dedicated hardware appliances within facility boundaries satisfy NERC CIP cybersecurity mandates and eliminate external connectivity dependencies. Texas hospitals and emergency centers mandate this architecture for winter storm hardening compliance.
- Edge Computing:Localized processing nodes operate autonomously with intermittent cloud synchronization. Remote industrial sites in Alaska and offshore platforms adopt this model where satellite latency precludes real-time central coordination.
- Cloud-Based:Centralized software platforms manage multiple microgrids through secure internet connectivity.
- Hybrid:Critical control functions remain on-premise while optimization analytics run in cloud environments.
Regulated critical infrastructure favors On-Premise deployment. Edge Computing is gaining share fastest in geographically isolated industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Controller manufacturing concentrates in East Asian foundries while deployment demand clusters in North America and Europe. California and Texas utilities drive procurement volumes through state resilience mandates. Germany and Australia emerge as secondary demand centers through renewable integration policies.
United States
FERC Order 2222 aggregation requirements and wildfire de-energization protocols propel utility-scale procurement. California's SB 100 mandates for carbon-free electricity by 2045 force advanced inverter management certification. Los Angeles and San Francisco metropolitan utilities specify native CAISO market interfaces in all new controller tenders.
Germany
Grid stability challenges from renewable intermittency accelerate adaptive control algorithm adoption. The EU Green Deal and national Energiewende framework fund distributed energy resource integration pilots. Industrial clusters in Bavaria and North Rhine-Westphalia deploy edge-capable controllers for manufacturing resilience.
China
Dual carbon goals and provincial renewable quotas expand microgrid deployment in remote industrial zones. MIIT standards for smart grid interoperability shape domestic controller specifications. Manufacturing concentration in the Yangtze River Delta supplies power electronics components to global controller vendors.
Australia
Grid instability from coal plant retirements drives behind-the-meter commercial adoption. The country's national energy regulator mandates frequency control ancillary services from distributed resources. Mining operations in Western Australia and Queensland procure standalone controllers for remote site power security.
Japan
METI funding for disaster-resilient infrastructure supports hospital and emergency center microgrids. Stringent grid codes for voltage ride-through shape product certification requirements. Industrial corridors in Kanto and Kansai regions pilot AI-driven predictive dispatch systems for manufacturing facilities.
Microgrid Controller Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and integrated system tiers. The vendor base spans electrical equipment multinationals, automation technology providers, and emerging software-native entrants. Three archetypes dominate: industrial conglomerates with captive distribution networks, power systems specialists with utility relationships, and software vendors with API-first architectures. Competitive moves center on modular software bundling and performance-based service contracting that transfers operational risk to vendors.
Among diversified electrical equipment providers, Schneider Electric, Siemens, and General Electric anchor competitive positioning through platform-based offerings. Schneider Electric represents the integrated hardware-software archetype with its EcoStruxure platform. Siemens exemplifies utility-scale optimization specialization through its Spectrum Power suite. General Electric occupies a position extending predictive analytics into controller firmware for distributed generation assets. These three conglomerates sit within the premium tier where procurement concentrates among California investor-owned utilities and Texas municipal power authorities seeking comprehensive system integration.
| Leading Market Players |
|---|
| Schneider Electric |
| General Electric |
| ABB |
| Siemens |
| Eaton |
| Schweitzer Engineering Laboratories |
| Honeywell International |
| S&C Electric Company |
| Emerson Electric |
| Others |
Value Chain & Pricing Dynamics
Specialized power electronics chips sourced from East Asian foundries flow through three-tier pricing structures across premium, standard, and economy controller tiers, with NERC CIP certification costs creating margin separation between compliant utility-grade systems and commercial retrofit offerings.
Pricing Analysis
Margin tightening in utility-grade centralized controllers reflects semiconductor input cost volatility and dedicated cybersecurity engineering overhead. Pricing stratifies across premium, standard, and economy tiers based on NERC CIP certification status and CAISO market interface native capability. Cost-down pressure on software controllers accelerates as containerized deployments compress capital expenditure timelines. Commercial facility buyers exhibit highest price sensitivity, while California investor-owned utilities absorb premiums for wildfire resilience compliance.
Supply Chain Analysis
Freight cost escalation from East Asian component hubs to North American assembly facilities is reshaping regional procurement strategies for controller hardware. Manufacturing draws from Taiwan, South Korea, and China for specialized power electronics chips, with Germany and Japan supplying precision sensor components. Single-source vulnerability concentrates in advanced FPGA supply for sub-100 millisecond response architectures. Distribution runs through authorized systems integrators for utility deployments and direct OEM channels for commercial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NERC CIP cybersecurity mandates construct a cost-of-compliance moat that favors established vendors with dedicated certification teams, elevating barriers for emerging software-native entrants seeking utility procurement access.
For Market Incumbents: Deepen vertical integration into power electronics chip sourcing to insulate margin structures from East Asian foundry lead time volatility. Anchor defensive positioning through captive certification engineering teams that accelerate NERC CIP compliance timelines relative to emerging competitors. Reinforce utility relationships via performance-based service contracts that transfer operational risk and technology obsolescence exposure. For New Entrants and Emerging Players: FERC Order 2222 in the United States opens a window for API-first software controllers targeting Texas municipal utilities and behind-the-meter commercial facilities seeking faster commissioning. White-space concentration sits with data center operators and cold storage facilities prioritizing over-the-air update capability over legacy SCADA integration. Go-to-market execution should emphasize containerized deployment architectures that compress commissioning from months to weeks. For Investors and Strategic Acquirers: Utility procurement specification shifts toward native CAISO market interfaces is the leading indicator that software-defined control architectures will displace hardware-centric incumbents over the long-term viability window. Acquisition target archetype: containerized software specialists with proven API interoperability and existing FERC Order 2222 deployment references. Monitor California SB 100 mandate enforcement timelines as inflection signal for renewable-optimized dispatch algorithm demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Containerized Software Deployment | Containerized controller instances on standard industrial servers compress capital expenditure timelines and enable over-the-air firmware updates. |
| NERC CIP Certification Investment | Dedicated cybersecurity engineering teams create compliance moats that exclude smaller vendors from utility procurement channels. |
| CAISO Market Interface Integration | Native capability for California grid operator participation becomes mandatory specification for California investor-owned utility tenders. |
| Performance-Based Service Contracting | Operational risk transfer models concentrate in Texas municipal utilities seeking technology obsolescence protection. |
| Edge Computing Architecture Development | Autonomous localized control nodes address latency requirements in remote mining and oilfield operations without cloud dependency. |
Study Parameters
Document review covered FERC filings, EIA grid modernization databases, state utility commission procurement records, and IEEE standards documentation, complemented by interviews with utility planning officers, microgrid EPC contractors, controller firmware engineers, and distribution utility procurement managers. Primary fieldwork across California and Texas markets triangulated against secondary validation from NERC reliability reports and state resilience mandate implementation timelines. Bottom-up deployment tracking across utility, commercial, and industrial segments reconciled with top-down market sizing from equipment vendor revenue disclosures.
Historical deployment trajectories cross-referenced against expert panel input from grid operators and systems integrators shaped the analytical framework across the projection horizon. Segmentation modeling incorporated product type, deployment architecture, end-user category, and regional regulatory framework dimensions. CAGRs derived from unit economics analysis of controller hardware, software licensing, and service contract components, with renewable penetration curves and battery cost trajectories as energy-sector-specific forecast inputs.
The model assumes a particular technology adoption path for containerized software architectures; alternative pathways favoring persistent centralized hardware dominance would alter the outlook for vendor competitive positioning. Forecasts reflect documented assumptions regarding FERC Order 2222 implementation pace and state-level resilience funding disbursement. Stakeholders should weight assumptions against their own operating context and regional regulatory enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Europe Automated Demand Response Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Power Grid Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
South Africa Smart Grid Network Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
Smart Demand Response Market
Smart Grid
China Smart Grid Network Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Smart Water Grid Market
Smart Grid
UK Smart Grid Network Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
Smart Grid Adoption Market