
 Smart Water Grid Market | 2026-2036
Smart Water Grid Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Water Grid Market Outlook
Municipal water utilities is consolidating as the dominant end-user vertical, displacing slower-moving agricultural buyers in overall project volume. Xylem Inc. leverages its vertical integration across pump systems and analytics platforms to capture bundled infrastructure contracts. Badger Meter Inc. anchors its position through specialized ultrasonic meter technology that commands premium positioning in North American replacement cycles.
A smart water grid integrates sensor networks, communication protocols, and software platforms to monitor, control, and optimize water distribution infrastructure in real time, typically operating through pressure ranges of 0.5 to 16 bar and supporting data transmission via LPWAN or cellular protocols. Advanced Metering Infrastructure leads product-type investment as utilities prioritize bidirectional communication for demand management and leak identification. Data Analytics represents the fastest-expanding technology segment, with margin pools concentrating in predictive maintenance algorithms and hydraulic modeling software that reduce physical inspection costs.
EPA regulations on lead service line replacement and the America's Water Infrastructure Act shape municipal procurement timelines and product certification requirements, while ISO 24500 standards on water efficiency influence equipment specifications in international tenders. State-level public utility commissions in California, Texas, and New York impose additional reporting mandates that accelerate AMI adoption. Stakeholders must monitor how evolving cybersecurity frameworks for critical infrastructure reshape vendor qualification criteria and system architecture decisions.
Market Dynamics
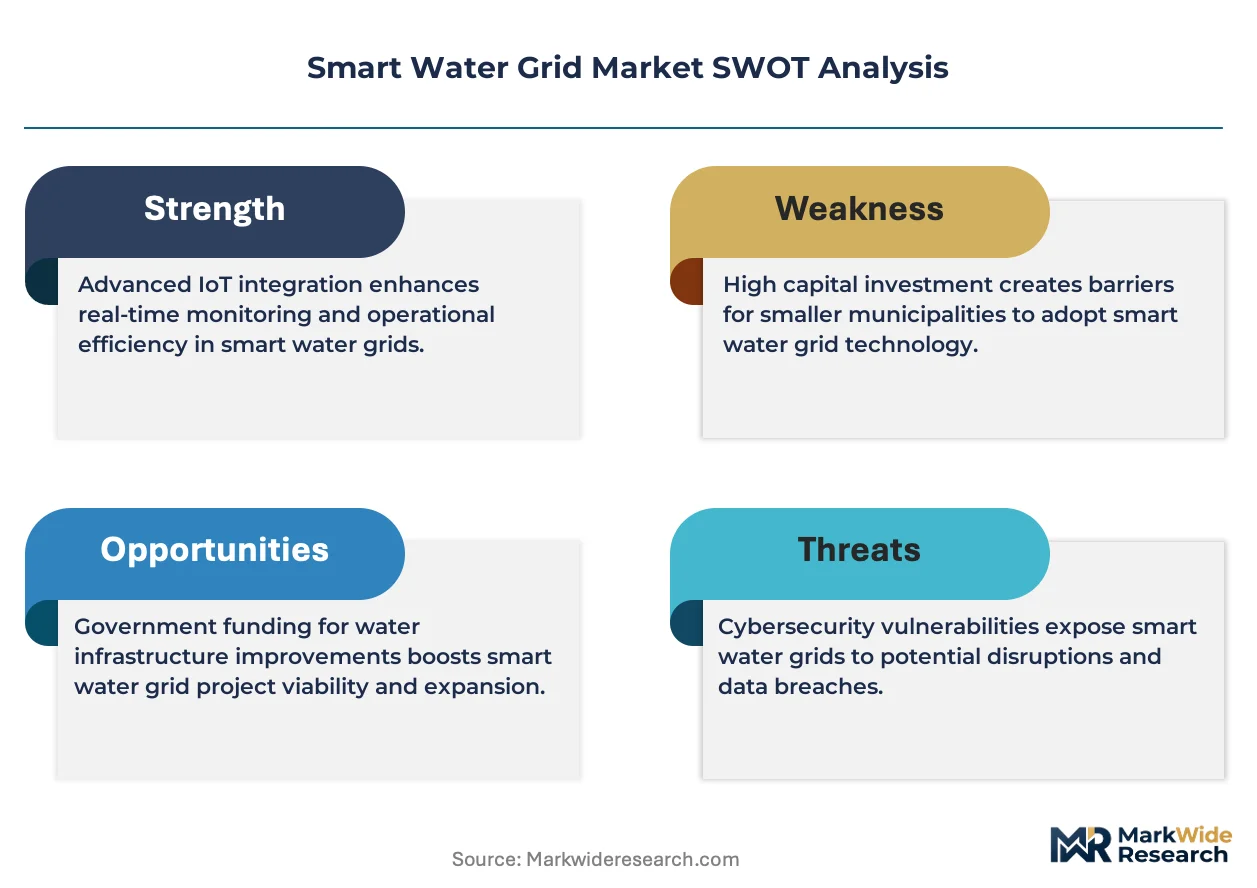
The EPA's Lead and Copper Rule Revision is compressing municipal procurement timelines while AMI technology maturation enables utilities to bundle leak detection with billing infrastructure, creating simultaneous pressure and capability for network modernization.
Growth Catalysts
- EPA Lead Service Line Mandates:Federal replacement deadlines force municipal utilities to prioritize sensor-integrated infrastructure during pipe renewal cycles, embedding smart grid components into mandatory capital programs.
- LPWAN Protocol Maturation:Low-power wide-area networks reduce communication infrastructure costs for rural and suburban utilities, expanding addressable market beyond dense urban deployments.
- Non-Revenue Water Loss Economics:Utilities facing 20-30% physical and commercial losses deploy pressure sensors and acoustic leak detectors to recover operational margins through reduced waste.
Market Restraints
- Semiconductor Supply Concentration:Sensor and communication module production clusters in East Asian foundries expose AMI vendors to input volatility and extended lead times.
- Cybersecurity Certification Friction:State-level public utility commissions impose divergent critical infrastructure standards, fragmenting vendor qualification requirements across California, Texas, and New York.
- Legacy SCADA Integration Costs:Proprietary protocols in existing control systems demand expensive middleware development for seamless smart grid overlay deployment.
Strategic Opportunities
- India Smart Cities Mission:Urban water distribution modernization under central government funding creates greenfield deployment potential for integrated sensor-analytics platforms in tier-1 and tier-2 municipalities.
- Digital Twin Convergence:Hydraulic modeling software combined with real-time sensor feeds enables predictive maintenance contracts that shift vendor revenue from hardware to recurring service streams.
- Outcome-Based Performance Contracts:Municipal procurement teams in water-stressed regions increasingly specify guaranteed leakage reduction targets rather than equipment specifications, favoring integrated solution providers.
Industry Challenges
- Cyber-Physical Systems Engineering Talent:Utilities struggle to recruit professionals capable of bridging operational technology security with IT network management for critical infrastructure protection.
- Interoperability Standardization Delays:Competing communication protocols between AMI vendors and SCADA manufacturers extend pilot-to-scale timelines as utilities await IEEE and ISO harmonization.
- Rate Case Approval Cycles:Public utility commission hearings for smart infrastructure cost recovery lag deployment schedules by 18-36 months in regulated markets, straining utility cash flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Water Grid Market |
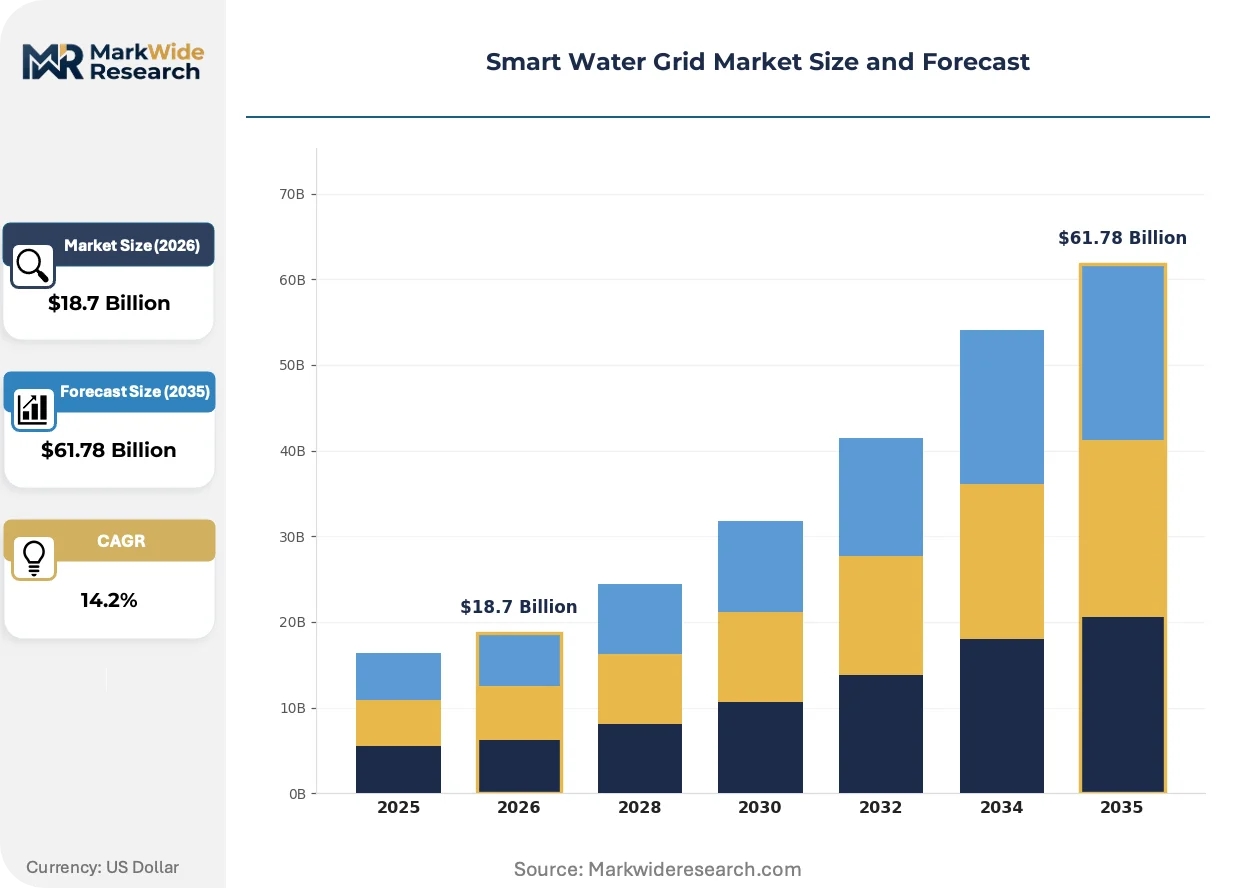
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, Advanced Metering Infrastructure, SCADA Systems, Data Analytics Product Type: Smart Meters, Pressure Management Solutions, Leak Detection Equipment, Water Quality Monitoring Application: Urban Water Supply, Industrial Water Use, Irrigation Management, Wastewater Treatment End User: Municipalities, Water Utilities, Agriculture, Commercial Entities |
| Companies Covered | Itron Inc., Xylem Inc., Badger Meter Inc., Landis+Gyr, Neptune Technology Group Inc., Kamstrup A/S, Diehl Metering GmbH, Honeywell International Inc., Arad Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Water Grid Market Strategic Shifts
Sensor fusion architectures and edge computing are collapsing the latency between physical network events and operational decisions, compressing response times from hours to seconds in leak detection and pressure management workflows.
Edge-native analytics platforms are unifying pressure transducer, acoustic, and flow data processing at the network node level. Municipal utilities in water-stressed regions deploy these systems to reduce cloud dependency and enable sub-minute leak localization. This unifying architecture compresses the competitive advantage of standalone sensor vendors against integrated platform providers.
The EU's revised Drinking Water Directive mandates real-time quality monitoring and risk-based management plans for distribution networks serving over 1,000 people. Equipment suppliers must now certify sensor accuracy under EN ISO 15839 while utilities restructure procurement to favor combined quality-pressure-flow monitoring suites. German and Dutch water authorities lead implementation, with Scandinavian utilities following in the 2025-2027 window.
Performance-based procurement is displacing capital equipment purchasing in North American municipal markets. Water utilities in California and Texas now contract for guaranteed outcomes—leakage reduction percentages, pressure compliance rates, energy savings—rather than specifying meter counts or sensor densities. This restructures vendor relationships toward multi-year service agreements with penalty clauses and renewal incentives.
Smart Water Grid Market Segmentation
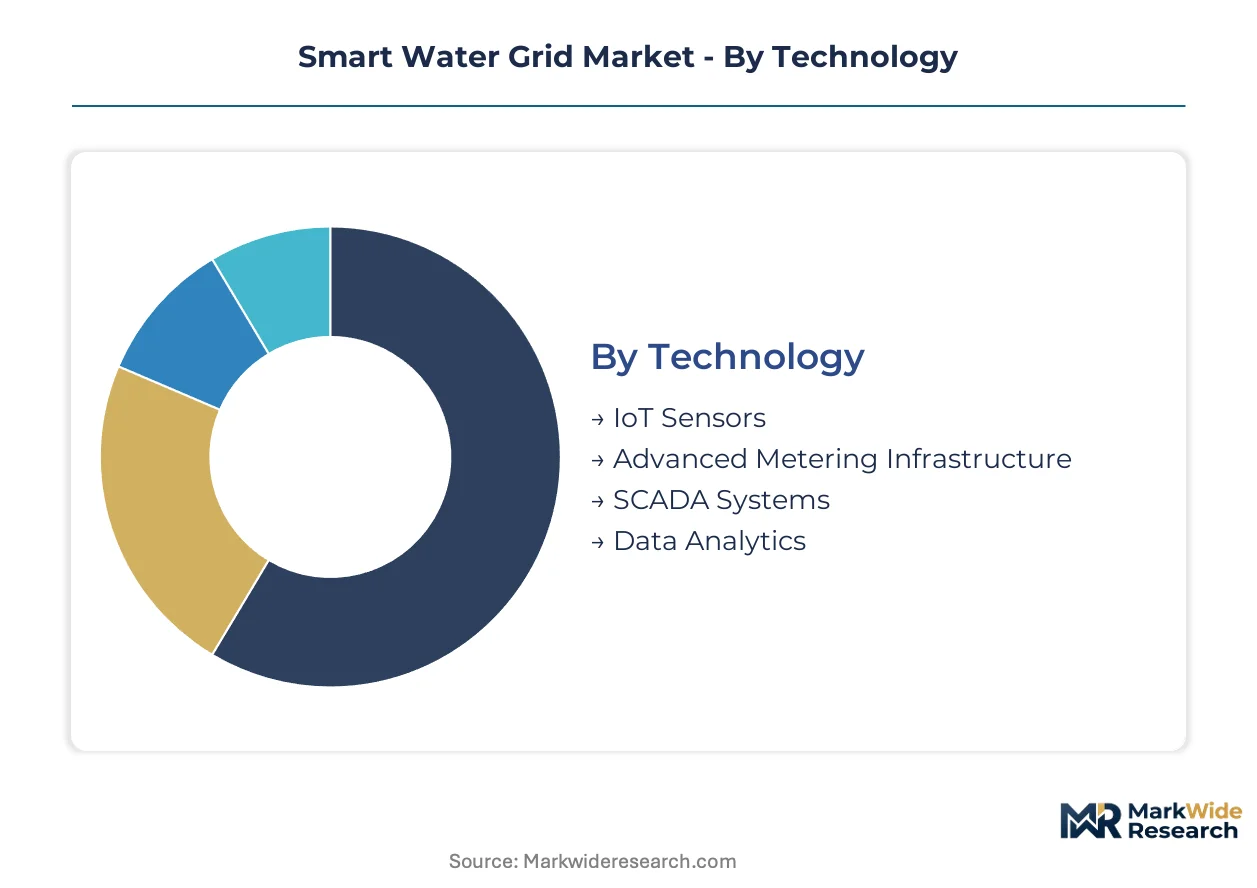
Smart water grid procurement varies sharply by technology maturity and infrastructure replacement cycles. Utility capital planners weigh upfront hardware costs against projected operational savings from reduced non-revenue water losses. Segment boundaries increasingly blur as vendors bundle sensors, communication modules, and analytics into unified platforms.
Technology:
Capital intensity concentrates in communication backbone deployment, with wide variation between legacy retrofit and greenfield sensor networks.
- IoT Sensors:Distributed pressure, acoustic, and flow sensors operate at 0.5-16 bar ranges with LPWAN or cellular backhaul. Municipal utilities in the United States embed these into lead service line replacement programs mandated by EPA deadlines.
- Advanced Metering Infrastructure:Bidirectional communication networks integrate billing systems with demand management and leak identification. California and Texas public utility commissions accelerate adoption through reporting mandates that compress procurement timelines.
- SCADA Systems:Proprietary protocols dominate legacy installations, demanding expensive middleware for smart grid overlay.
- Data Analytics:Predictive maintenance algorithms and hydraulic modeling software concentrate margin pools for vendors.
Advanced Metering Infrastructure absorbs the bulk of installed capacity; Data Analytics is expanding most quickly.
Product Type:
Application context determines specification tiers, with urban distribution networks demanding higher accuracy and cybersecurity certification than agricultural deployments.
- Smart Meters:Ultrasonic and electromagnetic variants achieve precision for billing integrity and leak detection. North American replacement cycles favor premium positioning for meters meeting revised EPA certification requirements.
- Pressure Management Solutions:Automated valve controllers and pump optimization systems reduce energy consumption and pipe burst frequency. Water-stressed regions specify guaranteed pressure compliance rates in procurement contracts.
- Leak Detection Equipment:Acoustic correlators and noise loggers localize losses in aging distribution networks.
- Water Quality Monitoring:Real-time contaminant sensors face EN ISO 15839 certification requirements under EU Drinking Water Directive revisions.
Smart Meters dominate current procurement volumes; Pressure Management Solutions are climbing the fastest as utilities prioritize energy recovery.
Application:
Customer concentration and regulatory exposure create divergent margin profiles across deployment contexts.
- Urban Water Supply:Dense meter populations and federal infrastructure funding accelerate digital transformation. India's Smart Cities Mission funds integrated sensor-analytics platforms in tier-1 and tier-2 municipalities.
- Industrial Water Use:Process-critical quality monitoring commands premium sensor specifications with rapid replacement cycles.
- Irrigation Management:Lower sensor density and price sensitivity characterize agricultural demand.
- Wastewater Treatment:Energy recovery and effluent compliance drive automation investment.
Urban Water Supply commands the largest addressable market; Industrial Water Use offers the steepest expansion trajectory for high-specification monitoring.
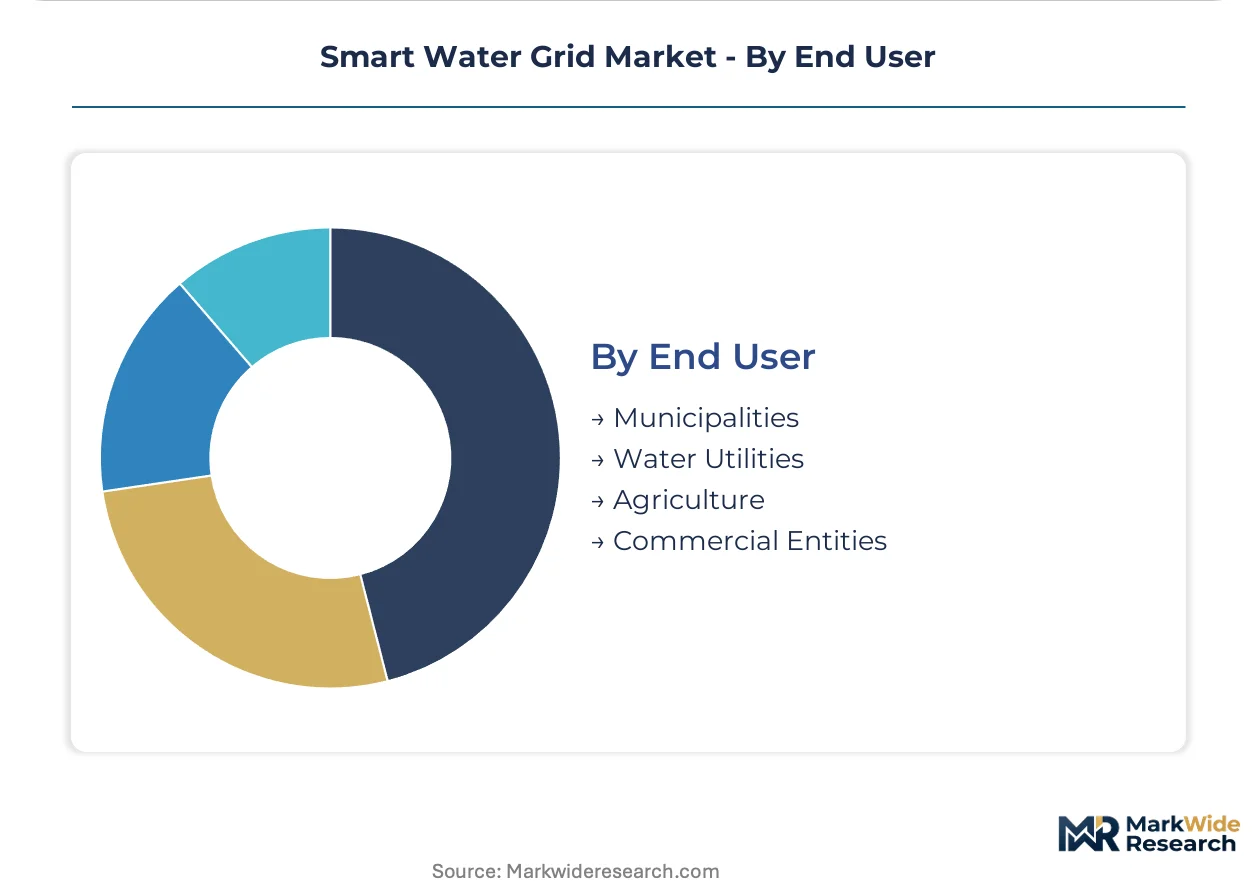
End User:
Budget authority and procurement sophistication fragment the customer base across regulated and unregulated water service models.
- Municipalities:Rate case approval cycles lag deployment schedules by 18-36 months, straining cash flows. Federal lead service line mandates compress timelines for integrated infrastructure renewal.
- Water Utilities:Investor-owned and publicly owned entities balance regulatory compliance with shareholder or ratepayer returns.
- Agriculture:Irrigation districts prioritize cost minimization over predictive analytics capabilities.
- Commercial Entities:Corporate water risk management drives private network monitoring for manufacturing and data center cooling.
Municipalities account for the dominant share of project volume; Commercial Entities are gaining share fastest as ESG reporting requirements expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for water technology in Singapore and Shenzhen concentrate sensor manufacturing and analytics R&D, creating regional hubs that export AMI components to municipal utilities worldwide.
United States
Federal infrastructure funding and EPA lead service line mandates drive replacement cycles across aging distribution networks. The America's Water Infrastructure Act compresses procurement timelines for integrated sensor systems. California's public utility commission accelerates AMI adoption through reporting mandates in Los Angeles and San Diego metro areas.
Germany
EN ISO 15839 certification requirements under the EU Drinking Water Directive reshape equipment specifications for real-time quality monitoring. German water authorities lead implementation of combined pressure-flow-quality monitoring suites. The Rhine-Ruhr industrial corridor deploys predictive maintenance contracts for leakage reduction in Düsseldorf and Cologne distribution networks.
India
The Smart Cities Mission funds greenfield sensor-analytics platforms in tier-1 and tier-2 municipalities facing acute water stress. Central government urban renewal programs prioritize digital distribution infrastructure in Bangalore and Hyderabad. Maharashtra's municipal corporations bundle leak detection with billing system modernization in Mumbai and Pune metro regions.
China
Dual carbon goals and urban water efficiency targets accelerate smart grid deployment in megacity distribution systems. MIIT standards for IoT communication protocols harmonize sensor networks across provincial utilities. The Yangtze River Delta concentrates manufacturing of pressure transducers and acoustic leak detectors for domestic and export markets.
Netherlands
Delta water management expertise translates into advanced pressure management and flood-resilient distribution design. Dutch water authorities pioneer digital twin integration for hydraulic modeling in Randstad urban clusters. Rotterdam and Amsterdam utilities specify guaranteed energy recovery outcomes in multi-year service contracts rather than equipment purchases.
Smart Water Grid Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing bundled infrastructure contracts while component vendors serve retrofit markets. The vendor base organizes into three tiers: multinational conglomerates with captive water divisions, pure-play metering specialists with deep AMI expertise, and regional system integrators serving municipal procurement. Consolidation pressure concentrates among mid-scale analytics providers as utilities favor end-to-end solution accountability. M&A activity targets predictive maintenance software capabilities, while strategic partnerships between sensor vendors and telecommunications firms accelerate LPWAN network deployment.
Within the pure-play metering tier, Badger Meter Inc. and Itron Inc. exemplify specialists that have deepened software and service capabilities to escape hardware commoditization. Xylem Inc. occupies a position among diversified industrials that leverage pump and treatment system installed bases to cross-sell grid analytics. Kamstrup A/S and Diehl Metering GmbH represent European-based fabricators that compete on precision certification and EU regulatory alignment.
| Leading Market Players |
|---|
| Itron Inc. |
| Xylem Inc. |
| Badger Meter Inc. |
| Landis+Gyr |
| Neptune Technology Group Inc. |
| Kamstrup A/S |
| Diehl Metering GmbH |
| Honeywell International Inc. |
| Arad Group Ltd. |
| Others |
Value Chain & Pricing Dynamics
Semiconductor wafer costs cascade through sensor module fabrication, concentrating pricing power among East Asian foundries that supply pressure transducers and acoustic detectors to AMI vendors bundling hardware with analytics subscriptions.
Pricing Analysis
Short lead-time premiums separate urgent replacement contracts from standard procurement cycles in municipal utility markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 24500 certification grade and after-sales service bundling. Price compression in the economy tier intensifies as Chinese sensor manufacturers expand LPWAN module exports. Agricultural irrigation districts exhibit highest price sensitivity, while California municipal utilities absorbing federal infrastructure funding show lowest.
Supply Chain Analysis
Dual-sourcing mandates from European water authorities require AMI vendors to qualify second-source suppliers for pressure sensor ASICs and cellular communication modules. Manufacturing concentrates in Taiwan, South Korea, and China for semiconductor fabrication, with Germany and the Netherlands hosting final assembly of certified metering systems. Raw material dependencies span silicon wafers, rare-earth magnets for valve actuators, and lithium for battery-backed edge devices. Single-source vulnerability in advanced node semiconductor production exposes vendors to foundry allocation constraints. Distribution runs through authorized system integrators serving municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity constraints prop pricing premiums for certified sensor modules, constraining volume expansion for undifferentiated hardware vendors while rewarding integrated platform providers with captive supply agreements.
For Market Incumbents: To counter margin erosion from Chinese sensor exports, deepen backward integration into edge computing chip design and secure multi-year foundry allocation agreements in Taiwan. Prioritize EN ISO 15839 certification investment to maintain premium positioning in EU procurement tenders. For New Entrants and Emerging Players: Predictive maintenance algorithms offering guaranteed leakage reduction contracts represent the most penetrable wedge for software-native entrants. Target India's Smart Cities Mission with outcome-based performance contracts rather than equipment sales. Pursue white-label partnerships with established AMI hardware vendors to bypass certification timelines. For Investors and Strategic Acquirers: Accelerated municipal procurement timelines under EPA lead service line mandates are the leading indicator that consolidation value is concentrating in predictive analytics capabilities rather than hardware manufacturing. Long-term viability favors vendors with recurring service revenue streams. Acquisition focus should center on hydraulic modeling software specialists with existing utility deployment records. Monitor state public utility commission rate case approval velocities as the critical inflection signal for utility cash flow health.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Analytics Platform Launch | Reduces cloud dependency for California utilities facing cybersecurity mandates. |
| LPWAN Network Infrastructure Partnership | Expands addressable market to rural Texas municipalities with limited cellular coverage. |
| Backward Integration into Sensor ASIC Design | Captures margin pools currently flowing to Taiwanese foundry customers. |
| Digital Twin Integration Agreement | Shifts Dutch water authority contracts from hardware to recurring service revenue. |
| Outcome-Based Performance Contracting | Aligns vendor incentives with Maharashtra municipal leakage reduction targets. |
Study Parameters
Document review covered EPA regulatory filings, ISO standards documentation, and municipal procurement databases, complemented by interviews with utility planning officers, AMI vendor product managers, and public utility commission regulatory staff. Secondary sources included FERC infrastructure investment reports, EIA energy consumption data for water utilities, and customs records for sensor module trade flows. Bottom-up utility deployment estimates triangulated against top-down market sizing from infrastructure spending projections.
Market value and volume outputs derived from segmented modeling across technology type, product category, application context, and end-user budget authority. Segmentation dimensions included IoT sensor density per kilometer of distribution network, AMI deployment scale by utility customer count, and analytics software licensing versus subscription revenue mix. CAGRs emerged from regression analysis of historical procurement cycles against regulatory deadline acceleration. Industry-specific inputs incorporated EPA lead service line replacement timelines and state-level rate case approval lag patterns.
Several conditions sit outside the modeled scope, including cyberattack disruptions to utility operations, abrupt shifts in federal infrastructure funding appropriations, and trade policy changes affecting semiconductor import flows. Deviation in municipal bond market conditions or state public utility commission staffing levels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
Microgrid Controller Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
India Smart Grid Network Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
Microgrid Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Smart Grid Market
Smart Grid
China Smart Power Distribution Systems Market