
 Smart Meters Market | 2026-2036
Smart Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Meters Market Analysis
China is rewriting competitive dynamics in smart meter manufacturing through massive domestic deployment programs and export-oriented production scale. Itron Inc. leverages its end-to-end AMI platform to anchor utility relationships across multiple continents. Landis+Gyr Group AG sustains technology leadership through deep R&D investment in grid-edge intelligence and communications modules. Kamstrup A/S specializes in ultrasonic metering technology that differentiates its water and thermal energy product lines.
Smart meters are digital measurement devices that record energy, gas, or water consumption at intervals of one hour or less and communicate that data remotely to utilities for monitoring and billing. These devices incorporate metrology sensors, application-specific integrated circuits, and RF or power-line communication modules to enable real-time data transmission and remote disconnect capability. Electric meters dominate installed base volume, while AMI technology captures the fastest growth trajectory as utilities replace first-generation AMR systems with two-way communications infrastructure. IoT-based deployments are expanding fastest among residential users, though industrial facilities represent the highest-margin segment due to complex integration requirements and demand-response participation.
Regulatory frameworks including the EU Green Deal, FERC Order 2222 in the United States, and India's CEA smart grid roadmap are mandating interval metering and grid interoperability standards that directly shape procurement specifications. REACH and RoHS compliance in Europe restricts hazardous substances in meter electronics, while CE marking requirements govern electromagnetic compatibility and safety certification. Stakeholders must monitor how cybersecurity standards evolve alongside connectivity mandates, as NIST frameworks and national critical infrastructure protections increasingly dictate which communication architectures qualify for utility deployment.
Market Dynamics
AMI infrastructure rollouts are compressing meter replacement cycles from fifteen years to seven-to-ten years as utilities prioritize two-way communications and grid-edge intelligence over basic metrology upgrades.
Growth Catalysts
- FERC Order 2222:This US regulation mandates grid interoperability standards that accelerate AMI procurement by requiring distributed energy resource aggregation capabilities in new meter deployments.
- EU Green Deal carbon tracking:European utilities face binding emissions disclosure requirements that interval metering infrastructure satisfies through granular consumption data collection and verification protocols.
- Ultrasonic metrology:Solid-state flow measurement eliminates mechanical wear in water and thermal applications, extending operational lifespan and reducing maintenance truck rolls for utilities.
Market Restraints
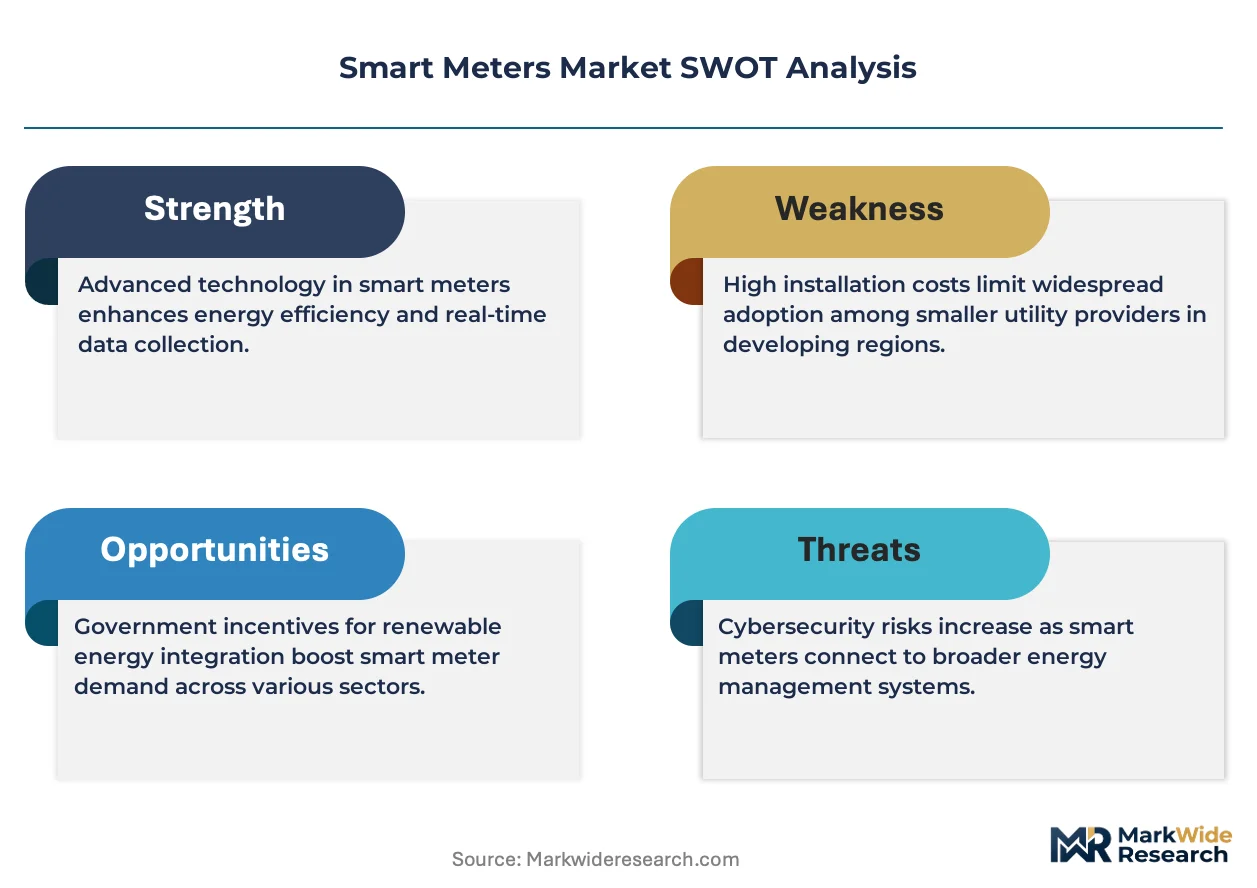
- Semiconductor supply concentration:ASIC and RF module production clusters in Taiwan and South Korea create vulnerability to geopolitical disruption and foundry allocation constraints.
- Copper and rare earth volatility:Coil assemblies and magnet materials face price swings that compress hardware margins for meter manufacturers locked into multi-year utility contracts.
- Legacy AMR stranded assets:First-generation drive-by radio systems in North American utilities resist full replacement due to capital recovery timelines and depreciation schedules.
Strategic Opportunities
- India CEA smart grid roadmap:Central Electricity Authority mandates create a 250-million-unit addressable market as state distribution companies modernize rural and urban metering infrastructure simultaneously.
- Edge AI convergence:On-device machine learning for anomaly detection and load forecasting merges with meter hardware, creating new software revenue streams beyond hardware sales.
- Direct-to-consumer channel emergence:Third-party energy retailers and prosumers bypass traditional utility procurement through marketplace platforms for behind-the-meter intelligence.
Industry Challenges
- Cybersecurity certification bottlenecks:NIST framework compliance and national critical infrastructure protections extend qualification timelines for new communication architectures.
- Protocol fragmentation:Competing RF mesh, cellular, and power-line carrier standards force utilities into premature technology bets with uncertain interoperability pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Meters Market |
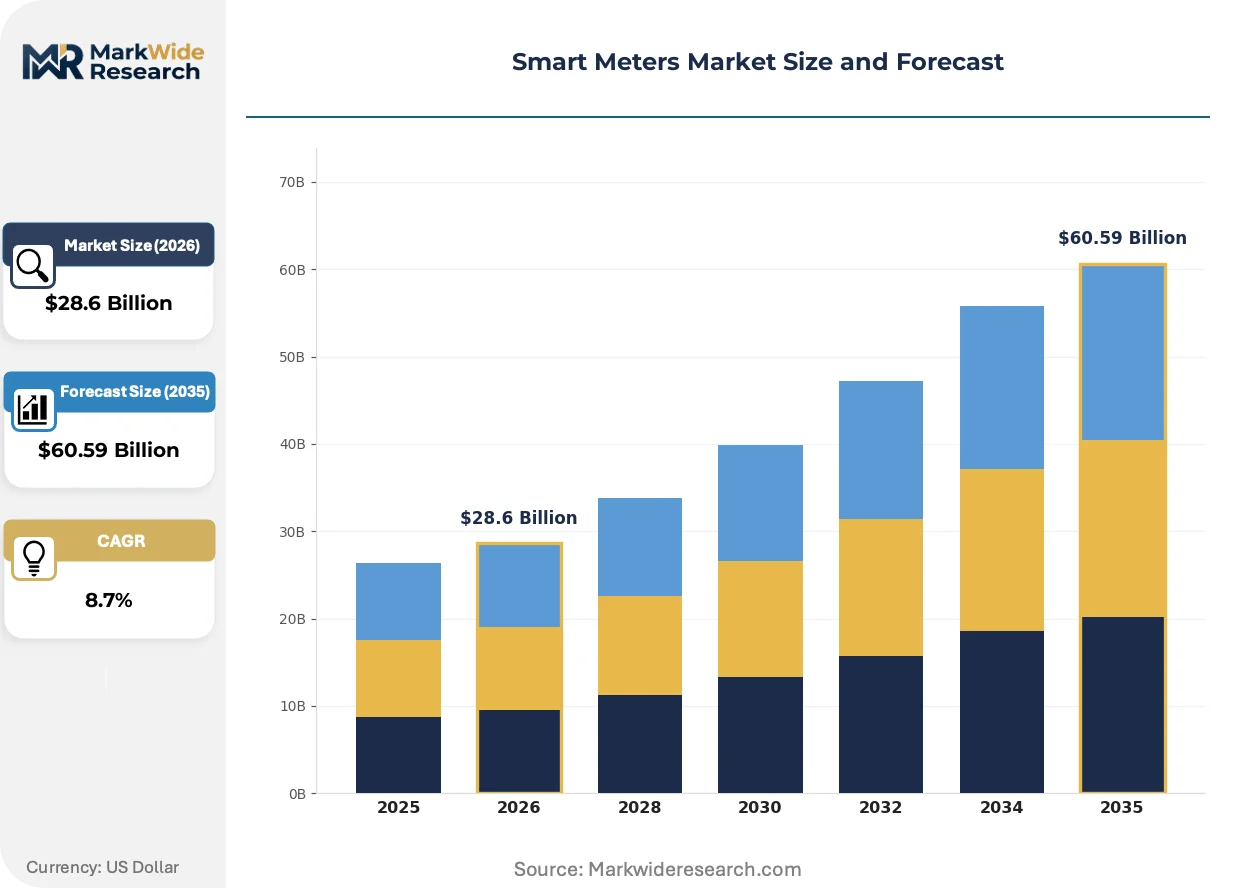
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Meters, Gas Meters, Water Meters, Multi-Utility Meters Technology: AMR, AMI, IoT-based, Hybrid Systems End User: Utilities, Commercial Establishments, Residential Users, Industrial Facilities Deployment: On-premises, Cloud-based, Remote, Hybrid |
| Companies Covered | Itron Inc., Landis+Gyr Group AG, Siemens AG, Schneider Electric SE, Honeywell International Inc., Sagemcom SAS, Osaki Electric Co., Kamstrup A/S, EDMI Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Meters Market Emerging Trajectories
Grid-edge intelligence is migrating from centralized control rooms into distributed meter endpoints, redefining where computation happens and who captures value from data monetization.
Edge computing architectures are digitizing demand-response orchestration by embedding processing power directly into residential meters. Large investor-owned utilities in California and Texas are deploying these capabilities at scale to manage rooftop solar intermittency without backhauling raw data to control centers. This compression of decision latency is digitizing how grid operators balance load, replacing fifteen-minute settlement intervals with real-time price signals.
REACH substance restrictions are forcing redesigns of printed circuit board assemblies and solder compositions across European supply chains. Meter manufacturers must reformulate electronics to eliminate restricted phthalates and cadmium while maintaining electromagnetic compatibility under CE marking requirements. German and French utilities now specify full material disclosure in procurement tenders, shifting supplier qualification from performance-only to chemistry-audited verification.
Subscription-based AMI-as-a-service models are displacing capital purchase agreements for municipal and cooperative utilities with constrained balance sheets. Third-party financiers own meter assets and charge per-endpoint monthly fees, transferring technology obsolescence risk from ratepayers to private capital. This structure is expanding fastest among rural electric cooperatives in the US Midwest where federal lending authority supports off-balance-sheet infrastructure deployment.
Smart Meters Market Segmentation
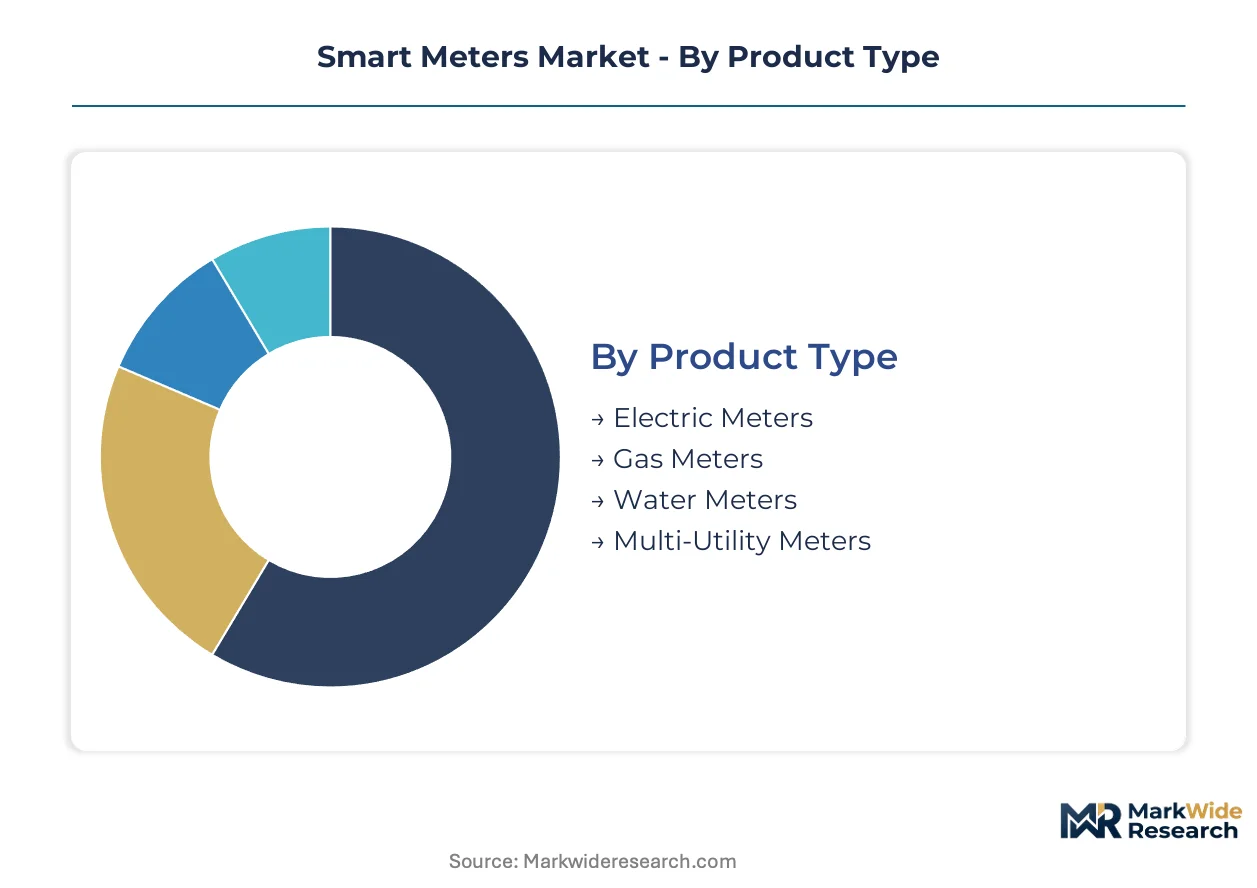
Smart meter segmentation reveals how deployment economics and grid modernization priorities reshape procurement patterns across utility infrastructure. Technology choices and end-user requirements fragment addressable markets into distinct value pools with diverging margin profiles and replacement cycles.
Product Type:
Use-case spectrum spans single-commodity measurement to integrated multi-utility platforms serving diverse infrastructure modernization timelines.
- Electric Meters:Digital endpoints with metrology sensors and RF communication modules record consumption at sub-hourly intervals for time-of-use billing. Demand concentrates in United States and Germany where state-level renewable portfolio standards and grid modernization programs mandate AMI procurement for distributed solar integration. FERC Order 2222 interoperability requirements accelerate replacement of electromechanical units with two-way capable endpoints.
- Water Meters:Ultrasonic and electromagnetic flow sensors eliminate mechanical wear while enabling leak detection and pressure monitoring. Adoption accelerates in California and Australia where drought resilience mandates drive precision metering for conservation pricing. Solid-state designs extend operational lifespan beyond fifteen years, reducing maintenance truck rolls for municipal utilities.
- Gas Meters:Diaphragm and turbine-based measurement devices with temperature compensation and remote shutoff capability serve residential and commercial heating loads. European utilities prioritize these for carbon tracking under EU Green Deal disclosure requirements.
- Multi-Utility Meters:Consolidated endpoints measuring electricity, water, and thermal energy through unified communication modules. Emerging adoption favors this segment as campus and district energy operators seek reduced installation complexity.
Established volume favors Electric Meters; emerging adoption favors Multi-Utility Meters.
Technology:
Cost tier stratification separates legacy one-way systems from premium two-way infrastructure with edge intelligence capabilities.
- AMI:Advanced Metering Infrastructure delivers two-way communications, remote disconnect, and distributed energy resource aggregation. Deployment accelerates in Texas and California where investor-owned utilities manage rooftop solar intermittency through real-time price signals. Grid-edge intelligence migration compresses replacement cycles from fifteen years to seven-to-ten years.
- IoT-based:Cellular and LPWAN-connected endpoints leverage cloud analytics for predictive maintenance and demand-response orchestration. Residential prosumers in Germany and Netherlands adopt these through third-party energy retail platforms bypassing traditional utility procurement.
- AMR:Automated Meter Reading systems using drive-by radio or walk-by data collection persist as stranded assets in North American utilities with unresolved capital recovery timelines.
- Hybrid Systems:Dual-communication architectures combining power-line carrier with RF mesh for redundancy in challenging topology environments. Rural electric cooperatives in United States Midwest favor these for AMI-as-a-service deployments.
Hardware margins concentrate in AMI; software revenue potential climbs fastest in IoT-based systems.
End User:
Customer type determines integration complexity and demand-response participation depth across utility and behind-the-meter applications.
- Utilities:Investor-owned and municipal operators procure at scale for grid balancing, outage management, and interval billing. State distribution companies in India address 250-million-unit modernization mandates under CEA smart grid roadmap.
- Industrial Facilities:Manufacturing and data center operations with complex load profiles and demand-response participation requirements represent highest-margin integration opportunities. Real-time settlement intervals replace fifteen-minute schedules for price-responsive load curtailment.
- Residential Users:Single-family and multi-tenant dwellings drive volume through utility-led AMI rollouts and consumer-facing energy management apps. Subscription-based AMI-as-a-service models expand fastest among rural electric cooperatives with constrained balance sheets.
- Commercial Establishments:Retail, hospitality, and office buildings with sub-metering requirements for tenant billing and sustainability reporting. REACH substance restrictions force chemistry-audited verification in German and French procurement tenders.
Procurement scale favors Utilities; margin capture favors Industrial Facilities.
Deployment:
Maturity gradient separates on-premises legacy systems from cloud-native architectures with differential cybersecurity qualification timelines.
- Cloud-based:Centralized data aggregation and analytics platforms reduce utility IT infrastructure burden while enabling third-party application development. NIST framework compliance and national critical infrastructure protections extend qualification timelines for new communication architectures.
- Hybrid:Edge processing for time-sensitive operations combined with cloud analytics for strategic planning. Large investor-owned utilities deploy these at scale to manage settlement latency without raw data backhaul.
- On-premises:Utility-owned data centers with dedicated security perimeters satisfy conservative risk profiles in critical infrastructure protection regimes.
- Remote:Fully managed service delivery with vendor-operated infrastructure and per-endpoint subscription pricing. Municipal and cooperative utilities with federal lending authority support favor this structure for off-balance-sheet deployment.
Security certification favors On-premises; operational flexibility favors Cloud-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart meter manufacturing concentrates in China, Germany, and the United States, where component ecosystems and utility procurement scale create distinct competitive advantages. National regulatory mandates reshape deployment timelines across these production centers.
United States
State-level renewable portfolio standards in California and Texas accelerate AMI procurement for distributed solar integration. FERC Order 2222 mandates grid interoperability standards that require two-way communication capabilities in new meter deployments. Investor-owned utilities in the ERCOT and CAISO markets deploy edge-intelligent endpoints at scale to manage rooftop intermittency through real-time price signals.
China
Massive domestic deployment programs and export-oriented production scale rewrite competitive dynamics in meter manufacturing. The country's dual carbon goals drive state grid corporations to replace electromechanical meters with digital endpoints supporting time-of-use pricing. Manufacturing clusters in Jiangsu and Zhejiang provinces supply both domestic utilities and export markets across Southeast Asia and Africa.
Germany
EU Green Deal carbon tracking requirements bind utilities to emissions disclosure protocols that interval metering infrastructure satisfies. REACH substance restrictions force redesigns of printed circuit board assemblies and solder compositions across European supply chains. Industrial metering demand concentrates in Baden-Württemberg and Bavaria, where manufacturing facilities require complex sub-metering for tenant billing and sustainability reporting.
India
Central Electricity Authority mandates create a 250-million-unit addressable market as state distribution companies modernize rural and urban metering infrastructure simultaneously. The national smart grid roadmap requires interval metering and grid interoperability standards that directly shape procurement specifications. Deployment acceleration concentrates in Maharashtra and Gujarat, where state utilities pursue parallel urban AMI and rural electrification metering programs.
Japan
METI grid modernization directives push utilities toward AMI replacement of first-generation automated meter reading systems. The country's semiconductor supply chain advantages support domestic production of application-specific integrated circuits for meter electronics. Tokyo Electric Power and Kansai Electric deploy advanced endpoints in the Kanto and Kansai regions to manage demand-response participation from industrial facilities.
Smart Meters Market Vendor Landscape
End-to-end platform providers and specialized component manufacturers split the market between integrated solution sales and technology licensing arrangements. The vendor base organizes around three strategic archetypes: full-stack AMI platform operators, ultrasonic metrology specialists, and communications module suppliers. Consolidation pressures favor scale-driven players with utility relationship depth across multiple continents. Competitive moves center on portfolio diversification into grid-edge intelligence software and strategic partnerships with semiconductor foundries.
Within the full-stack platform tier, Itron Inc. and Landis+Gyr Group AG occupy positions as archetypal integrated solution providers spanning hardware and software layers. Kamstrup A/S exemplifies the specialized technology path, with its Danish corporate structure signaling concentrated expertise in solid-state flow measurement. These three entities represent the dominant competitive positioning vectors—platform breadth versus metrology depth—that shape procurement decisions among utilities with diverging integration requirements.
| Leading Market Players |
|---|
| Itron Inc. |
| Landis+Gyr Group AG |
| Siemens AG |
| Schneider Electric SE |
| Honeywell International Inc. |
| Sagemcom SAS |
| Osaki Electric Co. |
| Kamstrup A/S |
| EDMI Limited |
| Others |
Supply Flow & Price Mechanics
Jiangsu and Zhejiang manufacturing clusters in China dictate downstream pricing power through captive production of application-specific integrated circuits and RF communication modules. Their scale advantages compress hardware margins for European and North American meter manufacturers locked into multi-year utility contracts with fixed-price escalation clauses.
Pricing Analysis
FERC Order 2222 dictates the pricing tier structure across the United States market by mandating distributed energy resource aggregation capabilities that separate premium AMI endpoints from basic metrology units. Pricing stratifies across certification-grade AMI, standard AMR replacement, and economy-tier legacy compatibility offerings. Cost compression in the standard tier is intensifying because semiconductor foundry allocation constraints force longer lead times for RF module procurement. Municipal and cooperative utilities exhibit highest price sensitivity due to constrained balance sheets, while investor-owned utilities prioritize interoperability certification over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Jabil, and Pegatron holding capacity for printed circuit board assembly and final meter integration. Taiwan and South Korea anchor semiconductor supply for ASIC and RF components, while China dominates magnet and coil assembly production. The chain draws from copper, rare earth elements, and epoxy resin inputs. Single-source vulnerability in Taiwan foundry capacity creates exposure to geopolitical disruption. Distribution runs through direct utility procurement channels and third-party AMI-as-a-service financiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates sticky utility relationships. Certification requirements and multi-year deployment cycles erect barriers that protect incumbent positions.
For Market Incumbents: Build switching-cost moats by embedding edge AI software layers that increase replacement friction. Deepen AMI platform integration to capture recurring revenue beyond hardware sales. Chinese manufacturers with state-backed financing pose the primary emerging threat through below-cost export pricing. Prioritize backward integration into semiconductor sourcing to secure foundry allocation.
For New Entrants and Emerging Players: Build out ultrasonic metrology specialization for water and thermal applications where mechanical meter incumbents lag. India's CEA smart grid roadmap presents the most penetrable geography given its 250-million-unit modernization mandate and fragmented state-utility procurement. Pursue direct-to-consumer channel strategies through third-party energy retail platforms in Germany and the Netherlands.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated-infrastructure play because national mandates for carbon tracking and grid modernization create durable demand visibility. Target acquisition candidates with communications module IP and utility relationship depth across multiple continents. Monitor NIST cybersecurity certification timelines as the critical inflection signal for communication architecture winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Integration | On-device machine learning for anomaly detection creates software revenue streams beyond hardware sales for Itron and Landis+Gyr. |
| AMI-as-a-Service Expansion | Subscription models transfer technology obsolescence risk from rural electric cooperatives to private capital financiers. |
| Ultrasonic Metrology Scale-Up | Solid-state flow measurement extends operational lifespan and reduces maintenance truck rolls for California municipal utilities. |
| Semiconductor Supply Agreement | Long-term foundry contracts with TSMC or Samsung secure ASIC allocation against geopolitical disruption risks. |
| India Market Entry Partnership | Joint ventures with Maharashtra and Gujarat state distribution companies accelerate penetration under CEA smart grid mandates. |
Methodological Framework
Cross-validation between utility procurement databases and semiconductor trade data anchors the qualitative findings in this analysis. Primary interviews with utility planning officers, AMI platform engineers, meter manufacturer procurement leads, and regulatory affairs specialists at state public utility commissions informed demand-side assumptions. Secondary sources include FERC filings, EIA smart grid deployment tracking, EU Green Deal implementation reports, and India CEA roadmap documentation. Bottom-up unit deployment estimates triangulate against top-down infrastructure investment forecasts.
Calibration against historical AMI replacement cycles and utility capital expenditure patterns shapes the projection framework across the analysis window. Segmentation dimensions modeled include technology tier (AMI, IoT-based, AMR, hybrid), end-user type (utility, industrial, residential, commercial), and deployment architecture (cloud, hybrid, on-premises, remote). CAGRs derive from fitted adoption curves incorporating regulatory mandate timelines and capital recovery schedules. Forecast inputs include foundry capacity expansion plans and raw material price indices for copper and rare earth elements.
Stress conditions across semiconductor supply disruption, copper price volatility, and cybersecurity certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and utility balance sheet capacity. Quarterly review of foundry allocation announcements, state-level renewable portfolio standard revisions, and NIST framework updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Home Energy Monitor Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Digital Water Meters Market
Smart Meters
Single-Phase Anti-Theft Meter Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
United States Smart Meter Market
Smart Meters
Smart Meter Data Management Market
Smart Meters
Europe Water Meter Market
Smart Meters
Power Monitoring System Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Smart Meter Battery Market
Smart Meters
Water Meter Market
Smart Meters
Plug in Power Meter Market
Smart Meters
Smart Meter Antenna Market