
 Global Smart Grid Networking Market | 2026-2036
Global Smart Grid Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Grid Networking Market Outlook
Copper cabling is decoupling from utility backbone deployments as fiber optic and wireless alternatives drive down lifecycle costs. ABB leverages its installed base in substation automation to sustain European utility contracts. Cisco Systems anchors North American market presence through standards-aligned networking hardware. Siemens differentiates with end-to-end digital grid portfolios spanning control systems to edge analytics.
Smart grid networking encompasses the communication infrastructure enabling real-time data exchange between generation, transmission, distribution, and consumption nodes in electrical power systems, typically operating across sub-GHz to multi-gigabit throughput ranges with latency requirements under 100 milliseconds for protection applications. Fiber optic technology leads capital deployment for backbone links while wireless sensor networks capture fastest growth in last-mile distribution monitoring. Control systems concentrate margin pools where software-defined automation integrates with legacy SCADA architectures. Metering solutions remain mature with replacement cycles driving steady revenue rather than expansion.
The EU Green Deal and F-Gas Regulation shape European product standards by mandating interoperable, low-emission grid infrastructure. The US Federal Energy Regulatory Commission and China's National Energy Administration each enforce distinct cybersecurity and reliability frameworks that vendors must satisfy for market access. Stakeholders should monitor divergence between IEEE and IEC protocol standards as regional regulatory fragmentation threatens interoperability investments.
Market Dynamics
IP/MPLS networking protocols are displacing legacy TDM backbones in utility communications, forcing infrastructure vendors to recertify hardware for packet-switched architectures while legacy SCADA integration costs mount.
Growth Catalysts
- EU Green Deal grid mandates:Brussels requires 80% smart meter penetration by 2027, compelling distribution operators to upgrade field area networks and backhaul capacity.
- China's dual carbon targets:State Grid Corporation deploys 5G private networks across 100+ cities to enable real-time demand response and distributed energy resource coordination.
- Sub-GHz mesh protocols:IEEE 802.15.4g Wi-SUN certification accelerates last-mile sensor deployment for transformer monitoring and fault detection.
Market Restraints
- Optical fiber input costs:Corning and Prysmian concentrate premium single-mode supply, exposing utilities to 18-24 month lead times for backbone cable orders.
- F-Gas regulatory friction:EU restrictions on sulfur hexafluoride switchgear force parallel communications infrastructure upgrades during replacement cycles.
- Proprietary protocol lock-in:DNP3 and IEC 61850 interoperability gaps require costly protocol gateways for multi-vendor deployments.
Strategic Opportunities
- India's smart city mission:Ministry of Power mandates smart prepaid metering in 100 urban clusters, opening greenfield communications infrastructure tenders.
- Edge AI convergence:NVIDIA Jetson and ARM Cortex deployments at distribution substations enable local inference for predictive maintenance without cloud latency.
- Virtual power plant orchestration:FERC Order 2222 compliance drives software procurement for aggregated DER dispatch across Texas and California ISO territories.
Industry Challenges
- OT cybersecurity certification:NERC CIP-013 supply chain standards extend vendor audit timelines by 9-14 months for North American utility approvals.
- Legacy SCADA integration:Serial-to-Ethernet protocol translation introduces latency jitter that violates protection relay timing requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Grid Networking Market |
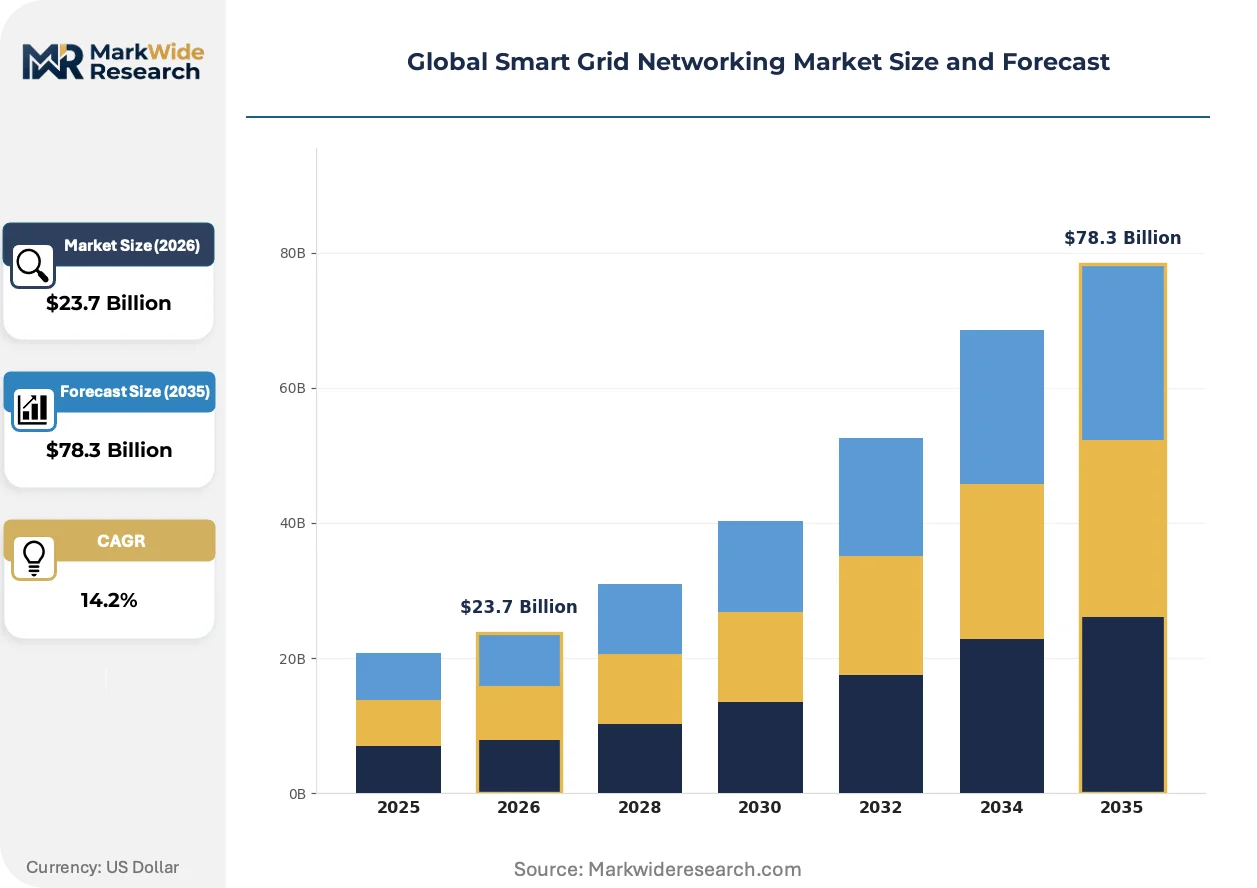
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IEC 61850, Wireless Sensor Networks, Power Line Communication, Fiber Optic Solution: Metering, Monitoring, Control Systems, Network Management End User: Utilities, Industrial Sector, Government Agencies, Commercial Buildings Deployment Model: On-Premises, Cloud-Based, Hybrid Solutions, Remote Monitoring |
| Companies Covered | ABB, Cisco Systems, Siemens, General Electric, Schneider Electric, Huawei Technologies, Fujitsu, Itron, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Grid Networking Market Strategic Shifts
Software-defined networking architectures are rewriting procurement specifications for utility communications, collapsing the distinction between operational technology and information technology infrastructure layers.
Time-sensitive networking over Ethernet is overtaking legacy SONET/SDH for protection-grade communications in transmission substations. Mid-Atlantic and Midwestern utilities in the United States are mandating TSN-capable switches in new RFPs. This migration is compressing maintenance windows for mission-critical circuits while enabling converged traffic classes.
EU F-Gas Regulation phase-down schedules are forcing synchronous upgrades of switchgear and communications cabinets in German and French substations. Utilities must coordinate SF6-free equipment procurement with fiber and wireless backhaul refreshes. The integrated tender approach favors vendors with combined electrical and networking portfolios.
Subscription-based network monitoring services are replacing perpetual-license NMS purchases among municipal and cooperative utilities. Cloud-native dashboards from systems integrators displace on-premise software in rural service territories. This shift concentrates most visibly in Australia and New Zealand where distributed generation penetration strains legacy operational models.
Global Smart Grid Networking Market Segmentation
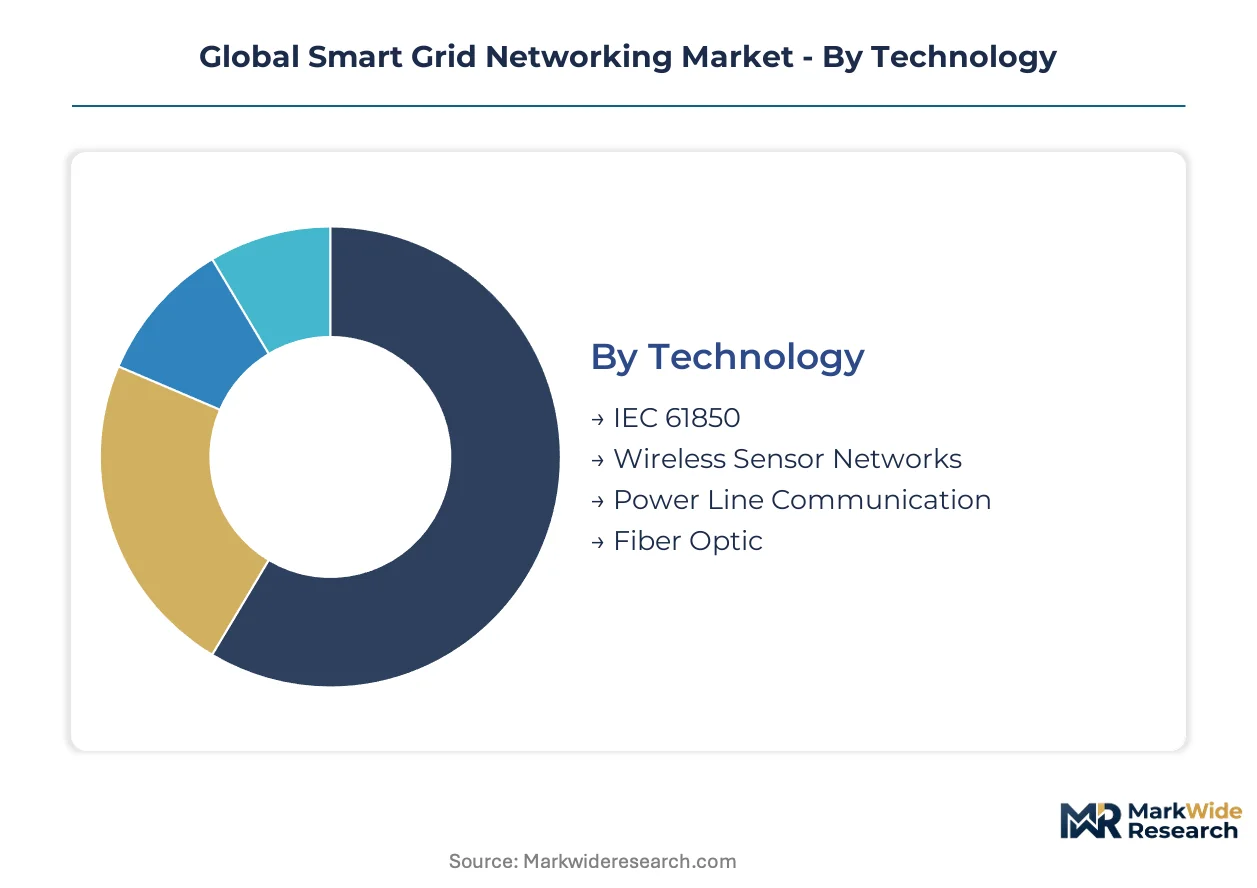
Smart grid networking segmentation reveals distinct technology maturity curves and procurement patterns across utility infrastructure layers. Each category carries specific interoperability requirements and lifecycle cost profiles that shape vendor positioning and deployment timelines.
Technology:
Fiber optic and wireless alternatives now dominate capital allocation, while legacy copper-dependent protocols retain installed base maintenance revenue.
- Fiber Optic:Single-mode and multimode fiber deliver gigabit throughput for transmission backbone links with sub-millisecond latency. German and Chinese utilities prioritize fiber for substation interconnects under EU Green Deal efficiency mandates and State Grid Corporation modernization programs. Mature deployment sits with Fiber Optic. Newer deployment is concentrated in Wireless Sensor Networks.
- Wireless Sensor Networks:IEEE 802.15.4g Wi-SUN and proprietary mesh protocols enable last-mile distribution monitoring without trenching costs. Australian utilities deploy sub-GHz networks across rural service territories where fiber economics fail. These networks expand most quickly across transformer monitoring and fault detection applications.
- IEC 61850:Ethernet-based substation automation standard with GOOSE messaging for protection-grade latency under 4 milliseconds. IEC 61850 requires packet-switched network infrastructure that displaces legacy TDM architectures.
- Power Line Communication:Narrowband and broadband signaling over existing medium-voltage and low-voltage conductors. PLC retains niche applications in European meter data collection where regulatory timelines preclude full fiber deployment.
Volume deployment favors established fiber infrastructure. Premium pricing attaches to wireless sensor networks in geographically constrained environments.
Solution:
Control systems and network management software concentrate margin pools, while metering solutions generate replacement-cycle revenue without expansion premiums.
- Control Systems:SCADA integration, distributed energy resource management, and protection relay coordination platforms. Siemens and ABB compete for European utility contracts with end-to-end digital grid portfolios spanning control systems to edge analytics. Mature deployment sits with Metering. Newer deployment is concentrated in Network Management.
- Network Management:Cloud-native dashboards and subscription-based monitoring services displace perpetual-license NMS purchases. Municipal utilities in Australia and New Zealand adopt SaaS operational models where distributed generation penetration strains legacy systems.
- Metering:Advanced metering infrastructure for consumption data collection and time-of-use billing. India's Ministry of Power mandates smart prepaid metering across 100 urban clusters, sustaining steady hardware procurement.
- Monitoring:Transformer health, line condition, and environmental sensor networks. Monitoring solutions bridge operational technology and information technology layers through software-defined networking architectures.
Software-defined architectures are compressing solution boundaries as utilities converge operational and information technology procurement.
End User:
Utility procurement dominates absolute spending, while industrial and commercial segments drive edge-case innovation for distributed energy integration.
- Utilities:Transmission and distribution operators with regulated rate-base treatment for infrastructure investment. US Federal Energy Regulatory Commission reliability frameworks and EU Green Deal interoperability mandates shape utility procurement specifications. Mature deployment sits with Utilities. Newer deployment is concentrated in Industrial Sector.
- Industrial Sector:Manufacturing campuses and process industries with captive generation and microgrid requirements. Texas and California industrial facilities procure FERC Order 2222-compliant virtual power plant orchestration software.
- Government Agencies:Municipal and cooperative utilities with constrained capital budgets. Subscription-based network monitoring services penetrate rural government-owned service territories.
- Commercial Buildings:High-rise and campus environments with building energy management system integration. Commercial demand concentrates in Germany and the United States where grid-edge flexibility markets reward demand response participation.
Regulatory rate-base treatment separates utility procurement timelines from commercial and industrial payback-driven investment cycles.
Deployment Model:
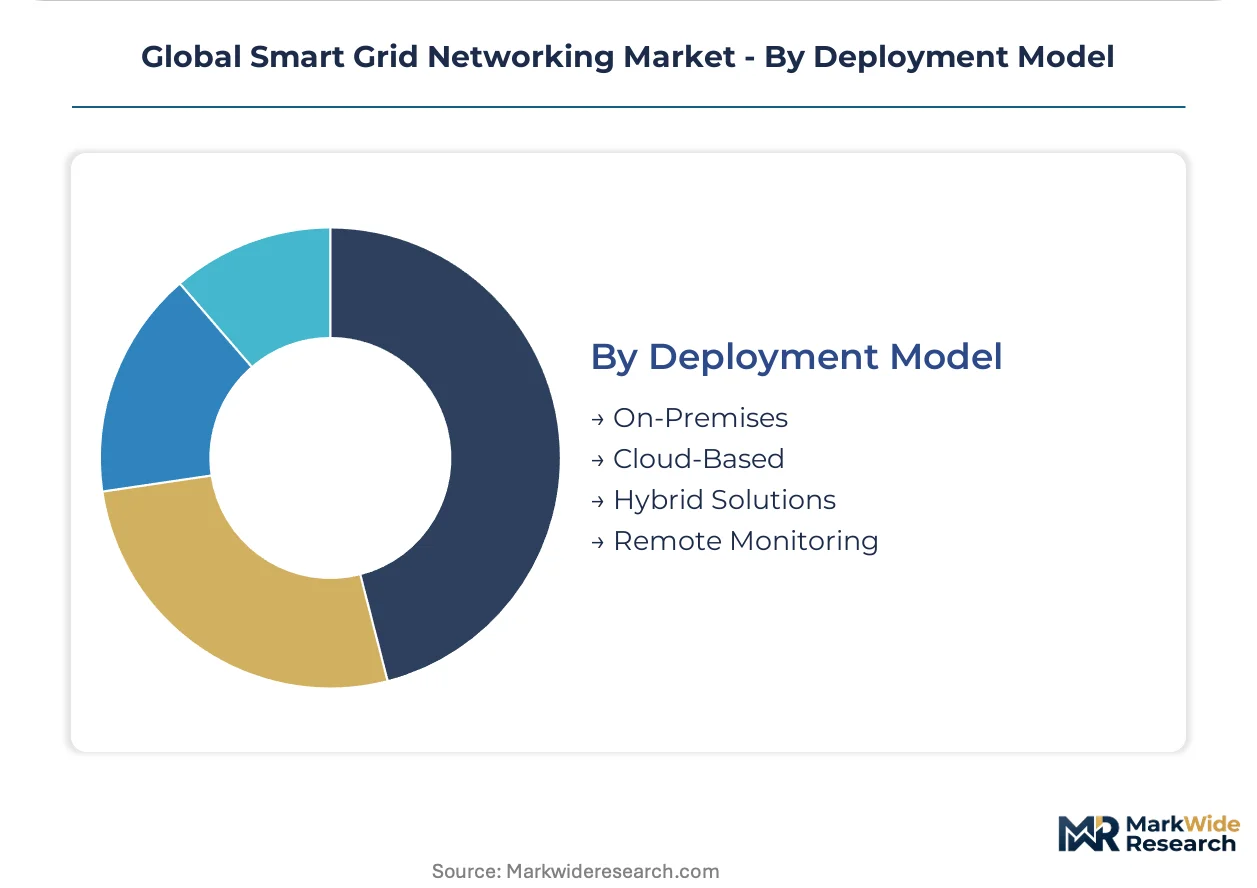
Hybrid architectures balance latency-critical on-premises control with cloud analytics scalability, while pure cloud models penetrate non-critical monitoring tiers.
- Hybrid Solutions:Time-sensitive networking switches at substations feed cloud-based analytics platforms for predictive maintenance. Mid-Atlantic and Midwestern US utilities mandate TSN-capable hardware in new RFPs while retaining local protection logic. Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
- Cloud-Based:Native SaaS network management and DER aggregation platforms. Cloud models gain traction in Australia and New Zealand where distributed generation penetration exceeds legacy operational model capacity.
- On-Premises:Air-gapped SCADA and protection systems meeting NERC CIP-013 cybersecurity certification requirements. On-premises deployment extends vendor audit timelines by 9-14 months for North American utility approvals.
- Remote Monitoring:Satellite and cellular backhaul for geographically dispersed assets. Remote monitoring serves transformer monitoring in rural China and pipeline-adjacent infrastructure in Canada.
Latency requirements for protection-grade circuits preserve on-premises dominance in transmission substations while distribution analytics migrate cloudward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart grid infrastructure investment concentrates in Germany, China, and the United States where aging transmission networks and decarbonization mandates converge. State Grid Corporation and municipal utilities across these markets drive capital allocation toward fiber backbones and wireless sensor networks. Regulatory frameworks in each jurisdiction shape procurement specifications and vendor certification requirements.
United States
FERC Order 2222 compliance and NERC CIP-013 cybersecurity standards drive utility procurement of virtual power plant orchestration software and packet-switched network hardware. The Federal Energy Regulatory Commission mandates reliability frameworks that extend vendor audit timelines by 9-14 months. Texas and California ISO territories concentrate demand response aggregation deployments across industrial facilities and municipal utilities.
Germany
EU Green Deal efficiency mandates and F-Gas Regulation phase-down schedules compel synchronous upgrades of switchgear and communications infrastructure. The EU Green Deal requires 80% smart meter penetration by 2027, forcing distribution operators to expand field area network capacity. Bavarian and North Rhine-Westphalian utilities favor vendors with combined electrical and networking portfolios for integrated tender compliance.
China
Dual carbon targets and State Grid Corporation modernization programs accelerate 5G private network deployment across 100+ cities for real-time demand response. The National Energy Administration enforces distinct cybersecurity and reliability frameworks for market access. Yangtze River Delta and Pearl River Delta clusters lead distributed energy resource coordination and substation automation investments.
India
Ministry of Power mandates for smart prepaid metering across 100 urban clusters open greenfield communications infrastructure tenders. The Central Electricity Authority and Bureau of Indian Standards shape interoperability specifications for multi-vendor deployments. Maharashtra and Gujarat industrial corridors concentrate early procurement of AMI backhaul and distribution transformer monitoring networks.
Australia
Distributed generation penetration exceeding legacy operational capacity drives cloud-native network management adoption among municipal and cooperative utilities. The Australian Energy Market Operator and state-level regulators facilitate subscription-based monitoring services in rural service territories. New South Wales and Victoria lead edge AI convergence at distribution substations for predictive maintenance without cloud latency.
Global Smart Grid Networking Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with end-to-end portfolio vendors capturing integrated tender opportunities while component specialists defend niche protocol certifications. The vendor base organizes around three archetypes: diversified industrial conglomerates with substation automation heritage, networking hardware specialists with standards-aligned product lines, and systems integrators with cloud-native service platforms. Competitive dynamics center on M&A activity to acquire protocol gateway capabilities and strategic partnerships to bridge IEEE-IEC interoperability gaps.
Within the diversified industrial tier, ABB leverages its installed base in substation automation to sustain European utility contracts, while Siemens differentiates with end-to-end digital grid portfolios spanning control systems to edge analytics. Cisco Systems anchors North American market presence through standards-aligned networking hardware. These three represent distinct strategic positions: ABB exemplifies legacy automation integration, Siemens occupies the comprehensive digital grid vector, and Cisco sits within the IT-native networking archetype.
| Leading Market Players |
|---|
| ABB |
| Cisco Systems |
| Siemens |
| General Electric |
| Schneider Electric |
| Huawei Technologies |
| Fujitsu |
| Itron |
| Mitsubishi Electric |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between NERC CIP-013 compliant hardware and uncertified commodity networking gear manifests in both procurement premiums and supply chain fragmentation. Utilities accepting extended vendor audit timelines for North American market access pay structural premiums, while municipal buyers in Australia and New Zealand gravitate toward subscription SaaS models that compress upfront capital requirements and reshape supplier inventory strategies.
Pricing Analysis
Volume deployment concentrates in mature fiber optic infrastructure where per-port pricing faces compression from Chinese and Korean optical component suppliers, while wireless sensor networks and edge AI-enabled substation equipment capture margin premiums through software-defined functionality and predictive maintenance bundling. Price differentiation rests on IEC 61850 protocol certification and FERC Order 2222 compliance tiering. Pricing pressure stems from State Grid Corporation's consolidated procurement power across 100+ city deployments. Municipal utilities exhibit highest price sensitivity; transmission operators with rate-base treatment show lowest.
Supply Chain Analysis
Single-mode fiber supply rests on Corning and Prysmian production concentration in the United States and Italy, while 5G private network equipment draws from Huawei, Ericsson, and Nokia manufacturing footprints in China, Sweden, and Finland. Critical dependencies include germanium-doped optical fiber preforms, ARM Cortex and NVIDIA Jetson edge processors, and sulfur hexafluoride-free switchgear enclosures. Single-source vulnerability concentrates in premium single-mode fiber for backbone links. Distribution runs through systems integrators with utility-certified installation capabilities rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over protocol gateway capabilities and IEEE-IEC interoperability bridging determines competitive durability. Players are pursuing backward integration into semiconductor and optical component supply to secure allocation priority during shortage cycles.
For Market Incumbents: Deepen substation automation software portfolios through edge AI acquisitions that compress cloud dependency for protection-grade latency requirements. Fortify against Cisco Systems' IT-native networking encroachment by embedding time-sensitive networking switches within integrated electrical and communications tenders. Prioritize certification investment for EU F-Gas Regulation synchronous upgrade cycles in German and French utilities. For New Entrants and Emerging Players: Rural cooperative utilities in Australia and New Zealand present underserved buyer archetypes with strained legacy operational capacity and openness to subscription-based network monitoring services. India's Ministry of Power smart city mandates across 100 urban clusters offer greenfield AMI backhaul penetration without incumbent replacement friction. Lead with cloud-native SaaS deployment to bypass capital-constrained procurement committees. For Investors and Strategic Acquirers: Re-rating potential sits with protocol gateway specialists given EU Green Deal and F-Gas Regulation interoperability mandates that force multi-vendor integration spend. Five-to-ten year viability favors vendors with combined electrical and networking portfolios capable of integrated tender compliance. Watch NERC CIP-013 audit timeline extensions as inflection indicator for North American vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Gateway Acquisition | IEEE-IEC interoperability gaps force costly multi-vendor integration spend across German and Chinese utilities. |
| Edge AI Platform Integration | NVIDIA Jetson deployments at distribution substations enable predictive maintenance without cloud latency penalties. |
| 5G Private Network Deployment | State Grid Corporation's 100+ city rollout establishes real-time demand response infrastructure for dual carbon targets. |
| SF6-Free Switchgear Synchronization | EU F-Gas Regulation phase-down compels coordinated communications cabinet upgrades in French substations. |
| Subscription NMS Transition | Australian municipal utilities adopt cloud-native dashboards where distributed generation strains legacy operational models. |
Study Parameters
Regulatory filings from FERC, EU Green Deal implementation documents, and State Grid Corporation procurement disclosures formed the secondary backbone. Primary interviews with utility planning officers, substation automation engineers, and systems integration specialists validated deployment timelines and vendor selection criteria. Bottom-up modeling of fiber optic, wireless sensor network, and edge equipment unit economics combined with top-down reconciliation against national smart meter penetration targets and grid modernization budgets.
Bottom-up volume builds aggregated individual technology segments across the projection horizon, while top-down constraints incorporated EU Green Deal 80% smart meter mandates and China's dual carbon policy enforcement. Segmentation dimensions spanned technology type, solution layer, end-user category, and deployment model complexity. CAGRs derived from utility capital expenditure trajectories and replacement cycle timing for legacy SCADA architectures. Forecast inputs incorporated 5G private network rollout schedules and F-Gas Regulation synchronous upgrade coordination.
Revisions become necessary when NERC CIP-013 certification timelines extend beyond current 9-14 month baselines, when optical fiber supply concentrates further among single-mode producers, or when IEEE-IEC protocol standard divergence accelerates regional fragmentation. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and utility rate-base treatment continuity. A small set of named triggers warrants ongoing watch: EU F-Gas phase-down acceleration, State Grid procurement consolidation, and Australia distributed generation penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Global Self-Healing Grid Market
Smart Grid
Smart Grid Technology Market
Smart Grid
India Smart Grid Network Market
Smart Grid
Power Grid Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Microgrid Market
Smart Grid
Smart Grid Network Market
Smart Grid
Smart Grid Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
Smart Water Grid Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
North America Microgrid Market