
 Microgrid Market | 2026-2036
Microgrid Market Size, Share, and Industry Trends Forecast 2026-2036
Microgrid Market Analysis
Data center and semiconductor fab load growth is repositioning microgrid demand toward multi-megawatt, always-on configurations. Schneider Electric leverages its EcoStruxure platform to dominate integrated control software for campus deployments. Siemens sustains technology leadership in grid-forming inverters and islanding controls. General Electric Company anchors its position through heavy rotating machinery and gas turbine hybridization expertise.
A microgrid constitutes a localized cluster of distributed energy resources, storage systems, and load management controls capable of islanding from or synchronizing with the broader utility grid, typically operating at voltages from 480V to 34.5kV depending on scale and interconnection requirements. Its primary purpose is to deliver resilient, dispatchable power to critical facilities, remote communities, or price-sensitive industrial loads. Energy storage deployments are expanding fastest as lithium-ion and emerging solid-state chemistries enable shorter payback periods and deeper renewable penetration. Solar photovoltaic integration occupies the largest installed capacity share across commercial and military end users. Remote deployment models compete on diesel displacement economics in mining camps, island grids, and frontier agricultural processing sites.
The US Federal Energy Regulatory Commission and state-level public utility commissions shape interconnection standards and standby tariff structures that directly influence project returns. Germany's Bundesnetzagentur and the EU F-Gas Regulation constrain synthetic refrigerant use in thermal assets, pushing thermal microgrids toward absorption chilling and waste heat recovery. Japan's METI grid codes for decentralized power sources govern inverter response and anti-islanding protocols. Stakeholders must monitor evolving capacity market participation rules and carbon border adjustments that will redefine which hybrid configurations qualify for premium revenue streams.
Market Dynamics
Island-capable microgrids are displacing traditional backup power architectures as data center load growth and climate-driven grid instability force facility operators toward autonomous energy systems with sub-cycle transfer capabilities.
Growth Catalysts
- US Inflation Reduction Act:Investment tax credits and standalone storage incentives compress payback periods for hybrid solar-plus-storage configurations across commercial and industrial sites.
- Semiconductor fabrication:Taiwan Semiconductor Manufacturing and Intel are procuring multi-megawatt islanding systems to protect wafer yields against voltage sags and momentary interruptions.
- Lithium-ion cost curves:Cell pack pricing declines enable four-hour storage durations to pencil economically against diesel gensets in mining camps and island territories.
Market Restraints
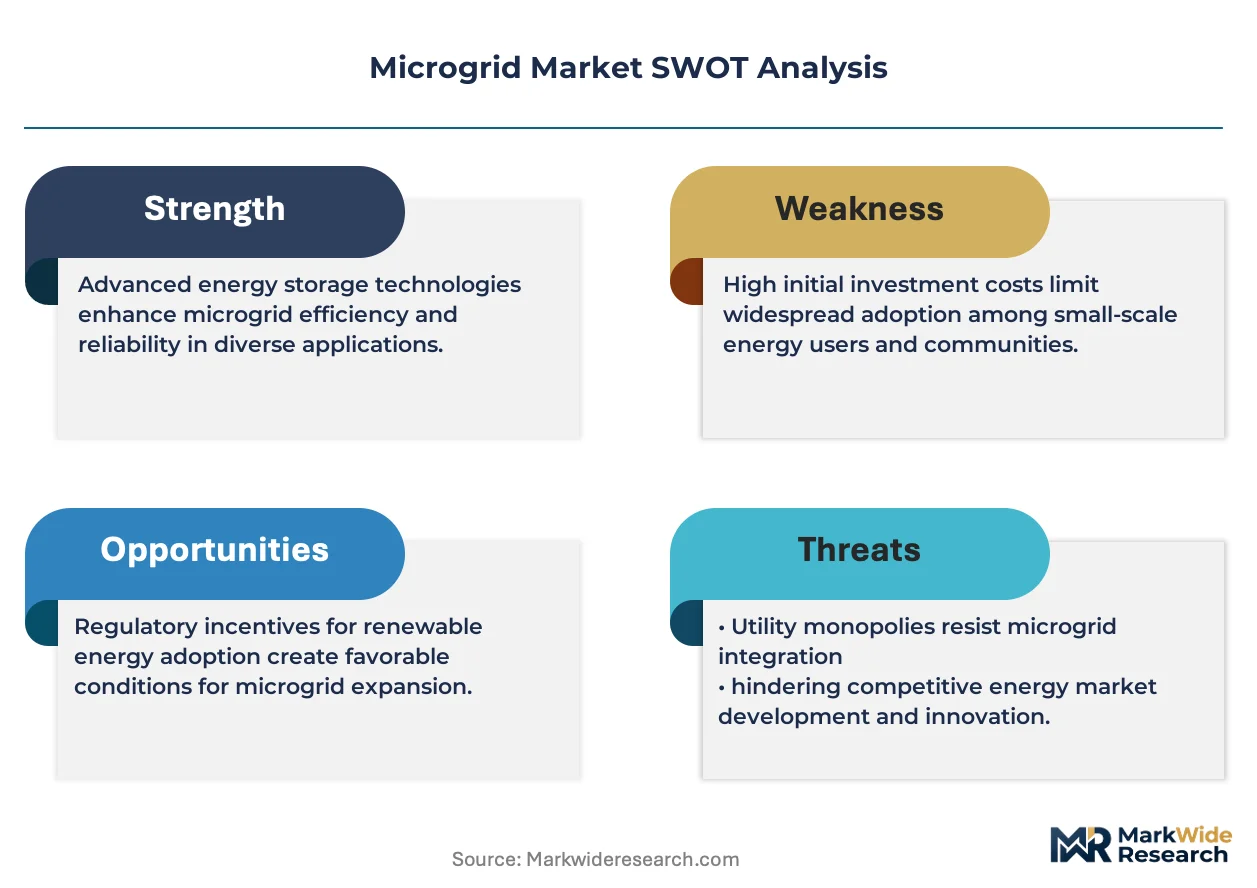
- Transformer and switchgear lead times:North American medium-voltage equipment backlogs extend project timelines by 8-14 months, constraining 2024-2025 deployment velocity.
- Copper and rare earth volatility:Permanent magnet synchronous generators for microturbines face input cost pressure from dysprosium and terbium supply concentration in Chinese processing facilities.
- Interconnection queue delays:US Federal Energy Regulatory Commission Order 2023 reforms have not cleared regional transmission organization backlogs, freezing revenue-grade metering approvals.
Strategic Opportunities
- Philippines archipelago electrification:The country's 7,600 islands present diesel displacement economics for solar-battery minigrids serving fishing cooperatives and rural health units.
- Grid-forming inverter convergence:Silicon carbide power electronics enable 150kHz switching frequencies that collapse harmonic distortion in 480V campus networks.
- Green hydrogen pilot zones:Germany's H2Global auction mechanism creates offtake certainty for electrolyzer-integrated microgrids at chemical parks in the Ruhr region.
Industry Challenges
- Protection engineering scarcity:Relay coordination for bidirectional fault current flows requires specialized technicians absent from most electrical contractor workforces.
- Cyber-physical security certification:NERC CIP-013 supply chain standards and IEC 62443-3-3 SL2 compliance add 6-9 months to control system commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microgrid Market |
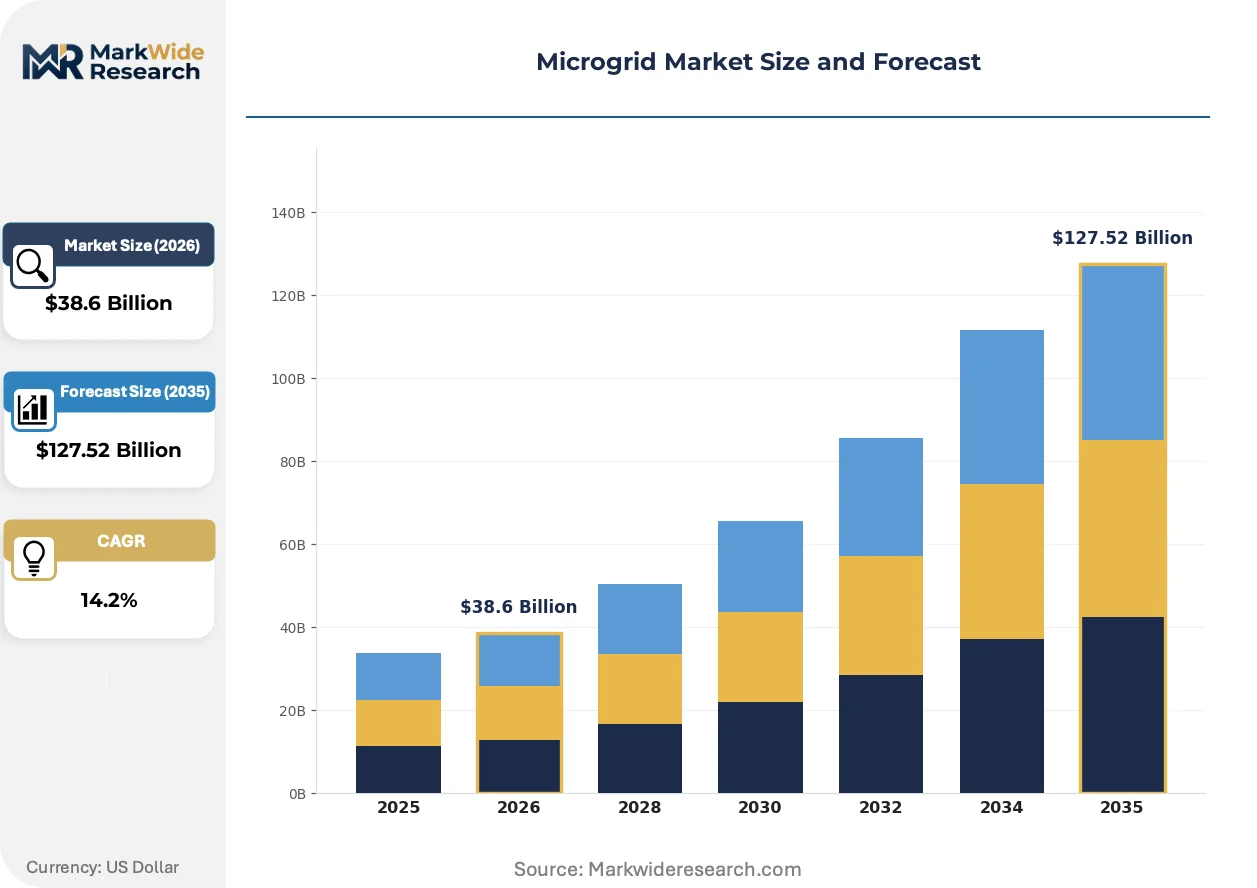
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Energy Storage Deployment: Onsite, Remote, Campus, Utility End User: Commercial, Industrial, Residential, Military Application: Renewable Integration, Backup Power, Grid Resilience, Smart City |
| Companies Covered | Schneider Electric, General Electric Company, Siemens, ABB, Eaton Corporation PLC, Hitachi Energy Ltd., Honeywell International Inc., S&C Electric Company, Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microgrid Market Emerging Trajectories
Solid-state battery chemistries and artificial intelligence-driven load forecasting are compressing the economic threshold for 100% renewable microgrids, while regulatory frameworks in multiple jurisdictions are codifying compensation for grid services previously treated as ancillary.
Solid-state lithium-metal cells are integrating into containerized storage skids for military forward operating bases, replacing flammable liquid electrolytes with ceramic separators that tolerate 60°C ambient temperatures without thermal runaway. Marine Corps Systems Command is qualifying 1MWh units for expeditionary deployments by 2026. This chemistry is integrating fire-safety margins that enable indoor installation in dense urban campuses previously restricted to outdoor battery yards.
Germany's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in absorption chillers, pushing district cooling microgrids toward ammonia-water and lithium bromide cycles with waste heat recovery from biogas engines. Bundesnetzagentur grid codes now remunerate fast frequency response from aggregated distributed assets. Industrial parks in Bavaria are responding with thermal-electric hybrid configurations that arbitrage capacity market payments against industrial steam loads.
Data center operators are unbundling energy-as-a-service contracts from colocation leases, creating direct offtake relationships with microgrid developers rather than utility intermediaries. Switch, CyrusOne, and EdgeConneX are negotiating 15-20 year power purchase agreements with behind-the-meter solar and storage assets in Arizona and Nevada. This restructuring is most visible in markets with retail choice or deregulated generation tariffs where nodal pricing exposes data halls to real-time volatility.
Microgrid Market Segmentation
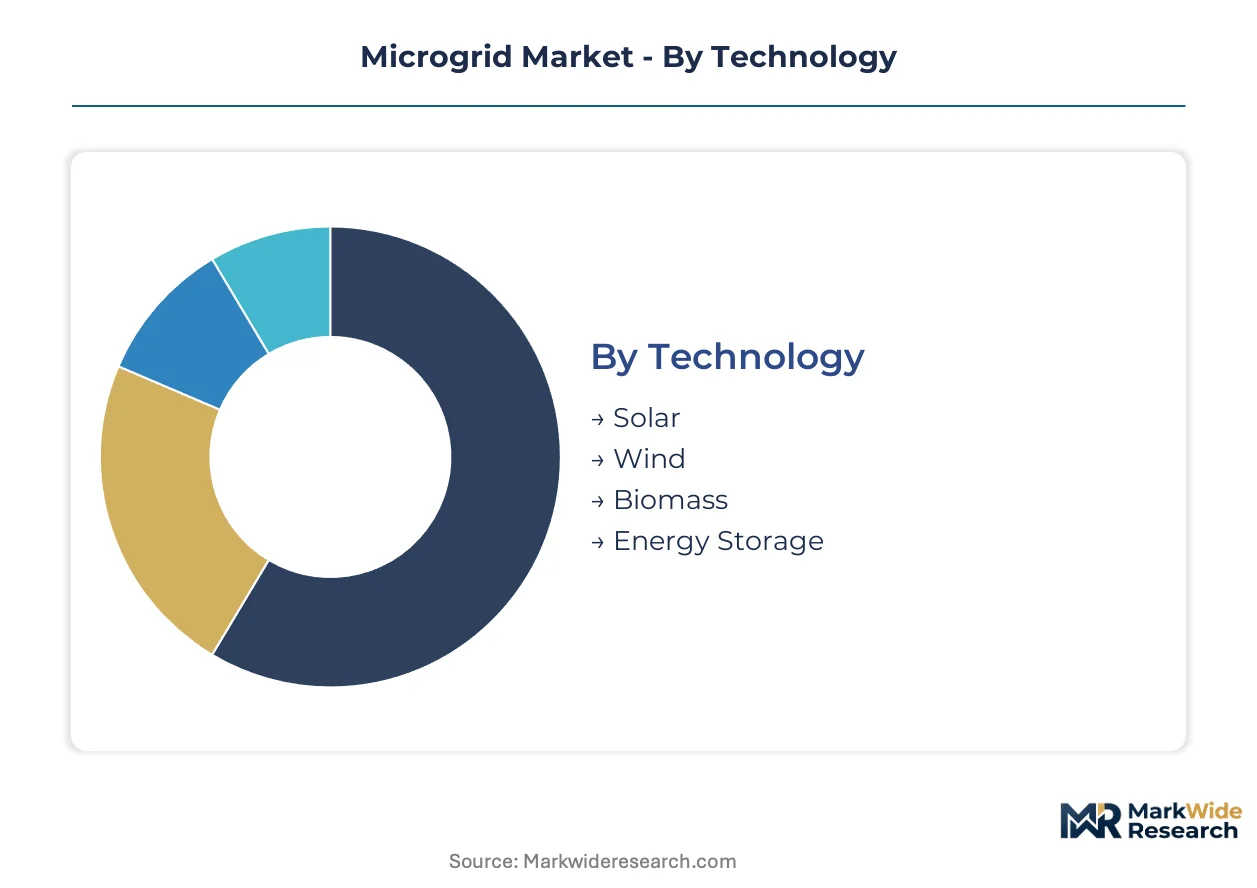
Microgrid architectures diverge sharply across deployment contexts, from standardized containerized units for mining camps to bespoke campus networks integrating legacy thermal assets. Technology selection and ownership models determine project economics, interconnection complexity, and regulatory exposure.
Technology:
Standardized modular designs dominate solar and storage, while biomass and wind require site-specific engineering and resource assessment.
- Solar:Photovoltaic arrays constitute the largest installed capacity share, with bifacial panels and tracking systems maximizing yield per acre. Data center operators in Arizona and Nevada are procuring behind-the-meter solar to hedge against nodal pricing volatility.
- Energy Storage:Lithium-ion battery systems enable sub-cycle islanding and four-hour dispatch economics, with solid-state chemistries entering qualification for military forward operating bases. Marine Corps Systems Command targets 1MWh containerized units by 2026.
- Wind:Small-scale turbines serve remote agricultural processing and island grids where diesel displacement economics justify higher capital intensity.
- Biomass:Biogas engines with waste heat recovery power district heating networks in Bavarian industrial parks, arbitraging capacity market payments against thermal loads.
Leading the category by volume: Solar. Expanding most quickly: Energy Storage.
Deployment:
Customer type and grid proximity dictate whether projects pursue behind-the-meter simplicity or utility-scale interconnection revenue streams.
- Onsite:Behind-the-meter configurations for semiconductor fabs and data centers prioritize sub-cycle transfer and voltage sag protection. Taiwan Semiconductor Manufacturing and Intel anchor procurement for multi-megawatt islanding systems.
- Remote:Diesel displacement economics drive solar-battery minigrids across the Philippines' 7,600 islands, serving fishing cooperatives and rural health units without transmission access.
- Campus:Universities and medical centers leverage existing distribution infrastructure, integrating combined heat and power with solar and storage under single control platforms.
- Utility:Front-of-the-meter assets participate in wholesale markets and capacity programs, requiring FERC interconnection compliance and revenue-grade metering approvals.
Steepest expansion trajectory: Remote. Largest revenue pool: Onsite.
End User:
Load criticality and uptime requirements separate price-sensitive commercial buyers from mission-critical military and industrial procurement.
- Industrial:Semiconductor fabrication and mining camps demand 99.999% availability, justifying premium island-capable architectures with N+1 redundancy.
- Military:Forward operating bases and domestic installations prioritize cyber-physical security, solid-state battery fire safety, and expeditionary mobility.
- Commercial:Retail and office loads optimize around peak shaving and demand charge reduction, with shorter payback thresholds than industrial buyers.
- Residential:Single-home and neighborhood systems concentrate in California and Texas grid instability zones, leveraging IRA investment tax credits.
Highest average project value: Industrial. Fastest policy support accumulation: Military.
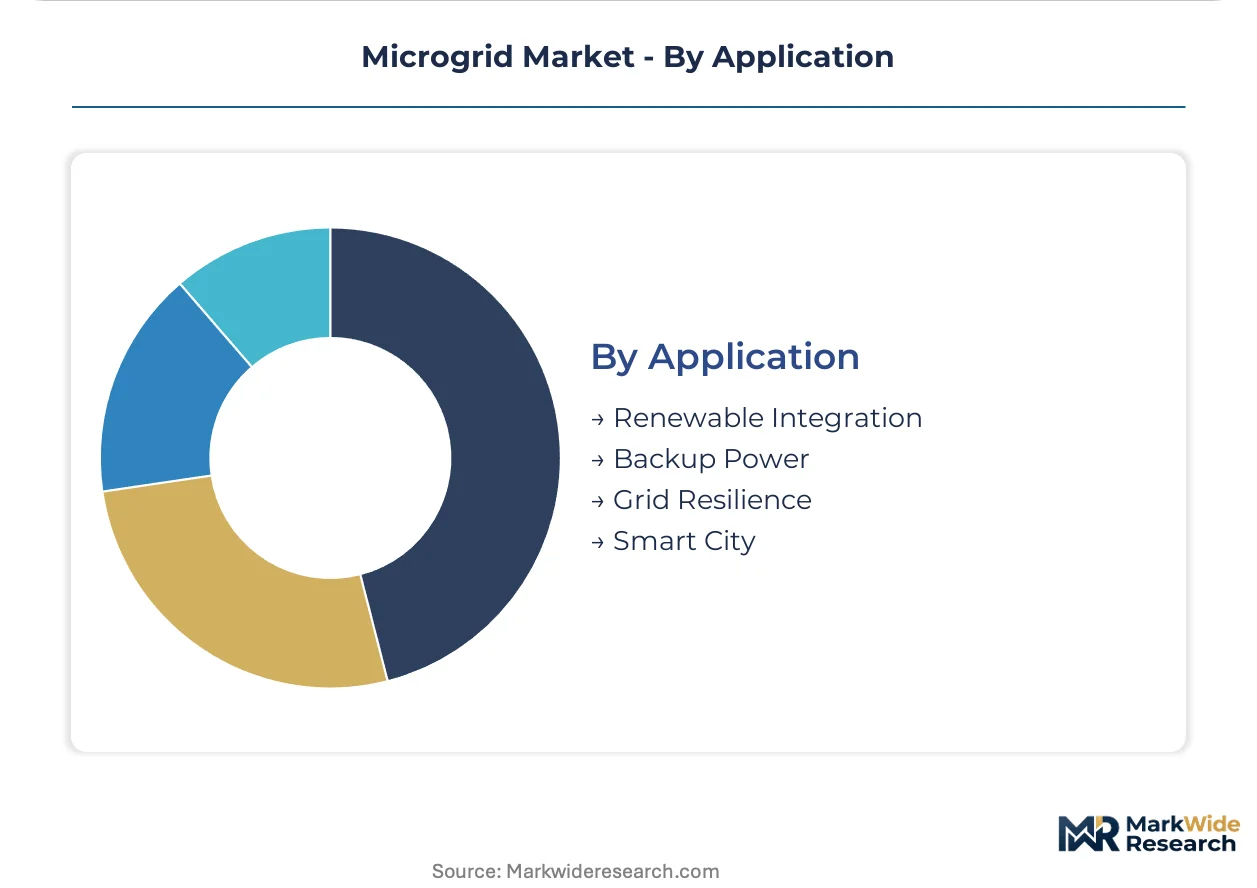
Application:
Use case specificity determines whether microgrids optimize for cost reduction, resilience, or grid services revenue.
- Grid Resilience:Hurricane-prone territories and wildfire zones in California deploy island-capable systems to maintain critical facility operations during extended outages.
- Renewable Integration:High renewable penetration targets in Germany's Ruhr region drive electrolyzer-integrated configurations under the H2Global auction mechanism.
- Backup Power:Traditional diesel genset replacement dominates mining camps and frontier agricultural processing where grid extension is uneconomic.
- Smart City:Municipal deployments aggregate distributed assets for frequency response and voltage regulation, remunerated under evolving capacity market rules.
Gaining share fastest: Grid Resilience. Maturest revenue model: Backup Power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones under the US Inflation Reduction Act, Germany's H2Global auction mechanism, and Japan's FIT successor programs are concentrating microgrid capital flows into specific regulatory jurisdictions with de-risked revenue streams.
United States
Data center load growth in Arizona and Nevada drives behind-the-meter solar-plus-storage procurement. FERC Order 2023 reforms attempt to clear interconnection backlogs that currently freeze revenue-grade metering approvals. Switch, CyrusOne, and EdgeConneX negotiate 15-20 year power purchase agreements in deregulated generation tariff markets.
Germany
Industrial parks in Bavaria and the Ruhr region arbitrage capacity market payments against thermal-electric hybrid configurations. The F-Gas Regulation phases down hydrofluorocarbon refrigerants, pushing district cooling toward ammonia-water absorption cycles. Bundesnetzagentur grid codes now remunerate fast frequency response from aggregated distributed assets.
Japan
Semiconductor fabrication facilities procure multi-megawatt islanding systems to protect wafer yields against voltage sags. METI grid codes for decentralized power sources govern inverter response and anti-islanding protocols. Domestic installations prioritize cyber-physical security and solid-state battery fire safety for critical infrastructure.
Philippines
The archipelago's 7,600 islands present diesel displacement economics for solar-battery minigrids serving fishing cooperatives and rural health units without transmission access. Remote deployment models compete on fuel substitution payback periods. Provincial electrification programs target frontier agricultural processing sites.
Australia
Mining camps in Western Australia and Queensland justify premium island-capable architectures through diesel displacement economics. Lithium-ion cost curves enable four-hour storage durations to pencil economically against gensets. State-level renewable penetration targets accelerate hybrid solar-plus-storage configurations.
Microgrid Market Vendor Landscape
Top-tier vendors anchor integrated control platforms and grid-forming inverter portfolios, while mid-tier specialists concentrate on protection engineering and cyber-physical security certification. The vendor base stratifies across three functional tiers: full-stack platform providers, component specialists in power electronics and thermal assets, and regional system integrators with local interconnection expertise. Dominant competitive moves include technology licensing partnerships for silicon carbide power electronics and strategic alliances between storage OEMs and campus control software providers.
Within the platform-provider tier, Schneider Electric SE and General Electric Company occupy positions exemplifying divergent strategic emphases—Schneider Electric leverages integrated software architectures for campus deployments, while General Electric anchors heavy rotating machinery and gas turbine hybridization expertise. Siemens AG represents the specialized inverter and islanding control archetype, sustaining technology leadership in grid-forming capabilities. These three entities collectively illustrate how competitive positioning fragments across software-centric, hardware-centric, and hybrid integration pathways.
| Leading Market Players |
|---|
| Schneider Electric |
| General Electric Company |
| Siemens |
| ABB |
| Eaton Corporation PLC |
| Hitachi Energy Ltd. |
| Honeywell International Inc. |
| S&C Electric Company |
| Lockheed Martin Corporation |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of silicon carbide power electronics and containerized battery skids anchors supply positions for integrated microgrid vendors while insulating them from spot-market volatility in copper and rare earth inputs. This vertical control over critical power conversion components translates directly into pricing power for grid-forming inverter portfolios and campus-scale control platforms.
Pricing Analysis
Premium pricing for sub-12-week transformer and switchgear delivery compresses margins for EPC contractors facing North American equipment backlogs. Project-based contract structures dominate, with price differentiation driven by UL 1741 certification tier and after-sales service bundling. Cost compression in lithium-ion cell packs is intensifying because Chinese cathode processing expansion outpaces demand, while mining camp operators remain most price-sensitive due to diesel displacement payback thresholds.
Supply Chain Analysis
Regional distribution centers in Texas and Arizona serve hub-and-spoke patterns for data center deployments, with final-mile integration handled by local electrical contractors. Manufacturing concentrates in China for lithium-ion cells, Germany for precision power electronics, and the US for gas turbine hybridization packages. Raw material dependencies span dysprosium and terbium for permanent magnet generators, copper for medium-voltage switchgear, and lithium carbonate for battery chemistries. Single-source vulnerability in Chinese rare earth processing feeds tariff exposure across inverter supply chains. Distribution runs through OEM-direct channels for large industrial offtakers and regional integrator networks for remote minigrid deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from transformer lead-time backlogs and interconnection queue delays will force smaller system integrators into strategic exits or acquisition by full-stack platform providers.
For Market Incumbents: Deepen captive supply of silicon carbide wafers and grid-forming inverter stacks to defend against emerging Chinese power electronics entrants. Acquire regional protection engineering specialists to address relay coordination scarcity that delays commissioning timelines. For New Entrants and Emerging Players: Begin with diesel displacement economics in Philippine island territories where incumbent presence remains thin and provincial electrification programs create direct procurement channels. Target fishing cooperatives and rural health units with standardized solar-battery skids under performance-based service contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated platform providers seeking cyber-physical security certification capabilities and islanding control IP. Long-term viability favors assets with FERC interconnection expertise and NERC CIP-013 compliance infrastructure. Watch for capacity market rule finalization as the inflection signal for grid-services revenue monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide | Captive wafer supply insulates GE and Siemens from Chinese power electronics pricing volatility. |
| Grid-Forming Inverter Certification | UL 1741 SA compliance unlocks California and Texas data center procurement for Schneider Electric. |
| Cyber-Physical Security Investment | NERC CIP-013 and IEC 62443-3-3 SL2 qualification differentiates Lockheed Martin in military forward operating base competitions. |
| Remote Minigrid Standardization | Containerized solar-battery skids with four-hour duration economics penetrate Philippine archipelago electrification programs. |
| Thermal-Electric Hybrid Configuration | Waste heat recovery from biogas engines arbitrages Bundesnetzagentur capacity market payments for Bavarian industrial parks. |
Methodological Framework
Multi-period observation of FERC interconnection queue lengths, lithium-ion cell pack pricing indices, and provincial electrification program allocations anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from EIA generation capacity databases, IEA distributed energy outlooks, FERC Order 2023 proceeding documents, and project development tracking services. Bottom-up unit economics for diesel displacement models triangulated against top-down regulatory incentive flow estimates.
Input-output matrices mapped technology adoption curves across solar, storage, wind, and biomass segments against deployment contexts from onsite behind-the-meter to remote island configurations. The analytical framework modeled capacity tier, regulatory framework, and regional grid stability indices throughout the forecast period. CAGRs derived from segment-level unit deployment trajectories and average project value compression curves. Forecast inputs included IRA investment tax credit utilization rates and solid-state battery qualification timelines from Marine Corps Systems Command.
Underlying measurement precision varies by segment; remote minigrid deployment counts carry tighter precision than speculative green hydrogen pilot zones. Forecasts reflect documented assumptions around interconnection reform implementation and rare earth supply chain diversification. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
China Smart Grid Network Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Smart Grid Market
Smart Grid
India Smart Grid Network Market
Smart Grid
Global Microgrid As a Service Market
Smart Grid
Smart Microgrid Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Smart Grid Network Market
Smart Grid
North America Automated Demand Response Management System Market
Smart Grid
Europe Microgrid Market