
 Demand Response Market | 2026-2036
Demand Response Market Size, Share, and Industry Trends Forecast 2026-2036
Demand Response Market Analysis
The EU Green Deal is broadening the addressable market for demand response aggregators across European member states. Siemens leverages its building automation portfolio to capture commercial and industrial load flexibility contracts. Schneider Electric anchors its position through integrated energy management systems that bridge grid operator signals with on-site asset control. AutoGrid Systems specializes in software platforms that enable utilities to dispatch distributed energy resources at scale.
Demand response encompasses the voluntary reduction or shifting of electricity consumption by end users in response to price signals, grid conditions, or direct dispatch instructions, typically executed through automated controls with response times ranging from seconds to hours depending on the service type. Its primary purpose is to balance electricity supply and demand in real time while deferring costly infrastructure investments. The service type dimension shows peak demand reduction and frequency regulation commanding premium compensation in wholesale markets, while load shifting represents the fastest-growing category as renewable penetration intensifies supply volatility. The technology dimension reveals demand response platforms capturing disproportionate software margin pools, whereas smart meters constitute the mature infrastructure layer with limited differentiation.
FERC in the United States, EMA through national implementations of EU electricity market directives, and Japan's METI each shape market access rules for aggregators and set compensation frameworks for flexibility services. These regulators determine whether distributed loads qualify as dispatchable resources and establish data interoperability standards between utilities and third-party providers. Stakeholders must monitor evolving market participation rules and technology certification requirements as grid operators redefine resource adequacy around flexible demand rather than firm generation capacity alone.
Market Dynamics
Automated load curtailment programs are restructuring electricity market participation as commercial building operators replace manual demand response with software-orchestrated flexibility services. Grid operators now treat aggregated distributed loads as dispatchable capacity, compressing the procurement timeline from day-ahead markets to real-time balancing mechanisms.
Growth Catalysts
- FERC Order 2222:The US regulation mandates wholesale market access for distributed energy resource aggregators, enabling commercial buildings to bid load flexibility alongside traditional generators.
- Commercial real estate:Property managers deploy automated building management systems to capture ancillary service revenue streams from frequency regulation and demand response programs.
- EU Green Deal:The framework accelerates member state implementation of demand response obligations, requiring utilities to procure a minimum percentage of flexibility from demand-side resources.
Market Restraints
- Interoperability fragmentation:Proprietary communication protocols between smart meters and aggregator platforms create integration friction and lock-in costs for building operators.
- Data access restrictions:Utility tariff structures in Germany and Japan limit granular consumption data sharing with third-party demand response providers, constraining optimization algorithms.
- Capital intensity of retrofits:Legacy HVAC and industrial process equipment requires control system upgrades before automated load curtailment becomes technically feasible.
Strategic Opportunities
- Behind-the-meter storage convergence:Pairing battery systems with demand response software creates stacked revenue streams from energy arbitrage, frequency regulation, and peak demand reduction.
- India's electricity market reforms:State-level regulatory pilots are opening wholesale markets to demand response aggregators in Maharashtra and Gujarat.
- Industrial process flexibility:Cold storage, water pumping, and electrolysis operations represent underutilized interruptible loads with fast ramp capabilities suitable for ancillary services.
Industry Challenges
- Cybersecurity certification timelines:Grid operators impose IEC 62443 compliance requirements on demand response platforms, extending vendor qualification cycles by 12-18 months.
- Legacy SCADA integration:Industrial facilities operate control systems with decades-old architectures that resist API-based connectivity to modern aggregation platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demand Response Market |
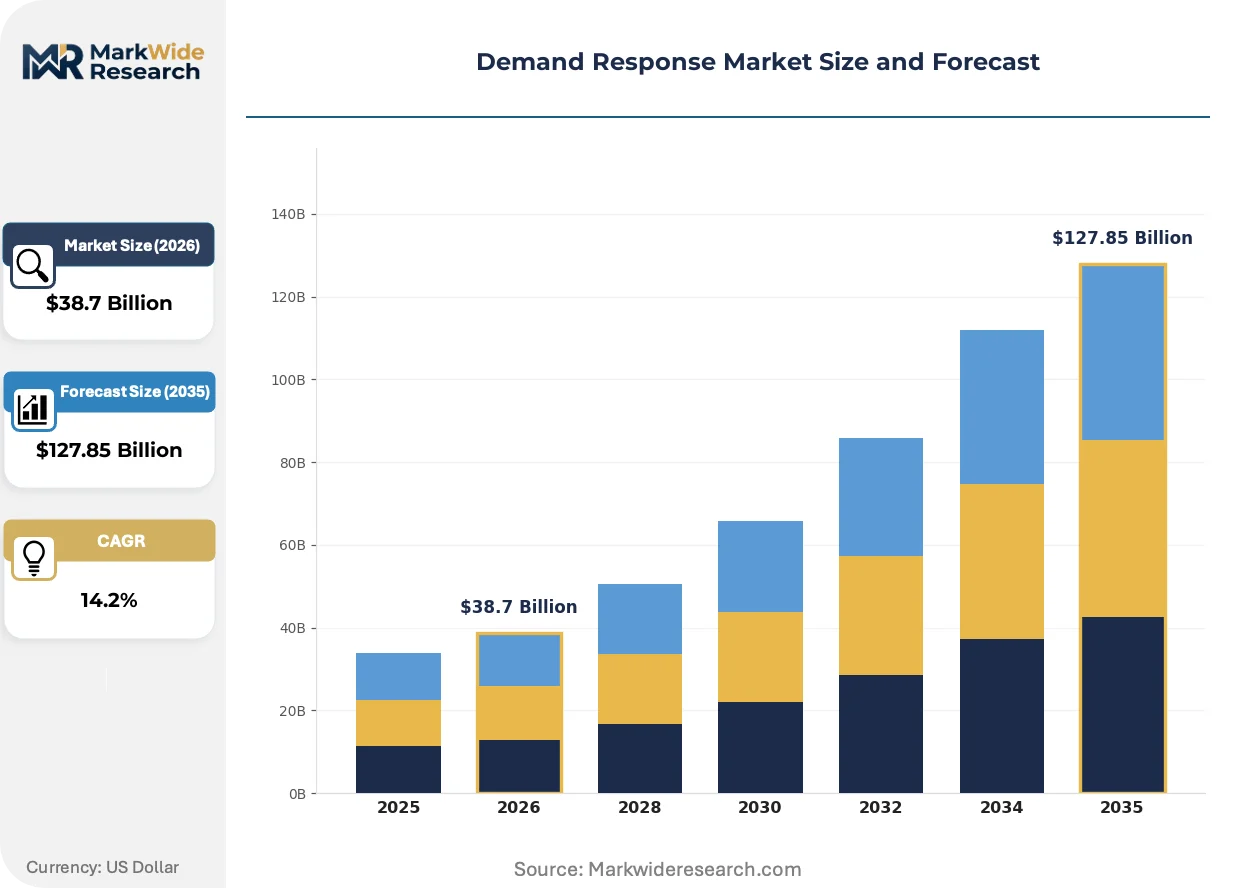
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Load Shifting, Peak Demand Reduction, Frequency Regulation, Capacity Market Technology: Automated Controls, Smart Meters, Energy Management Systems, Demand Response Platforms End User: Commercial, Industrial, Residential, Utilities Application: Electricity Market Participation, Grid Stabilization, Renewable Integration, Energy Efficiency Programs |
| Companies Covered | Eaton, Siemens, Honeywell International Inc., Enel X, Oracle, General Electric, Schneider Electric, AutoGrid Systems, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demand Response Market Emerging Trajectories
Software platforms for distributed energy resource management are absorbing functionality from adjacent categories, collapsing the vendor landscape as building automation and grid-edge control converge. This consolidation is compressing procurement decisions for utilities and large energy users.
Artificial intelligence-based load forecasting is consolidating predictive capabilities previously scattered across separate demand response, energy management, and building automation systems. Grid operators in California and Texas deploy these platforms to anticipate consumption patterns at 15-minute intervals. The technology is consolidating vendor margins into integrated software stacks that displace point solutions.
The EU Electricity Market Directive through national implementations requires member states to remove barriers preventing demand response participation in all market timeframes. Germany's Bundesnetzagentur and France's CRE have issued implementation rules mandating fair compensation for flexibility services. Industrial loads in Northern Europe now qualify for capacity markets previously reserved for generation assets.
Energy-as-a-service contracting is displacing capital expenditure models for demand response enablement. Commercial building owners in the United States and Japan prefer performance-based agreements where technology vendors retain ownership of control systems and share realized savings. This restructures vendor economics toward recurring software revenue and away from hardware margins.
Demand Response Market Segmentation
Segmentation in demand response reveals how value pools distribute across technical capabilities, customer sophistication, and regulatory access. Buyers with automated infrastructure capture premium service contracts, while technology choices determine integration complexity with grid operator systems.
Service Type:
Compensation tiers separate emergency capacity from continuous ancillary services, with response speed and duration driving contract value.
- Peak Demand Reduction:Curtailment events lasting 1-4 hours reduce consumption during system peak periods. Commercial buildings in the United States dominate procurement, with FERC Order 2222 enabling aggregator participation in wholesale capacity markets.
- Frequency Regulation:Sub-second to minute-scale load adjustments maintain grid frequency within operational bounds. Industrial facilities with automated process controls in Germany capture premium payments through the country's primary control reserve market.
- Load Shifting:Time-flexible consumption moves demand away from peak pricing windows.
- Capacity Market:Forward commitments provide resource adequacy guarantees to system operators.
Volume sits with Peak Demand Reduction; growth tilts toward Frequency Regulation.
Technology:
Integration depth determines whether demand response operates as siloed equipment or unified grid-edge infrastructure.
- Demand Response Platforms:Cloud-based software orchestrates dispatch signals across heterogeneous asset portfolios. Aggregators in Japan leverage these systems to pool residential and commercial loads for METI-certified flexibility tenders.
- Automated Controls:Building management system integrations execute curtailment without manual intervention. Large commercial real estate operators in the United States deploy these to capture ancillary service revenue without on-site staff.
- Energy Management Systems:On-site optimization software balances energy costs against demand response payments.
- Smart Meters:Interval metering infrastructure provides consumption visibility and remote switching capability.
Deployment concentrates in Automated Controls; margin expansion favors Demand Response Platforms.
End User:
Load scale and controllability determine which customer classes qualify for wholesale market participation versus utility-managed programs.
- Commercial:Office buildings, retail centers, and hotels with centralized HVAC systems offer predictable curtailment profiles. Property managers across EU member states deploy building automation to meet Green Deal flexibility procurement mandates.
- Industrial:Manufacturing and process facilities with interruptible loads provide fast-ramp flexibility. Cold storage and water pumping operations in Texas and California qualify for grid operator dispatch as emergency reserves.
- Residential:Distributed thermostat and water heater control aggregates household loads into dispatchable blocks.
- Utilities:Vertically integrated power providers deploy demand response as regulated demand-side management programs.
Revenue pools concentrate in Commercial; participation rates expand fastest in Industrial.
Application:
Use case specificity shapes whether demand response functions as market revenue generator or compliance-driven cost center.
- Grid Stabilization:Real-time frequency and voltage support prevents cascading outages. System operators in Japan and Germany procure these services through competitive tenders open to aggregated demand resources.
- Renewable Integration:Flexible demand absorbs solar and wind output variability. California grid operators deploy automated load curtailment to manage duck curve ramping constraints during evening demand surges.
- Electricity Market Participation:Direct bidding of load flexibility into wholesale energy and capacity markets.
- Energy Efficiency Programs:Utility-administered demand reduction achieves mandated conservation targets.
Procurement volume flows through Grid Stabilization; policy momentum gathers behind Renewable Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of demand response software and control systems concentrates in the United States, Germany, and Japan, while consumption spreads across commercial and industrial clusters in these markets as grid operators procure flexibility services.
United States
FERC Order 2222 mandates wholesale market access for distributed energy resource aggregators, opening capacity and ancillary service markets to commercial building loads. Texas and California grid operators deploy automated load curtailment to manage supply volatility from renewable penetration. Property managers in Dallas-Fort Worth and Silicon Valley capture frequency regulation revenue through building management system integrations.
Germany
Industrial facilities with automated process controls capture premium payments through the primary control reserve market for fast-ramp flexibility services. The Bundesnetzagentur implements EU Electricity Market Directive rules mandating fair compensation for demand-side resources in capacity markets. Manufacturing clusters in North Rhine-Westphalia and Bavaria qualify aggregated loads for grid operator dispatch previously reserved for generation assets.
Japan
METI-certified flexibility tenders enable aggregators to pool residential and commercial loads for system operator procurement. The country's electricity market reforms open wholesale balancing mechanisms to demand response providers. Tokyo and Osaka metropolitan areas concentrate building automation deployments that automate HVAC curtailment without on-site staff intervention.
United Kingdom
Grid operator procurement frameworks treat aggregated distributed loads as dispatchable capacity for real-time balancing services. National implementation of EU flexibility mandates requires utilities to remove barriers preventing demand response participation across all market timeframes. Commercial real estate in London and Manchester deploys energy management systems to bridge grid operator signals with on-site asset control.
India
State-level regulatory pilots in Maharashtra and Gujarat open wholesale markets to demand response aggregators as electricity market reforms advance. The Central Electricity Authority shapes market access rules for flexibility service providers and sets compensation frameworks. Industrial zones in Ahmedabad and Mumbai test automated load curtailment programs for cement, steel, and cold storage operations.
Demand Response Market Vendor Landscape
The competitive structure tilts toward integrated energy management conglomerates with building automation portfolios. Software specialists and industrial control manufacturers occupy distinct tier positions based on integration depth with grid operator systems. Three archetypes dominate: building automation incumbents leveraging HVAC control infrastructure, pure-play aggregation software vendors, and diversified industrial electrification conglomerates. M&A activity concentrates on acquiring cloud-based dispatch platforms, while strategic partnerships focus on utility channel access for behind-the-meter storage convergence.
Within the building automation tier, Siemens and Schneider Electric anchor positions through integrated energy management systems that bridge grid operator signals with on-site asset control. AutoGrid Systems exemplifies the pure-play software archetype, specializing in platforms that enable utilities to dispatch distributed energy resources at scale. Honeywell International Inc. occupies a position spanning both building controls and industrial process automation, serving commercial and manufacturing flexibility programs across multiple geographies.
| Leading Market Players |
|---|
| Eaton |
| Siemens |
| Honeywell International Inc. |
| Enel X |
| Oracle |
| General Electric |
| Schneider Electric |
| AutoGrid Systems |
| ABB |
| Others |
Supply Flow & Price Mechanics
FERC Order 2222 compliance certification gates both qualified supply and premium-tier pricing access for demand response aggregators bidding into wholesale capacity markets. Utilities and grid operators restrict procurement to vendors meeting cybersecurity and interoperability standards, concentrating pricing power among certified platform providers while excluding uncertified competitors from high-margin ancillary service contracts.
Pricing Analysis
Value-based pricing anchored to megawatt-hour curtailment outcomes dominates demand response contracting, with aggregators earning performance premiums for sub-second frequency regulation response times versus standard peak reduction services. Price differentiation separates IEC 62443-certified platforms from uncertified alternatives, while volume scale and geographic concentration of load portfolios determine contract rates. Pricing pressure stems from software commoditization in building management system integrations, compressing margins for hardware-dependent vendors. Commercial real estate operators exhibit highest price sensitivity, whereas industrial facilities with interruptible process loads accept premium rates for guaranteed dispatch priority.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan coordinate hub-and-spoke deployment of demand response control hardware and software licenses to aggregator networks and utility clients. Component sourcing draws from Taiwanese semiconductor foundries for edge computing devices, South Korean battery manufacturers for behind-the-meter storage integration, and domestic software development centers for cloud-based dispatch platforms. Supply chain risk centers on single-source vulnerability in proprietary communication protocol chips that lock building automation systems to specific vendor ecosystems. Distribution runs through direct utility channel partnerships and energy service company intermediaries serving commercial and industrial end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified cybersecurity engineering capacity constrains qualified vendor supply, propping pricing for FERC-compliant aggregation platforms as grid operators extend procurement mandates. This bottleneck sustains premium-tier margins while limiting market entry for uncertified competitors.
For Market Incumbents: Anchor defensive positioning through backward integration into edge computing hardware and captive certification pipelines that accelerate IEC 62443 compliance timelines. Acquire cloud-native dispatch platforms to neutralize pure-play software entrants threatening utility channel relationships. Siemens and Schneider Electric leverage building automation installed bases to lock out competitors via proprietary API ecosystems. For New Entrants and Emerging Players: Capture white-space in India's state-level regulatory pilots across Maharashtra and Gujarat, where wholesale market reforms lack established aggregator incumbents. Target industrial cold storage and water pumping operations in Texas and California with fast-ramp flexibility profiles that qualify for premium frequency regulation payments. Pursue energy-as-a-service contracting models that eliminate capital barriers for building owners. For Investors and Strategic Acquirers: FERC Order 2222 implementation acceleration across additional regional transmission organizations is the leading indicator that platform consolidation will intensify, favoring vendors with multi-ISO certification coverage. Long-term viability rests on software recurring revenue models displacing hardware-dependent economics. Acquisition targets should demonstrate METI-certified flexibility tender participation or Bundesnetzagentur-approved capacity market access as proof of regulatory navigation capability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates building automation and grid-edge control into unified software stacks displacing point solutions. |
| Acquisition of Specialist Firm | Captures cloud-native dispatch capabilities and utility channel relationships from pure-play aggregation vendors. |
| Strategic Partnership | Secures behind-the-meter battery convergence through alliances with energy storage system manufacturers. |
| Geographic Expansion | Establishes early-aggregator positioning in India's Maharashtra and Gujarat state-level regulatory pilots. |
| Green Certification Program | Aligns demand response portfolios with EU Green Deal flexibility procurement mandates across member states. |
Methodological Framework
Regulatory filings from FERC, EMA national implementations, and METI flexibility tender documentation formed the secondary backbone validating market size and participation rule evolution. Primary interviews with utility demand-side management officers, aggregator platform engineers, commercial real estate energy managers, and industrial facility controls specialists informed operational constraints and procurement timelines. Bottom-up triangulation across individual ISO/RTO market participation data and top-down validation through national electricity market reform announcements anchored forecast construction.
Bottom-up modeling of aggregator revenue pools by service type, technology deployment, and end-user segment across the projection horizon generated volume and value estimates. Segmentation dimensions encompassed response speed tiers, software integration depth, building automation vintage, and regional regulatory framework maturity. CAGRs were derived from utility procurement trajectory analysis and renewable penetration curves shaping flexibility demand. Forecast inputs incorporated FERC Order 2222 implementation pace and EU Electricity Market Directive national transposition schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to wholesale market reform delays, cybersecurity certification timeline extensions, and renewable penetration volatility altering flexibility value curves. Outputs reflect documented assumptions around regulatory implementation schedules and technology adoption S-curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Smart Demand Response Market
Smart Grid
Smart Water Grid Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Asia-Pacific Demand Response Management Systems Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
Smart Microgrid Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
India Smart Grid Network Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
South and Central America Smart Grid Market