
 Power Grid Market | 2026-2036
Power Grid Market Size, Share, and Industry Trends Forecast 2026-2036
Power Grid Market Analysis
Aftermarket service revenue is rewriting profit dynamics across the power grid value chain. GE Vernova leverages its digital twin platform to capture recurring service contracts on installed turbine and transformer bases. Siemens anchors its position through in-house production of high-voltage switchgear and grid automation software. Schneider Electric differentiates via integrated energy management systems that span consulting through maintenance services.
Power grids comprise interconnected generation, transmission, and distribution infrastructure operating at voltages from 110V residential levels to 765kV ultra-high-voltage transmission corridors, designed to deliver electricity with frequency stability typically within 0.5Hz tolerance. Smart Grids represent the fastest-expanding technology segment as utilities deploy advanced metering infrastructure and real-time grid automation. Energy Storage solutions within the Solution category command premium margins where grid operators require lithium-ion and flow battery systems for frequency regulation and peak shaving. Installation Services remain the most labor-intensive service type, with specialized field crews from Quanta Services and regional contractors commanding scarcity premiums in remote or hazardous terrain.
FERC Order 2222 in the United States mandates grid operators to accommodate distributed energy resources, directly expanding addressable market scope for aggregators and storage developers. The EU Green Deal and associated CSRD disclosure requirements force European utilities to document grid decarbonization pathways, redirecting capital toward renewable integration and away from fossil-fuel peaking plants. China's MIIT enforces GB standards for grid-connected battery energy storage systems, creating compliance barriers for non-domestic suppliers. Stakeholders must weigh regulatory compliance costs against the structural advantage of early certification in markets where standards are tightening faster than equipment replacement cycles.
Market Dynamics
Smart grid infrastructure is hybridizing legacy electromechanical systems with digital control layers, forcing utilities to reconfigure capital deployment timelines and vendor relationships across transmission and distribution networks.
Growth Catalysts
- FERC Order 2222:The US mandate requires grid operators to integrate distributed energy resources, expanding market access for battery aggregators and virtual power plant operators.
- EU F-Gas Regulation:Phasedown of sulfur hexafluoride in high-voltage switchgear is accelerating demand for gas-insulated alternatives and vacuum interrupter technologies.
- India's industrial corridors:Manufacturing clusters in Gujarat and Tamil Nadu are driving concentrated demand for dedicated 132kV and 220kV substations with integrated SCADA systems.
Market Restraints
- Copper and aluminum price volatility:Conductor materials constitute 15-25% of transmission line costs, exposing project returns to commodity swings on the London Metal Exchange.
- Transformer core steel concentration:Grain-oriented electrical steel production centers on Japan, South Korea, and China, creating supply vulnerability for non-Asian grid OEMs.
- Permitting timelines for overhead lines:Right-of-way acquisition and environmental review processes stretch 5-8 years in Germany and parts of the US Northeast, delaying capacity additions.
Strategic Opportunities
- Vietnam and Indonesia distribution networks:Electrification rates below 100% in rural provinces create first-mover advantage for turnkey substation providers with local assembly partnerships.
- Grid-edge AI convergence:Machine learning models deployed on substation edge devices are enabling predictive load forecasting that reduces spinning reserve requirements.
- US IRA manufacturing tax credits:Domestic content bonuses for transformers and switchgear are reshaping supplier location decisions toward Ohio, Texas, and South Carolina.
Industry Challenges
- Protection relay programming expertise:Utilities face shortages of engineers fluent in IEC 61850 GOOSE messaging and digital twin configuration for substation automation.
- Cybersecurity certification lag:NERC CIP compliance timelines for bulk electric system assets often exceed vendor software release cycles, creating patch management gaps.
- Interconnection queue backlogs:ISOs and RTOs in California, Texas, and the Mid-Atlantic hold 2,000+ GW of generation and storage projects awaiting grid impact studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Grid Market |
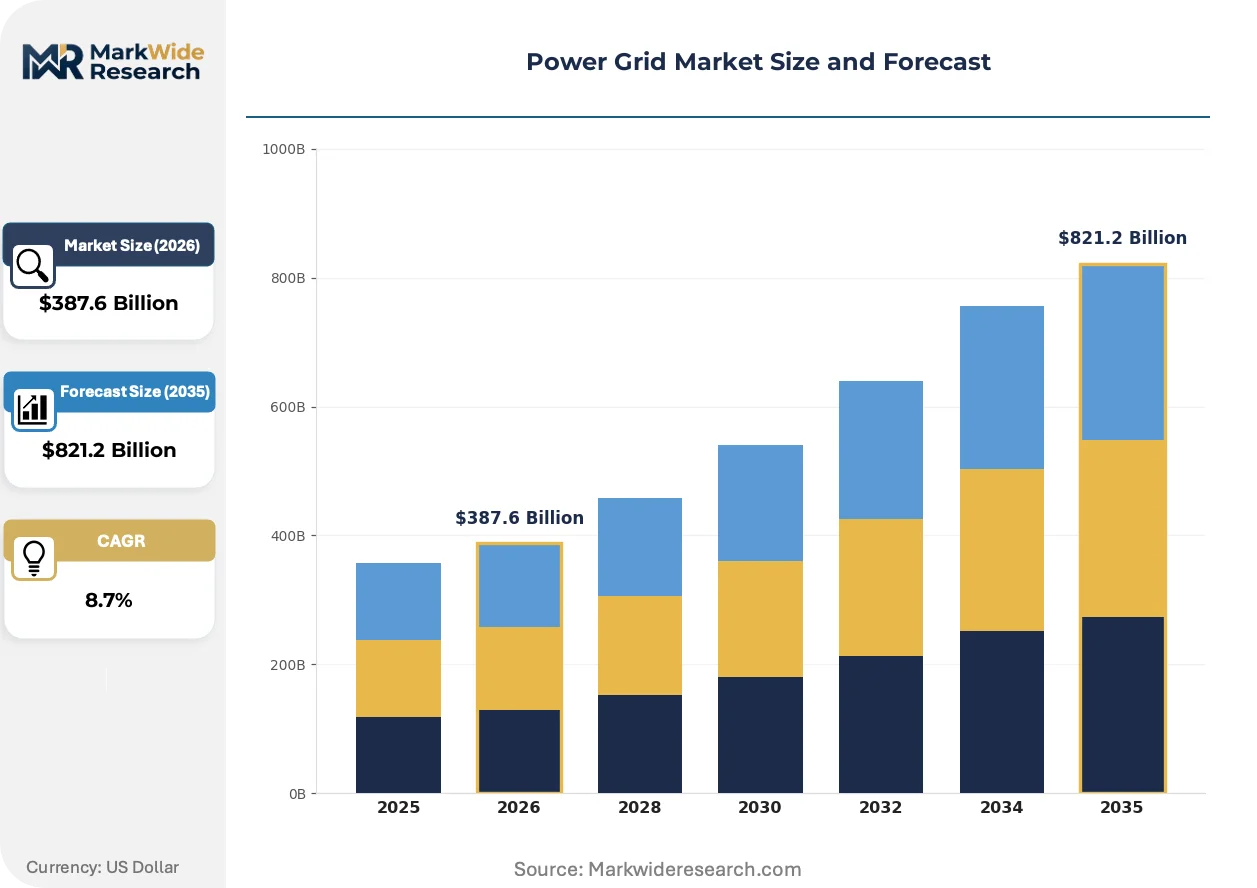
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Grids, Renewable Integration, Transmission Networks, Energy Management Systems Service Type: Maintenance Services, Consulting Services, Installation Services, Upgrades End User: Utilities, Industrial Users, Residential Consumers, Commercial Establishments Solution: Grid Automation, Demand Response, Distributed Generation, Energy Storage |
| Companies Covered | GE Vernova, Schneider Electric, Siemens, Hubbell, Quanta Services, Eaton, National Grid, NextEra Energy, Powergrid Corporation of India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Grid Market Emerging Trajectories
Digital twin technology is compressing commissioning cycles and reshaping service revenue models across transmission and distribution asset classes. Three developments are restructuring competitive positioning.
Solid-state transformers are hybridizing power electronics with conventional magnetic cores to enable bidirectional power flow and voltage regulation in real time. Data center operators in Northern Virginia and Frankfurt are piloting 1MVA units for direct medium-voltage feed to IT loads. This technology is hybridizing the boundaries between transmission infrastructure and power quality equipment, opening new vendor entry points.
The EU CSRD disclosure framework mandates granular reporting of grid decarbonization capital expenditure and Scope 3 emissions from purchased equipment. European TSOs must now document SF6 leakage rates and copper sourcing traceability in annual sustainability statements. German and French utilities are responding by embedding lifecycle carbon metrics into transformer and cable procurement specifications.
Utility procurement of grid hardware is fragmenting from bundled EPC contracts toward component-level sourcing with separate systems integration responsibility. State-owned distributors in Brazil and Saudi Arabia now issue distinct tenders for GIS switchgear, protection relays, and SCADA platforms. This pattern is most pronounced in markets where national development banks finance infrastructure through multiple-tranche disbursements tied to construction milestones.
Power Grid Market Segmentation
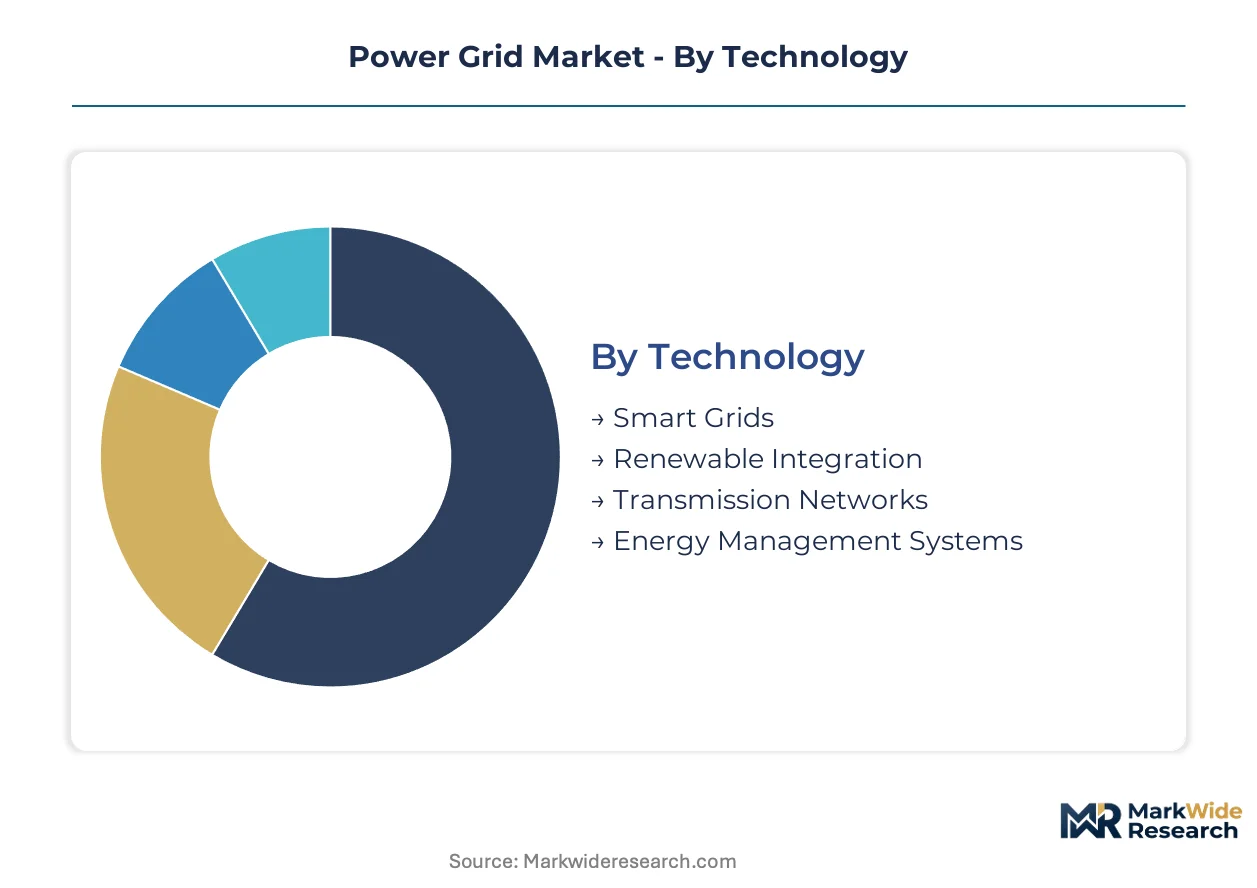
Segmentation in the power grid sector reveals how capital allocation priorities diverge across technology maturity curves and service intensity levels. Understanding these divides helps vendors align R&D pipelines with procurement patterns that utilities display across transmission, distribution, and grid-edge domains.
Technology:
Mature infrastructure categories coexist with emerging digital layers, creating divergent investment timelines and vendor qualification requirements across utility procurement teams.
- Smart Grids:Advanced metering infrastructure and real-time automation systems overlay legacy electromechanical assets. Demand concentrates in India's urban distribution networks where utilities deploy AMI to reduce aggregate technical and commercial losses below 15%.
- Renewable Integration:Grid-forming inverters and synchronous condensers stabilize variable generation from wind and solar farms. Procurement accelerates in Germany and Spain where TSOs must accommodate 80%+ renewable penetration targets.
- Transmission Networks:Ultra-high-voltage corridors and HVAC/HVDC interconnections move bulk power across regional balancing authorities.
- Energy Management Systems:SCADA and advanced distribution management platforms optimize dispatch and outage response.
Transmission Networks handles the majority of throughput; Smart Grids is climbing the fastest on share as distribution operators digitize legacy infrastructure.
Service Type:
Cost tier differentiation separates labor-intensive field execution from knowledge-based advisory work, with margin structures varying by crew specialization and equipment vintage.
- Installation Services:Specialized field crews erect substations, string conductors, and commission protection systems across voltages from 11kV distribution to 765kV transmission. Scarcity premiums apply in remote terrain where Quanta Services and regional contractors face limited competition.
- Maintenance Services:Predictive analytics and drone-based thermography extend asset life for transformers and switchgear. Recurring contracts dominate in the US Northeast where NERC CIP compliance mandates continuous monitoring of bulk electric system assets.
- Consulting Services:Grid planning, interconnection studies, and regulatory strategy support utility capital programs.
- Upgrades:Retrofit programs modernize protection relays and control systems without greenfield construction.
Installation Services absorbs the largest share of labor spend; Maintenance Services is expanding most quickly as utilities shift from reactive to condition-based asset management.
End User:
Customer type determines voltage level, reliability requirements, and procurement sophistication, with industrial accounts driving premium specifications.
- Utilities:Vertically integrated and unbundled grid operators own transmission and distribution infrastructure subject to rate-base regulation. Investment cycles align with FERC Order 1000 transmission planning in the US and EU Ten-Year Network Development Plan cycles.
- Industrial Users:Data centers, semiconductor fabs, and steel mills demand dedicated substations with power quality guarantees. Load growth in Northern Virginia and Arizona Phoenix corridors is forcing expedited interconnection timelines.
- Residential Consumers:Distributed solar and EV charging create bidirectional power flows at the grid edge.
- Commercial Establishments:Retail and office complexes procure behind-the-meter storage and microgrids for resilience.
Utilities command the dominant share of equipment procurement; Industrial Users is gaining share fastest as manufacturing reshoring drives concentrated load growth.
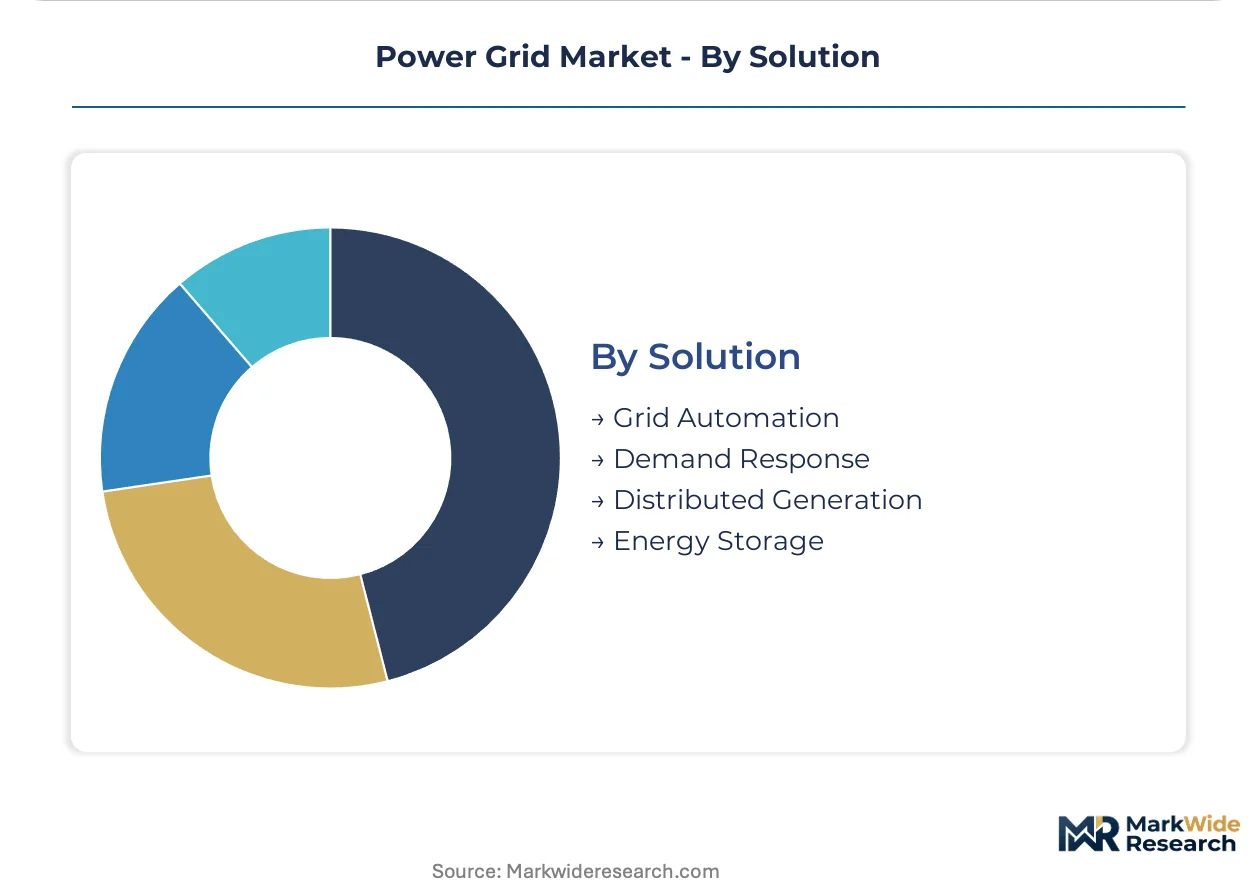
Solution:
Application focus separates hardware-centric automation from software-driven optimization, with integration complexity rising at the grid edge.
- Energy Storage:Lithium-ion and flow battery systems provide frequency regulation, peak shaving, and black-start capability. Premium margins attach to grid-scale deployments in California and Texas where ISO markets compensate fast-ramping resources.
- Grid Automation:Digital substations with IEC 61850 protocol stacks enable remote operation and reduced maintenance intervals. Adoption accelerates in China's coastal provinces where State Grid targets full automation of 110kV+ substations.
- Demand Response:Aggregated load curtailment and price-responsive demand shift consumption patterns.
- Distributed Generation:Rooftop solar, small-scale wind, and gas-fired microturbines reduce reliance on centralized supply.
Grid Automation represents the largest installed base; Energy Storage is expanding most steeply as battery costs decline and market mechanisms mature for ancillary services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Vietnam exhibit the highest price elasticity, squeezing margins on standardized equipment, while US and German utilities absorb premiums for digital-ready infrastructure and compliance-certified hardware.
United States
FERC Order 2222 mandates distributed energy resource integration, expanding procurement scope for battery aggregators and virtual power plant operators. The Inflation Reduction Act channels manufacturing tax credits toward domestic transformer and switchgear production. Northern Virginia data center clusters are driving expedited 500kV substation timelines to match hyperscale load growth.
Germany
The EU F-Gas Regulation phases down sulfur hexafluoride in high-voltage switchgear, accelerating vacuum interrupter and clean air-insulated alternative adoption. CSRD disclosure requirements force granular reporting of grid decarbonization capital expenditure and Scope 3 emissions. Industrial load centers in North Rhine-Westphalia are procuring synchronous condensers to stabilize renewable-heavy regional grids.
China
MIIT-enforced GB standards for grid-connected battery energy storage systems create compliance barriers for non-domestic suppliers while favoring domestic integrators. State Grid targets full automation of 110kV+ substations across coastal provinces. Yangtze River Delta manufacturing hubs are deploying ultra-high-voltage DC corridors to transmit western hydro and solar eastward.
India
CEA mandates and PLI scheme incentives accelerate smart metering and renewable integration investments across state distribution companies. Industrial corridors in Gujarat and Tamil Nadu are driving concentrated demand for dedicated 132kV and 220kV substations with integrated SCADA systems. Aggregate technical and commercial loss reduction targets below 15% are forcing urban distribution digitization in Maharashtra and Karnataka.
Brazil
National development bank financing through multiple-tranche disbursements is fragmenting procurement from bundled EPC contracts toward component-level sourcing. ANEEL regulatory frameworks govern transmission concession renewals and tariff reviews. São Paulo and Minas Gerais industrial zones are expanding dedicated substation capacity to serve reshoring manufacturing investments.
Power Grid Market Vendor Landscape
Integrated conglomerates and specialized service providers split the market along the fault line of capital intensity versus labor intensity. Vertically integrated electrical equipment manufacturers capture margin through in-house production of high-voltage switchgear, transformers, and grid automation software. Specialized field service contractors command scarcity premiums in remote terrain and complex commissioning environments. Dominant competitive moves include geographic expansion through local assembly partnerships and technology licensing agreements for digital twin and edge AI platforms.
Within the integrated equipment tier, GE Vernova, Siemens, and Schneider Electric exemplify divergent strategic positioning. GE Vernova anchors the digital services archetype through recurring revenue models tied to installed turbine and transformer bases. Siemens occupies the hardware-automation hybrid position with captive production of switchgear and protocol-compliant protection systems. Schneider Electric sits within the integrated energy management segment spanning consulting through maintenance service contracts. Hubbell and Eaton represent the component-specialist archetype, while Quanta Services exemplifies the labor-scarcity premium model in installation and commissioning execution.
| Leading Market Players |
|---|
| GE Vernova |
| Schneider Electric |
| Siemens |
| Hubbell |
| Quanta Services |
| Eaton |
| National Grid |
| NextEra Energy |
| Powergrid Corporation of India |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor carries grain-oriented electrical steel from Shanghai ports to transformer factories in Jiangsu and Zhejiang, with container rates fluctuating in tandem with spot prices for copper and aluminum on the London Metal Exchange. This logistics-cost volatility amplifies the pricing power held by Japanese and South Korean steel producers while forcing grid OEMs to pass through material surcharges to utilities in Germany and the United States.
Pricing Analysis
Aftermarket service contracts spanning predictive maintenance and digital twin subscriptions now capture lifetime value exceeding original equipment sales for major turbine and transformer installations. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61850-certified digital substations from legacy electromechanical gear and basic distribution hardware. Cost compression in the economy tier is intensifying because Indian state utilities consolidate procurement through bulk tenders with 15% technical-commercial loss targets. Industrial users in Northern Virginia and Arizona Phoenix corridors show least price sensitivity, absorbing premiums for guaranteed power quality and expedited interconnection timelines.
Supply Chain Analysis
Contract manufacturing for power electronics and protection relay assemblies concentrates among Flex, Jabil, and regional EMS providers in Mexico and Eastern Europe serving North American and EU grid OEMs. Grain-oriented electrical steel production centers on Japan, South Korea, and China, while copper cathode refining feeds from Chile and Peru smelters. Single-source vulnerability in transformer core steel creates procurement risk for European and North American transformer builders. Distribution runs through bundled EPC contractors in Brazil and Saudi Arabia, component-level sourcing in Germany and India, and direct utility procurement in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power grid market sits in early-stage cyclical recovery driven by manufacturing reshoring and data center load growth forcing accelerated interconnection investments across multiple geographies.
For Market Incumbents: Insulate installed-base revenue through captive digital twin platforms and recurring service contracts tied to transformer and turbine fleets. Backward integration into high-voltage switchgear production reduces exposure to SF6 phase-down regulatory shifts in Europe. Channel control through exclusive field service partnerships with Quanta Services and regional contractors protects margin in remote terrain installation markets. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia rural distribution networks where electrification gaps below 100% create first-mover advantage for turnkey substation providers with local assembly partnerships. Grid-edge AI for predictive load forecasting represents the most penetrable application segment, with machine learning models deployed on substation edge devices reducing spinning reserve requirements for utilities. Go-to-market through licensing agreements with State Grid and regional distributors accelerates technology adoption without greenfield manufacturing investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized field service contractors with scarcity premiums in complex commissioning environments and cybersecurity-certified automation software vendors. Long-term viability rests on structural underinvestment in transmission infrastructure across developed markets and renewable integration mandates tightening faster than equipment replacement cycles. Watch interconnection queue clearance rates at California and Texas ISOs as the signal indicating whether capital deployment timelines compress or extend.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | GE Vernova and Siemens capture recurring service revenue on installed turbine and transformer bases. |
| SF6-Free Switchgear Transition | Vacuum interrupter and clean air-insulated alternatives gain share under EU F-Gas Regulation phase-down mandates. |
| Domestic Content Manufacturing | US IRA tax credits reshape supplier location decisions toward Ohio, Texas, and South Carolina transformer plants. |
| Grid-Edge AI Integration | Machine learning models on substation devices reduce spinning reserve requirements for ISO market participants. |
| Local Assembly Partnerships | Turnkey providers in Vietnam and Indonesia secure first-mover advantage in rural electrification expansion zones. |
Methodological Framework
Cross-validation between utility capital expenditure disclosures and equipment vendor order backlogs anchors the qualitative findings on procurement cycle timing and technology adoption rates. Primary interviews with utility planning officers, EPC project managers, grid automation engineers, and aftermarket service directors combined with secondary validation from FERC filings, EIA generation capacity data, IEA grid investment reports, and national regulator infrastructure databases. Bottom-up project pipeline analysis and top-down macroeconomic scenario modeling triangulate volume estimates across the analysis window.
Calibration against historical transmission and distribution spending patterns, renewable interconnection queue data, and smart meter deployment trajectories shaped the analytical framework. Segmentation dimensions modeled include technology maturity curve position, service intensity level, end-user voltage tier, and regional regulatory framework cluster. CAGRs were derived from regression analysis of capital deployment trends correlated with manufacturing reshoring indices and data center load growth forecasts, with inputs from commodity price scenarios for copper and electrical steel.
Stress conditions across copper and aluminum price volatility, transformer core steel supply disruption, and permitting timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on policy continuity for FERC Order 2222, EU Green Deal implementation, and IRA manufacturing credit availability. Quarterly review of interconnection queue clearance rates, ISO capacity market clearing prices, and raw material futures curves is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Microgrid Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
Smart Demand Response Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
India Smart Grid Network Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Smart Grid Market
Smart Grid
Microgrid Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
Demand Response Market
Smart Grid
Europe Smart Grid Security Market