
 United Kingdom Smart Grid Market | 2026-2036
United Kingdom Smart Grid Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Smart Grid Market Analytics
Power systems engineering talent is rotating from conventional generation toward distributed energy resource integration, tightening labor pools for legacy grid operators. National Grid plc leverages its transmission monopoly to anchor large-scale smart substation rollouts across England and Wales. Schneider Electric SE competes through deep specialization in demand response software platforms serving UK utility clients. Siemens AG dominates the digital twin segment for predictive grid asset management, extending its European industrial automation heritage into British distribution networks.
A smart grid deploys two-way digital communication, advanced sensing, and automated control across electricity generation, transmission, and distribution infrastructure to balance supply and demand in real time. The system integrates phasor measurement units operating at sub-second sampling intervals with SCADA overlays to detect faults before cascading failures propagate. Advanced Metering Infrastructure leads technology deployment as Ofgem mandates mass smart meter installation under the Retail Energy Code. Demand Response System represents the fastest-growing technology segment where industrial off-takers monetize load flexibility through the Balancing Mechanism. Smart Meters anchor product type volumes while Communication Networks capture expanding margin pools as 5G and fiber backhaul replace aging cellular links for substation connectivity.
Ofgem enforces the RIIO-ED2 price control framework, compelling distribution network operators to publish digitalization investment plans and deliver measurable network loss reductions. BEIS and the National Infrastructure Commission coordinate long-term grid modernization standards that shape procurement specifications for flexibility services and storage interconnection. The Electricity System Operator transition to independent operation under government legislation reconfigures market governance for distributed resource participation. Stakeholders must monitor how forthcoming capacity market reforms and carbon border adjustments reshape investment signals for grid-edge intelligence versus central transmission upgrades.
Market Dynamics
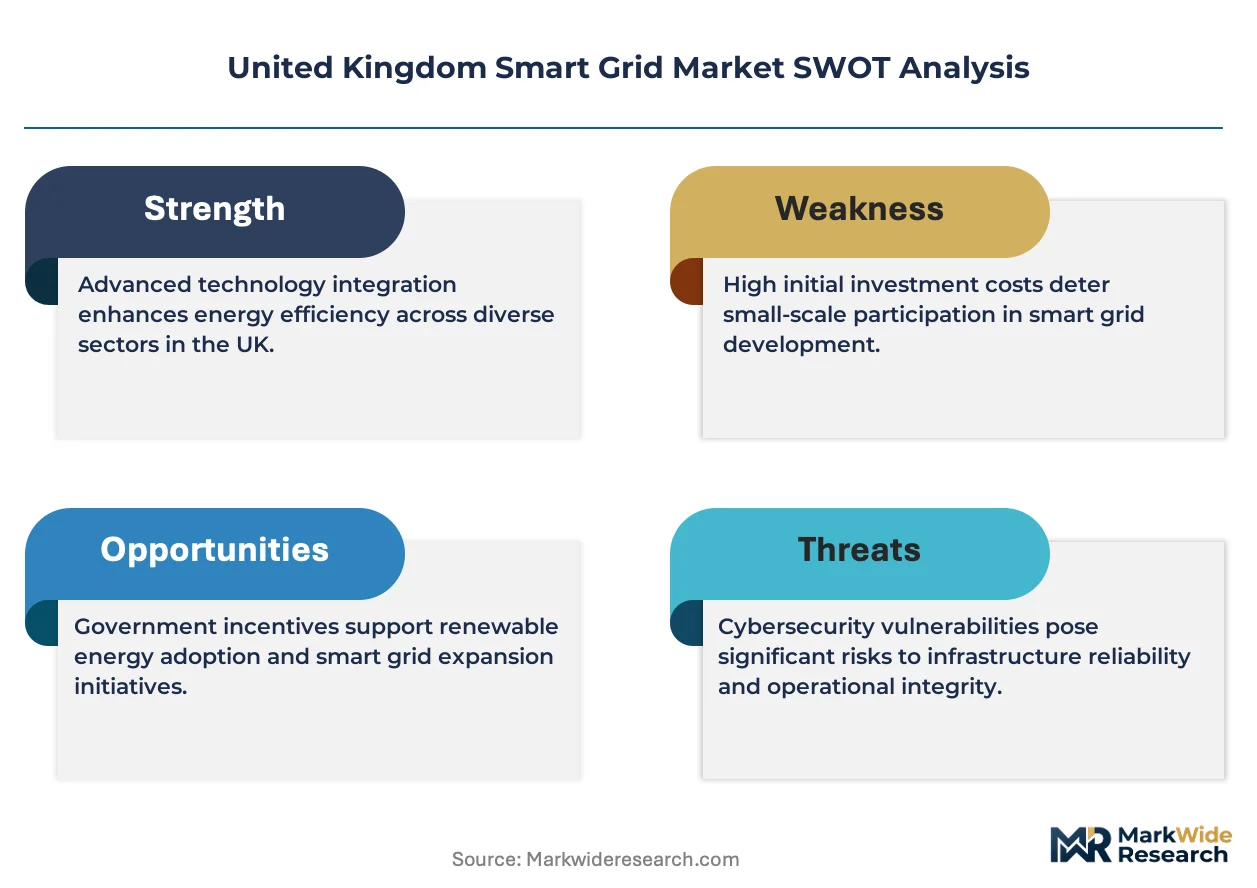
Ofgem's RIIO-ED2 price control framework is forcing distribution network operators to accelerate digitalization investments while delivering measurable loss reductions, compressing procurement timelines for flexibility services and intelligent substation hardware across England, Scotland, and Wales.
Growth Catalysts
- Balancing Mechanism Reform:The Electricity System Operator's transition to independent operation under UK government legislation is reconfiguring market access rules for distributed energy resource aggregators and demand response providers.
- Smart Meter Mandate:Ofgem's enforcement of the Retail Energy Code drives mass Advanced Metering Infrastructure deployment, creating guaranteed demand for communication modules and data management platforms.
- Urban Corridor Load Concentration:Aging substation infrastructure across England's Manchester-to-London corridor requires intelligent monitoring upgrades to manage electrification-driven peak demand growth.
Market Restraints
- Copper and Rare Earth Input Volatility:Power transformer and inverter manufacturing depends on copper pricing and neodymium supply concentration, exposing project developers to commodity-driven margin compression.
- Cellular Backhaul Obsolescence:Aging 2G and 3G networks for substation communication create stranded asset risk as mobile operators sunset legacy spectrum bands before fiber and 5G coverage reach rural Scotland and Wales.
- Interconnection Queue Congestion:Grid connection delays for battery storage and distributed generation projects extend payback periods, dampening investor appetite for grid-edge intelligence deployment.
Strategic Opportunities
- Welsh and Scottish Rural Electrification:Underpenetrated distribution automation in remote networks offers first-mover advantage for fault location isolation and service restoration technology providers.
- Digital Twin Convergence:Integration of physics-based modeling with real-time sensor streams enables predictive asset management for transmission infrastructure, opening software subscription revenue pools.
- Capacity Market Reconfiguration:Forthcoming reforms to the UK's capacity remuneration mechanism may recognize demand-side response and storage as firm capacity, improving project financeability for flexibility investors.
Industry Challenges
- Power Systems Engineering Talent Scarcity:Labor pools for legacy grid protection and control systems are tightening as technical talent rotates toward distributed energy resource integration and software-defined platforms.
- Multi-Vendor System Integration Complexity:SCADA overlays must interoperate with proprietary protocols from incumbent equipment suppliers, extending commissioning timelines and inflating systems integration costs for network operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Smart Grid Market |
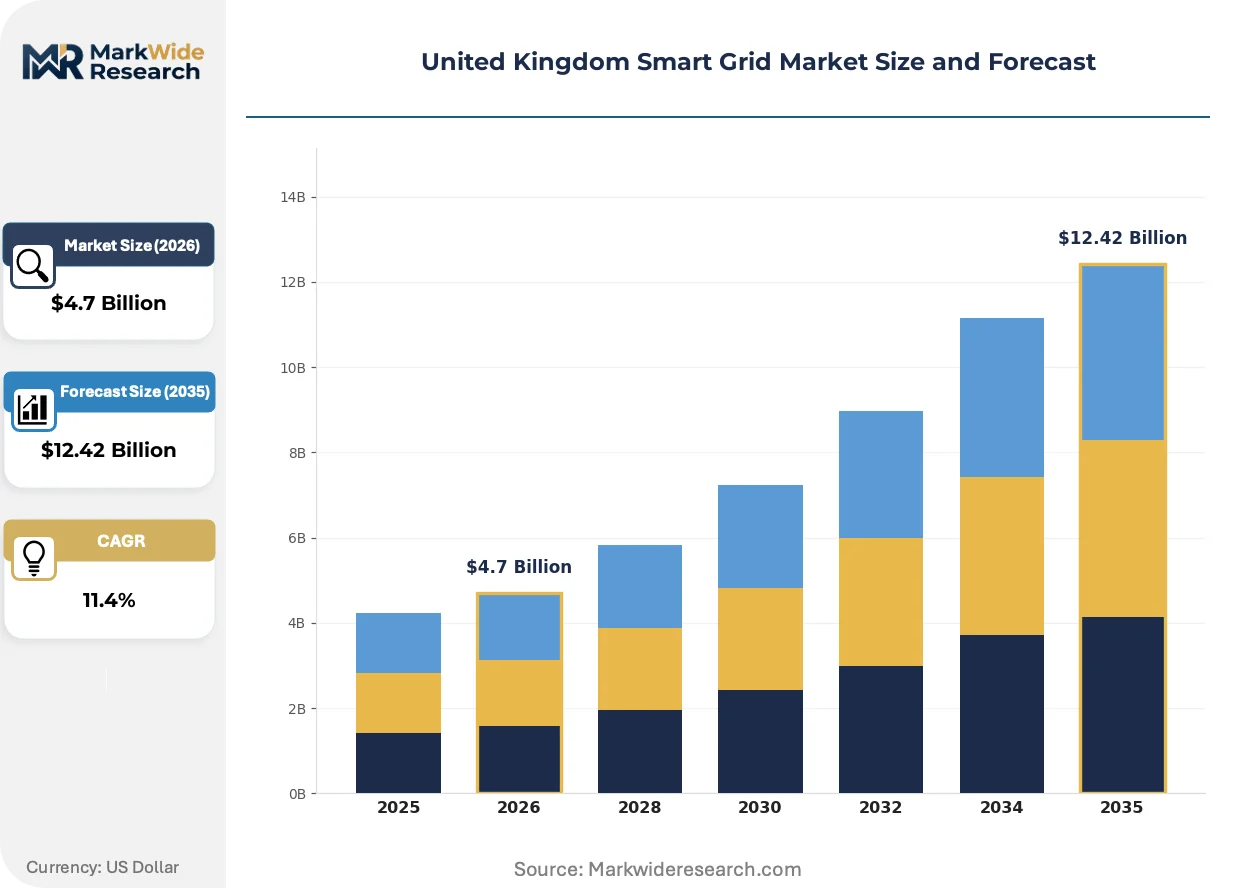
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Distribution Management System, Demand Response System, Energy Management System Application: Residential, Commercial, Industrial, Utility Product Type: Smart Meters, Smart Sensors, Communication Networks, Control Systems End User: Utilities, Energy Providers, Government, Consumers |
| Companies Covered | National Grid plc, Schneider Electric SE, Siemens AG, ABB Ltd., General Electric Company, EDF Energy, E.ON SE, SSE PLC, Itron, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Smart Grid Market Evolving Landscape
Digital sensing and control technologies are compressing fault detection intervals from seconds to milliseconds while policy frameworks restructure compensation for grid-edge flexibility services. Procurement patterns favor integrated platform providers over point-solution vendors.
Phasor measurement unit technology is miniaturizing from rack-mounted substation installations to pole-top distribution sensors. Distribution network operators in England's urban corridor are deploying these compact units at tenfold density compared to traditional installations. The technology is miniaturizing protection and control hardware costs while enabling sub-cycle fault detection that prevents cascading outages.
Ofgem's RIIO-ED2 output delivery incentives now explicitly reward network loss reduction and customer interruption frequency improvement. Distribution network operators must publish digitalization investment plans with measurable targets, reshaping procurement specifications toward intelligent monitoring and automated switching. The regulation most affects England's urban distribution networks where aging infrastructure and load growth create the widest performance gaps.
Industrial off-takers are monetizing load flexibility directly through the Balancing Mechanism rather than via third-party aggregators. Large manufacturing facilities in the Midlands and North West are installing behind-the-meter control systems that bypass traditional demand response service providers. This disintermediation concentrates in energy-intensive sectors where half-hourly meter data and half-hourly settlement enable direct bidding into system operator markets.
United Kingdom Smart Grid Market Segmentation
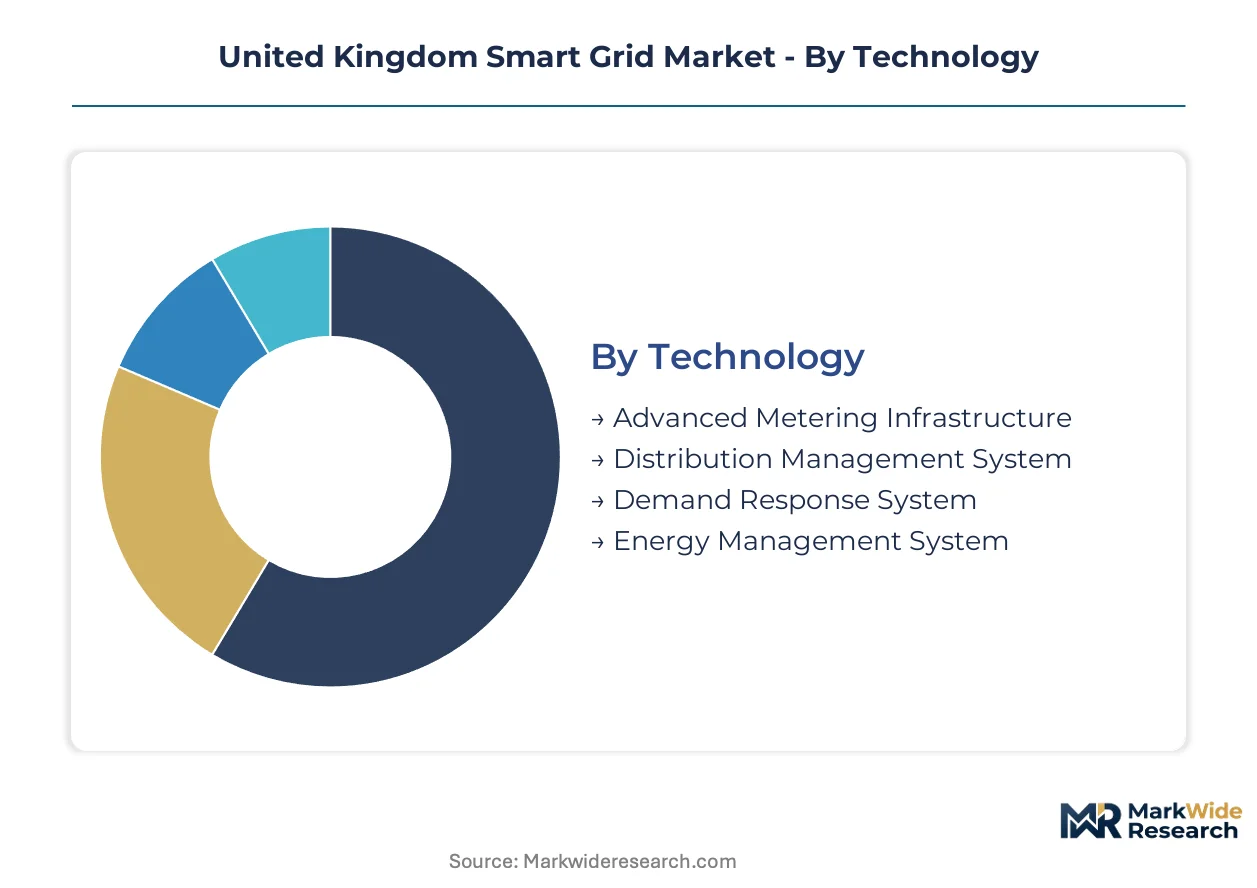
Smart grid procurement patterns diverge sharply across technology maturity curves and end-user sophistication levels. Ofgem's RIIO-ED2 incentives reshape how distribution network operators prioritize segments against measurable loss reduction targets.
Technology:
Ofgem's Retail Energy Code and Balancing Mechanism reforms create divergent compliance pressures across technology categories, with mandated deployment timelines compressing procurement for some segments while market-based mechanisms accelerate others.
- Advanced Metering Infrastructure:Mass smart meter rollout mandated under the Retail Energy Code drives guaranteed hardware volumes across England, Scotland, and Wales. Distribution network operators in England's urban corridor prioritize AMI deployment to meet Ofgem's 2025 coverage targets while managing legacy cellular backhaul obsolescence risks.
- Demand Response System:Software platforms enabling industrial load flexibility bidding into the Balancing Mechanism are expanding most quickly as large Midlands manufacturers install behind-the-meter control systems. Direct market access disintermediates traditional aggregators, concentrating demand among energy-intensive sectors with half-hourly settlement capabilities.
- Distribution Management System:SCADA overlays with fault location and service restoration capabilities anchor digitalization investments for rural Welsh and Scottish networks.
- Energy Management System:Grid-edge optimization platforms integrate distributed generation forecasting with battery storage dispatch schedules.
Established volume favors Advanced Metering Infrastructure; emerging adoption favors Demand Response System.
Application:
Load concentration patterns across England's Manchester-to-London corridor determine application-tier investment intensity, with electrification-driven peak demand growth widening performance gaps in dense urban substations.
- Industrial:Large manufacturing facilities in the Midlands and North West monetize half-hourly flexibility directly through the Balancing Mechanism, bypassing third-party demand response providers. Energy-intensive sectors with advanced metering infrastructure capture premium compensation rates for fast-frequency response services.
- Utility:Distribution network operators under RIIO-ED2 output delivery incentives deploy intelligent monitoring across aging substation infrastructure to reduce customer interruption frequency. England's urban networks absorb disproportionate capital allocation against measurable loss reduction targets.
- Residential:Mass smart meter installation creates data management platform demand while time-of-use tariff structures remain underpenetrated.
- Commercial:Mid-sized load aggregation through third-party providers dominates flexibility participation where direct Balancing Mechanism access remains uneconomical.
Utility procurement anchors near-term revenue; industrial direct market access delivers steepest expansion trajectory.
Product Type:
Hardware-software margin structures diverge across product categories, with communication infrastructure capturing expanding value pools as 5G and fiber backhaul displace stranded cellular assets.
- Communication Networks:5G and fiber backhaul deployment for substation connectivity replaces aging 2G and 3G cellular links before mobile operator spectrum sunsets strand rural Scottish and Welsh assets. Network operators prioritize resilient communication architecture to support sub-second phasor measurement unit data streams.
- Smart Meters:Mass deployment volumes mandated under Ofgem's Retail Energy Code concentrate procurement among integrated platform providers capable of end-to-end AMI ecosystem delivery. Hardware commoditization pressures favor vendors with captive data management and analytics software capabilities.
- Smart Sensors:Miniaturized pole-top phasor measurement units enable tenfold density increases over traditional rack-mounted substation installations.
- Control Systems:Automated switching and protection hardware interoperates with proprietary SCADA protocols from incumbent equipment suppliers.
Smart Meters dominate unit volumes; Communication Networks command margin expansion.
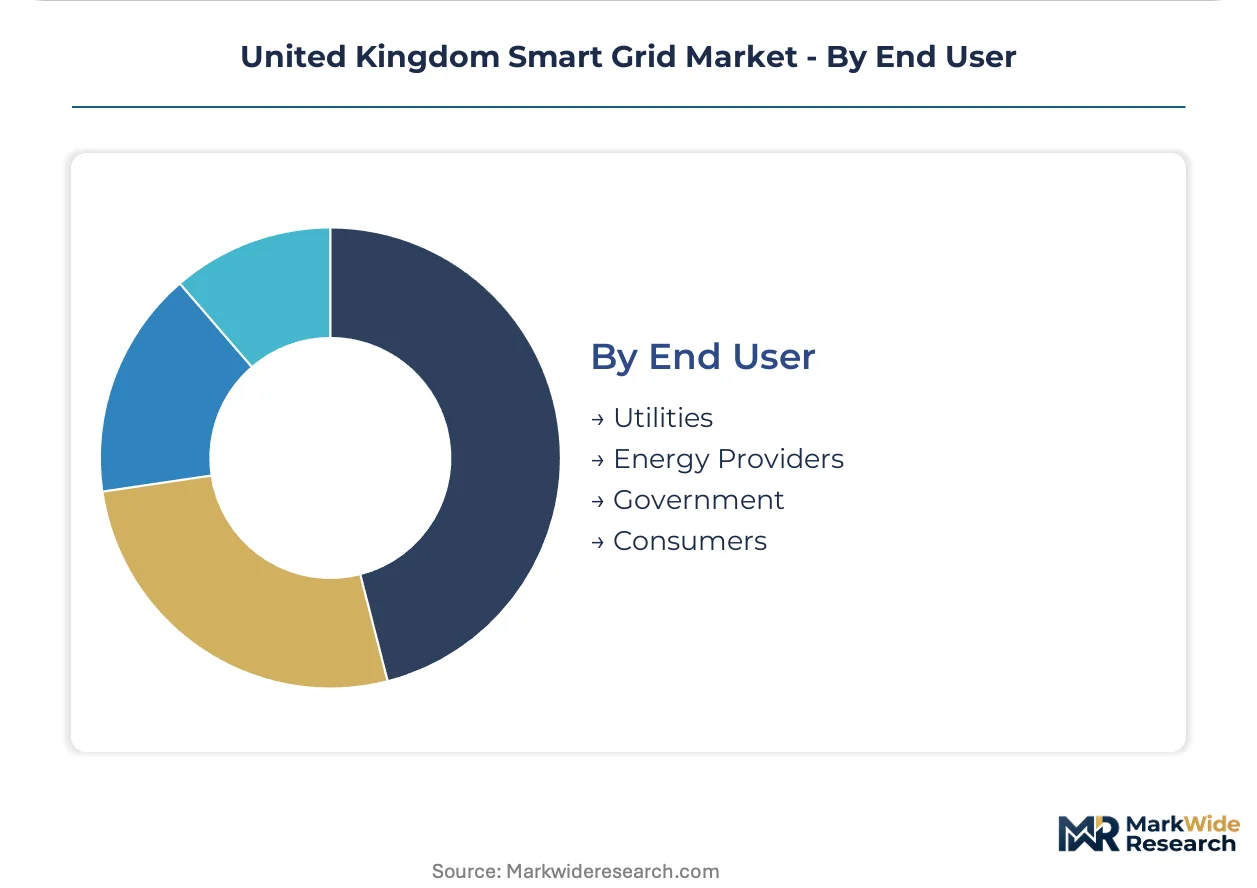
End User:
Procurement authority concentration varies across end-user categories, with government coordination of long-term grid modernization standards shaping utility and energy provider specifications.
- Utilities:Distribution network operators under Ofgem's RIIO-ED2 framework publish digitalization investment plans with explicit network loss reduction and customer interruption frequency targets. BEIS and the National Infrastructure Commission procurement specifications constrain vendor selection toward integrated flexibility service platforms.
- Government:The Electricity System Operator transition to independent operation under UK legislation reconfigures market governance, directly influencing distributed resource participation rules and capacity market design. BEIS coordinates storage interconnection standards that reshape grid-edge intelligence deployment signals.
- Energy Providers:Retail suppliers leverage smart meter data streams for demand forecasting and tariff innovation.
- Consumers:Industrial and commercial load flexibility participation grows through direct Balancing Mechanism access.
Utilities anchor procurement scale; government policy reform steers technology adoption direction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ofgem anchors England's smart grid investment through the RIIO-ED2 price control framework, compelling distribution network operators to publish measurable digitalization targets across substation infrastructure.
England
London-to-Manchester urban corridor drives concentrated demand for intelligent substation monitoring as electrification strains aging infrastructure. The Retail Energy Code mandates mass smart meter deployment with 2025 coverage deadlines pressing procurement timelines. Midlands manufacturing clusters in Birmingham and Manchester install behind-the-meter control systems to bid directly into the Balancing Mechanism.
Scotland
Remote Highland and Island networks create fault location isolation demand as sparse distribution lines extend across challenging terrain. Scottish Government energy transition programs coordinate with Ofgem to fund rural automation pilots. Glasgow and Edinburgh urban centers concentrate utility procurement for grid-edge battery storage interconnection.
Wales
Valley communities and coastal networks require resilient communication backhaul as mobile operators sunset 2G spectrum before fiber reaches rural substations. Welsh Government grid modernization funding targets distribution automation gaps in North Wales. Swansea and Cardiff industrial zones anchor demand response aggregation for steel and manufacturing load flexibility.
London and Southeast
Peak demand density in Greater London strains underground cable networks, accelerating deployment of miniaturized pole-top phasor measurement units. National Infrastructure Commission specifications for storage interconnection reshape procurement in Thames Valley data center clusters. Kent and Sussex distribution operators prioritize automated switching to reduce customer interruption frequency in dense suburban substations.
United Kingdom Smart Grid Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with transmission incumbents leveraging infrastructure monopolies against software-defined challengers. National Grid plc anchors large-scale deployment through regulated asset base advantages. Three archetypes dominate: integrated transmission utilities, European industrial automation conglomerates, and specialized demand response software vendors. Competitive moves concentrate on strategic partnerships for multi-vendor system integration and portfolio diversification into grid-edge flexibility platforms.
Within the integrated utility tier, National Grid plc occupies the dominant transmission position across England and Wales. Schneider Electric SE and Siemens AG exemplify European industrial conglomerates competing through platform breadth, with the former representing demand response specialization and the latter anchoring digital twin predictive asset management. These three companies illustrate how vendor selection increasingly favors integrated ecosystem providers over point-solution specialists under Ofgem's output delivery incentive frameworks.
| Leading Market Players |
|---|
| National Grid plc |
| Schneider Electric SE |
| Siemens AG |
| ABB Ltd. |
| General Electric Company |
| EDF Energy |
| E.ON SE |
| SSE PLC |
| Itron, Inc. |
| Others |
Value Network & Pricing Analysis
Twenty-four-week lead times for power transformers and intelligent substation hardware concentrate procurement leverage among European industrial conglomerates serving Ofgem-regulated distribution network operators, compressing margin buffers for project developers exposed to commodity volatility.
Pricing Analysis
England's urban corridor commands fifteen to twenty percent premiums over rural Scottish and Welsh deployments due to congestion-driven logistics costs and specialized labor requirements. Project-based contracting dominates, with price differentiation anchored in certification tier and volume scale. Pricing pressure stems from copper and rare earth input volatility squeezing transformer and inverter manufacturing margins. Small-scale flexibility providers exhibit highest price sensitivity, while transmission incumbents absorb cost fluctuations through regulated asset base recovery mechanisms.
Supply Chain Analysis
Germany and France anchor production of protection relays and SCADA control systems for UK distribution networks. China dominates rare earth magnet supply for inverter manufacturing, while Japan and South Korea feed semiconductor components for phasor measurement units. The supply chain draws from concentrated neodymium sourcing, creating single-source vulnerability exposure as geopolitical friction disrupts magnet flows. Distribution runs through integrated platform providers bundling hardware, software, and commissioning services under long-term service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined grid management platforms threaten hardware-centric incumbents as procurement patterns shift toward integrated ecosystem providers under Ofgem's output delivery incentive frameworks.
For Market Incumbents: Consolidate multi-vendor system integration capabilities through strategic partnerships that reduce commissioning timelines and proprietary protocol friction. Secure captive supply of copper and rare earth inputs to defend margin position against commodity-driven compression. Deepen backward integration into demand response software platforms to counter disintermediation by industrial off-takers bidding directly into the Balancing Mechanism. For New Entrants and Emerging Players: Lead with fault location isolation and service restoration technology targeting underpenetrated rural Welsh and Scottish distribution networks where sparse line topology creates acute pain points. Deploy pole-top phasor measurement unit miniaturization as the go-to-market wedge, offering tenfold density improvements over rack-mounted substation installations at reduced hardware cost points. For Investors and Strategic Acquirers: Long-term, this sits as a regulated utility infrastructure play because Ofgem's RIIO-ED2 price control framework guarantees cost-plus recovery for digitalization investments across the analysis window. Target acquisition candidates with demonstrated interoperability across incumbent SCADA protocols and emerging 5G communication backhaul architectures. Monitor Balancing Mechanism reform implementation as the critical inflection signal for distributed energy resource aggregator viability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Multi-vendor SCADA interoperability reduces commissioning friction for Ofgem-regulated network operators. |
| Backward Integration | Captive rare earth sourcing insulates transformer manufacturing from neodymium supply concentration risks. |
| Geographic Expansion | Welsh and Scottish rural automation pilots unlock first-mover advantage in fault isolation technology deployment. |
| Strategic Partnership | 5G carrier alliances secure resilient substation backhaul before cellular spectrum sunsets strand rural assets. |
| Product Launch | Pole-top phasor measurement unit miniaturization captures margin expansion in England's urban corridor density deployments. |
Research Methodology
A standing panel of distribution network operator planning officers, flexibility service aggregators, EPC contractors, and grid protection engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from Ofgem RIIO-ED2 filings, BEIS grid modernization consultations, National Infrastructure Commission reports, and distribution operator digitalization investment plans. Bottom-up project pipeline analysis triangulated against top-down regulatory expenditure forecasts to anchor volume estimates.
Consistency checks against external benchmarks validated output ranges across the projection horizon. The analytical framework modeled technology deployment curves, application-tier procurement intensity, product type margin structures, and end-user authority concentration. CAGRs derived from segment-level growth rate differentials applied against baseline regulatory expenditure commitments. Forecast inputs incorporated Balancing Mechanism participation trajectories and smart meter installation run-rates.
Forecasts assume regulatory continuity in Ofgem price control frameworks and UK electricity market governance; material policy shifts around capacity market design or carbon border adjustments would require re-modeling. Recalibration cycles align with material shifts in RIIO-ED2 incentive structures and distributed energy resource interconnection queue processing rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Grid Network Market
Smart Grid
Microgrid Controller Market
Smart Grid
China Smart Grid Network Market
Smart Grid
Power Grid Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Smart Energy Switch Market
Smart Grid
North America Microgrid Market
Smart Grid
Smart Grid Adoption Market
Smart Grid
UK Smart Grid Network Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
Microgrid Market
Smart Grid
India Smart Grid Network Market
Smart Grid
United Arab Emirates Smart Grid Market
Smart Grid
Global Smart Grid Security Market