
 Europe Microgrid Market | 2026-2036
Europe Microgrid Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Microgrid Market Analysis
Buyer concentration among industrial energy consumers is consolidating as large manufacturing campuses and data center operators pool procurement for multi-megawatt microgrid installations. ABB Ltd. leverages its power-electronics portfolio to anchor turnkey delivery across Nordic industrial zones. Siemens AG competes through its digital-twin platform for real-time microgrid optimization. Schneider Electric SE specializes in commercial-building microgrids, extending its building-automation channel into on-site energy management.
A microgrid constitutes a localized electrical network integrating distributed generation, energy storage, and control systems capable of islanding from or synchronizing with the main utility grid, typically operating at voltage levels from 480V to 34.5kV depending on scale and application. Its primary purpose is to deliver reliable, optimized power to specific facilities or communities while enabling renewable penetration and reducing transmission dependency. Grid-connected configurations dominate installed capacity across Europe, though hybrid architectures combining solar and battery storage represent the fastest-expanding technology segment as capital costs decline and software controls mature. Diesel-backed remote microgrids retain relevance in island territories and alpine installations where grid extension remains uneconomical.
The EU Green Deal, F-Gas Regulation, and CE marking requirements under the MDR framework collectively shape equipment standards, refrigerant restrictions for thermal storage, and market access protocols for power-conversion hardware sold across member states. ECHA chemical compliance and national grid codes in Germany, France, and Italy further fragment certification pathways for vendors seeking cross-border deployment. Stakeholders must monitor the evolving interplay between national capacity-market reforms and EU-wide storage mandates to anticipate where procurement authority shifts from utility planners to facility operators.
Market Dynamics
Industrial campuses across Germany and Scandinavia are consolidating procurement for multi-megawatt installations, compressing vendor selection timelines and favoring turnkey integrators with power-electronics manufacturing depth.
Growth Catalysts
- EU Green Deal emissions benchmarks:Tightening carbon thresholds for distributed energy systems are accelerating diesel-to-battery retrofits in alpine microgrids.
- Data center load growth:Hyperscale operators in the Netherlands are mandating on-site generation for grid independence, creating dedicated microgrid procurement streams.
- France's capacity market reforms:Shifting procurement authority from utility planners to facility operators unlocks behind-the-meter storage investments.
Market Restraints
- Battery raw material concentration:Lithium and cobalt supply chains concentrate in non-European geographies, exposing project developers to input cost volatility.
- F-Gas Regulation compliance friction:Thermal storage systems face refrigerant restrictions that extend equipment certification timelines by 12-18 months.
- Grid code fragmentation:Germany's VDE-AR-N 4105, France's NF C 15-100, and Italy's CEI 0-16 create divergent interconnection standards that raise engineering costs for cross-border vendors.
Strategic Opportunities
- Polish industrial zones:Underpenetrated heavy manufacturing clusters offer first-mover positioning for solar-plus-storage microgrids ahead of EU storage mandates.
- Digital-twin convergence:Real-time optimization software merging physics-based modeling with AI forecasting is opening premium service contracts.
- Building-to-grid aggregation:Commercial real estate portfolios are emerging as a new channel for multi-site microgrid orchestration platforms.
Industry Challenges
- Power-electronics engineering scarcity:Specialist talent in grid-forming inverter design remains concentrated among a handful of Nordic and German engineering teams.
- CE marking under MDR:Power-conversion hardware faces evolving conformity assessment pathways that delay market entry for novel topologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Microgrid Market |
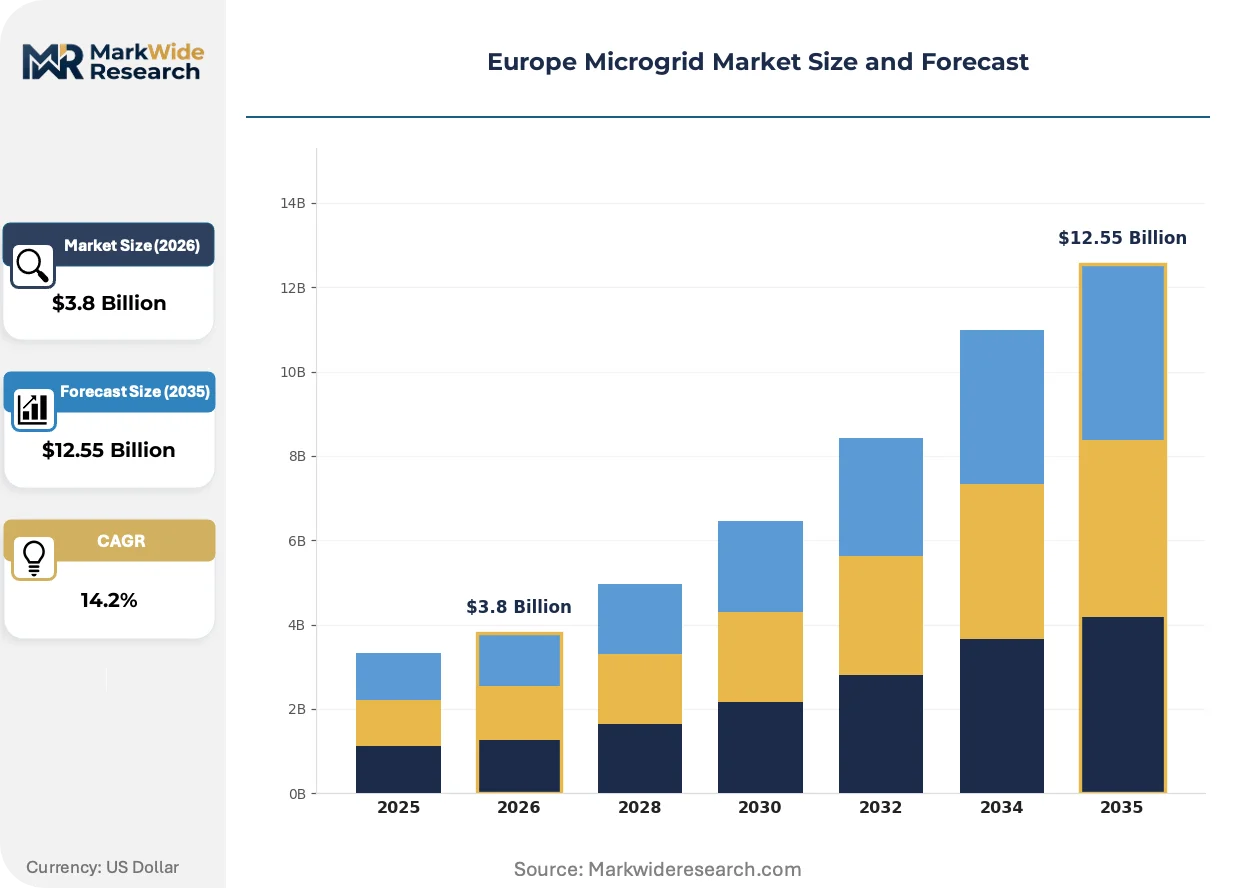
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grid-Connected, Off-Grid, Hybrid, Remote Technology: Solar, Wind, Storage, Diesel End User: Commercial, Industrial, Residential, Municipal Application: Renewable Integration, Emergency Backup, Energy Management, Peak Shaving |
| Companies Covered | ABB Ltd., Hitachi Energy Ltd., Schneider Electric SE, S&C Electric Company, Honeywell International Inc., Siemens AG, General Electric, Enel X S.r.l., Eaton Corporation plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Microgrid Market Emerging Trajectories
Software-defined control architectures are displacing hardware-centric protection schemes, enabling faster reconfiguration and predictive maintenance across heterogeneous generation assets.
Solid-state transformers are converging with silicon carbide power modules to enable direct medium-voltage connection of solar and storage without conventional step-up infrastructure. Industrial campuses in Germany's Ruhr region are piloting these systems for 10-20MW installations. This convergence is compressing substation footprints and reducing balance-of-plant costs by eliminating conventional transformer stages.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in thermal energy storage, forcing manufacturers toward CO2-based or water-based alternatives. Equipment suppliers face redesign cycles for heat pumps and chillers integrated into combined heat-and-power microgrids. Nordic vendors with existing CO2 heat pump portfolios are capturing specification advantages in district heating microgrids.
Energy-as-a-service contracts are displacing traditional equipment ownership models for commercial building microgrids. Facility operators in France and the Netherlands prefer fixed operational expenditures over capital-intensive asset purchases. Schneider Electric's building-automation channel and Siemens' financing arms are restructuring offerings around performance guarantees rather than hardware sales.
Europe Microgrid Market Segmentation
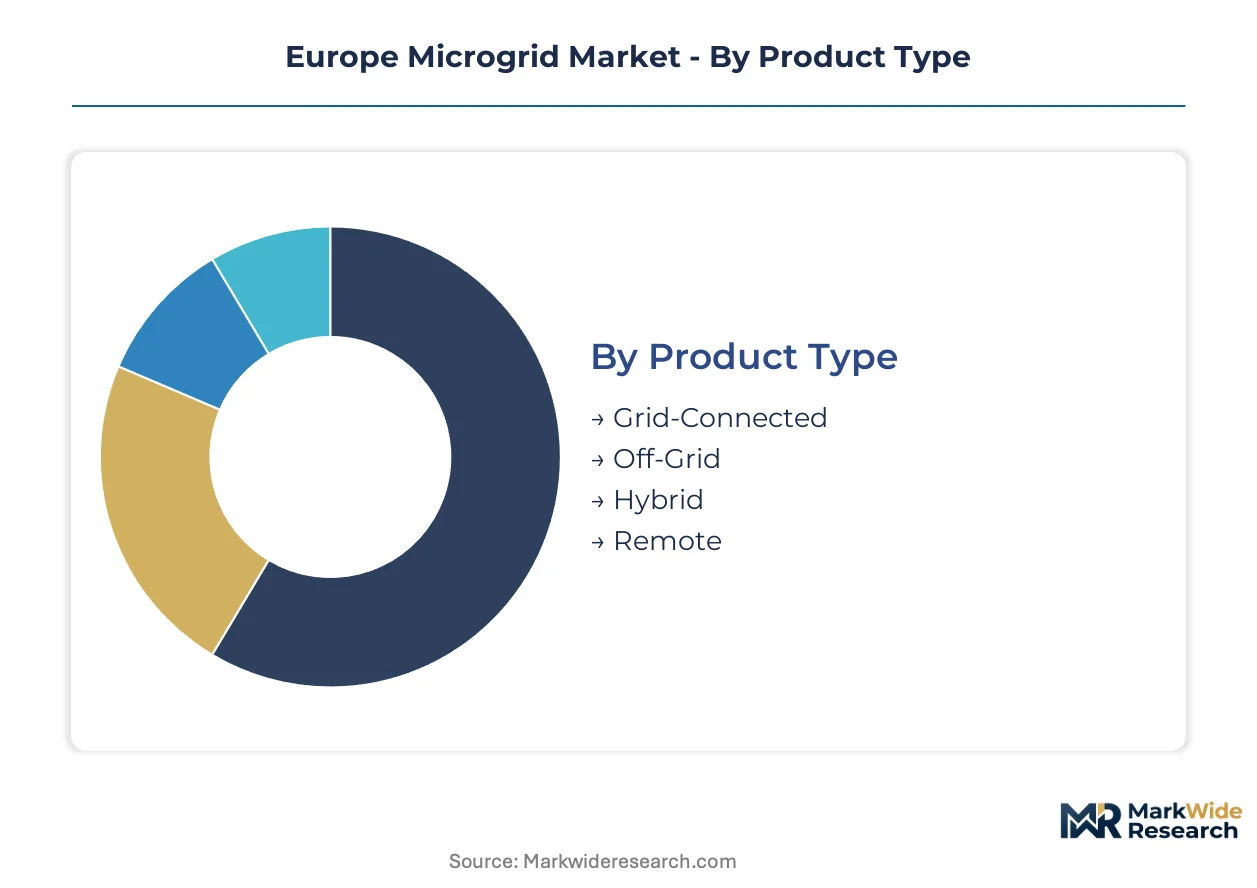
Microgrid architectures vary sharply in hardware requirements and software complexity. Procurement patterns diverge across customer types, with industrial buyers consolidating multi-megawatt installations while commercial portfolios favor modular, repeatable designs.
Product Type:
Supply concentration in power-electronics manufacturing favors vendors with in-house inverter and transformer production.
- Grid-Connected:Synchronizes with utility infrastructure through bidirectional inverters, enabling revenue stacking from wholesale markets and ancillary services. Demand concentrates at German industrial parks and Dutch hyperscale data centers where grid codes under VDE-AR-N 4105 and Dutch TenneT requirements mandate specific ride-through capabilities.
- Hybrid:Combines multiple generation sources with intelligent dispatch algorithms optimizing between solar, storage, and grid import. French manufacturing campuses under capacity market reforms are accelerating procurement of these systems to arbitrage time-of-use tariffs.
- Off-Grid:Fully autonomous systems serving isolated loads without utility interconnection. Alpine research stations and Scandinavian mining operations specify these for locations beyond economic grid extension.
- Remote:Diesel-backed architectures for island territories and emergency installations. Greek islands and Scottish archipelagos retain demand where submarine cable costs prove prohibitive.
Today's leader: Grid-Connected. Tomorrow's challenger: Hybrid.
Technology:
Cost tier differentiation separates capital-intensive electrochemical storage from mature rotating generation.
- Storage:Lithium-ion battery systems with four-hour duration dominate new capacity additions. Netherlands data center operators mandate these for grid independence commitments, though ECHA chemical compliance and cobalt supply concentration create procurement friction.
- Solar:Photovoltaic arrays with silicon or thin-film modules constitute the primary renewable anchor. German Ruhr region industrial pilots pair these with solid-state transformers for direct medium-voltage connection.
- Wind:Small-scale turbines and mid-size installations for high-resource locations. Scottish Highlands and Danish coastal zones specify these where capacity factors exceed solar economics.
- Diesel:Compression-ignition generators providing spinning reserve and black-start capability. Alpine microgrids under EU Green Deal benchmarks are retrofitting these to biofuel or battery hybrid configurations.
Storage commands premium pricing. Solar delivers volume scale.
End User:
Customer type determines procurement authority and financing structure.
- Industrial:Manufacturing campuses and process facilities with 24/7 baseload requirements. Germany and Scandinavia concentrate procurement for multi-megawatt installations with 10-20 year power purchase agreements.
- Commercial:Office buildings, retail portfolios, and hospitality assets with daytime-peaking loads. France and Netherlands facility operators prefer energy-as-a-service contracts over capital ownership.
- Municipal:District heating networks, public buildings, and civic infrastructure. Nordic cities with existing CO2 heat pump portfolios integrate these into combined heat-and-power microgrids.
- Residential:Single-family and multi-family developments with sub-megawatt requirements. German residential solar-plus-storage mandates under national building codes are expanding this segment.
Industrial buyers consolidate procurement. Commercial portfolios favor standardization.
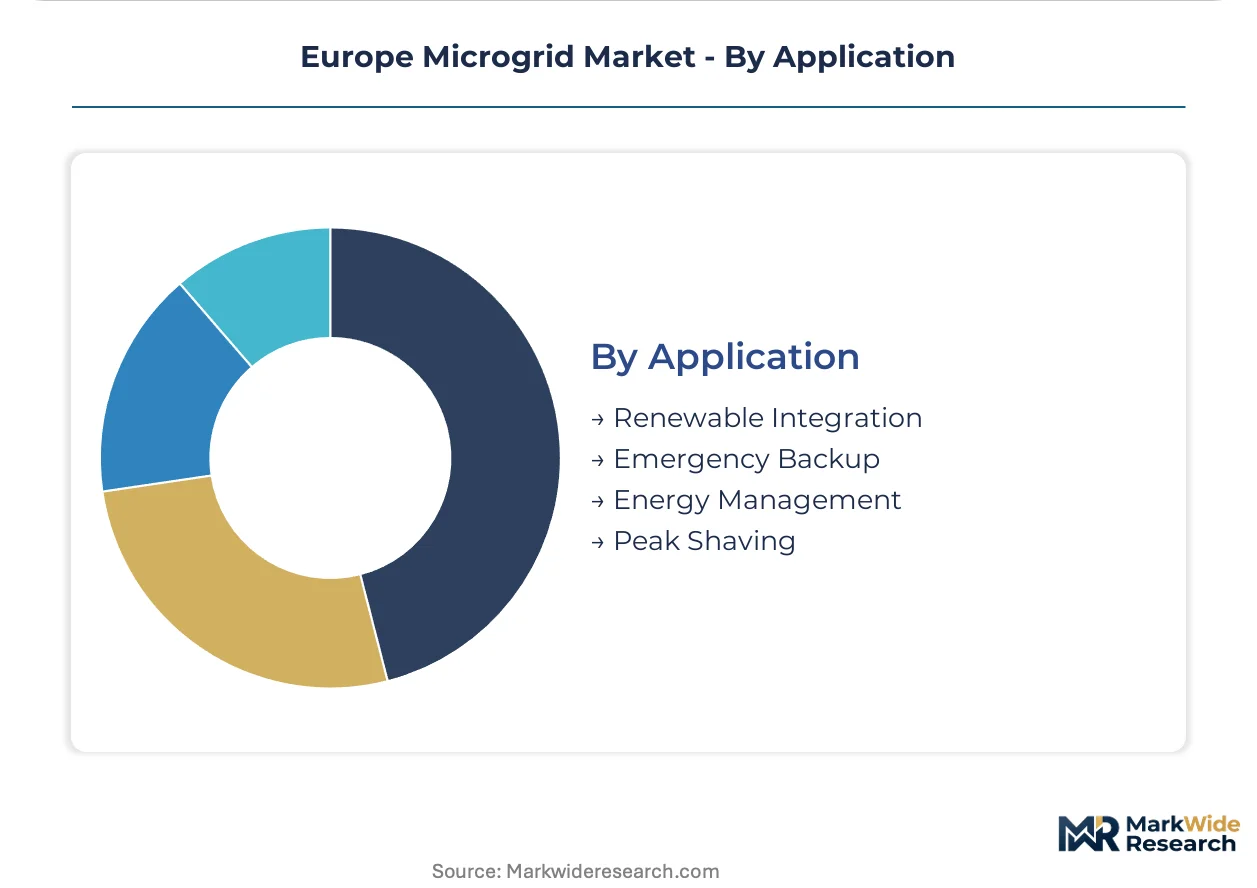
Application:
Margin profiles vary by value proposition, with emergency backup commanding reliability premiums.
- Renewable Integration:Maximizes self-consumption of on-site solar and wind while managing intermittency. German industrial zones prioritize these for emissions compliance under EU Green Deal thresholds.
- Emergency Backup:Islanding capability for critical loads during grid outages. Dutch healthcare facilities and French nuclear supply chain manufacturers specify these for business continuity.
- Energy Management:Predictive optimization of generation, storage, and load dispatch. Real-time digital-twin platforms from Nordic engineering teams enable these advanced control schemes.
- Peak Shaving:Reducing maximum demand charges through stored energy discharge. Netherlands commercial real estate applies these to manage TenneT transmission tariff structures.
Emergency backup captures reliability premiums. Renewable integration scales fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist engineering talent in power-electronics and grid-forming inverter design concentrates in Nordic and German engineering clusters, anchoring procurement authority for multi-megawatt industrial installations across Northern Europe.
Germany
Industrial campuses in the Ruhr region and Bavaria are consolidating procurement for 10-20MW microgrid installations with solid-state transformer pilots. The VDE-AR-N 4105 grid code mandates specific ride-through capabilities for distributed generation. Manufacturing zones around Dortmund and Munich are retrofitting diesel assets to battery hybrid configurations under EU Green Deal emissions benchmarks.
France
Capacity market reforms are shifting procurement authority from utility planners to facility operators, unlocking behind-the-meter storage investments. The NF C 15-100 electrical installation standard governs interconnection protocols for commercial building microgrids. Nuclear supply chain manufacturers in the Île-de-France region are specifying emergency backup microgrids for business continuity requirements.
Netherlands
Hyperscale data center operators are mandating on-site generation for grid independence commitments, creating dedicated procurement streams for lithium-ion battery systems. TenneT transmission tariff structures incentivize peak shaving through stored energy discharge. Amsterdam and Eindhoven metro areas concentrate demand for four-hour duration storage integrated with grid-connected architectures.
Scandinavia
CO2 heat pump portfolios from Nordic vendors are capturing specification advantages in district heating microgrids as the F-Gas Regulation phases down hydrofluorocarbon refrigerants. Swedish and Finnish engineering teams retain concentrated capability in grid-forming inverter design. Alpine research stations and mining operations across Norway and northern Sweden specify fully autonomous off-grid systems where grid extension remains uneconomical.
Poland
Underpenetrated heavy manufacturing clusters offer first-mover positioning for solar-plus-storage microgrids ahead of EU-wide storage mandates. National grid code alignment with EU directives is streamlining certification pathways for cross-border vendors. Industrial zones around Katowice and Łódź are emerging as procurement targets for turnkey integrators seeking volume scale beyond saturated Western European markets.
Europe Microgrid Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing and software control layers. The vendor base organizes around three strategic archetypes: power-electronics manufacturers with captive inverter production, building-automation specialists extending into energy management, and digital-platform providers monetizing optimization software. Consolidation pressure favors turnkey integrators capable of spanning engineering, procurement, and construction for industrial-scale deployments. Dominant competitive moves include strategic partnerships between hardware OEMs and AI forecasting vendors, plus backward integration into battery system assembly.
Within the diversified industrial tier, ABB Ltd. and Siemens AG exemplify contrasting strategic positions. Schneider Electric SE occupies a distinct channel position bridging building automation and on-site energy management. These three anchors represent the primary competitive vectors shaping procurement outcomes across German industrial zones and French commercial portfolios.
| Leading Market Players |
|---|
| ABB Ltd. |
| Hitachi Energy Ltd. |
| Schneider Electric SE |
| S&C Electric Company |
| Honeywell International Inc. |
| Siemens AG |
| General Electric |
| Enel X S.r.l. |
| Eaton Corporation plc |
| Others |
Supply Flow & Price Mechanics
Data center operators in the Netherlands mandating four-hour lithium-ion battery specifications for grid independence commitments are forcing EPC contractors toward qualified cell suppliers with CE marking under MDR and ECHA chemical compliance, compressing vendor margins while premiumizing certified system pricing.
Pricing Analysis
Capacity additions in Poland and Scandinavia are reshaping price floors for solar-plus-storage microgrids as turnkey integrators compete for first-mover positioning ahead of EU-wide storage mandates. Three-tier pricing structure across premium, standard, and economy levels separates grid-forming inverter systems with predictive maintenance software from basic string inverter configurations. Pricing pressure stems from cobalt and lithium supply chain concentration in non-European geographies exposing project developers to input cost volatility. Industrial buyers consolidating multi-megawatt procurement demonstrate lowest price sensitivity while commercial real estate portfolios under energy-as-a-service contracts exhibit highest elasticity.
Supply Chain Analysis
Lithium-ion cell supply rests on South Korean and Japanese producers with cathode active material processing concentrated in China, creating multi-node dependency for European microgrid integrators. Silicon carbide power modules, solid-state transformer cores, and grid-forming inverter control boards constitute critical component inputs. Single-source vulnerability around silicon carbide substrate supply exposes project timelines to semiconductor foundry allocation decisions. Distribution runs through EPC contractors with captive engineering capability in Germany and the Netherlands, bypassing traditional electrical wholesale channels for industrial-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Poland's underpenetrated industrial zones offer margin expansion unavailable in saturated German procurement markets, amplified by national grid code alignment with EU directives streamlining cross-border vendor certification.
For Market Incumbents: Anchor procurement authority through backward integration into battery system assembly and captive silicon carbide power module sourcing, defending against pure-play software vendors encroaching on optimization service contracts. Deepen channel control via strategic partnerships with AI forecasting vendors for real-time digital-twin platforms. Prioritize CE marking investment under evolving MDR pathways to delay market entry for novel inverter topologies from Asian competitors. For New Entrants and Emerging Players: Begin with Polish heavy manufacturing clusters around Katowice and Łódź where EU storage mandates have not yet concentrated buyer attention, offering solar-plus-storage microgrids with simplified interconnection protocols. Target municipal district heating networks in Nordic cities with CO2 heat pump integration for specification advantages under F-Gas Regulation phase-down. Pursue energy-as-a-service contract structures to bypass capital ownership barriers among French and Netherlands commercial facility operators. For Investors and Strategic Acquirers: Asymmetric upside sits with Nordic engineering teams possessing concentrated grid-forming inverter design capability as talent scarcity intensifies across the analysis window. Long-term viability over the projection horizon favors turnkey integrators spanning hardware manufacturing and software control layers. Acquisition targets should demonstrate cross-border deployment experience under fragmented national grid codes. Watch for inflection when capacity market reforms shift procurement authority from utility planners to facility operators in additional member states beyond France.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Captive cell supply reduces ECHA compliance friction and cobalt price volatility exposure. |
| Digital-Twin Platform Development | Real-time optimization software from Nordic engineering teams commands premium service contracts. |
| CO2 Heat Pump Portfolio Expansion | F-Gas Regulation phase-down creates specification advantages in district heating microgrids. |
| Polish Industrial Zone Market Entry | First-mover positioning ahead of EU storage mandates unlocks volume scale beyond Western Europe. |
| Energy-as-a-Service Contract Restructuring | Fixed operational expenditure models displace capital ownership among Netherlands data center operators. |
Methodological Framework
Bottom-up industrial campus and data center operator modeling reconciled against top-down power-electronics manufacturing tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across Germany, France, the Netherlands, and Poland combined with secondary validation from EIA data, IEA reports, FERC filings, and European project development databases. Cross-referencing CE marking documentation under MDR, F-Gas Regulation compliance filings, and national grid code interpretations enabled triangulation of vendor certification timelines.
Historical trendline analysis of installed microgrid capacity by architecture type, generation technology, and end-use segment established baseline penetration patterns. Segmentation dimensions modeled across the projection horizon include grid interconnection configuration, electrochemical storage duration, generation fuel source, facility scale tier, and national regulatory framework. CAGRs were derived from capacity addition forecasts weighted by technology cost curves and policy implementation schedules. Forecast inputs incorporated solid-state transformer pilot deployment timelines in Germany's Ruhr region and capacity market reform propagation across member states.
Several conditions sit outside the modeled scope, including abrupt lithium or cobalt supply disruptions, unilateral national grid code deviations from EU harmonization directives, and accelerated F-Gas Regulation enforcement timelines. Forecasts reflect assumptions around software control architecture adoption rates and energy-as-a-service contract penetration in commercial building segments. Material deviation in battery raw material pricing, CE marking pathway duration, or national capacity market reform implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Grid Communications Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Smart Grid Market
Smart Grid
Smart Energy Switch Market
Smart Grid
Smart Grid Data Management Market
Smart Grid
Smart Demand Response Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
Smart Grid Sensors Market
Smart Grid
Middle-East Smart Grid Network Market
Smart Grid
Europe Automated Demand Response Market