
 Smart Grid Data Management Market | 2026-2036
Smart Grid Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Grid Data Management Market Insights
Cloud-native architecture is consolidating around containerized data pipelines that replace monolithic SCADA databases. Siemens leverages deep vertical integration into substation hardware to bundle analytics software with switchgear contracts. Oracle anchors large utility accounts through its enterprise database footprint, while Cisco competes on network-layer security for AMI backhaul.
Smart Grid Data Management encompasses the collection, storage, processing, and analytics of operational and consumer-generated data across electricity distribution networks, typically handling petabyte-scale time-series streams from millions of endpoints with sub-second latency requirements. Its primary purpose is to enable real-time grid visibility, predictive load balancing, and automated fault response. Advanced Metering Infrastructure dominates current deployment value due to its foundational role in data acquisition, though Distributed Energy Resource Management is expanding fastest as rooftop solar and battery assets proliferate. Cloud-Based deployment is capturing margin pools from utilities seeking to shift capital expenditure to operational models.
The EU AI Act and GDPR impose strict algorithmic transparency and data residency rules on predictive grid analytics deployed across European utilities. In the US, FERC Order 2222 and state-level net metering reforms are reshaping how grid operators must integrate and compensate behind-the-meter resources. Stakeholders must monitor whether emerging interoperability standards from IEC and IEEE fragment into competing regional certifications that complicate cross-border software deployment.
Market Dynamics
Cloud-native containerization is compressing deployment timelines for utility data platforms, forcing incumbent vendors to rearchitect monolithic SCADA systems or cede municipal contracts to software-native competitors.
Growth Catalysts
- FERC Order 2222:US grid operators must now integrate and compensate behind-the-meter battery and solar resources, mandating real-time data visibility that legacy infrastructure cannot provide.
- EV load volatility:Rapid electrification of transport fleets is generating sub-second demand spikes that require predictive analytics platforms to prevent distribution transformer overload.
- EU Green Deal efficiency mandates:Binding targets for transmission and distribution loss reduction are compelling utilities to replace siloed meter data management with unified operational data lakes.
Market Restraints
- Semiconductor supply concentration:AMI endpoint chipsets rely on concentrated East Asian foundry capacity, exposing deployment schedules to geopolitical disruption.
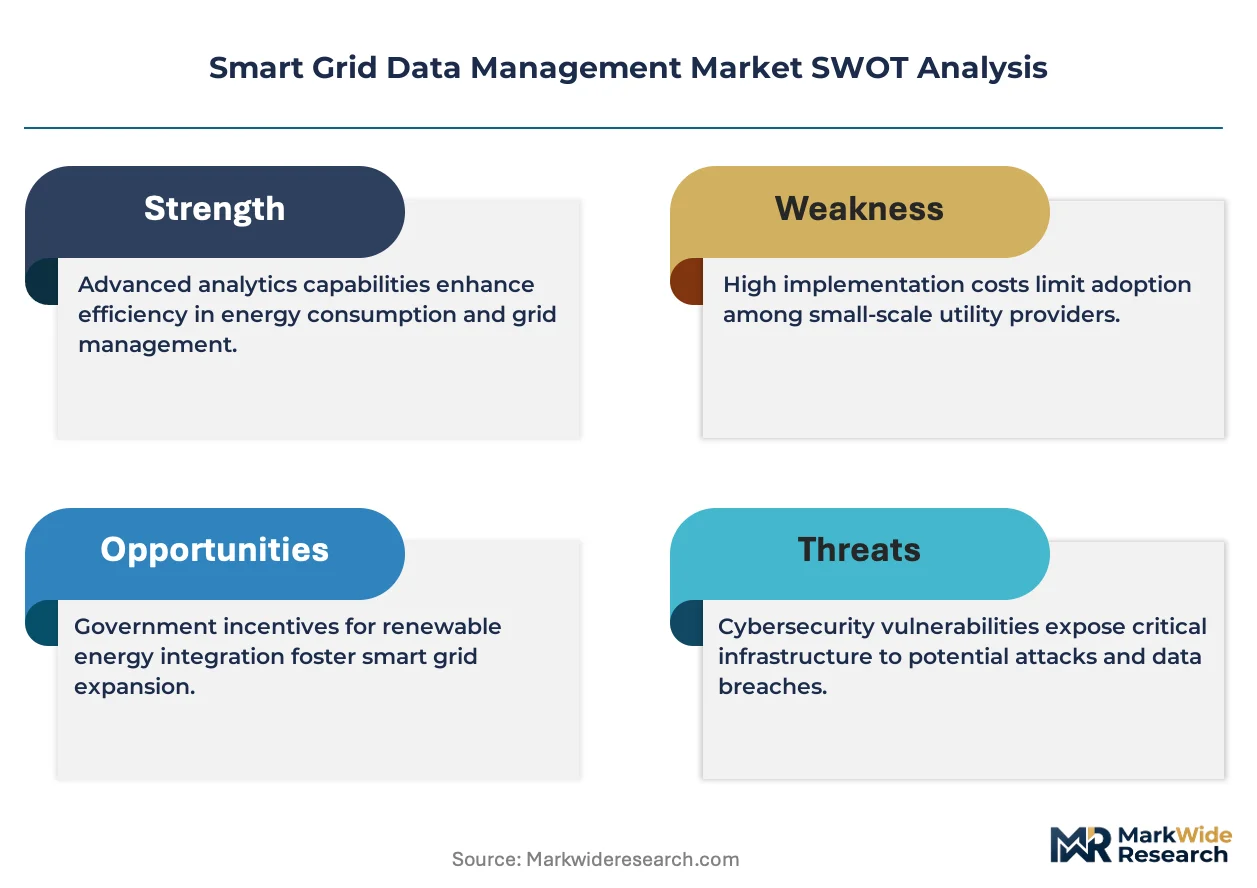
- GDPR algorithmic transparency requirements:The EU AI Act mandates explainability for predictive load forecasting models, increasing development costs and validation timelines.
- Legacy protocol fragmentation:DNP3, IEC 61850, and proprietary SCADA protocols resist seamless interoperability, trapping utilities in vendor-specific upgrade cycles.
Strategic Opportunities
- Behind-the-meter DER orchestration:Virtual power plant aggregation of residential solar and battery assets represents unmonetized grid flexibility capacity in deregulated US markets.
- India's smart city missions:Urban distribution infrastructure upgrades in Mumbai, Bangalore, and Delhi are creating demand for AMI analytics without legacy system migration burdens.
- Edge-AI inference convergence:On-premise model execution at substations reduces backhaul bandwidth requirements and enables sub-100ms fault isolation responses.
Industry Challenges
- Cybersecurity certification bottlenecks:NERC CIP compliance timelines for cloud-hosted operational technology extend procurement cycles by 12-18 months.
- Time-series database talent scarcity:Specialized engineering for petabyte-scale ingestion at sub-second latency commands premium compensation that strains mid-tier vendor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Grid Data Management Market |
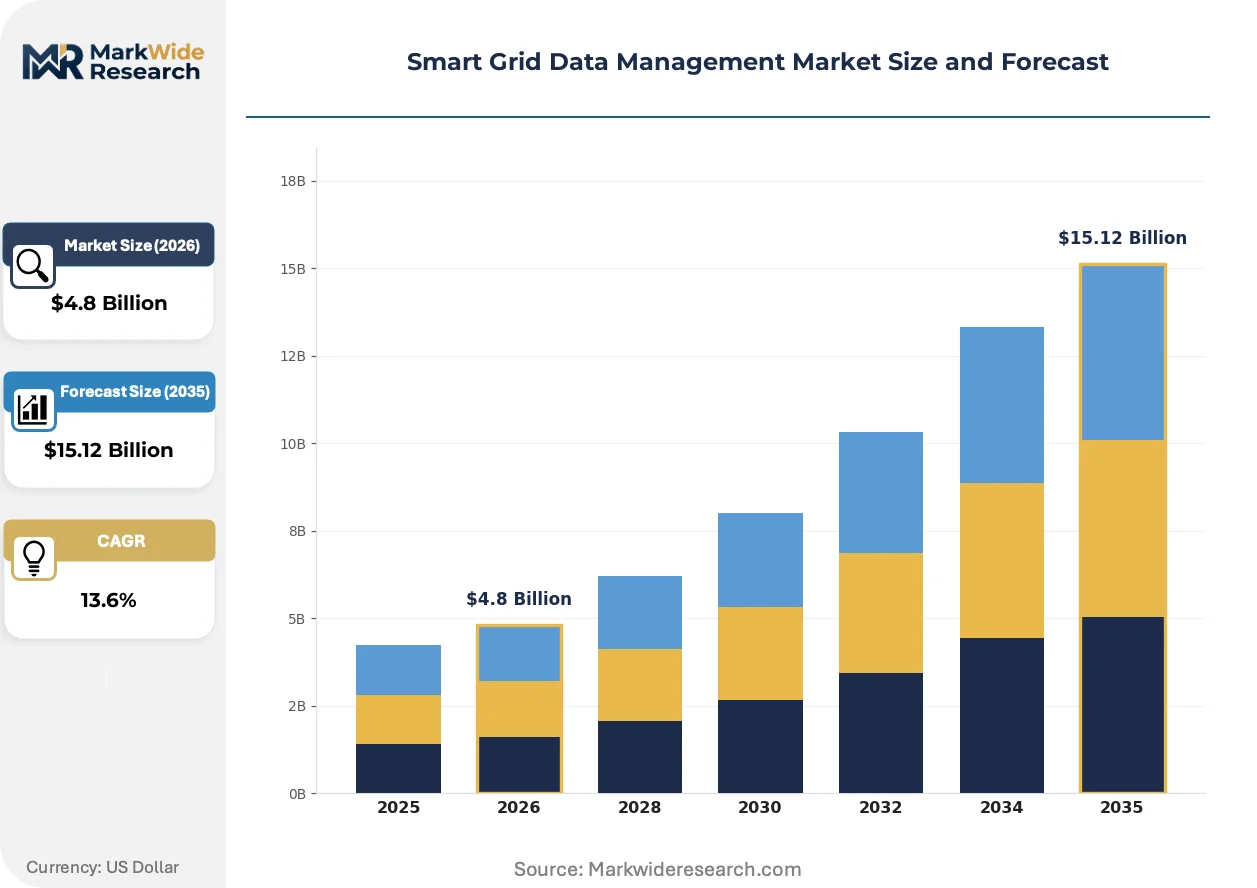
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Advanced Metering Infrastructure, Distributed Energy Resource Management, Demand Response Management, Energy Management Systems Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Utility Companies, Government Agencies, Research Institutions, Industrial Consumers Solution: Data Analytics, Security Management, Grid Automation, Communication Infrastructure |
| Companies Covered | Siemens, Itron, Landis+Gyr, Oracle, Schneider Electric, GE Vernova, SAP, IBM, Cisco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Grid Data Management Market Trends and Innovations
Operational technology boundaries are dissolving as IT-native architectures penetrate substation control rooms, compressing the traditional separation between enterprise analytics and real-time grid operations.
Digital twin modeling is absorbing capital planning functions across transmission operators. European TSOs in Germany and Denmark deploy physics-based grid simulations for contingency analysis. The technology is absorbing engineering hours previously allocated to manual load flow studies, compressing project approval timelines from months to weeks.
The EU AI Act's risk classification framework imposes documentation burdens on predictive maintenance algorithms deployed across German and French distribution networks. Grid software vendors must now maintain model cards and training data provenance for regulatory inspection. High-risk applications in automated switching face mandatory human-in-the-loop requirements that slow autonomous fault response deployment.
Subscription pricing for meter data management platforms is displacing perpetual license structures among North American municipal utilities. Smaller co-ops and PUDs in Washington and Texas states prefer operational expenditure treatment for analytics software. This shift is most visible among utilities under 500,000 endpoints seeking to preserve bond capacity for physical infrastructure.
Smart Grid Data Management Market Segmentation
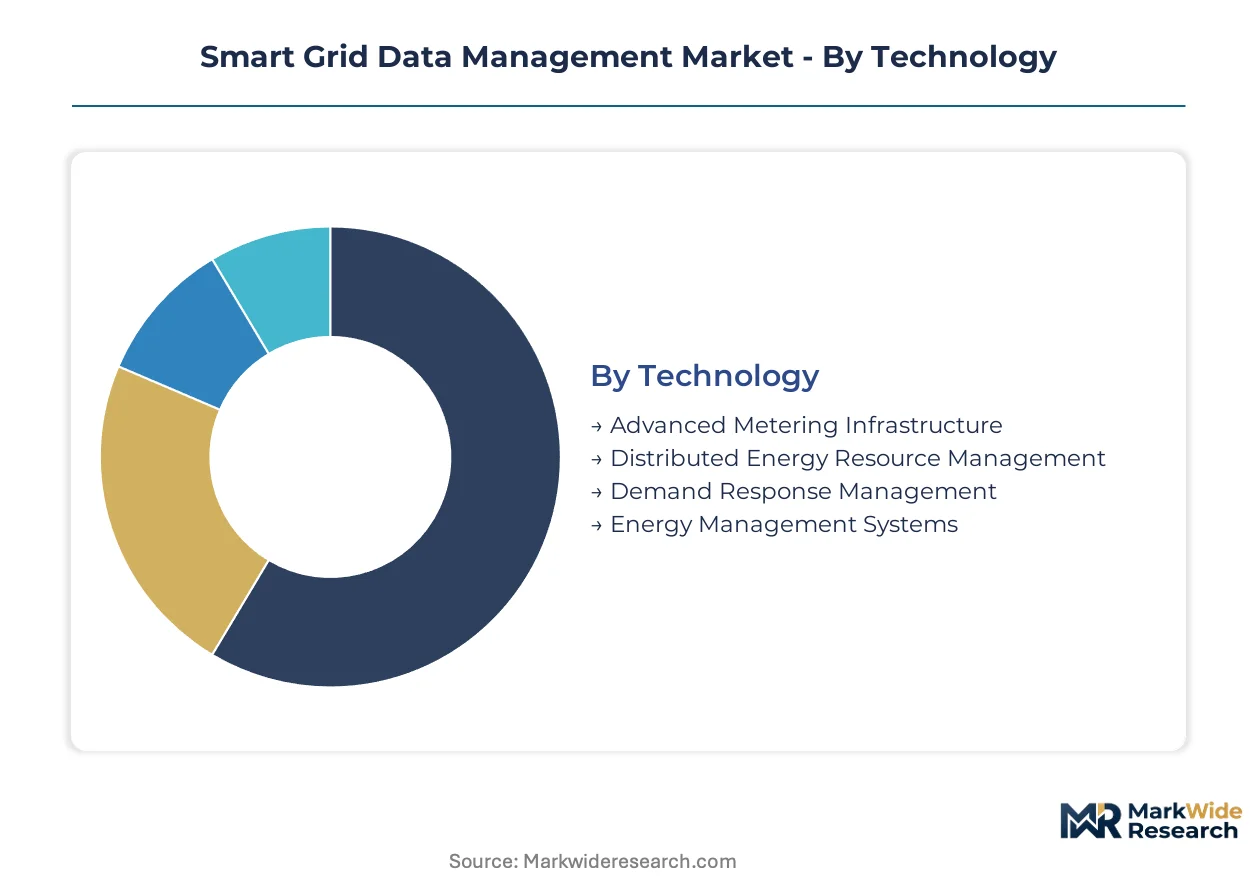
Smart Grid Data Management vendors structure their offerings across four distinct taxonomies that reflect divergent buyer priorities: technology maturity, infrastructure ownership models, regulatory compliance burdens, and operational risk tolerance. Each segmentation axis carries different margin profiles and contract renewal dynamics.
Technology:
Utility buyers in this category differentiate by data latency requirements and the complexity of distributed asset orchestration they must support.
- Advanced Metering Infrastructure:Foundation layer for bidirectional communication between utilities and endpoints, handling 15-minute interval reads from millions of meters. Demand concentrates among US municipal utilities in Texas and California replacing first-generation AMR systems under state efficiency mandates; procurement cycles extend 18-24 months due to NERC CIP compliance requirements.
- Distributed Energy Resource Management:Orchestrates rooftop solar, battery storage, and EV chargers as dispatchable grid resources through real-time telemetry aggregation. German distribution system operators deploy DERMS platforms fastest under EU Green Deal flexibility procurement rules; software-native vendors capture share from hardware incumbents here.
- Demand Response Management:Enables load curtailment signals to industrial and commercial customers during peak events.
- Energy Management Systems:Enterprise-grade platforms for integrated utility operations spanning generation to customer billing.
Volume sits with Advanced Metering Infrastructure; growth tilts toward Distributed Energy Resource Management.
Deployment:
Buyer infrastructure strategies split between capital preservation and data sovereignty requirements, with hybrid architectures emerging as a compromise posture.
- Cloud-Based:Multi-tenant SaaS platforms with utility-specific tenant isolation and encrypted data lakes. Municipal utilities in Washington and Oregon states favor this model to preserve bond capacity for physical infrastructure; subscription pricing displaces perpetual licenses fastest among co-ops under 500,000 endpoints.
- Edge Computing:Substation-resident compute nodes executing AI inference for fault detection without backhaul dependency. Danish TSOs deploy edge nodes for sub-100ms fault isolation in offshore wind interconnect zones; latency requirements here preclude cloud-only architectures.
- On-Premises:Dedicated data centers with full utility control over hardware and software stacks.
- Hybrid:Tiered architecture with sensitive operational data on-premise and analytics workloads in cloud.
Cloud-Based deployments hold current volume concentration; Edge Computing is climbing the fastest as latency-sensitive applications proliferate.
End User:
Procurement authority and compliance scope separate buyers in this segmentation, with regulatory exposure driving solution complexity.
- Utility Companies:Vertically integrated and deregulated operators managing transmission, distribution, and retail functions. US investor-owned utilities under FERC jurisdiction deploy the most comprehensive data lake architectures; cybersecurity certification timelines extend procurement cycles by 12-18 months for cloud-hosted operational technology.
- Government Agencies:National and state energy departments funding smart city infrastructure and rural electrification programs.
- Research Institutions:Universities and national laboratories developing next-generation grid algorithms and interoperability standards.
- Industrial Consumers:Large manufacturing and data center operators with behind-the-meter generation and storage assets seeking grid services revenue.
Utility Companies dominate absolute spend; Industrial Consumers are gaining share fastest as FERC Order 2222 enables aggregation participation.
Solution:
Functional depth and integration burden distinguish buyers, with risk tolerance for autonomous decision-making as the key differentiator.
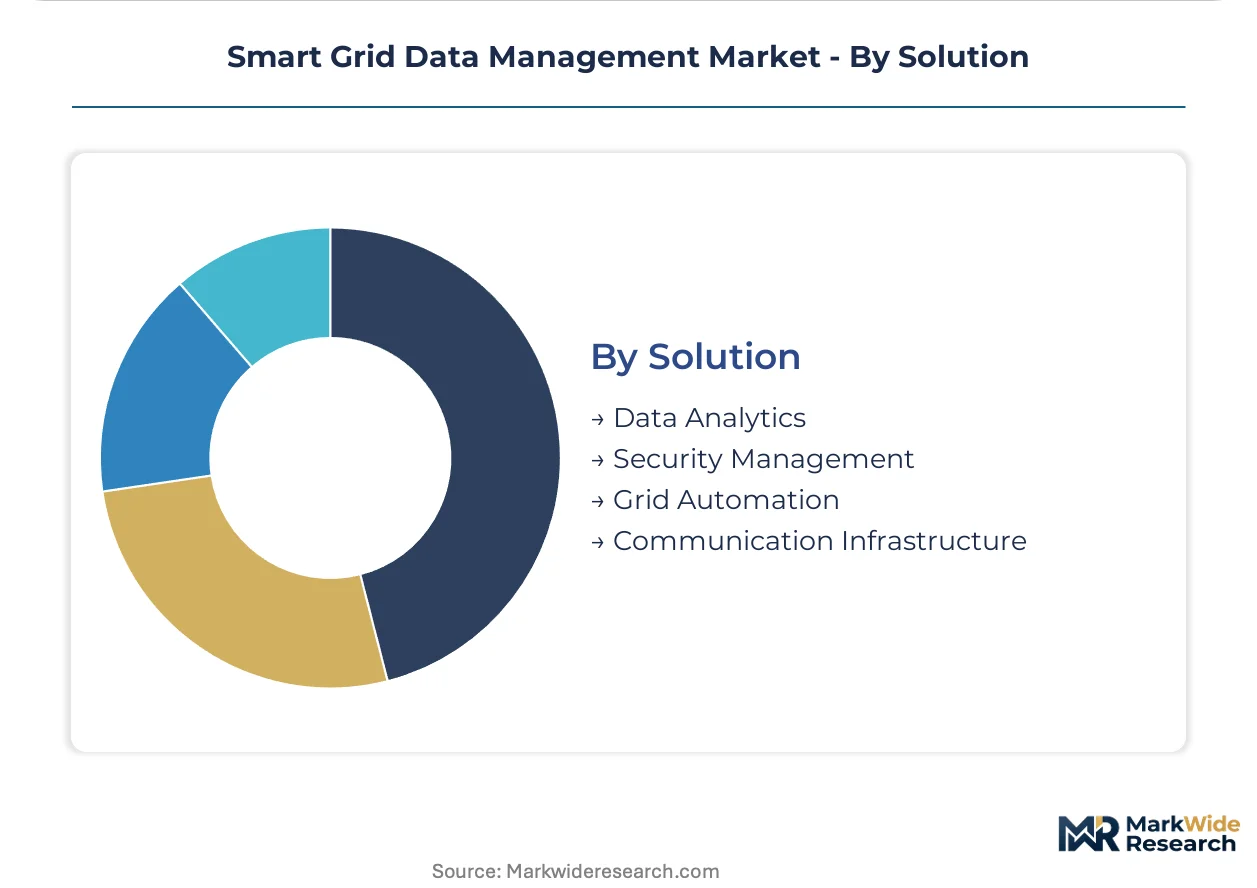
- Data Analytics:Predictive load forecasting, customer segmentation, and asset health modeling platforms. EU utilities face elevated development costs here under GDPR algorithmic transparency requirements and EU AI Act documentation burdens for high-risk automated switching applications.
- Security Management:Encryption, access control, and anomaly detection for operational technology networks.
- Grid Automation:Autonomous fault isolation, voltage optimization, and capacitor bank control systems.
- Communication Infrastructure:RF mesh, cellular, and fiber networks connecting field devices to control centers.
Data Analytics commands the largest share of solution spending; Grid Automation is expanding most quickly as utilities pursue autonomous response capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility data platform procurement concentrates in jurisdictions with binding grid efficiency mandates and high distributed energy penetration. Demand patterns diverge sharply between mature markets replacing legacy SCADA architectures and emerging markets deploying cloud-native systems without migration burdens.
United States
FERC Order 2222 mandates real-time visibility for behind-the-meter resources that legacy infrastructure cannot support. State-level net metering reforms in California and Texas accelerate AMI replacement cycles. Municipal utilities in Washington and Oregon favor subscription pricing to preserve bond capacity for physical infrastructure.
Germany
EU Green Deal transmission loss reduction targets force unified operational data lakes across distribution networks. The F-Gas Regulation and EU AI Act impose algorithmic documentation burdens on predictive maintenance platforms. Siemens and SAP anchor a dense software engineering cluster in Munich and Walldorf.
China
Dual carbon goals and state-mandated smart city programs drive petabyte-scale grid data lake deployment. The national energy regulator enforces interoperability standards for distributed solar aggregation. Yangtze River Delta utilities lead edge-AI substation deployment for sub-100ms fault response.
India
Smart city missions in Mumbai, Bangalore, and Delhi create demand for AMI analytics without legacy system migration costs. The Central Electricity Authority mandates time-series data standards for urban distribution upgrades. Maharashtra and Karnataka distribution companies procure cloud-based platforms to manage rooftop solar volatility.
Denmark
Offshore wind interconnect zones require edge computing nodes for sub-100ms fault isolation that cloud-only architectures cannot deliver. EU GDPR data residency rules constrain cross-border analytics deployment. Danish TSOs deploy physics-based digital twins for contingency analysis, compressing project approval timelines.
Smart Grid Data Management Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hardware incumbents bundling software through switchgear contracts and software-native vendors capturing municipal utilities seeking faster deployment. The vendor base organizes into three archetypes: vertically integrated industrial conglomerates with captive hardware supply, enterprise software vendors leveraging database footprints, and network equipment specialists competing on operational technology security. Dominant competitive moves include strategic partnerships between meter manufacturers and cloud providers, plus geographic expansion through smart city program participation in India and Southeast Asia.
Among industrial conglomerates, Siemens and GE Vernova represent the hardware-anchored archetype, leveraging substation equipment relationships to bundle analytics software. SAP exemplifies the enterprise software tier, converting existing utility ERP accounts into grid data platform deployments. Cisco occupies a position within the network-security vector, competing for AMI backhaul contracts through operational technology hardening capabilities.
| Leading Market Players |
|---|
| Siemens |
| Itron |
| Landis+Gyr |
| Oracle |
| Schneider Electric |
| GE Vernova |
| SAP |
| IBM |
| Cisco |
| Others |
Pricing and Supply Chain Analysis
Semiconductor foundry capacity for AMI endpoint chipsets flows from concentrated East Asian sources through tiered pricing structures that separate utilities by deployment scale and compliance burden. Contract manufacturers in Taiwan and South Korea anchor upstream supply, while downstream pricing stratifies across premium, standard, and economy tiers based on NERC CIP certification levels and data sovereignty requirements.
Pricing Analysis
Volume concentration in Advanced Metering Infrastructure compresses margins, while Distributed Energy Resource Management commands premium pricing due to real-time orchestration complexity. Price differentiation hinges on GDPR-compliant algorithmic transparency certification and edge-AI inference capability at substations. Pricing pressure stems from municipal utilities in Washington and Oregon states shifting capital expenditure to operational models through subscription SaaS structures. Co-ops under 500,000 endpoints exhibit highest price sensitivity; German distribution system operators under EU Green Deal mandates show lowest sensitivity due to binding efficiency targets.
Supply Chain Analysis
Regional distribution centers for substation hardware cluster in Germany, China, and the United States to serve utility procurement cycles. AMI endpoint production draws from Taiwan, South Korea, and Japan for specialized chipsets and RF mesh components. Supply chain risk centers on single-source vulnerability for time-series database engineering talent commanding premium compensation. Distribution runs through direct OEM-utility relationships for switchgear-bundled analytics, with software-native vendors bypassing traditional channel structures through cloud-native SaaS deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering capacity for petabyte-scale time-series ingestion functions as the binding constraint propping pricing power across vendor tiers. Foundry allocation for grid-specific semiconductors remains tighter than general-purpose silicon, extending procurement timelines for AMI deployments.
For Market Incumbents: To counter software-native competitors capturing municipal contracts through faster cloud deployment, Siemens and GE Vernova should deepen backward integration into substation edge computing hardware. Certification investment in EU AI Act-compliant model documentation for predictive maintenance algorithms preserves German and French utility relationships. Channel control through switchgear bundling contracts defends margin position against unbundled analytics vendors.
For New Entrants and Emerging Players: Containerized data pipelines replacing monolithic SCADA databases offer the clearest technology-first wedge for mid-tier vendors. India's smart city missions in Mumbai and Bangalore present the most penetrable geography given absence of legacy migration burdens. A direct SaaS go-to-market angle targeting co-ops under 500,000 endpoints with subscription pricing outflanks incumbent license structures.
For Investors and Strategic Acquirers: FERC Order 2222 implementation velocity across Texas and California utilities is the leading indicator that behind-the-meter DER orchestration platforms will capture disproportionate value creation. Long-term viability over the next decade favors vendors with hybrid cloud-edge architectures serving deregulated US markets. Acquisition targets should display time-series database engineering depth and NERC CIP pre-certification. The signal to monitor is state-level net metering reform announcements accelerating AMI replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Containerized data pipelines displace monolithic SCADA databases in municipal utility procurements. |
| Acquisition of Specialist Firm | Time-series database engineering teams command scarcity premiums in competitive talent markets. |
| Strategic Partnership | Meter manufacturers ally with cloud providers to bypass traditional channel structures. |
| Geographic Expansion | Smart city program participation in India and Southeast Asia accesses greenfield deployment demand. |
| Product Launch | Edge-AI inference nodes at substations enable sub-100ms fault isolation responses. |
Research Methodology
Multi-period observation of AMI deployment timelines, DER penetration rates, and utility procurement patterns anchored the trend analysis, supplemented by interviews with utility planning officers, grid operators, AMI program managers, and software procurement leads. Secondary validation drew from FERC filings, EIA grid data, IEA energy transition reports, and EU regulatory transparency databases. Bottom-up segmentation modeling triangulated against top-down market sizing across technology, deployment, end-user, and solution dimensions.
Input-output matrices mapped deployment model adoption curves to subscription pricing elasticity by utility size tier. Segmentation dimensions modeled included infrastructure ownership structure, regulatory compliance burden, data latency requirement, and operational risk tolerance. CAGRs were derived from fitted growth curves against historical deployment trajectories. Forecast inputs incorporated EV load volatility projections and EU Green Deal efficiency mandate enforcement schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption scenarios and NERC CIP compliance timeline extensions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Microgrid Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
Smart Microgrid Controller Market
Smart Grid
Smart Demand Response Market
Smart Grid
Europe Microgrid Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Microgrid Market
Smart Grid
North America Microgrid Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
India Smart Grid Network Market
Smart Grid
Smart Grid Communications Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
UK Smart Grid Network Market