
 Grid-Scale Battery Market | 2026-2036
Grid-Scale Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Grid-Scale Battery Market Intelligence
Software-defined energy management is rebalancing what buyers procure, shifting capital expenditure toward subscription-based performance contracts and predictive maintenance overlays. Fluence Energy leverages its AI-powered trading and optimization platform to differentiate beyond hardware sales. CATL anchors its position through backward integration into lithium refining and cathode production, controlling cost structures across the supply chain. Tesla sustains technology leadership via vertical integration of in-house cell chemistry, pack assembly, and grid-side software stacks.
Grid-scale batteries are electrochemical storage systems rated at one megawatt-hour or above, engineered for frequency regulation, capacity firming, and bulk energy time-shifting across transmission and distribution networks. Lithium-ion chemistry dominates installed capacity due to energy density advantages and declining cell costs, though flow batteries are gaining traction in long-duration applications requiring eight-plus hours of discharge. Utility-scale deployment leads by project volume, while community storage and commercial microgrids represent faster-growing segments where margin pools concentrate around distributed control software and local market participation services.
FERC Order 841 in the United States mandates wholesale market access for storage resources, while the EU Green Deal and F-Gas Regulation shape European procurement standards and thermal management requirements. China's MIIT and NMPA enforce domestic battery safety and recycling protocols that influence export certification pathways. Stakeholders must monitor how evolving capacity market rules and carbon border adjustments reshape competitive positioning across manufacturing and project development decisions.
Market Dynamics
Software-defined energy management is compressing hardware margins and redistributing value toward predictive analytics and trading optimization layers that ride atop electrochemical assets.
Growth Catalysts
- US Inflation Reduction Act production tax credits:Domestic cell and pack manufacturing receives $35 per kilowatt-hour incentives, reshaping location decisions for gigafactory investments.
- Frequency regulation procurement:Grid operators in Texas, California, and Germany now mandate fast-response storage for grid stabilization services.
- Lithium iron phosphate chemistry:Lower thermal runaway risk and extended cycle life are accelerating utility adoption for 4-6 hour duration applications.
Market Restraints
- Lithium carbonate price volatility:Spot market swings between $15,000 and $80,000 per metric ton since 2021 destabilize project financing and offtake pricing.
- Cathode precursor concentration:Over 70% of refined cobalt and nickel processing capacity sits in China, creating single-source vulnerability for non-Chinese integrators.
- Eight-hour duration threshold:Lithium-ion degradation economics break down beyond six hours, leaving long-duration firming to unproven alternatives.
Strategic Opportunities
- India's renewable purchase obligations:State-level mandates for 500 megawatt-hour storage procurement by 2030 create first-mover terrain for technology licensors.
- Vanadium redox flow batteries:12-hour discharge capability opens wholesale arbitrage and transmission deferral applications closed to lithium-ion.
- Behind-the-meter aggregation:Virtual power plant software stacks enable commercial and industrial assets to participate in capacity markets previously reserved for utility-scale plants.
Industry Challenges
- Fire suppression system integration:NFPA 855 and local fire code variations create project-specific engineering delays and insurance premium uncertainty.
- Power conversion system interoperability:Proprietary communication protocols between battery management systems and inverters extend commissioning timelines and lock integrators into single-vendor relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grid-Scale Battery Market |
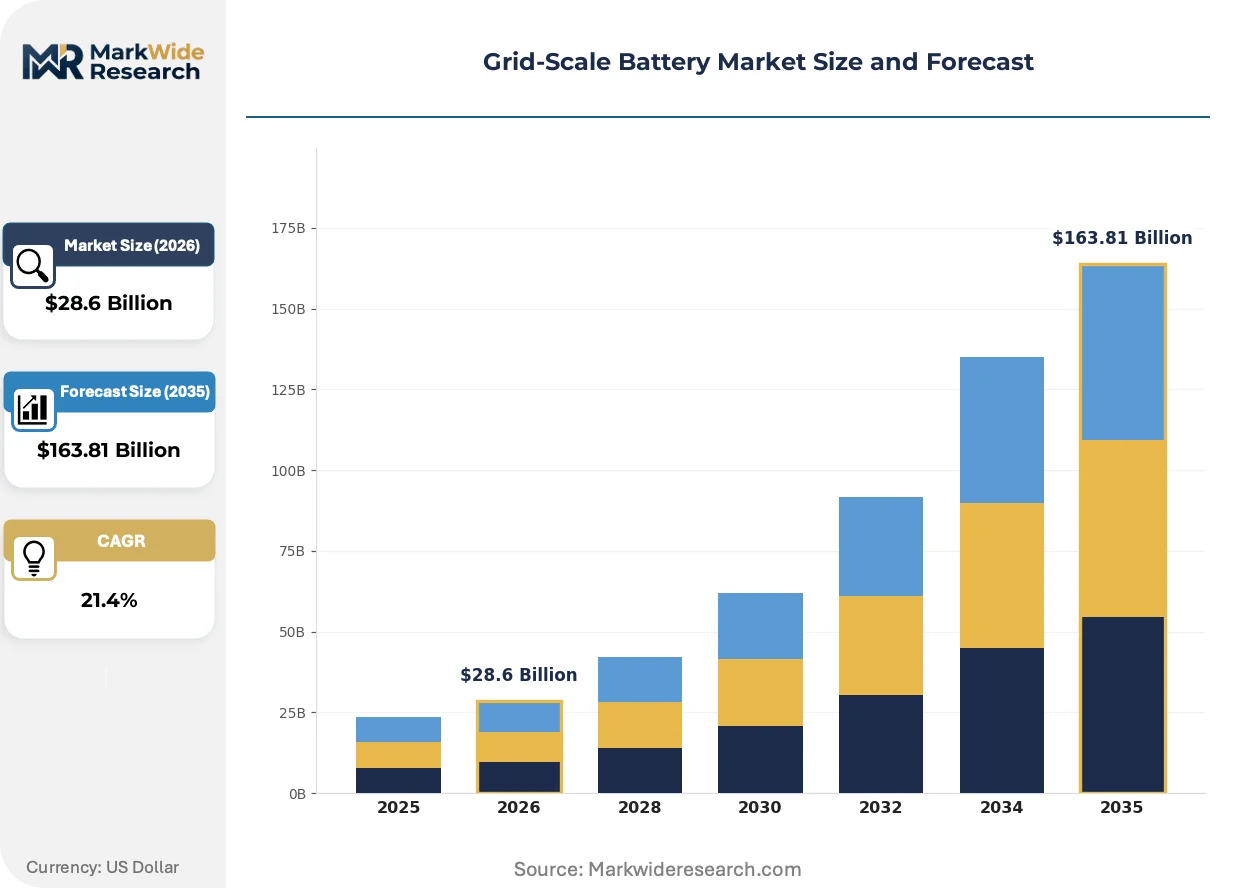
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $163.81 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Chemistry: Lithium-Ion, Sodium-Sulfur, Flow Batteries, Lead Acid, Nickel-Cadmium, Zinc-Air Deployment Type: Utility-Scale, Community Storage, Commercial Microgrid, Off-Grid Systems, Peak Shaving, Load Balancing End User Industry: Electric Utilities, Renewable Energy Producers, Data Centers, Telecommunications, Microgrid Operators, Manufacturing Plants Installation Environment: Urban Areas, Rural Sites, Industrial Complexes, Remote Sites, Substations, Power Plants |
| Companies Covered | Tesla, Fluence Energy, LG Energy Solution, BYD Company, Sungrow Power Supply, CATL, Samsung SDI, NGK Insulators, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grid-Scale Battery Market Strategic Shifts & Innovations
Artificial intelligence is penetrating every layer of battery asset management, from cell formation optimization to wholesale market bidding algorithms that extract value beyond energy throughput.
Solid-state electrolyte research is electrifying next-generation cell architectures by replacing flammable liquid electrolytes with ceramic or sulfide conductors. Automotive and grid OEMs are co-investing in pilot lines, targeting 2027-2028 commercialization. This transition is compressing the safety-certificate advantage that incumbent lithium-ion suppliers currently hold in dense urban installations.
Europe's F-Gas Regulation is phasing down hydrofluorocarbon use in thermal management systems, forcing manufacturers to adopt CO2 or water-glycol cooling loops. Battery integrators serving EU markets must redesign pack architectures and requalify safety certifications. German and Dutch project developers now specify natural refrigerant compatibility as a procurement gate.
Utility procurement departments are unbundling hardware supply from long-term service agreements, creating separate contract vehicles for cells, power conversion, and optimization software. This fragmentation enables specialized vendors to compete without full-stack capabilities. Texas and Australian grid operators exhibit the most advanced disaggregation, with independent power producers assembling multi-vendor systems under single offtake contracts.
Grid-Scale Battery Market Segmentation
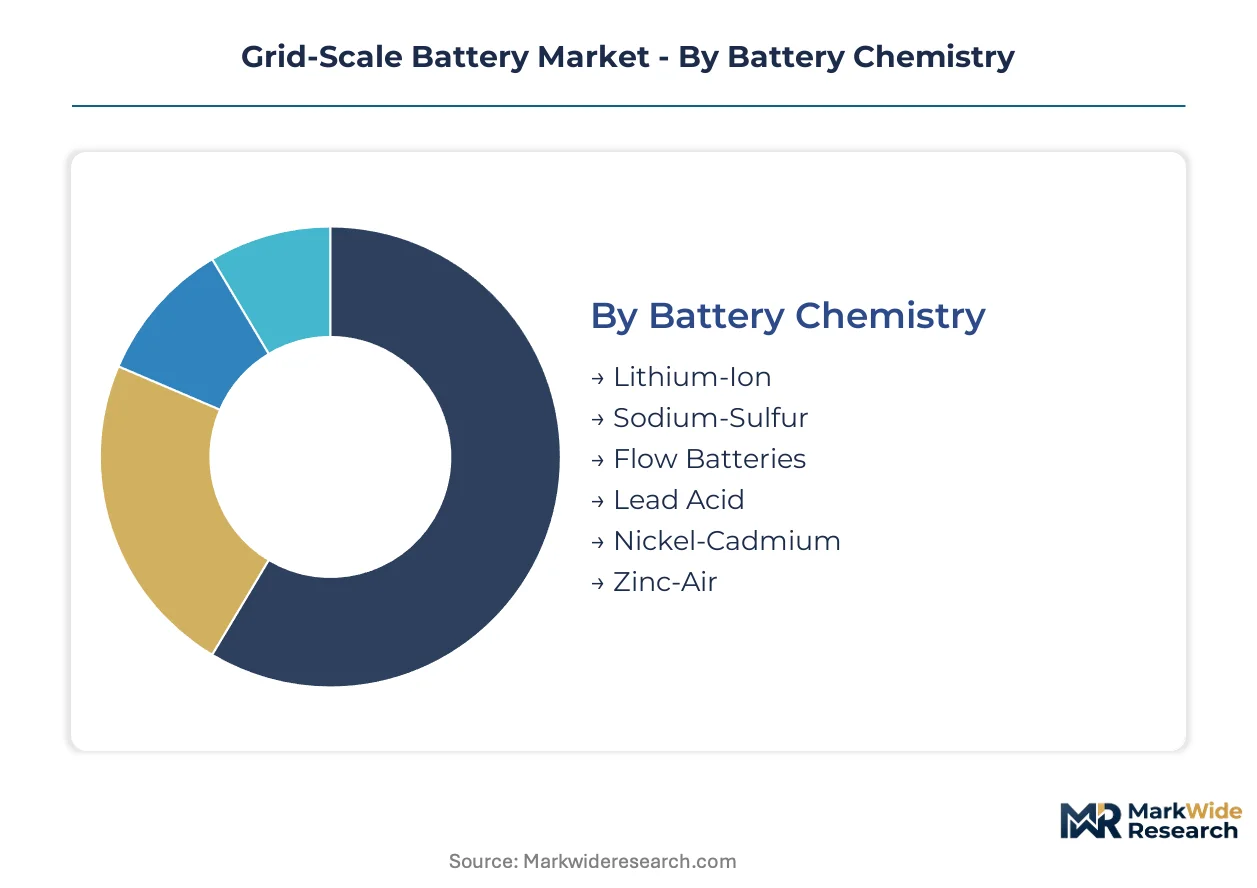
Grid-scale battery procurement fractures across chemistry choices, deployment scale, and end-user risk profiles. Each segmentation axis carries distinct margin structures and regulatory exposure that reshape vendor competitive positioning.
Battery Chemistry:
Chemistry selection dictates thermal management requirements, cycle life economics, and supply chain sourcing strategy for integrators and developers.
- Lithium-Ion:Energy-dense cells using lithium iron phosphate or nickel-manganese-cobalt oxide cathodes dominate 4-6 hour duration installations. Electric utilities in Texas and California concentrate procurement here, driven by FERC Order 841 wholesale market access and declining cell cost curves.
- Flow Batteries:Vanadium redox and zinc-bromine systems separate power and energy scaling, enabling 8-12 hour discharge without capacity fade. Germany's transmission deferral projects and India's renewable purchase obligations are concentrating demand for long-duration firming applications.
- Sodium-Sulfur:High-temperature ceramic electrolyte systems deliver extended cycle life in stationary applications. Japanese grid operators and Middle Eastern utilities deploy these for bulk energy shifting.
- Lead Acid:Mature flooded and valve-regulated designs serve backup power and frequency regulation in cost-sensitive installations. Telecommunications and rural electrification projects specify these where capital constraints override energy density requirements.
- Nickel-Cadmium:Robust performance across temperature extremes supports substation backup and critical infrastructure applications. Cold-climate utilities and Arctic remote sites maintain procurement for reliability assurance.
- Zinc-Air:Metal-air architecture promises theoretical energy density advantages with abundant raw material inputs. Pilot deployments in Australia and California test mechanical recharging models for seasonal storage.
Lithium-ion leads on scale; flow batteries lead on momentum.
Deployment Type:
Project scale determines control software complexity, offtake contract structures, and participation eligibility in wholesale capacity markets.
- Utility-Scale:Systems exceeding 100 megawatt-hours connect directly to transmission infrastructure for frequency regulation and wholesale arbitrage. ERCOT and CAISO interconnection queues concentrate procurement, though permitting timelines and fire code compliance extend development cycles.
- Community Storage:Shared assets serving multiple retail customers behind distribution substations enable virtual power plant aggregation. New York's Value of Distributed Energy Resources tariff and Australian neighborhood battery programs are expanding procurement.
- Commercial Microgrid:Campus-scale systems with islanding capability serve manufacturing plants and data centers requiring resilience assurance. California's Public Safety Power Shutoff exposure and Southeast Asian industrial estate reliability mandates drive adoption.
- Off-Grid Systems:Standalone installations without utility interconnection serve mining operations and remote communities. Australian mining corridors and Canadian Arctic settlements specify these where transmission extension proves uneconomical.
- Peak Shaving:Demand charge reduction applications for commercial and industrial ratepayers optimize against utility tariff structures. Texas and Northeast US markets with volatile demand charges concentrate deployment.
- Load Balancing:Real-time power injection and absorption stabilizes renewable intermittency at solar and wind farms. China's dual carbon goals and India's solar parks mandate co-located storage procurement.
Utility-scale deployments anchor revenue concentration; community storage is climbing the fastest.
End User Industry:
Buyer sophistication varies sharply across procurement departments, with electric utilities demanding full-stack warranties while industrial users prioritize resilience guarantees.
- Electric Utilities:Vertically integrated and independent power producers procure multi-gigawatt portfolios through competitive solicitations. FERC Order 841 compliance and state renewable portfolio standards shape technical specifications and dispatch requirements.
- Renewable Energy Producers:Solar and wind developers add storage to firm output and capture capacity market revenues. PPA offtakers in Spain, Australia, and the US Southwest increasingly require storage co-location.
- Data Centers:Hyperscale and colocation operators deploy batteries for seamless load transfer and diesel generator displacement. EU Green Deal carbon accounting and corporate sustainability commitments accelerate procurement.
- Telecommunications:Tower operators and network providers specify backup power for grid outage resilience. India's universal service obligation programs and African rural connectivity initiatives expand addressable demand.
- Microgrid Operators:Military bases, universities, and island utilities integrate storage with distributed generation for autonomous operation. US Department of Defense resilience mandates and Caribbean hurricane recovery programs concentrate procurement.
- Manufacturing Plants:Process industries with continuous production requirements value power quality and ride-through capability. German automotive suppliers and Southeast Asian electronics fabs specify storage for voltage sag protection.
Electric utilities dominate procurement volume; data centers show the steepest expansion trajectory.
Installation Environment:
Siting constraints reshape enclosure specifications, fire suppression integration, and maintenance access economics.
- Urban Areas:Dense installations near load centers face strict NFPA 855 fire codes and limited footprint availability. New York City and London developers pay premiums for containerized systems with advanced gas suppression.
- Rural Sites:Agricultural and exurban land offers lower real estate costs but requires longer transmission tie-ins. Midwest US wind-solar hybrid projects and Australian agricultural zones concentrate deployment.
- Industrial Complexes:Co-location with manufacturing or processing facilities enables waste heat utilization and shared maintenance crews. German chemical parks and Chinese industrial zones integrate storage with captive renewable generation.
- Remote Sites:Off-grid mining, military, and research installations demand autonomous operation with minimal service intervals. Canadian Arctic, Australian outback, and Chilean Atacama projects specify extended temperature range systems.
- Substations:Grid-tied installations at existing transmission infrastructure minimize interconnection costs and permitting complexity. US investor-owned utilities and European transmission system operators prefer these for frequency regulation assets.
- Power Plants:Retrofit and greenfield generation sites co-locate storage with gas turbines or renewables for capacity firming. California peaker plant replacements and Middle East solar-storage hybrids exemplify this configuration.
Substations capture the largest project pipeline; urban areas face the tightest siting constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production tax credits in the United States and China's dual carbon goals are diverting gigafactory investments toward jurisdictions with lower compliance costs and stronger incentive packages.
United States
ERCOT interconnection queues in Texas and CAISO procurement in California concentrate utility-scale deployment. FERC Order 841 mandates wholesale market access for storage resources. The Inflation Reduction Act's $35 per kilowatt-hour production tax credit is redirecting cell manufacturing toward Arizona and Nevada industrial zones.
China
Provincial renewable purchase obligations in Jiangsu and Guangdong provinces mandate multi-gigawatt storage co-location with solar and wind farms. MIIT and NMPA enforce domestic battery safety and recycling protocols that influence export certification pathways. The Yangtze River Delta anchors cathode precursor refining capacity.
Germany
Transmission deferral projects in Bavaria and North Rhine-Westphalia concentrate flow battery procurement for 8-12 hour duration applications. The EU Green Deal and F-Gas Regulation phase down hydrofluorocarbon use in thermal management systems. Stuttgart industrial clusters specify natural refrigerant compatibility.
India
State-level renewable purchase obligations in Gujarat and Karnataka mandate 500 megawatt-hour storage procurement by 2030. CEA guidelines shape technical specifications for grid-connected installations. The Delhi-Mumbai Industrial Corridor attracts technology licensors seeking first-mover terrain.
Australia
Wholesale arbitrage opportunities in the National Electricity Market drive utility-scale deployment in South Australia and Queensland. AEMO market rules enable fast-frequency response procurement. Pilbara mining corridors specify off-grid systems where transmission extension proves uneconomical.
Grid-Scale Battery Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with full-stack integrators commanding premium pricing in utility-scale procurement while component suppliers capture volume in distributed applications. The vendor base concentrates around three strategic archetypes: vertically integrated cell-to-system providers, pure-play software optimization platforms, and regional system integrators with local certification expertise. Capacity expansion and strategic partnerships dominate competitive moves as players secure cathode precursor supply and interconnection queue positions.
Among vertically integrated specialists, Tesla and CATL occupy positions that exemplify divergent paths to scale, with the former emphasizing in-house cell chemistry and grid-side software stacks while the latter anchors cost structures through upstream control over lithium refining. Fluence Energy sits within the software-centric tier, representing the shift toward subscription-based performance contracts that redistribute value toward predictive analytics layers.
| Leading Market Players |
|---|
| Tesla |
| Fluence Energy |
| LG Energy Solution |
| BYD Company |
| Sungrow Power Supply |
| CATL |
| Samsung SDI |
| NGK Insulators |
| Sumitomo Electric Industries |
| Others |
Cost & Logistics Intelligence
Utility procurement departments unbundling hardware from service agreements are compressing integrator margins and forcing suppliers to absorb cost volatility. This buyer-driven fragmentation reshapes how cell manufacturers, power conversion vendors, and software platforms negotiate contract structures across project development cycles.
Pricing Analysis
Direct-to-utility contract structures dominate large-scale procurement, bypassing distributor markups that still capture 8-12% in distributed commercial segments. Project-based long-term offtake agreements stratify across premium UL-certified systems, standard IEC-compliant installations, and economy-tier configurations lacking advanced fire suppression. Cost compression in lithium carbonate feedstocks is intensifying because spot market volatility destabilizes project financing, with independent power producers exhibiting highest price sensitivity and data center operators least willing to trade certification grade for cost savings.
Supply Chain Analysis
Ocean freight rates from Chinese cathode precursor facilities to European and North American assembly plants constitute 4-7% of landed cell costs, incentivizing regional gigafactory placement. Manufacturing concentrates in China, South Korea, and Japan, with cathode active materials drawing from Indonesian nickel, Chilean lithium carbonate, and Australian spodumene concentrate. Single-source vulnerability in refined cobalt processing creates structural risk, while distribution runs through EPC contractor-led project finance structures that bundle engineering, procurement, and construction under single-source accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
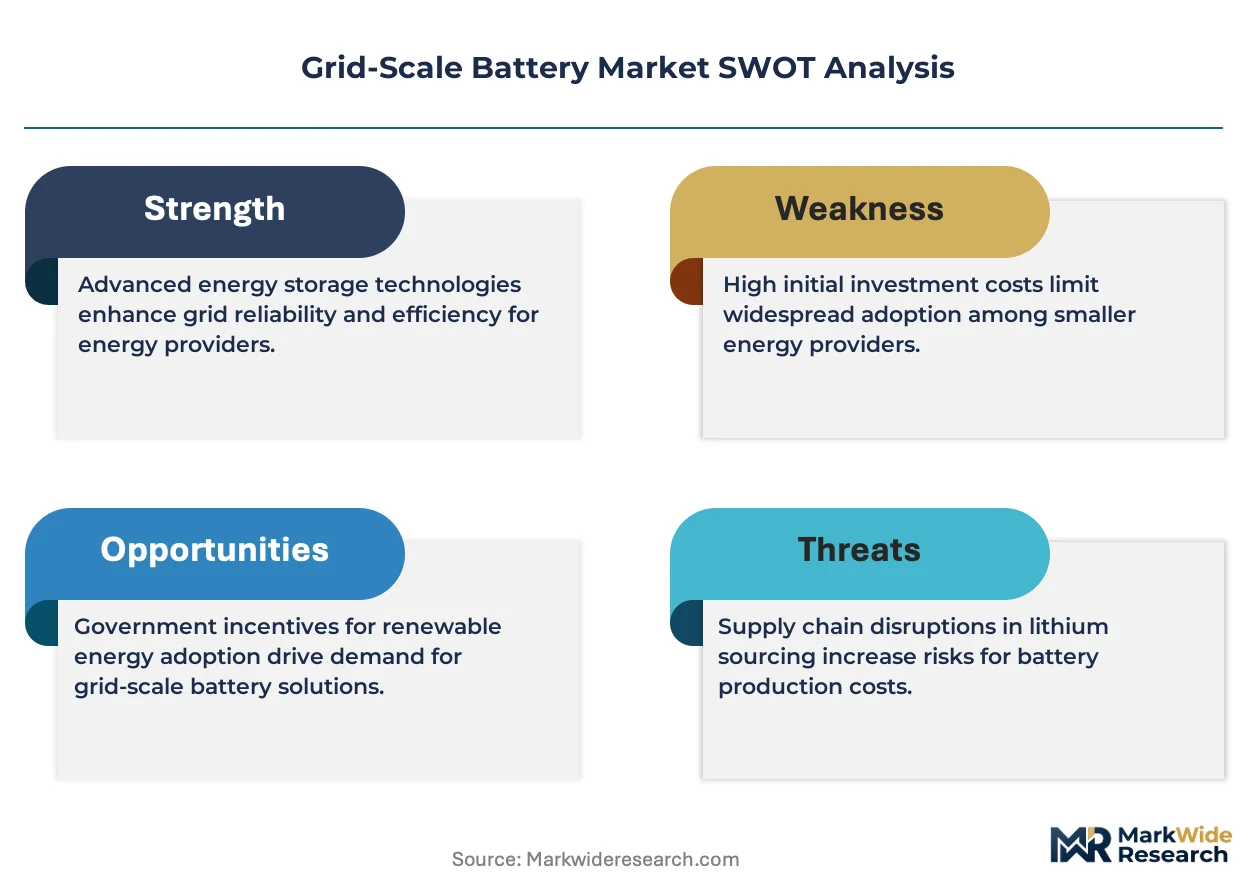
Software-defined service layers are expanding margin pools faster than hardware commoditization erodes them, with predictive analytics and trading optimization commanding recurring revenue premiums that offset cell cost cyclicality.
For Market Incumbents: Hedge lithium price exposure through long-term offtake agreements with Australian and Chilean mining operators rather than spot market procurement. Secure backward integration into cathode precursor refining to defend against Chinese supply concentration, while investing in NFPA 855 certification capabilities to capture urban siting premiums that emerging competitors cannot match. For New Entrants and Emerging Players: Enter via India's state-level renewable purchase obligations, where 500 megawatt-hour mandates by 2030 create first-mover terrain without incumbent lock-in. Target vanadium redox flow battery licensing to German transmission deferral projects, positioning around 12-hour duration applications where lithium-ion economics degrade. Pursue technology licensing partnerships with established EPC contractors rather than direct utility sales. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play software optimization platforms that extract recurring revenue from hardware assets without manufacturing capital intensity. Long-term viability favors vendors controlling grid-side dispatch algorithms and wholesale market bidding systems. Monitor FERC Order 841 implementation depth across US independent system operators as the inflection indicator for software layer monetization potential.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | CATL's lithium refining control insulates margin structures from carbonate spot volatility. |
| AI-Powered Trading Platform Deployment | Fluence Energy's optimization software captures wholesale arbitrage value beyond hardware throughput. |
| Natural Refrigerant Thermal Management Redesign | EU F-Gas Regulation compliance opens German and Dutch procurement gates for redesigned pack architectures. |
| Vanadium Redox Flow Battery Licensing | Sumitomo Electric's technology transfer agreements penetrate India's long-duration storage mandates. |
| Virtual Power Plant Software Stack Development | Tesla's Autobidder platform aggregates behind-the-meter assets into ERCOT capacity markets. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against EIA storage deployment databases, FERC interconnection filings, IEA technology roadmaps, and project finance tracker records. Bottom-up cell shipment aggregation and top-down grid investment flow analysis were triangulated to reconcile volume estimates.
Historical reference periods anchored the projection horizon to observed deployment cycles across preceding regulatory and incentive regimes. The analytical framework modeled battery chemistry, deployment scale, end-user industry, and installation environment as core segmentation dimensions, with regional regulatory framework and grid market structure as cross-cutting variables. CAGRs were derived from fitted adoption curves incorporating lithium cost trajectories, policy incentive durability, and interconnection queue processing rates.
Inputs from utility procurement officers and EPC project managers were available through the study window; gaps in long-duration storage commercial deployment data introduce uncertainty bands around flow battery adoption assumptions. Forecasts reflect documented assumptions on policy continuity and raw material supply expansion. A model refresh is warranted upon material change in Inflation Reduction Act credit eligibility or FERC Order 841 implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
China Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
Europe SLI Battery Market
Batteries
Military Battery Market
Batteries
Consumer Battery Market
Batteries
PVT Battery Panel Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Battery Wash System Market
Batteries
Rechargeable Coin Cell Market
Batteries
South America Battery Cell Market
Batteries
Italy Rechargeable Battery Market
Batteries
North Europe Battery Market
Batteries
PERC Battery Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
India Battery Cell Market
Batteries
India Lead-Acid Battery Market